
 Wet Chemicals for Electronics and Semiconductor Application Market | 2026-2036
Wet Chemicals for Electronics and Semiconductor Application Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Chemicals for Electronics and Semiconductor Application Market Intelligence
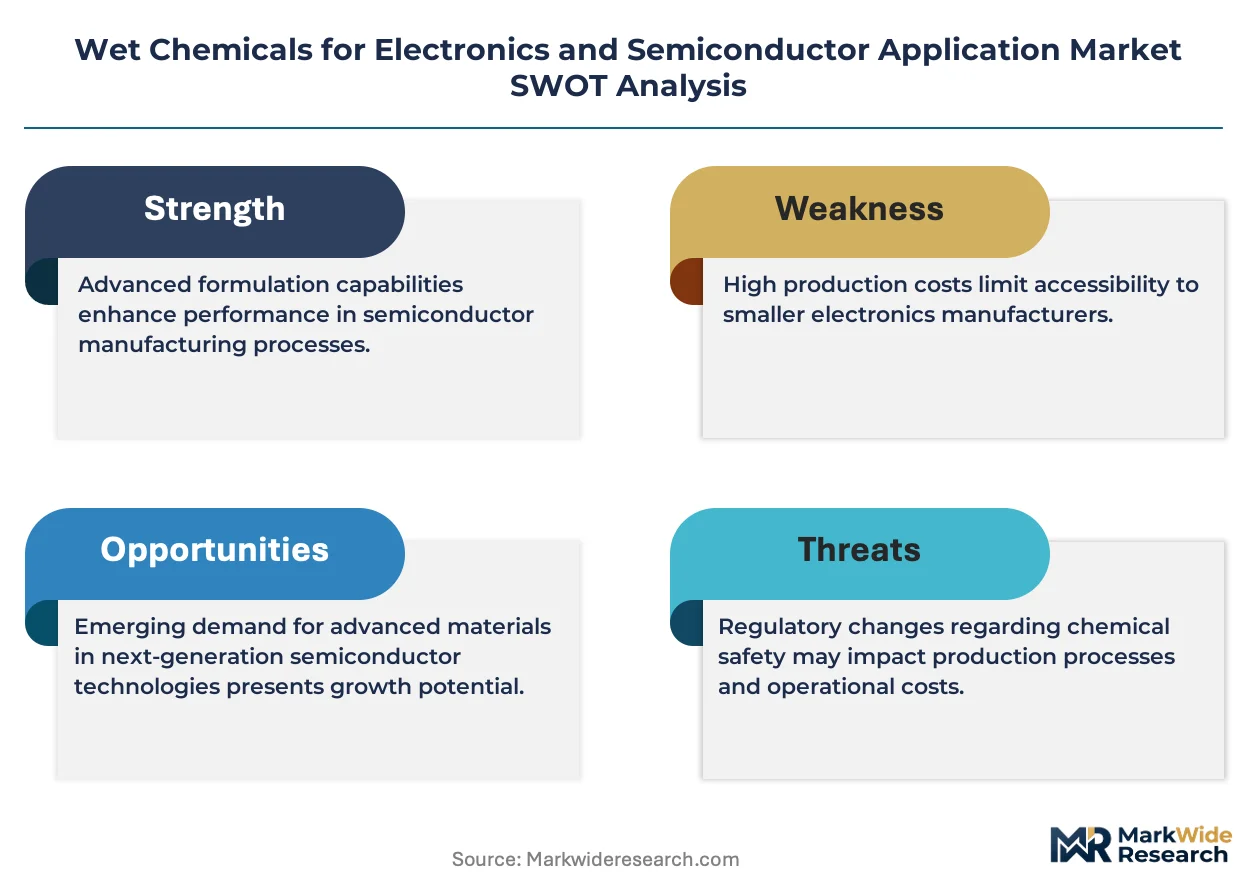
ISO 14644 cleanroom certification is collapsing the supplier base as only a handful of chemical producers can sustain Class 1 particulate limits across bulk delivery systems. Entegris anchors North American supply through its contamination-control-integrated fluid handling architecture. BASF SE leverages its Ludwigshafen integrated site to captive-produce electronic-grade acids with batch-to-batch traceability below 10 parts-per-trillion for critical metal impurities.
Wet chemicals for electronics and semiconductor applications encompass ultra-high-purity formulations—typically acids, solvents, bases, and cleaners with impurity thresholds below 100 parts-per-trillion—engineered for wafer-level processing in controlled environments. These chemistries perform etching, stripping, and surface preparation functions where even nanoscale contamination causes catastrophic device yield loss. Acids and cleaners command the deepest margin pools due to their irreplaceability in front-end-of-line RCA cleaning sequences and back-end copper pillar bumping. Photoresist stripping applications are gaining fastest as EUV lithography adoption multiplies resist layers per wafer, while etching formulations face pricing pressure from dry-plasma substitution in certain 3D NAND steps.
EPA hazardous waste regulations and REACH substance restrictions are forcing reformulation of legacy solvent blends and driving capital investment in closed-loop chemical regeneration systems. Japan's METI oversees national purity benchmarks through JIS standards that effectively gate market access for imported electronic-grade chemistries. Korea's MFDS and environmental ministry coordinate on perfluorinated compound discharge limits that directly affect wet etchant selection at Samsung and SK Hynix facilities. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments made for one geography rarely transfer cleanly to another, fragmenting product portfolios and raising working capital requirements for multi-site qualification programs.
Market Dynamics
Sub-7nm node migration is compressing impurity tolerances by orders of magnitude, forcing chemical suppliers to rebuild purification infrastructure around single-digit parts-per-trillion specifications while foundries consolidate qualified vendor lists to three or fewer per chemistry class.
Growth Catalysts
- EUV Lithography Penetration:Multi-patterning requirements at leading-edge nodes multiply photoresist stripping cycles per wafer, expanding volume demand for N-methyl-2-pyrrolidone and advanced solvent formulations.
- REACH Substance Restrictions:Europe's phased bans on per- and polyfluoroalkyl substances are accelerating reformulation investment toward fluorine-free etchants with equivalent selectivity profiles.
- Hsinchu Science Park Clustering:Taiwan's concentrated fab ecosystem enables just-in-time bulk chemical delivery at Class 1 cleanroom standards, reducing inventory carrying costs for TSMC and allied foundries.
Market Restraints
- Feedstock Purity Bottlenecks:Semiconductor-grade sulfuric acid requires starting material with base metal impurities below 1 part-per-billion, constraining qualified sulfur burner sources to four global suppliers.
- Capital Intensity Barriers:ISO 14644-1 Class 1 bulk delivery systems demand $40-60 million per installation, excluding regional chemical blenders from front-end qualification programs.
- Dry Plasma Substitution:Atomic layer etch processes in 3D NAND string stacking are displacing wet chemistry in select high-aspect-ratio steps, compressing addressable volume in memory segments.
Strategic Opportunities
- India Semiconductor Mission:The country's $10 billion production-linked incentive scheme is attracting foundry investments in Gujarat and Assam, creating first-mover qualification opportunities for electronic-grade chemical suppliers.
- Closed-Loop Regeneration:On-site solvent recovery systems at large-scale memory fabs reduce virgin chemical procurement by 60-70%, enabling service-based revenue models for equipment-chemistry integrated providers.
- Advanced Packaging Chemistry:Copper pillar bumping and through-silicon via formation require specialized plating chemistries with organic additive control, a segment with fewer entrenched suppliers than front-end markets.
Industry Challenges
- Analytical Metrology Talent Scarcity:Inductively coupled plasma mass spectrometry operators capable of sub-parts-per-trillion verification command 40% salary premiums, constraining quality team scaling.
- Multi-Site Qualification Burden:A single wet chemistry requires 18-24 months of parallel validation across three or more foundry locations before volume allocation, freezing working capital in inventory and technical service deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Chemicals for Electronics and Semiconductor Application Market |
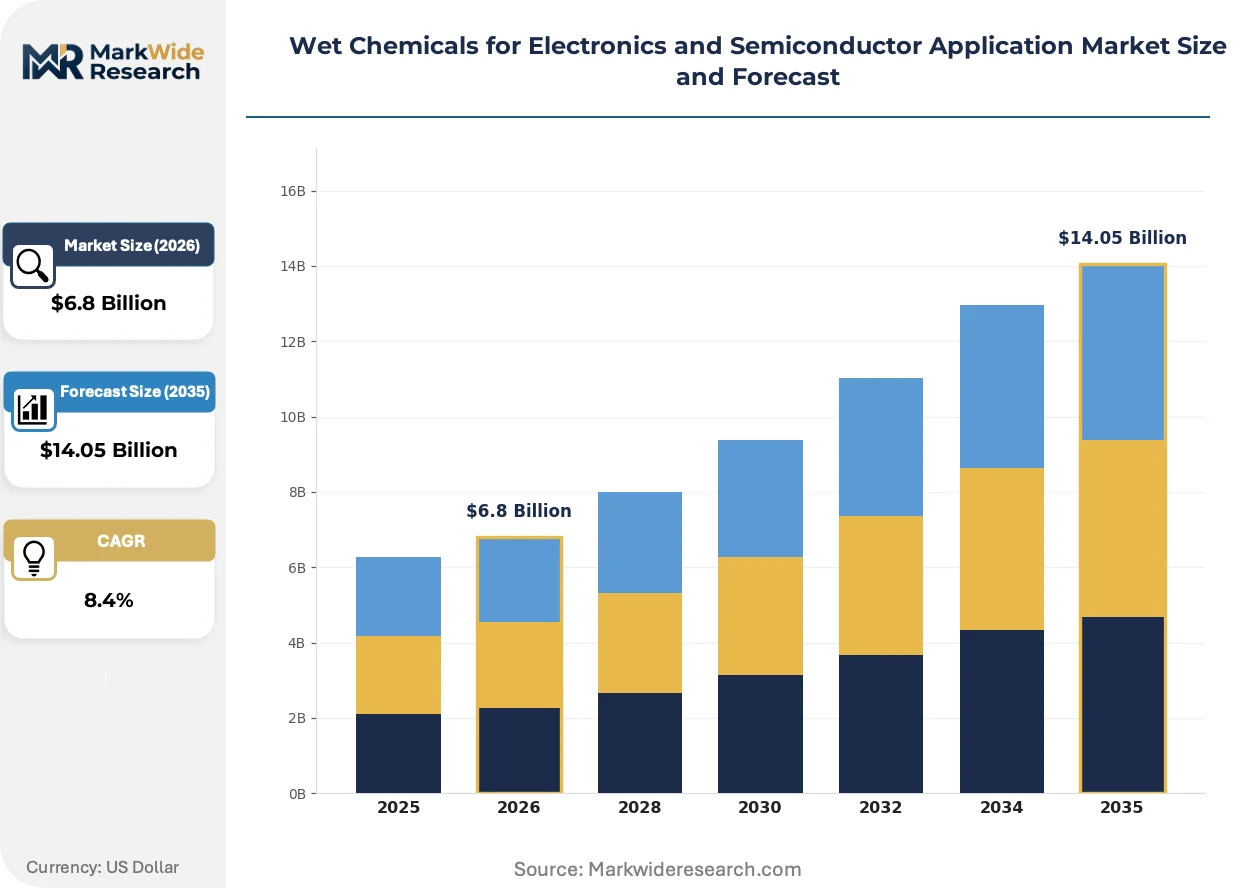
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acids, Solvents, Bases, Cleaners Application: Wafer Cleaning, Photoresist Stripping, Etching, Surface Preparation End User: Foundries, IDMs, OSATS, R&D Labs Distribution Channel: Direct Sales, Distributors, Online Retailers, Resellers |
| Companies Covered | Honeywell International Inc., KANTO KAGAKU, Entegris, Fujifilm Holdings Corporation, Solvay, BASF SE, Dow Inc., Air Products and Chemicals Inc., Avantor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Chemicals for Electronics and Semiconductor Application Market Strategic Shifts & Innovations
Process complexity at angstrom-scale nodes is fragmenting the supplier base into two tiers: integrated contamination-control architects and specialized formulation boutiques with proprietary purification IP.
Single-wafer processing equipment is miniaturizing chemical consumption per wafer by 30-50% versus batch immersion tools, forcing suppliers to restructure pricing models around delivered value rather than volume throughput. Leading logic foundries in Taiwan and Korea are retrofitting 300mm lines with these tools to reduce chemical waste disposal liabilities. The shift is miniaturizing the addressable tonnage per fab while expanding margin capture for ultra-high-purity formulations.
EPA's forthcoming hazardous waste generator improvements rule will tighten manifesting requirements for spent sulfuric acid and solvent blends, increasing compliance documentation burden for US-based fabs. The industrial consequence is accelerated investment in on-site neutralization and regeneration capacity to reclassify waste streams as product. Memory producers in Idaho and Arizona are most affected, with two facilities already announcing $200 million-plus regeneration system deployments.
Specification-driven procurement is consolidating qualified supplier lists to two or three vendors per chemistry class, replacing the historical five-to-seven vendor model. Distributors and regional blenders are being disintermediated as foundries demand direct mill-to-fab traceability with batch-level analytical certificates. This concentration is most visible in Korea's Pyeongtaek and Yongin corridors, where Samsung and SK Hynix have implemented vendor reduction programs with 18-month phase-out timelines for non-strategic chemical sources.
Wet Chemicals for Electronics and Semiconductor Application Market Segmentation
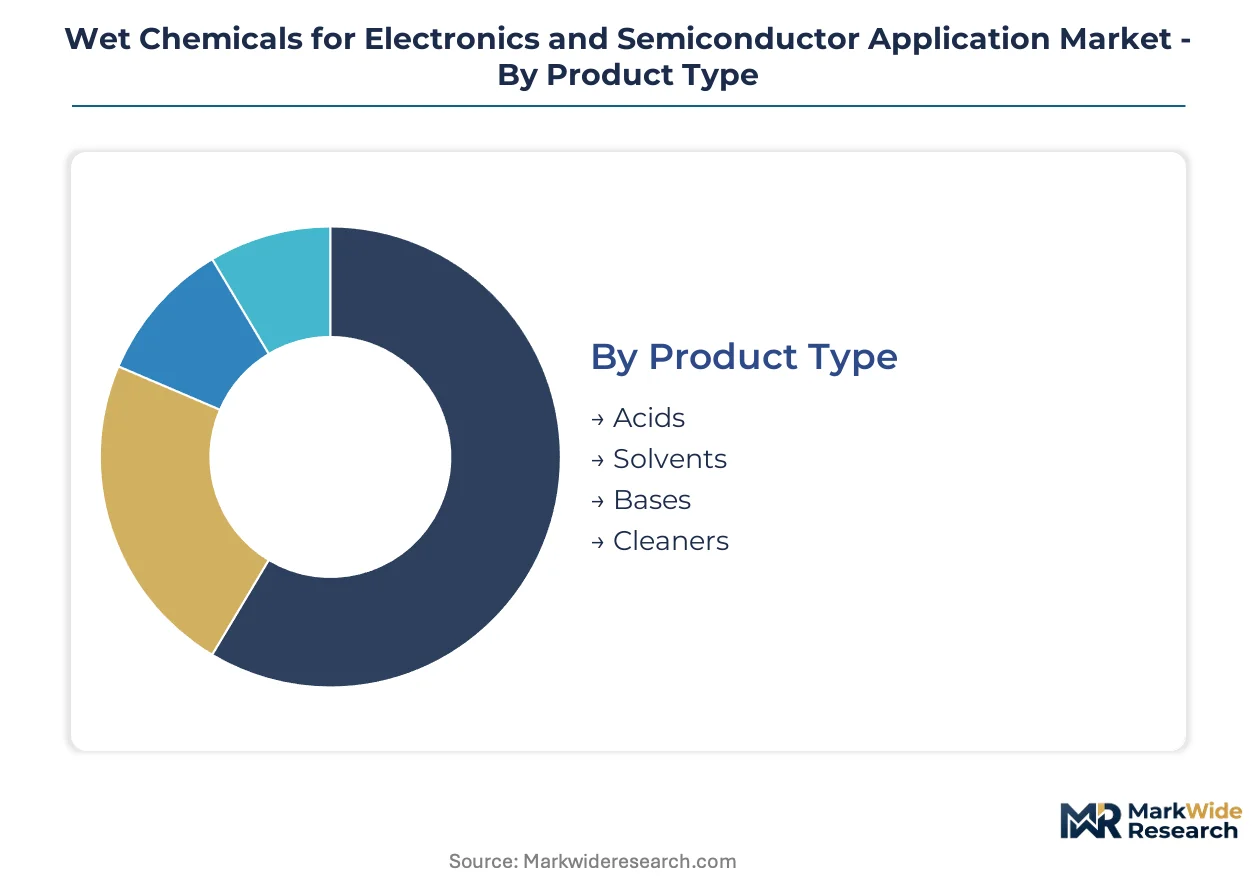
Wet chemicals for electronics and semiconductor applications fragment across purification grades, delivery modes, and customer technical requirements. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape competitive positioning across the value chain.
Product Type:
REACH substance restrictions and EPA hazardous waste protocols are forcing divergent formulation strategies across acid, solvent, and base categories, with fluorine-free alternatives gaining accelerated qualification timelines in Europe while legacy chemistries retain grandfathered status in Asian manufacturing clusters.
- Acids:Electronic-grade sulfuric, hydrochloric, and hydrofluoric acids with base metal impurities below 10 parts-per-trillion serve RCA cleaning sequences and silicon nitride etching. Taiwan's Hsinchu Science Park consumes the densest volumes, where TSMC's sub-7nm nodes demand batch-to-batch traceability certificates.
- Solvents:N-methyl-2-pyrrolidone and advanced polar aprotic formulations strip multi-layer EUV photoresists. Korea's Pyeongtaek corridor drives fastest volume expansion as Samsung expands EUV lithography penetration across logic and memory lines.
- Bases:Ammonium hydroxide and tetramethylammonium hydroxide solutions perform particle removal and developer functions with pH precision to 0.01 units.
- Cleaners:Surfactant-enhanced aqueous formulations displace solvent blends in environmentally constrained fabs, particularly at Intel's Arizona and Ohio facilities under tightened EPA discharge limits.
Established volume favors acids; emerging adoption favors solvents.
Application:
Process node migration is reweighting application mix, with angstrom-scale lithography multiplying resist stripping cycles while 3D NAND string stacking partially displaces wet etching with atomic layer processes.
- Wafer Cleaning:RCA Standard Clean 1 and 2 sequences using hydrogen peroxide-ammonia and hydrogen peroxide-hydrochloric mixtures remove organic and metallic contaminants from silicon surfaces. Front-end-of-line processing at leading logic foundries specifies Class 1 particulate limits across bulk delivery systems.
- Photoresist Stripping:Post-lithography residue removal consumes solvent volumes that scale with patterning complexity. EUV multi-patterning at TSMC's Fab 18 and Samsung's Pyeongtaek S5 expands stripping cycles per wafer by 40-60% versus DUV-era baselines.
- Etching:Wet chemical etching retains dominance in silicon dioxide and aluminum layer patterning despite plasma substitution in high-aspect-ratio 3D NAND steps.
- Surface Preparation:Pre-deposition cleaning and native oxide removal ensure adhesion for subsequent thin-film stacks.
Front-end wafer cleaning commands margin premiums; photoresist stripping exhibits steepest expansion trajectory.
End User:
Customer scale and integration depth determine procurement leverage, with captive chemical regeneration investments concentrated at memory IDMs while foundries prioritize just-in-time bulk delivery.
- Foundries:TSMC, Samsung Foundry, and GlobalFoundries operate pure-play wafer fabrication with chemical specifications tied to customer process design kits. Taiwan's foundry ecosystem drives the tightest purity requirements globally.
- IDMs:Vertically integrated memory and logic producers including Samsung Electronics, SK Hynix, and Intel captive-produce devices and maintain internal chemical regeneration capacity. Korea's IDMs lead closed-loop solvent recovery deployment.
- OSATS:Outsourced semiconductor assembly and test providers consume specialized plating chemistries for copper pillar bumping and redistribution layer formation.
- R&D Labs:University and corporate research facilities purchase small-batch ultra-high-purity chemistries for process development and materials characterization.
Foundries concentrate specification-setting power; IDMs drive capital-intensive regeneration adoption.
Distribution Channel:
Traceability mandates and contamination-control requirements are disintermediating traditional distribution, with direct mill-to-fab relationships replacing regional blender networks at leading-edge accounts.
- Direct Sales:BASF SE, Entegris, and integrated chemical producers deliver bulk ISO-tank shipments with batch-level analytical certificates. Korea's Samsung and SK Hynix have implemented 18-month phase-out timelines for non-direct chemical sources.
- Distributors:Regional chemical blenders serve second-tier foundries and legacy-node producers with lower purity requirements, though ISO 14644-1 Class 1 bulk systems exclude most from front-end qualification.
- Online Retailers:Electronic-grade chemical e-commerce remains confined to laboratory-scale volumes and research-grade specifications.
- Resellers:Secondary market participants handle surplus inventory and spot purchases for non-critical maintenance chemicals.
Direct sales capture leading-edge value; distributors retain legacy-node service roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry procurement teams concentrate purchasing authority in Taiwan, South Korea, and the United States, where sub-7nm node production drives specification-setting power for ultra-high-purity chemistries.
Taiwan
TSMC's Fab 18 and allied facilities in Hsinchu Science Park consume the densest volumes of electronic-grade sulfuric acid and N-methyl-2-pyrrolidone globally. The National Development Council coordinates industrial park expansion with EPA Taiwan enforcement of wastewater discharge standards for perfluorinated compounds. Kaohsiung's emerging fab cluster is attracting secondary chemical supplier qualification programs.
South Korea
Samsung Electronics and SK Hynix operate vertically integrated memory and logic production in Pyeongtaek and Yongin corridors with captive solvent regeneration investments. MFDS and the Ministry of Environment jointly administer perfluorinated compound discharge limits affecting wet etchant selection. Busan's chemical handling port infrastructure supports just-in-time bulk delivery to Gyeonggi Province fabrication complexes.
United States
Intel's Arizona and Ohio facilities plus GlobalFoundries' Malta fab drive demand for EPA-compliant solvent formulations and spent acid regeneration systems. The EPA's hazardous waste generator improvements rule tightens manifesting requirements for sulfuric acid and solvent blends. Idaho's Micron facilities are deploying $200 million-plus on-site neutralization capacity to reclassify waste streams.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor demand for JIS-standard electronic-grade chemistries in the Kanto and Kansai industrial belts. METI oversees national purity benchmarks through JIS K 8541 and related standards that gate market access for imported formulations. Kyushu's Kumamoto region hosts Sony and Renesas fabs with specialized requirements for automotive-grade semiconductor processing.
China
SMIC and Hua Hong Semiconductor operate trailing-edge and mature-node fabs in Shanghai and Wuxi with growing domestic chemical supplier qualification. MIIT and MEE administer GB standards for electronic-grade chemical purity and environmental discharge. The Yangtze River Delta cluster in Jiangsu Province is developing localized supply chains for hydrofluoric acid and photoresist strippers.
Wet Chemicals for Electronics and Semiconductor Application Market Key Industry Players
Player mix skews toward integrated contamination-control architects with captive purification infrastructure and specialized formulation boutiques holding proprietary trace-metal removal IP. Tier-one suppliers maintain direct mill-to-fab relationships with batch-level analytical certificates, while regional blenders face exclusion from front-end qualification due to ISO 14644-1 Class 1 bulk system requirements. Two strategic archetypes dominate: integrated chemical-architecture providers and boutique purification specialists. Competitive moves concentrate on vendor reduction program participation and closed-loop regeneration service deployment.
Within the integrated-architecture tier, Entegris and BASF SE exemplify contamination-control-integrated supply models. Entegris anchors North American delivery through fluid handling systems with Class 1 particulate limits. BASF SE leverages its Ludwigshafen integrated site for electronic-grade acid production with traceability below 10 parts-per-trillion. Among Asia-Pacific specialists, KANTO KAGAKU occupies a position in Japanese electronic-grade chemical supply aligned with METI purity benchmarks.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| KANTO KAGAKU |
| Entegris |
| Fujifilm Holdings Corporation |
| Solvay |
| BASF SE |
| Dow Inc. |
| Air Products and Chemicals Inc. |
| Avantor Inc. |
| Others |
Cost & Logistics Intelligence
ISO 14644-1 Class 1 certification gates both supplier qualification and price stratification simultaneously, as only producers sustaining sub-1 particulate limits across bulk delivery systems command premium positioning at TSMC and Samsung foundries while regional blenders compete on cost for trailing-edge accounts.
Pricing Analysis
Cost-plus contracts with sulfur burner feedstock indexation dominate long-term offtake agreements between integrated producers and leading foundries. Three-tier pricing structure across electronic-grade, high-purity, and standard grades reflects batch-level traceability depth and impurity thresholds. Cost compression in standard-grade acids is intensifying because Chinese domestic suppliers are expanding captive purification capacity. Memory IDMs exhibit highest price sensitivity due to regeneration system investments, while sub-7nm logic foundries prioritize specification compliance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, consuming the densest volumes of electronic-grade sulfuric acid and N-methyl-2-pyrrolidone globally. Feedstock supply draws from elemental sulfur deposits in the United States and the Middle East, with semiconductor-grade hydrogen fluoride sourcing concentrated in Mexican and Chinese mining operations. Single-source vulnerability permeates qualified sulfur burner supply, where four global producers control base metal impurity thresholds below 1 part-per-billion. Distribution runs through direct mill-to-fab ISO-tank delivery with batch-level analytical certificates, excluding regional blenders from front-end qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sub-7nm node migration represents a high-growth disruption as angstrom-scale lithography multiplies chemical consumption cycles per wafer while collapsing impurity tolerances by orders of magnitude.
For Market Incumbents: Shield qualification status by deepening backward integration into captive sulfur burner capacity and accelerating closed-loop regeneration service deployment. Dry plasma substitution in 3D NAND string stacking threatens wet etchant volumes, making ISO 14644-1 certification maintenance the priority defensive lever against disintermediation. For New Entrants and Emerging Players: Anchor in India's Gujarat and Assam fab clusters under the Semiconductor Mission production-linked incentive scheme, where first-mover qualification opportunities precede entrenched supplier consolidation. Advanced packaging plating chemistries for copper pillar bumping offer the most penetrable white space, with fewer qualified competitors than front-end markets and direct sales to OSATs as the viable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop regeneration equipment-chemistry integration as memory fabs deploy $200 million-plus on-site neutralization systems. Five-to-ten-year viability favors acquisition targets with proprietary trace-metal removal IP and existing vendor reduction program participation at Samsung or SK Hynix. The signal to watch is EPA hazardous waste generator improvements rule implementation pace, which accelerates regeneration system procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Burner Capacity | Captive feedstock supply secures batch-to-batch traceability below 10 parts-per-trillion for TSMC qualification. |
| Closed-Loop Regeneration System Deployment | On-site solvent recovery reduces virgin chemical procurement by 60-70% at Micron's Idaho facilities. |
| ISO 14644-1 Class 1 Bulk Delivery Installation | $40-60 million capital barrier excludes regional blenders from Samsung and SK Hynix vendor lists. |
| Fluorine-Free Etchant Reformulation | REACH substance restriction compliance opens European market access ahead of phased PFAS bans. |
| Direct Mill-to-Fab Relationship Establishment | Batch-level analytical certificates replace distributor networks at Korea's Pyeongtaek and Yongin corridors. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with plant managers at leading foundries, procurement leads at memory IDMs, technical R&D directors at integrated chemical producers, and distribution channel partners; and secondary validation through customs and trade data, SEC 10-K filings, ACC and Cefic industry reports, and EPA regulatory filings. Bottom-up capacity and consumption modeling triangulated against top-down market sizing from production cluster analysis.
Across the projection horizon, the analytical framework segmented volume and value outputs by purification grade, end-use application, customer integration depth, and regional production hub. CAGRs derived from node-specific chemical intensity factors, EUV lithography penetration curves, and regeneration system adoption rates. Forecast inputs incorporated foundry capex disclosure patterns and perfluorinated compound discharge limit evolution.
Material uncertainties — regulatory divergence between REACH, EPA, and METI jurisdictions, dry plasma substitution acceleration in memory segments, and feedstock purity bottleneck resolution — sit outside the modeled envelope. Recalibration cycles align with material shifts in node migration timelines and hazardous waste generator improvements rule enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Germanium Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market