
 Polycrystalline Silicon Market | 2026-2036
Polycrystalline Silicon Market Size, Share, and Industry Trends Forecast 2026-2036
Polycrystalline Silicon Market Outlook
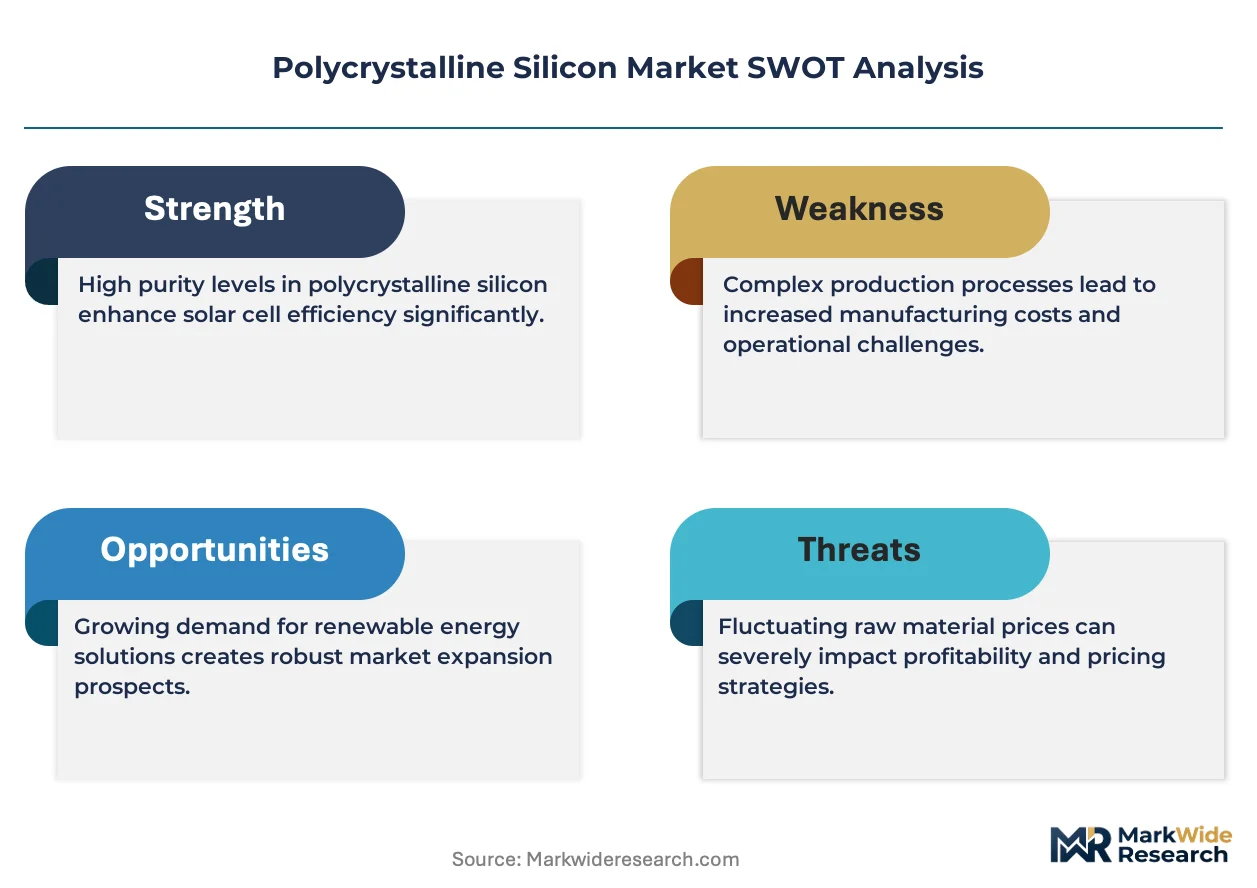
Asset-light leasing arrangements for polysilicon reactors and modular plant designs is narrowing the capital barrier for mid-scale entrants. Tongwei Co., Ltd leverages captive hydroelectric power in Sichuan to sustain cost leadership across solar-grade output. Wacker Chemie AG anchors its position through backward integration into trichlorosilane chemistry at its Burghausen complex. Daqo New Energy Corp. differentiates via ultra-high-purity electronic-grade specifications serving semiconductor foundries.
Polycrystalline silicon consists of multiple small silicon crystals fused together, typically manufactured through the Siemens process or fluidized bed reactor methods to achieve purity levels ranging from 6N to 9N depending on end-use requirements. The material serves as the foundational feedstock for both photovoltaic cell fabrication and semiconductor wafer production, with impurity thresholds determining whether batches qualify for solar or electronics applications. Solar grade polysilicon currently leads volume throughput as photovoltaic deployment scales across utility-scale installations, while electronic grade commands premium pricing due to stringent trace-metal specifications demanded by chip manufacturers. Chemical vapor deposition technology dominates purification workflows, though plasma-enhanced CVD variants are gaining traction for specialized thin-film applications where deposition temperature constraints matter.
China's Ministry of Ecology and Environment enforces dual carbon targets that restrict coal-dependent polysilicon expansion in Xinjiang, redirecting capacity toward hydropower-rich southwestern provinces. The EPA in the United States and REACH in Europe impose divergent reporting obligations on chlorosilane byproducts, shaping where producers locate cracking and distillation stages. Stakeholders must monitor how carbon border adjustment mechanisms and country-of-origin traceability rules reshape procurement criteria for solar module assemblers sourcing polysilicon feedstock.
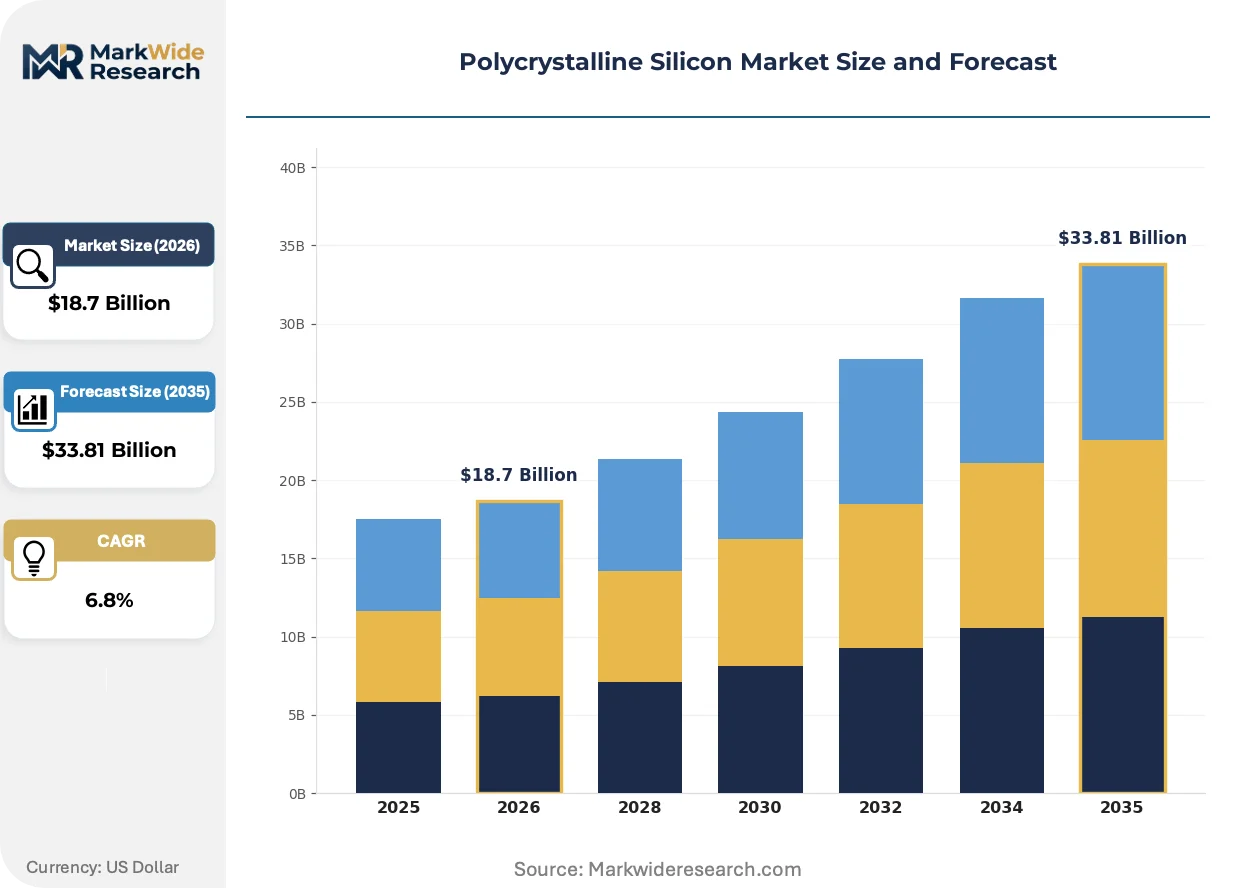
Market Dynamics
China's dual carbon goals are redrawing the geographic map of polysilicon capacity, forcing producers to abandon coal-dependent Xinjiang corridors and relocate to hydropower-rich southwestern provinces where clean energy access determines license eligibility.
Growth Catalysts
- Solar deployment mandates:National renewable portfolio standards in India and the European Union mandate minimum shares of photovoltaic generation, locking in feedstock demand for crystalline silicon cells.
- REACH chemical registration:The European Chemicals Agency's streamlined chlorosilane handling protocols reduce compliance friction for Burghausen-based purification complexes serving continental semiconductor foundries.
- Fluidized bed reactor chemistry:Continuous deposition methods cut specific energy consumption versus batch Siemens processing, attracting capital from independent producers seeking cost parity with integrated majors.
Market Restraints
- Metallurgical-grade silicon price volatility:Quartzite and carbon electrode input costs swing with ferroalloy demand, compressing margin buffers for unhedged polysilicon converters.
- Xinjiang supply concentration risk:Forced labor allegations and customs enforcement actions in the United States have triggered module assembler audits that disqualify feedstock from northwestern Chinese corridors.
- Electronic-grade purity thresholds:Semiconductor applications require 9N+ trace-metal specifications that only a handful of distillation trains worldwide can reliably achieve, capping addressable market expansion.
Strategic Opportunities
- India's PLI-linked solar manufacturing:Production-linked incentive schemes for photovoltaic module assembly create captive demand for domestic polysilicon conversion capacity.
- TOPCon cell architecture diffusion:Tunnel oxide passivated contact designs consume higher-purity n-type feedstock than legacy PERC cells, upgrading procurement specifications across tier-one module makers.
- Carbon border adjustment mechanisms:The EU's phased implementation of embedded emissions tariffs on imported solar modules rewards producers with verified low-carbon Sichuan or Norwegian hydropower credentials.
Industry Challenges
- Chlorosilane handling certification:EPA and OSHA process safety management audits impose multi-quarter compliance timelines on US greenfield projects, delaying commercial operation dates.
- Semiconductor-grade analytical chemistry talent:ICP-MS and glow discharge mass spectrometry expertise concentrates within a small pool of German and Japanese laboratory specialists, constraining quality control scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycrystalline Silicon Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Grade, Electronic Grade, Photovoltaic Cells, Wafers Application: Solar Energy Systems, Electronics Manufacturing, Semiconductor Devices, Chemical Industry End User: Solar Power Plants, Electronics Firms, Renewable Energy Consumers, Research Institutions Technology: Silicon Casting, Czochralski Process, Chemical Vapor Deposition, Plasma-Enhanced CVD |
| Companies Covered | Tongwei Co., Ltd, Wacker Chemie AG, GCL Technology Holdings Limited, Xinte Energy Co., Ltd, Daqo New Energy Corp., OCI Company Ltd., Hemlock Semiconductor Corporation, REC Silicon ASA, Tokuyama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycrystalline Silicon Market Strategic Shifts
Monosilane-based deposition routes and granular polysilicon morphologies are compressing traditional equipment paradigms, while regulatory carbon accounting and buyer procurement audits reshape competitive qualification criteria.
Granular polysilicon produced via fluidized bed reactors is collapsing the cost structure of continuous Czochralski ingot pulling. Polysilicon chunk suppliers serving n-type wafer growers are adopting this morphology to reduce crucible loading labor and improve melt homogeneity. The shift enables smaller furnace operators to achieve throughput parity with integrated majors without Siemens batch reactor capital intensity.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is tightening byproduct handling requirements for trichlorosilane distillation facilities. German and Austrian chemical parks must retrofit vent gas recovery systems or face production quota restrictions. Semiconductor-grade suppliers with existing TCS backward integration are absorbing compliance costs more readily than merchant chlorosilane purchasers.
Module assemblers are consolidating supplier panels and demanding granular carbon intensity disclosures for every polysilicon production stage. Long-term offtake contracts now embed emissions verification clauses audited against ISO 14064-1 protocols. This behavioral pivot is most visible among European and North American project developers qualifying for green bond financing or corporate renewable energy procurement programs.
Polycrystalline Silicon Market Segmentation
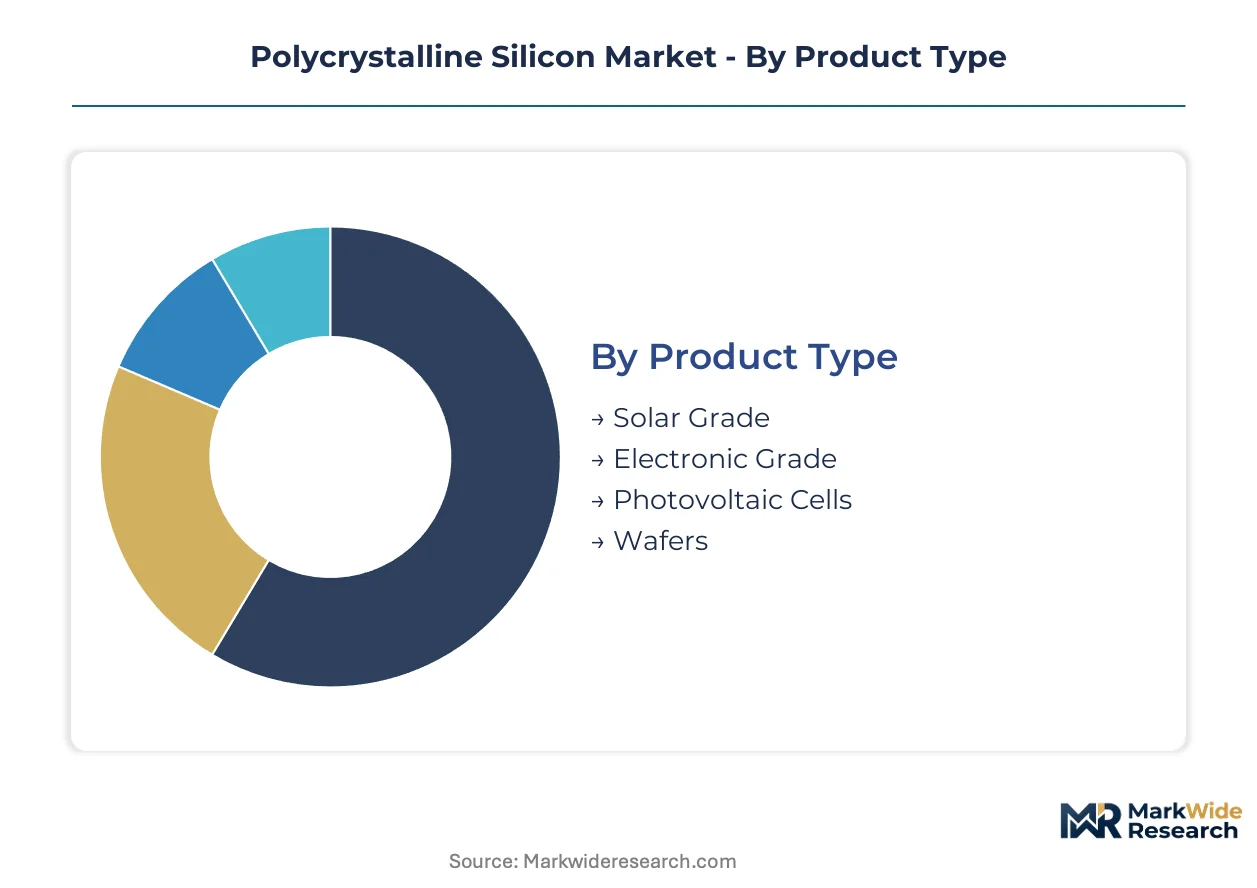
Polycrystalline silicon splits across purity thresholds and deposition chemistries that determine addressable end-markets. Each segment carries distinct capital intensity, certification requirements, and customer concentration profiles that reshape supplier economics.
Product Type:
Use-case spectrum spans commodity photovoltaic feedstock through ultra-pure semiconductor inputs, with purity gradients dictating pricing architecture and customer qualification timelines.
- Solar Grade:6N to 7N purity specifications serve crystalline silicon cell fabrication, with boron and phosphorus dopant tolerances calibrated for p-type and n-type wafer architectures. Procurement concentrates among Chinese module assemblers in Jiangsu and Anhui provinces, where TOPCon cell conversion is upgrading feedstock specifications beyond legacy multicrystalline requirements.
- Electronic Grade:9N+ trace-metal thresholds demanded by 300mm semiconductor foundries require dedicated distillation trains and glow discharge mass spectrometry validation. Supply concentrates at Wacker Chemie's Burghausen complex and select Japanese producers serving TSMC and Samsung fabs.
- Photovoltaic Cells:Finished cell products incorporating polysilicon feedstock, with efficiency ratings and degradation warranties determining module tier classification.
- Wafers:Sliced ingot products bridging polysilicon conversion and cell fabrication, with thickness and kerf loss metrics shaping silicon utilization economics.
Established volume favors Solar Grade; emerging adoption favors Electronic Grade.
Application:
Cost tier stratification separates utility-scale solar deployment from precision electronics manufacturing.
- Solar Energy Systems:Utility-scale and distributed photovoltaic installations driving crystalline silicon demand, with procurement scale and offtake duration determining supplier margins.
- Electronics Manufacturing:Consumer device and industrial electronics incorporating silicon components, with supply chain qualification protocols shorter than semiconductor foundry standards.
- Semiconductor Devices:Integrated circuit fabrication requiring 9N+ polysilicon for epitaxial layer deposition and substrate manufacturing. Demand clusters at Taiwan Semiconductor Manufacturing Company and Intel facilities, where single-digit parts-per-billion metal contamination limits constrain qualified supplier pools to three global producers.
- Chemical Industry:Chlorosilane and silicone precursor applications leveraging polysilicon as feedstock for organosilicon chemistry.
Utility-scale procurement dominates tonnage; semiconductor applications command premium pricing multiples.
End User:
Customer type diversity spans project developers, integrated electronics firms, and institutional research consumers with diverging volume and specification requirements.
- Solar Power Plants:Independent power producers and utility developers procuring polysilicon through long-term offtake contracts tied to module supply agreements. India's NTPC and Saudi ACWA Power anchor procurement scale for gigawatt-scale installations.
- Electronics Firms:Diversified manufacturers sourcing silicon for discrete components and power electronics, with less stringent purity requirements than semiconductor foundries.
- Renewable Energy Consumers:Corporate offtakers and green bond-financed projects demanding carbon intensity disclosures across polysilicon supply chains.
- Research Institutions:National laboratories and university facilities requiring small-batch ultra-high-purity material for next-generation cell architecture development.
Merchant supply concentrates with Solar Power Plants; captive integration favors Electronics Firms.
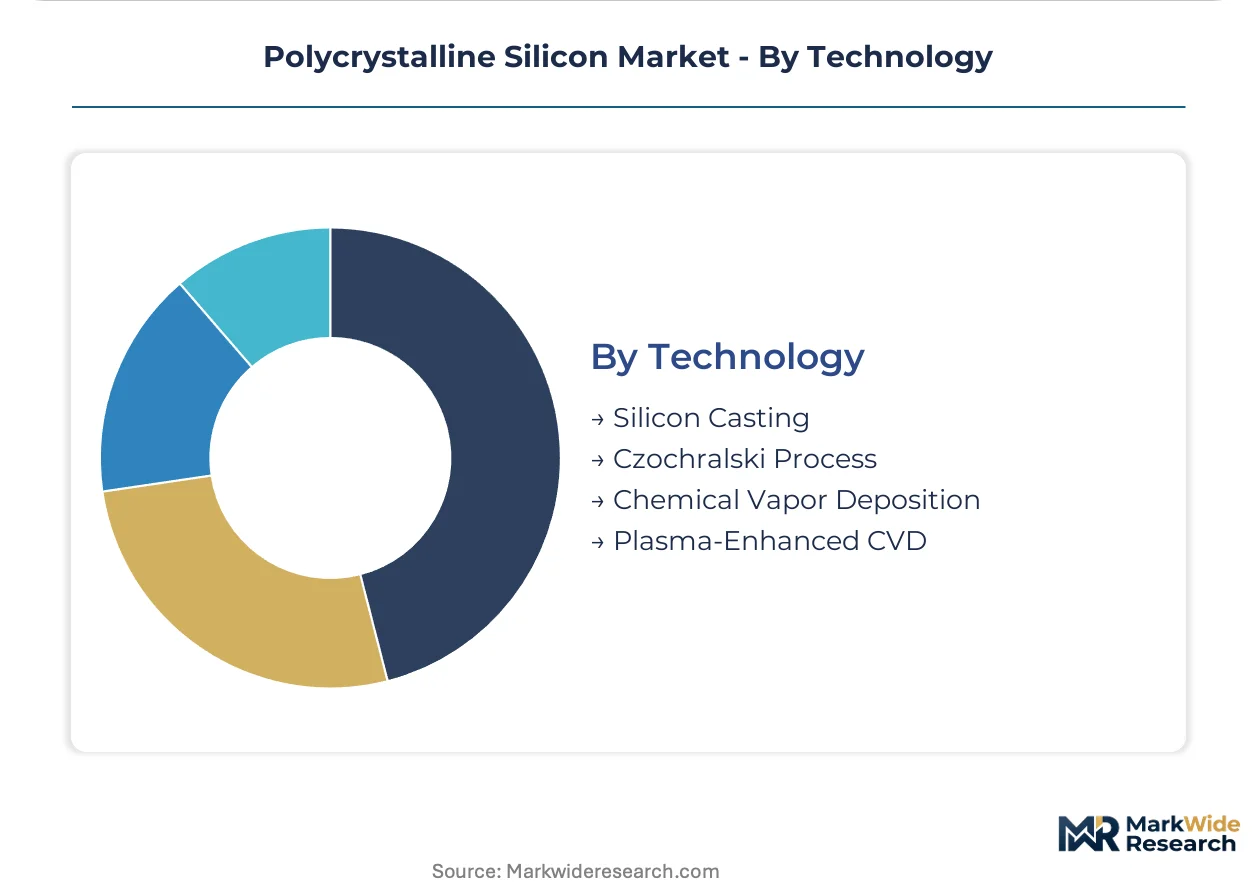
Technology:
Process maturity and capital efficiency separate batch Siemens legacy from continuous deposition alternatives.
- Silicon Casting:Directional solidification methods producing multicrystalline ingots, with equipment depreciation cycles and crucible consumption shaping unit economics.
- Czochralski Process:Single-crystal ingot pulling from polysilicon feedstock, with pull rate and oxygen content control determining wafer yield for semiconductor applications.
- Chemical Vapor Deposition:Dominant polysilicon purification technology using trichlorosilane or silane decomposition at high temperature. The Siemens process variant consumes 40-60 kWh per kilogram, driving relocation to Sichuan hydropower corridors under China's MEE emissions enforcement.
- Plasma-Enhanced CVD:Low-temperature deposition enabling thin-film and heterojunction cell architectures, with equipment utilization rates below thermal CVD but substrate flexibility advantages.
Thermal CVD retains volume leadership; plasma-enhanced variants are gaining share fastest in heterojunction cell integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and India's PLI-linked solar manufacturing incentives are redirecting polysilicon capacity toward hydropower corridors and domestic conversion facilities. The United States and Germany enforce divergent chemical handling standards that shape where purification stages locate. Southeast Asian module assembly clusters in Vietnam and Thailand create intermediate demand nodes between Chinese feedstock and Western project developers.
China
Xinjiang's coal-dependent producers face MEE emissions enforcement that restricts expansion licenses, forcing relocation to Sichuan's hydropower-rich southwestern corridor where Tongwei and Daqo operate megaton-scale facilities. The dual carbon policy framework prioritizes clean energy access over legacy cost advantages. Sichuan's Yalong River and Jinsha River basins host the densest concentration of solar-grade polysilicon capacity globally.
India
NTPC and ACWA Power anchor gigawatt-scale solar procurement that strains imported feedstock dependencies under the PLI scheme for domestic module assembly. The Central Electricity Authority mandates renewable purchase obligations that lock in crystalline silicon demand. Gujarat's Mundra and Andhra Pradesh's Kakinada clusters emerge as polysilicon conversion candidates under tariff protection regimes.
United States
Domestic content bonuses in the Inflation Reduction Act incentivize polysilicon sourcing for module assembly serving utility-scale developers. EPA process safety management audits impose multi-quarter compliance timelines on greenfield cracking and distillation projects. Hemlock Semiconductor's Tennessee operations and REC Silicon's Moses Lake facility represent surviving merchant capacity amid import competition.
Germany
Wacker Chemie's Burghausen complex anchors European semiconductor-grade supply through REACH-compliant chlorosilane handling protocols. The EU F-Gas Regulation forces vent gas recovery retrofits at trichlorosilane distillation facilities. Bavaria's chemical park infrastructure absorbs compliance costs more readily than merchant chlorosilane purchasers lacking backward integration.
Japan
Tokuyama Corporation serves domestic semiconductor foundries and thin-film deposition equipment makers with silane-based chemistry. METI energy security frameworks prioritize supply chain resilience for chip manufacturing inputs. Kyushu's industrial corridor hosts specialty polysilicon operations serving heterojunction cell architectures and epitaxial wafer markets.
Polycrystalline Silicon Market Competitive Environment
On the supply side, the industry is consolidating around integrated majors with captive energy access and specialized purity capabilities, while mid-scale entrants exploit modular reactor leasing to narrow capital barriers. Three archetypes dominate: hydropower-anchored Chinese solar-grade specialists, German-Japanese semiconductor-grade purists with TCS backward integration, and Western merchant survivors leveraging IRA domestic content rules. Capacity expansion and geographic relocation constitute the dominant competitive moves, with players abandoning coal-dependent corridors for clean-energy-licensed zones.
Within the integrated Chinese tier, Tongwei Co., Ltd exemplifies the hydropower-cost-leadership archetype through its Sichuan-based operations, while Daqo New Energy Corp. occupies the ultra-high-purity specialist position serving semiconductor foundries. Wacker Chemie AG anchors the European premium-grade segment through its Burghausen complex. These three represent the strategic poles—cost-optimized solar, purity-optimized electronics, and regulatory-optimized regional supply—around which competitive positioning organizes.
| Leading Market Players |
|---|
| Tongwei Co., Ltd |
| Wacker Chemie AG |
| GCL Technology Holdings Limited |
| Xinte Energy Co., Ltd |
| Daqo New Energy Corp. |
| OCI Company Ltd. |
| Hemlock Semiconductor Corporation |
| REC Silicon ASA |
| Tokuyama Corporation |
| Others |
Value Chain & Pricing Dynamics
Xinjiang's coal-dependent polysilicon corridors face MEE emissions enforcement that restricts expansion licenses, redirecting capacity toward Sichuan's hydropower basins where clean energy access determines license eligibility and downstream pricing power. This geographic shift concentrates solar-grade supply among hydropower-anchored producers while electronic-grade premiums widen at qualified semiconductor-grade facilities.
Pricing Analysis
Purity grade creates the primary spread between solar-grade and electronic-grade quotations, with 9N+ semiconductor specifications commanding substantial premiums over 6N-7N photovoltaic feedstock. Three-tier pricing structure across electronic-grade premium, solar-grade standard, and metallurgical-grade economy levels reflects certification investment and distillation train complexity. Cost compression in solar-grade tiers is intensifying because fluidized bed reactor entrants achieve Siemens process parity without equivalent capital intensity. Utility-scale module assemblers exhibit highest price sensitivity, while semiconductor foundries prioritize purity guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for module assemblers qualifying for IRA domestic content bonuses. Production concentrates in China, Germany, and the United States, with Sichuan province and Bavaria's chemical parks anchoring cost-optimized and premium-grade corridors respectively. Raw material dependencies rest on metallurgical-grade silicon, trichlorosilane, and high-purity hydrogen. Single-source vulnerability concentrates at chlorosilane distillation stages where REACH and EPA handling certifications constrain qualified supplier pools. Distribution runs through long-term offtake contracts with embedded emissions verification clauses audited against ISO 14064-1 protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting and supply chain traceability services represent a faster-expanding recurring-revenue layer than polysilicon hardware production, as module assemblers consolidate supplier panels and demand granular emissions disclosures for every production stage.
For Market Incumbents: Harden quality control scaling through ICP-MS and glow discharge mass spectrometry capability acquisition, addressing the semiconductor-grade analytical chemistry talent shortage that constrains 9N+ output expansion. Defend margin position by relocating remaining Xinjiang capacity to Sichuan hydropower corridors before MEE enforcement tightens. Prioritize backward integration into trichlorosilane chemistry to absorb EU F-Gas Regulation compliance costs more readily than merchant chlorosilane purchasers. For New Entrants and Emerging Players: Pursue modular reactor leasing arrangements and fluidized bed reactor chemistry to narrow capital barriers for mid-scale solar-grade entry. Target India's PLI-linked solar manufacturing incentives where domestic polysilicon conversion capacity remains underdeveloped relative to module assembly scale. Exploit asset-light deployment models serving n-type wafer growers adopting granular polysilicon morphologies for improved melt homogeneity. For Investors and Strategic Acquirers: Long-term, this sits as a clean-energy-credential play because carbon border adjustment mechanisms and green bond financing requirements are embedding emissions verification into procurement qualification. Acquisition targets should concentrate on hydropower-anchored producers with ISO 14064-1 audit infrastructure and Sichuan or Norwegian clean energy credentials. Watch EU F-Gas Regulation implementation pace as inflection indicator for trichlorosilane distillation facility retrofit requirements and compliance cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Relocation to Hydropower Corridors | Secures MEE license eligibility under China's dual carbon enforcement framework. |
| Backward Integration into Trichlorosilane | Absorbs EU F-Gas Regulation vent gas recovery costs at Burghausen-type chemical parks. |
| Granular Polysilicon Morphology Adoption | Enables smaller furnace operators to achieve Czochralski throughput parity with integrated majors. |
| ISO 14064-1 Emissions Verification Certification | Qualifies suppliers for European green bond-financed project developer procurement panels. |
| ICP-MS Analytical Chemistry Capability Buildout | Addresses glow discharge mass spectrometry expertise scarcity constraining 9N+ semiconductor-grade expansion. |
Study Parameters
Cross-validation between primary interviews with polysilicon plant managers, solar module procurement leads, semiconductor foundry supply chain directors, and chlorosilane distribution channel partners anchors the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings, MEE emissions enforcement disclosures, and IEA renewable energy deployment statistics. Bottom-up capacity modeling and top-down demand triangulation reconcile across the analysis window.
Calibration against historical capacity utilization rates and purity-grade pricing spreads shapes the analytical framework across product type, application, technology, and regional production hub segmentation. CAGRs derive from slope-consistent trajectory fitting moderated by regulatory enforcement timing and technology substitution elasticity. Forecast inputs incorporate China's dual carbon policy implementation pace, India's PLI scheme disbursement schedules, and EU carbon border adjustment mechanism phase-in thresholds.
Sensitivities concentrate around MEE enforcement intensity in Xinjiang, IRA domestic content bonus qualification interpretations, and fluidized bed reactor chemistry adoption curves. Forecasts reflect documented assumptions regarding hydropower license allocation and chlorosilane handling certification timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
North America Silicone Market