
 Mexico Pressure Sensor Market | 2026-2036
Mexico Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Pressure Sensor Market Foresight
NOM-001-SECRE-2010 energy efficiency standards for industrial equipment is pivoting procurement specifications toward higher-accuracy pressure sensors in manufacturing facilities. Bosch Sensortec GmbH leverages MEMS miniaturization expertise to sustain design wins with tier-one automotive suppliers. Honeywell International Inc. anchors its position through backward integration into silicon wafer processing for piezoresistive elements. Sensata Technologies Inc. differentiates via application-specific calibration protocols serving oilfield service operators in Veracruz and Tabasco.
A pressure sensor converts fluid or gas pressure into an analog electrical signal, typically employing strain gauges, capacitive plates, or piezoelectric crystals bonded to a diaphragm with sensitivity ranges from millibars to thousands of PSI for process monitoring and safety interlock systems. Gauge sensors dominate unit volume in Mexico's automotive assembly plants where tire pressure monitoring and fuel rail measurement represent high-volume repeat demand. MEMS technology captures the fastest expansion trajectory as foundries in Guadalajara and Tijuana scale wafer-level packaging capacity for consumer and medical device crossover applications.
Secretaría de Economía (SE) oversees NOM certification compliance for measurement instruments deployed in trade and industrial safety contexts, while PROFEPA enforces environmental monitoring mandates that require calibrated pressure instrumentation for emissions control systems. Cofepris medical device regulations shape validation protocols for sensors integrated into ventilators and dialysis equipment produced in Mexico City and Querétaro medical device parks. Stakeholders must monitor pending updates to NOM-113-STPS-2009 workplace safety standards that could mandate redundant pressure sensing in hazardous process environments.
Market Dynamics
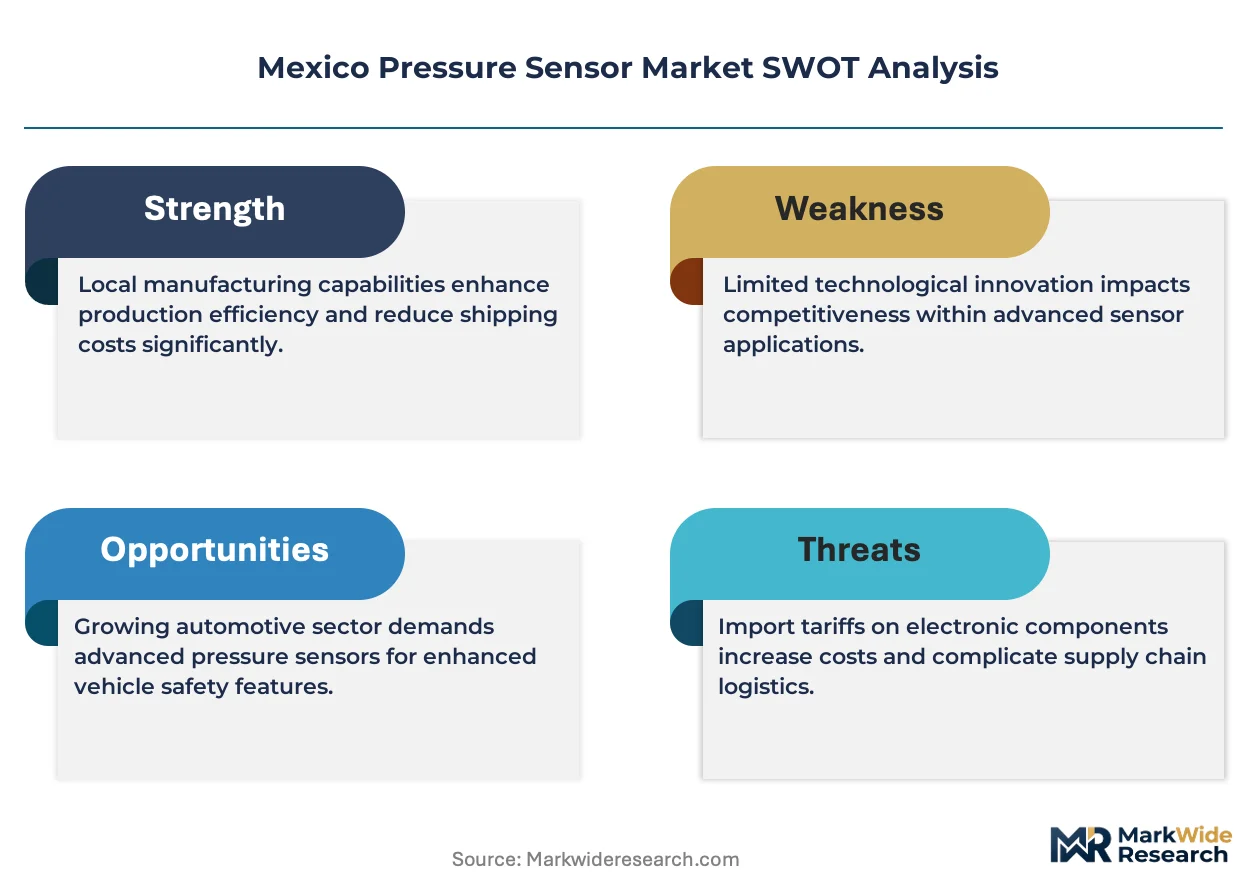
NOM-001-SECRE-2010 energy efficiency mandates are compressing replacement cycles across Mexican manufacturing plants, forcing specification upgrades from analog to digital pressure sensing architectures with integrated diagnostics.
Growth Catalysts
- TPMS mandates:Mexican automotive assembly plants must integrate tire pressure monitoring systems into all light vehicle platforms, sustaining high-volume demand for gauge pressure sensors with automotive-grade reliability ratings.
- Industry 4.0 adoption:Manufacturing clusters in Querétaro and Guanajuato are deploying networked pressure sensors with IO-Link connectivity for predictive maintenance workflows in CNC machining and plastic injection operations.
- Medical device park expansion:Cofepris validation protocols for ventilator and dialysis equipment are accelerating sensor qualification programs in Mexico City and Querétaro production facilities.
Market Restraints
- Silicon wafer supply concentration:Domestic piezoresistive element production remains limited, forcing Mexican sensor assemblers to rely on imported MEMS die from Asian foundries with extended lead times.
- Specialized calibration infrastructure gaps:Oilfield service operators in Veracruz and Tabasco face capacity constraints for high-pressure calibration services above 10,000 PSI, delaying field deployment of downhole sensors.
- Substitution by ultrasonic flow meters:Water treatment facilities in Monterrey and Tijuana are piloting non-invasive ultrasonic alternatives for certain pressure-derived flow calculations, compressing addressable volume in municipal applications.
Strategic Opportunities
- Yucatán Peninsula industrialization:The Progreso deepwater port and Mérida aerospace cluster present greenfield deployment opportunities for pressure instrumentation in fuel systems and hydraulic test rigs.
- AgTech irrigation automation:Drip irrigation networks in Sinaloa and Baja California vegetable belts require soil moisture-integrated pressure sensors for precision water management, an emerging application with limited incumbent suppliers.
- PROFEPA emissions enforcement:Strengthened environmental monitoring mandates are creating calibrated pressure instrumentation demand for continuous emissions monitoring systems at cement plants and refineries.
Industry Challenges
- MEMS packaging technician shortage:Guadalajara and Tijuana foundries struggle to hire wafer-level bonding specialists, constraining capacity expansion for consumer-grade pressure sensor crossover production.
- NOM certification timeline compression:SECRETARÍA DE ECONOMÍA approval cycles for measurement instruments used in trade applications extend 14-18 months, delaying revenue recognition for new product introductions.
- Legacy 4-20mA integration complexity:Digital IO-Link sensors face retrofit friction in established process plants where HART protocol infrastructure dominates, requiring dual-output product variants that increase unit cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Pressure Sensor Market |
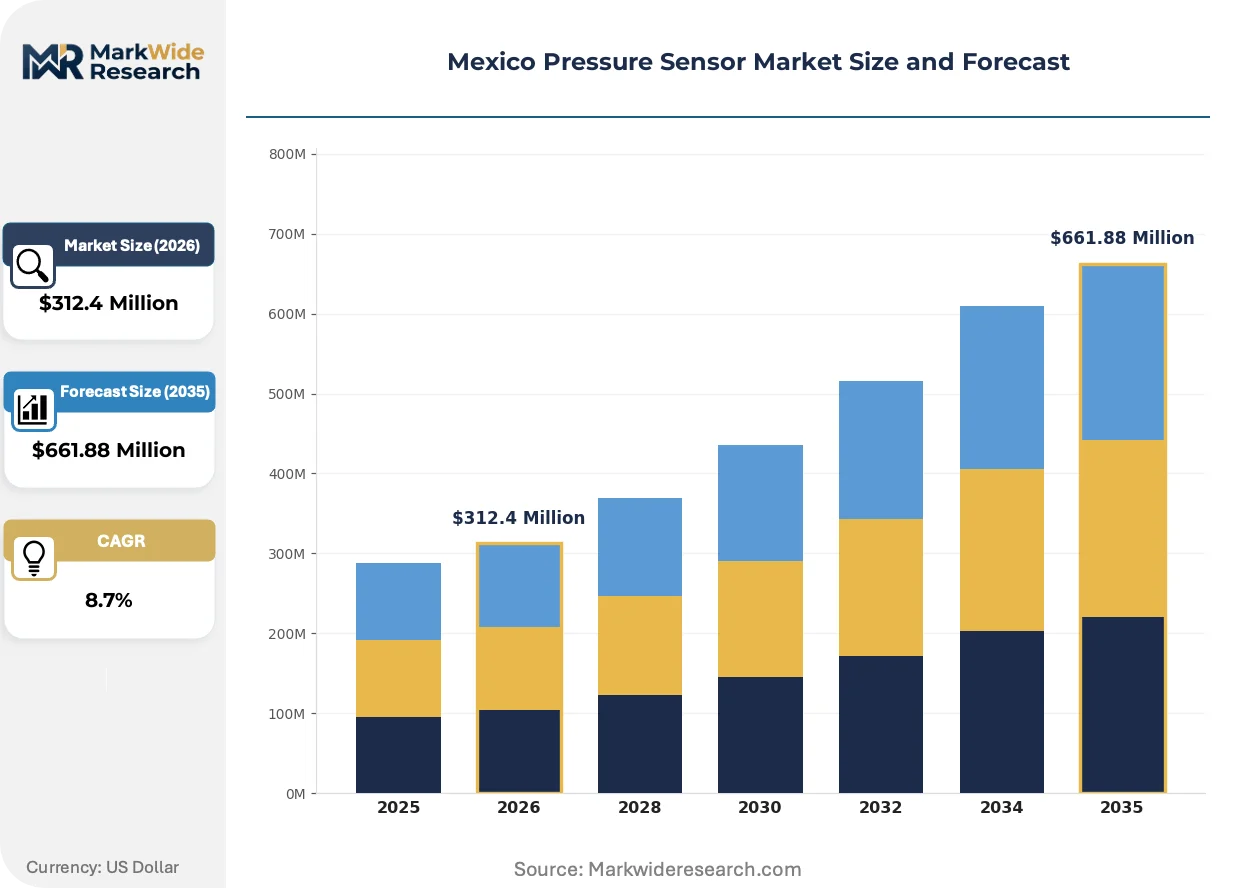
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Sensors, Gauge Sensors, Differential Sensors, Multi-Function Sensors End User: Automotive, Aerospace, Industrial Automation, HVAC Technology: MEMS, Piezoresistive, Capacitive, Optical Application: Process Control, Oil & Gas, Medical Devices, Environmental Monitoring |
| Companies Covered | Bosch Sensortec GmbH, Endress+Hauser AG, Honeywell International Inc., Siemens AG, Danfoss, Sensata Technologies Inc., ABB Ltd, NXP Semiconductors N.V., TE Connectivity, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Pressure Sensor Market Shifts & Advancements
MEMS fabrication advances and digital communication protocols are restructuring how Mexican industrial buyers specify pressure instrumentation, compressing the performance gap between automotive-grade and general-purpose sensors.
Silicon carbide MEMS pressure sensing is converging with high-temperature engine management applications in Mexican automotive plants, where tier-one suppliers are qualifying ceramic-diaphragm designs for exhaust gas recirculation systems operating above 300°C. Powertrain engineers at Puebla and Ramos Arizpe assembly facilities are accelerating validation timelines from 24 to 14 months. This convergence is compressing the addressable market for traditional stainless steel capacitive sensors in underhood environments.
Pending updates to NOM-113-STPS-2009 workplace safety standards are mandating redundant pressure sensing in hazardous process environments, requiring dual-channel architectures with independent diagnostic circuits. Chemical processors in Tamaulipas and Coahuila are pre-qualifying SIL-rated transmitters ahead of formal enforcement. Oil and gas gathering stations in Burgos Basin are most affected, with operators budgeting for parallel instrument installations rather than single-sensor retrofits.
Sensor-as-a-service procurement models are displacing capital purchase arrangements among mid-sized plastic injection molders in Guadalajara's manufacturing corridor. Equipment lessors now bundle calibrated pressure transducers with maintenance subscriptions, transferring obsolescence risk from plant engineers to instrumentation providers. This shift is most visible in automotive supplier parks where OEMs dictate supplier-managed inventory terms for auxiliary equipment.
Mexico Pressure Sensor Market Segmentation
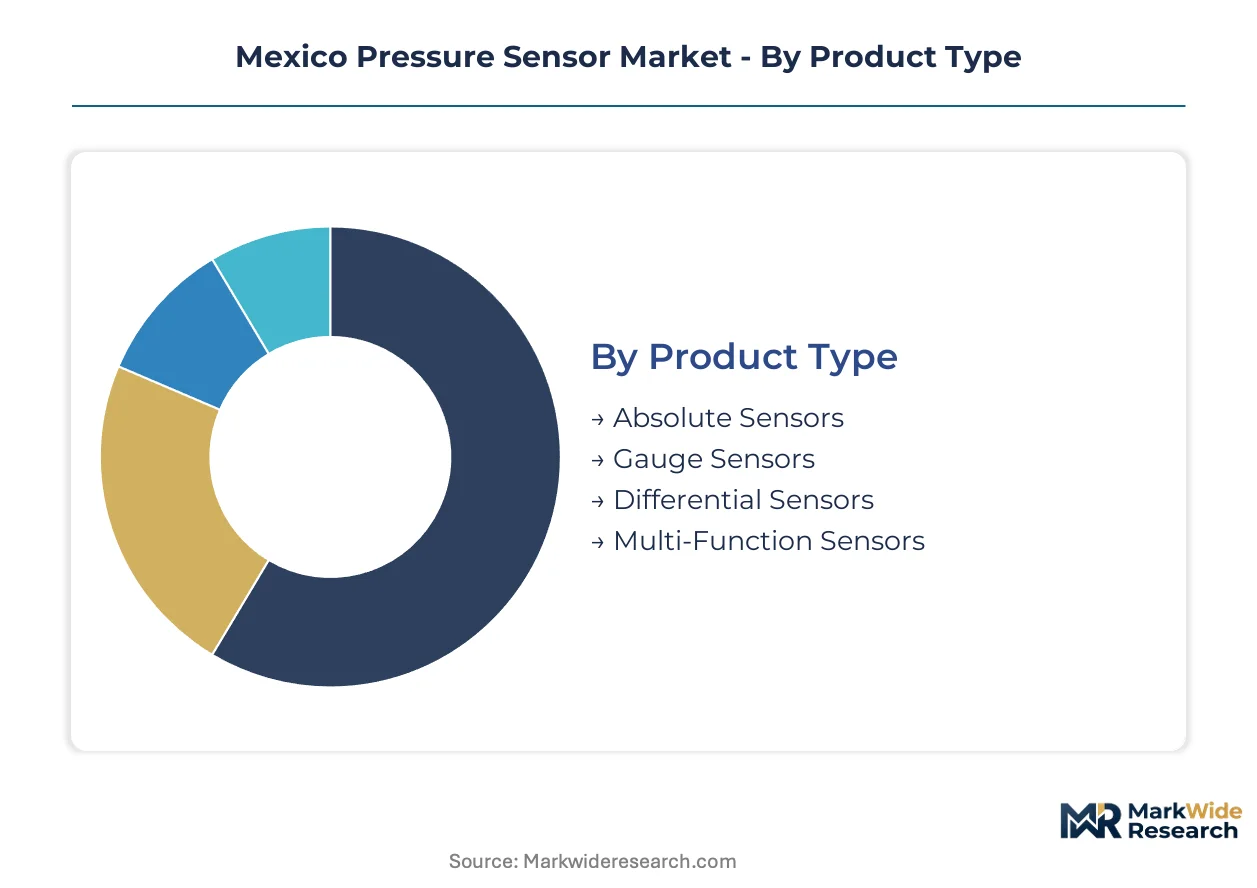
Pressure sensor procurement patterns in Mexico diverge sharply between high-volume automotive assembly and precision-driven medical device manufacturing. Specification requirements from NOM certification and OEM supplier mandates create distinct technical thresholds across each segment boundary.
Product Type:
Gauge sensors dominate unit volume in tire pressure monitoring and fuel rail applications, while absolute sensors command premium positioning in aerospace and medical validation protocols.
- Absolute Sensors:These reference vacuum-sealed cavities to measure pressure against a perfect zero baseline, enabling altitude compensation in aircraft systems and precise barometric correction for ventilator flow control. Demand concentrates in Querétaro's aerospace cluster and Mexico City medical device parks where Cofepris validation requires traceable calibration chains.
- Gauge Sensors:Venting to atmospheric pressure simplifies installation and reduces unit cost, making these the default specification for TPMS modules and engine management systems across Puebla and Ramos Arizpe assembly plants. Bosch Sensortec and Honeywell anchor supply relationships through automotive-grade reliability ratings and backward integration into silicon wafer processing.
- Differential Sensors:Dual-port architectures measure pressure variance between two process points, serving HVAC airflow monitoring and filter clog detection in Monterrey commercial buildings.
- Multi-Function Sensors:Integrated temperature-pressure outputs reduce wiring complexity in transmission control modules and hydraulic test rigs, gaining traction in Guanajuato Industry 4.0 deployments.
Mature deployment sits with gauge sensors. Newer deployment is concentrated in multi-function sensors.
End User:
Automotive procurement drives scale economies that subsidize technology transfer into adjacent industrial segments.
- Automotive:Tier-one suppliers at Puebla, Ramos Arizpe, and Saltillo assembly facilities specify piezoresistive and MEMS architectures for engine management, transmission control, and tire pressure monitoring systems. NOM-001-SECRE-2010 energy efficiency mandates are compressing replacement cycles and forcing specification upgrades from analog to digital sensing with integrated diagnostics.
- Industrial Automation:CNC machining and plastic injection operations in Querétaro and Guanajuato are deploying networked pressure sensors with IO-Link connectivity for predictive maintenance workflows, climbing the fastest among end-use categories as foundries scale wafer-level packaging capacity.
- Aerospace:Mérida's emerging cluster and established Chihuahua maintenance facilities require high-reliability absolute sensors with extended temperature ranges for fuel system and hydraulic test applications.
- HVAC:Commercial building automation in Monterrey and Tijuana specifies differential sensors for airflow balancing, though ultrasonic alternatives are compressing addressable volume in certain flow calculation applications.
Volume procurement centers on automotive. Margin expansion is concentrating in aerospace qualification programs.
Technology:
MEMS miniaturization is displacing traditional piezoresistive architectures in cost-sensitive applications while ceramic-diaphragm designs capture high-temperature engine bay positioning.
- MEMS:Silicon micromachining enables sub-millimeter form factors with wafer-level packaging economies, scaling production at Guadalajara and Tijuana foundries for consumer crossover and medical device applications. Technician shortages for wafer-level bonding constrain capacity expansion.
- Piezoresistive:Diffused silicon strain gauges bonded to stainless steel diaphragms deliver proven automotive reliability, anchoring Honeywell's position through in-house silicon processing and backward integration into wafer supply.
- Capacitive:Ceramic or metal diaphragms with capacitive plates offer media isolation for aggressive process fluids, serving chemical processors in Tamaulipas ahead of pending NOM-113-STPS-2009 redundant sensing mandates.
- Optical:Fiber Bragg grating and interferometric architectures eliminate electromagnetic interference in oilfield downhole and high-voltage substation applications, though calibration infrastructure gaps above 10,000 PSI delay deployment in Veracruz and Tabasco.
Established production runs through piezoresistive. Steepest expansion trajectory belongs to MEMS.
Application:
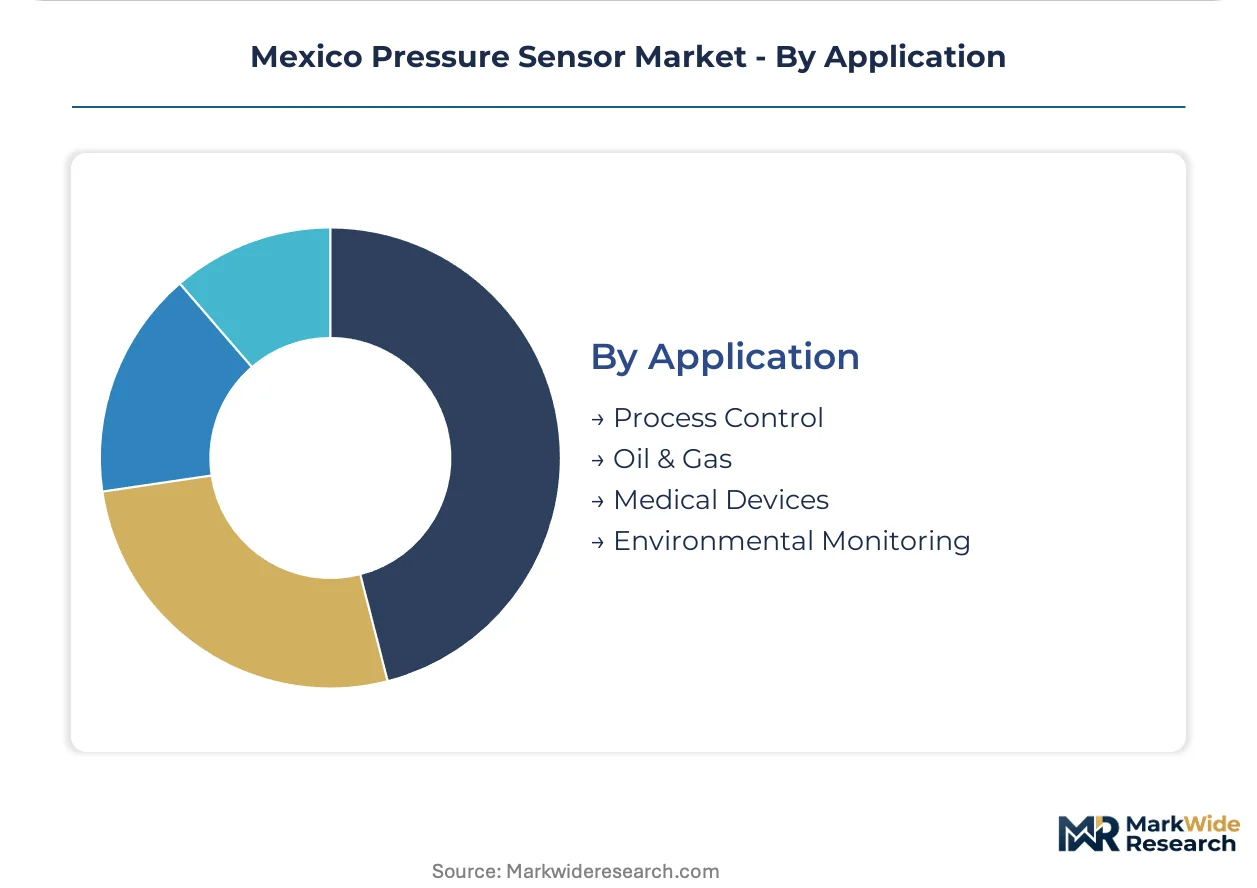
Process control and oilfield service demand shapes high-pressure specification requirements, while medical device validation creates barrier-to-entry dynamics for qualified suppliers.
- Process Control:Chemical processors and food packaging lines specify sanitary pressure transmitters with tri-clamp connections, with SIL-rated architectures gaining pre-qualification momentum in Tamaulipas and Coahuila ahead of workplace safety standard updates.
- Oil & Gas:Downhole pressure-temperature monitoring in Burgos Basin and offshore Veracruz requires specialized calibration protocols that Sensata Technologies addresses through application-specific service programs, though capacity constraints for ultra-high-pressure validation delay field deployment.
- Medical Devices:Cofepris validation protocols for ventilators and dialysis equipment produced in Mexico City and Querétaro medical device parks accelerate sensor qualification timelines and compress supplier lists to pre-approved vendors.
- Environmental Monitoring:PROFEPA emissions enforcement mandates are creating calibrated instrumentation demand for continuous emissions monitoring systems at cement plants and refineries, with redundant sensor architectures specified for regulatory defensibility.
Regulatory-driven replacement is strongest in environmental monitoring. Longest validation cycles persist in medical devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bajío's automotive corridor concentrates Mexico's pressure sensor procurement, with OEM supplier density at Puebla and Ramos Arizpe assembly plants driving specification standardization across tier-one networks.
Bajío Region
Querétaro and Guanajuato manufacturing clusters deploy networked pressure sensors with IO-Link connectivity for predictive maintenance in CNC machining operations. NOM-001-SECRE-2010 energy efficiency mandates compress replacement cycles toward digital architectures. Foundries in Querétaro scale wafer-level packaging capacity for consumer crossover applications.
Northern Border States
Tijuana and Ciudad Juárez electronics assembly plants source MEMS pressure sensors for medical device and automotive crossover production. Cofepris validation protocols for ventilator equipment accelerate sensor qualification timelines. Technician shortages for wafer-level bonding constrain capacity expansion at Guadalajara-serving facilities.
Mexico City Metro
Medical device parks in Mexico City and adjacent Querétaro facilities drive demand for absolute pressure sensors with traceable calibration chains. Cofepris regulations shape validation protocols for dialysis and respiratory equipment. Environmental monitoring mandates from PROFEPA create instrumentation demand for cement plant emissions systems.
Nuevo León
Monterrey's commercial building automation sector specifies differential sensors for HVAC airflow balancing, though ultrasonic alternatives compress addressable volume in certain flow calculations. Industrial automation in the state's manufacturing corridor climbs fastest among end-use categories as Industry 4.0 adoption accelerates specification upgrades.
Yucatán Peninsula
Progreso deepwater port development and Mérida's emerging aerospace cluster present greenfield deployment opportunities for fuel system and hydraulic test instrumentation. Pending infrastructure investments could establish calibrated pressure sensor demand for port logistics and maintenance operations without incumbent supplier relationships.
Mexico Pressure Sensor Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive MEMS fabrication capacity. Tier-one automotive suppliers consolidate procurement around vendors with backward integration into silicon wafer processing and in-house calibration infrastructure. Three archetypes dominate: automotive-grade specialists with AEC-Q100 qualification, process automation multinationals with SIL-rated transmitter portfolios, and MEMS foundries scaling wafer-level packaging for consumer crossover. Capacity expansion and strategic partnerships represent the dominant competitive moves as players address technician shortages and NOM certification timeline compression.
Among Germany-based fabricators, Bosch Sensortec GmbH and Endress+Hauser AG exemplify divergent archetypes within the supplier base. Bosch Sensortec occupies a position as an automotive-grade MEMS specialist, while Endress+Hauser represents the process automation multinational model. Honeywell International Inc., as a US-based industrial conglomerate, anchors the tier-one supplier relationships through captive silicon processing capabilities. Sensata Technologies Inc. exemplifies the application-specific calibration approach serving specialized industrial segments.
| Leading Market Players |
|---|
| Bosch Sensortec GmbH |
| Endress+Hauser AG |
| Honeywell International Inc. |
| Siemens AG |
| Danfoss |
| Sensata Technologies Inc. |
| ABB Ltd |
| NXP Semiconductors N.V. |
| TE Connectivity |
| Others |
Supply & Pricing Matrix
Automotive-grade AEC-Q100 certification separates premium pressure sensors from commodity alternatives in Mexico, with that performance gap translating into silicon wafer sourcing from captive foundries versus spot-market MEMS die procurement. NOM certification timelines and tier-one supplier qualification protocols create pricing power for backward-integrated vendors while compressing margins for assembly-only competitors dependent on Asian foundry supply.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and predictive maintenance outcomes dominates Industry 4.0 deployments in Querétaro and Guanajuato manufacturing corridors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with automotive OEM procurement teams exhibiting lowest price sensitivity due to liability exposure and Cofepris-validated medical device manufacturers accepting premium positioning for traceable calibration chains. Cost compression in gauge sensor tiers is intensifying because Guadalajara and Tijuana foundries are scaling wafer-level packaging capacity for consumer crossover applications.
Supply Chain Analysis
Refurbishment flows for industrial pressure transmitters create secondary supply channels serving mid-sized plastic injection molders in Guadalajara's manufacturing corridor. Silicon wafer supply concentrates in Taiwan, South Korea, and the United States, with Mexican sensor assemblers drawing from imported MEMS die for piezoresistive element production. Single-source vulnerability sits with Asian foundry concentration for consumer-grade crossover applications. Distribution runs through tier-one automotive supplier networks and direct OEM relationships anchored by SECRETARÍA DE ECONOMÍA trade measurement certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS packaging technician shortages at Guadalajara and Tijuana foundries are constraining capacity expansion, propping pricing power for incumbents with in-house wafer-level bonding capabilities.
For Market Incumbents: Deepen backward integration into silicon wafer processing to secure supply continuity against Asian foundry lead time volatility, while accelerating NOM certification pre-qualification programs to compress 14-18 month SECRETARÍA DE ECONOMÍA approval cycles. Sensor-as-a-service procurement models among automotive supplier parks threaten capital equipment margins; counter through bundled maintenance subscriptions that transfer obsolescence risk from plant engineers to instrumentation providers. For New Entrants and Emerging Players: Equipment lessors represent the most penetrable channel partner type for bypassing entrenched tier-one supplier relationships, particularly in mid-sized plastic injection operations seeking calibrated pressure transducer bundles with maintenance subscriptions. Target Yucatán Peninsula greenfield deployments at Progreso deepwater port and Mérida aerospace cluster where incumbent supplier relationships remain unformed. Lead with application-specific calibration protocols for oilfield service operators in Veracruz and Tabasco facing capacity constraints above 10,000 PSI. For Investors and Strategic Acquirers: Re-rating potential sits with MEMS foundries scaling wafer-level packaging capacity given Guadalajara and Tijuana technician shortage dynamics and automotive-to-medical device crossover demand acceleration. Long-term viability favors acquisition targets with captive silicon processing and established Cofepris validation protocols for ventilator and dialysis equipment production. Monitor NOM-113-STPS-2009 workplace safety standard enforcement timing as inflection indicator for redundant pressure sensing mandate implementation across chemical processors in Tamaulipas and Coahuila.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Capacity Expansion | Addresses technician shortage constraints at Guadalajara and Tijuana MEMS foundries serving automotive crossover demand. |
| NOM Certification Pre-Qualification Investment | Compresses SECRETARÍA DE ECONOMÍA approval cycles from 14-18 months for measurement instruments used in trade applications. |
| Sensor-as-a-Service Business Model Transition | Captures recurring revenue from automotive supplier parks where OEMs dictate supplier-managed inventory terms. |
| Application-Specific Calibration Infrastructure | Secures design wins with oilfield service operators in Veracruz and Tabasco requiring specialized protocols above 10,000 PSI. |
| Silicon Carbide MEMS Qualification | Enables high-temperature engine management positioning above 300°C for exhaust gas recirculation systems at Puebla and Ramos Arizpe. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tier-one automotive supplier procurement teams, MEMS foundry operations managers, SECRETARÍA DE ECONOMÍA certification specialists, and Cofepris validation consultants. SEC 10-K disclosures, Mexican customs import records, and NOM regulatory databases provided cross-referenced validation points. Bottom-up sensor shipment estimates triangulated against top-down automotive production and industrial automation capex flows.
Product type, end user, technology, and application dimensions were modeled at the SKU level across the projection horizon, with regional clusters disaggregated to Bajío corridor, northern border states, Mexico City metro, Nuevo León, and Yucatán Peninsula. CAGRs derived from regression analysis against automotive assembly volumes, Industry 4.0 adoption indices, and medical device park expansion trajectories. Forecast inputs incorporated NOM-001-SECRE-2010 energy efficiency mandate compliance timelines and PROFEPA emissions enforcement intensity assumptions.
Caveats apply where silicon wafer supply disruptions, NOM certification timeline compression, or MEMS packaging technician shortage resolution could materially shift the outlook. Practitioners should monitor SECRETARÍA DE ECONOMÍA regulatory update announcements and Asian foundry capacity expansion signals for early indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Thermistor Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market