
 Rotary and RF Rotary Joints Market | 2026-2036
Rotary and RF Rotary Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary and RF Rotary Joints Market Outlook
Modular packaging of RF rotary joints with integrated fiber optic channels and embedded position sensors is realigning how system integrators specify procurement bundles. Moog Inc. leverages its heritage in precision motion control to anchor high-reliability military and aerospace contracts. Spinner GmbH specializes in waveguide-based rotary joint configurations for satellite communications ground infrastructure. Kadant Inc. competes across industrial automation with rotary unions that extend into combined fluid-power and signal transfer platforms.
Rotary and RF rotary joints are electromechanical devices that maintain electrical continuity between stationary and rotating structures, typically specified by frequency range, insertion loss, voltage standing wave ratio, and rotational life cycles measured in millions of revolutions. Their primary purpose is to enable uninterrupted power and signal transmission in radar antennas, medical CT scanners, robotic arms, and broadcast satellite dishes. RF rotary joints represent the fastest-expanding product category as Ka-band and multi-channel designs displace legacy single-channel units in telecommunications and defense applications. Industrial automation applications command mature volume demand but face margin compression from standardized compact rotary joint imports.
FCC Part 15 emissions standards and EU CE marking requirements under the Radio Equipment Directive shape product certification costs and design cycles for manufacturers selling into North American and European telecommunications and defense markets. Military customers additionally require compliance with MIL-DTL-38999 connector specifications and ITAR-controlled export classifications that restrict supplier base eligibility. Stakeholders must monitor evolving spectrum allocation decisions by national regulators and the trajectory of open-architecture radar programs that could unbundle proprietary rotary joint specifications from prime contractor platforms.
Market Dynamics
Ka-band and multi-channel RF rotary joint architectures are compressing design cycles as defense primes and satellite operators unbundle legacy single-channel specifications from platform-integrated procurement bundles.
Growth Catalysts
- Defense Radar Modernization:NATO procurement agencies are embedding RF rotary joints into next-generation phased array systems for continuous antenna rotation. Military specifications under MIL-DTL-38999 connector standards are expanding addressable contract volumes for qualified suppliers.
- EU Electromagnetic Compatibility Mandates:CE marking requirements under the Radio Equipment Directive are compelling manufacturers to redesign contact interfaces and shielding architectures. Compliance investments are filtering non-specialized competitors from European telecommunications and defense supply chains.
- Precision Engineering Clusters:Concentrated manufacturing capabilities around Munich and Stuttgart in Germany are supplying integrated slip-ring and rotary joint assemblies for satellite ground stations and robotic welding cells. Geographic density reduces logistics costs for system integrators.
Market Restraints
- Raw Material Cost Volatility:Beryllium copper and specialized high-frequency laminates face price instability from concentrated mining and refining operations. Input cost swings compress margin predictability for mid-volume manufacturers.
- Supplier Base Concentration:Qualified suppliers for ITAR-controlled rotary joint classifications remain limited to a narrow tier of defense-cleared manufacturers. Export restriction compliance creates supply bottleneck risk for international programs.
- Technical Performance Ceilings:Rotary life cycles measured in millions of revolutions impose hard physical limits on maintenance intervals for offshore wind turbines and subsea applications. Material fatigue in rotating electrical contacts resists incremental improvement.
Strategic Opportunities
- Medical Imaging Expansion:CT scanner manufacturers in Japan are specifying compact RF rotary joints for gantry rotation systems. PMDA regulatory pathways for diagnostic equipment create certified demand channels.
- Industrial Fiber Optic Convergence:Modular packaging combining RF rotary joints with integrated fiber optic channels and embedded position sensors is opening specification bundles for robotic automation integrators. Technology convergence commands premium positioning.
- US Infrastructure Modernization:IRA-funded grid hardening and broadband expansion programs are stimulating demand for utility-scale antenna systems. Federal procurement preferences for domestic content align with onshore manufacturing investments.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Finite element analysis expertise for high-frequency rotary joint design remains concentrated among specialized engineering consultancies. Workforce gaps extend product development timelines.
- Multi-Standard Certification Burden:Simultaneous compliance with FCC Part 15 emissions standards, EU CE marking, and MIL-SPEC military classifications requires parallel testing tracks. Certification timeline overlap delays revenue recognition.
- Legacy Platform Integration Complexity:Open-architecture radar programs are unbundling proprietary rotary joint specifications from prime contractor platforms. Interface standardization efforts create transitional friction for incumbent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary and RF Rotary Joints Market |
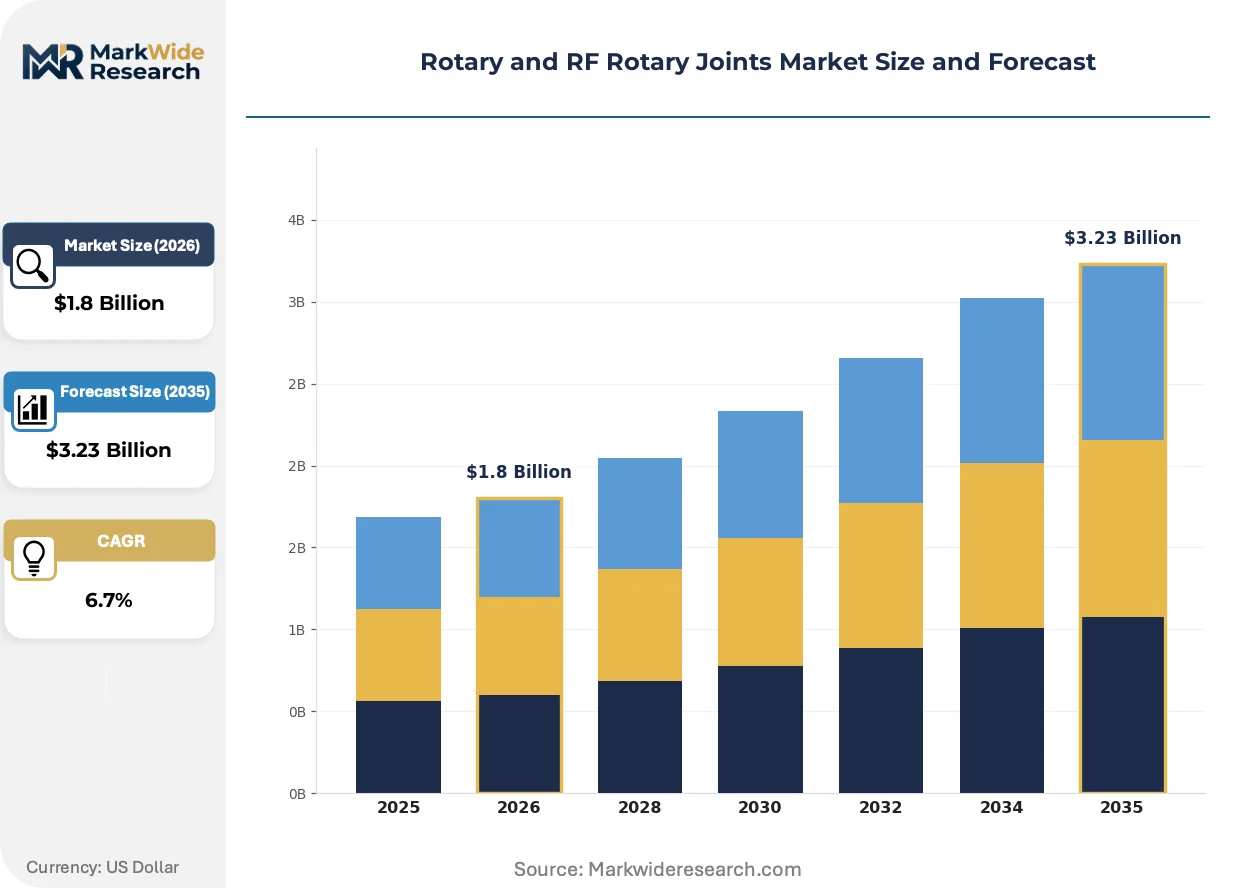
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Rotary Joints, Standard Rotary Joints, Multifunction Rotary Joints, Compact Rotary Joints Industry Vertical: Aerospace, Telecommunications, Medical Devices, Industrial Automation Application: Broadcasting, Robotics, Medical Imaging, Military Equipment Connectivity: Copper, Fiber Optic, Waveguide, Others |
| Companies Covered | Deublin Company, Cobham France SAS, Moog Inc., Macartney Underwater Technology, Spinner GmbH, Kadant Inc., Dynamic Sealing Technologies Inc., Pasternack Enterprises Inc., Columbus McKinnon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary and RF Rotary Joints Market Strategic Shifts
Three interconnected developments are restructuring how rotary joint specifications propagate through defense, telecommunications, and industrial automation supply chains.
Multi-channel waveguide rotary joint configurations are decentralizing procurement authority from prime contractors to subsystem integrators. Satellite ground station operators in Germany and the United States are specifying channel-count-flexible architectures that accommodate Ka-band frequency expansion without platform redesign. This modular approach is compressing supplier qualification cycles and enabling competitive entry for specialized waveguide manufacturers.
FCC Part 15 emissions standards and EU CE marking requirements under the Radio Equipment Directive are mandating shielding redesigns that add material cost but filter marginal competitors. Telecommunications infrastructure deployers in North America and Europe are consolidating supplier lists around manufacturers with pre-certified platform families. The regulatory burden falls heaviest on single-channel legacy product lines that lack architectural headroom for compliance adaptation.
System integrators are unbundling rotary joint procurement from complete antenna platform purchases and negotiating direct supply agreements with specialized manufacturers. Defense primes and broadcast satellite operators are compressing switching cycles by qualifying second-source suppliers for critical rotating interfaces. This disintermediation is most visible in Germany, where precision engineering clusters enable rapid technical collaboration between rotary joint specialists and end-use system architects.
Rotary and RF Rotary Joints Market Segmentation
Rotary joint procurement specifications diverge sharply across defense radar platforms, satellite ground stations, and industrial automation cells. Understanding segment-level technical requirements enables suppliers to align R&D investments with qualified demand channels and certification pathways.
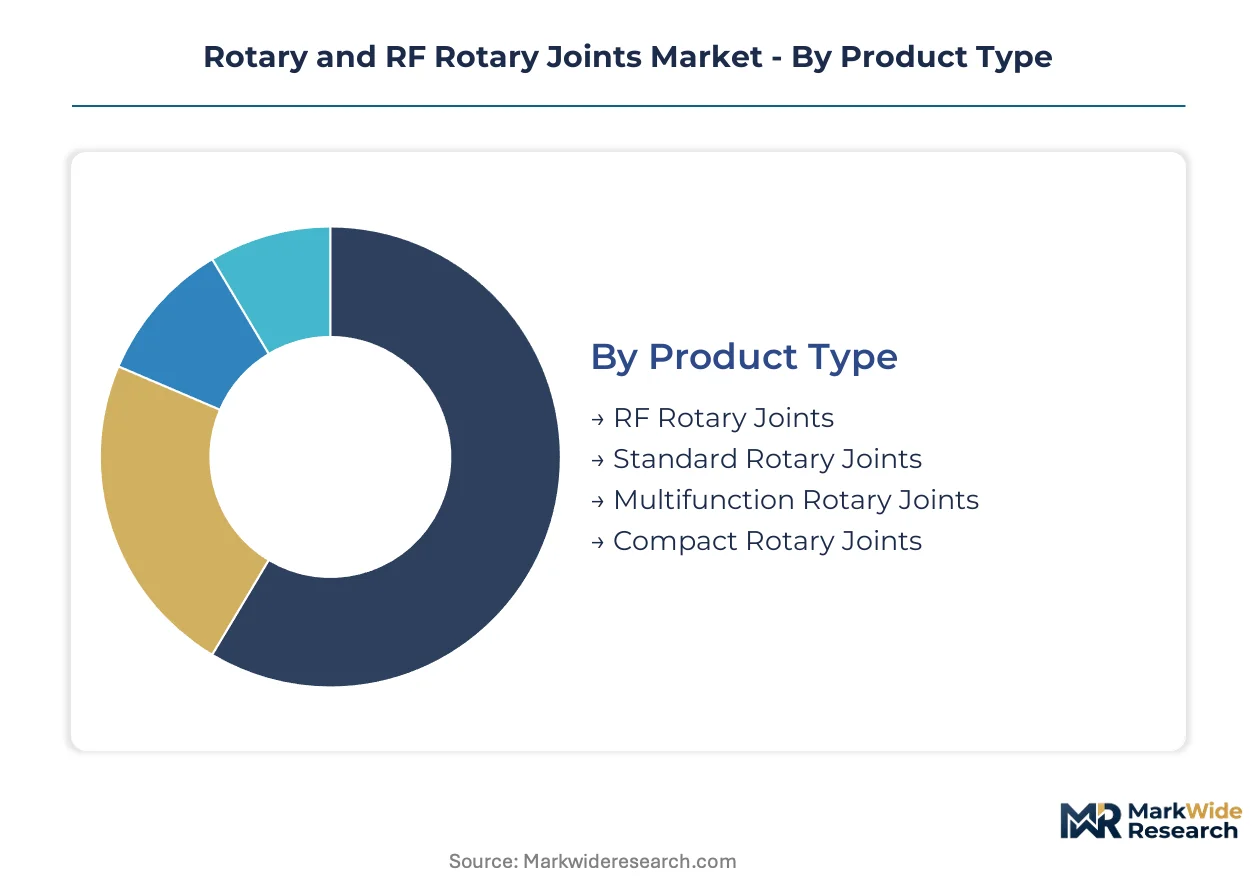
Product Type:
Upgrade cycles from single-channel legacy units to multi-channel architectures are compressing supplier qualification timelines and expanding addressable contract volumes for modular platforms.
- RF Rotary Joints:These devices maintain signal integrity across rotating interfaces in radar antennas and satellite communications systems, with Ka-band configurations displacing legacy L-band and C-band units in NATO defense procurement. Ka-band and multi-channel designs are gaining specification share fastest in telecommunications infrastructure deployments.
- Standard Rotary Joints:Conventional electromechanical designs transmit power and low-frequency signals through precious metal contact interfaces, serving mature industrial automation applications where rotational life cycles dominate procurement criteria. Cost pressure from standardized compact imports is compressing margins in this segment.
- Multifunction Rotary Joints:Integrated platforms combining RF channels with fiber optic pathways and position sensing in unified housings.
- Compact Rotary Joints:Miniaturized configurations for medical CT scanner gantries and robotic end-effectors where space constraints override channel count.
Standard Rotary Joints sits at the top of the volume ranking, with RF Rotary Joints climbing the fastest.
Industry Vertical:
Cost tier stratification separates military-aerospace qualification investments from industrial automation volume plays.
- Aerospace:Satellite ground stations and airborne radar platforms demand MIL-SPEC certified rotary joints with ITAR-controlled export classifications, concentrating procurement among defense-cleared manufacturers. FCC Part 15 emissions compliance adds parallel certification tracks for domestic content requirements.
- Telecommunications:Broadcast satellite dishes and cellular infrastructure antennas specify RF rotary joints for continuous azimuth and elevation tracking, with EU CE marking under the Radio Equipment Directive filtering supplier eligibility in European markets. Ka-band frequency expansion is driving replacement demand.
- Medical Devices:CT scanner OEMs in Japan specify compact rotary joints for gantry rotation systems, with PMDA regulatory pathways creating certified demand channels distinct from industrial procurement patterns.
- Industrial Automation:Robotic welding cells and material handling systems utilize combined fluid-power and signal transfer platforms, with precision engineering clusters in Germany supplying integrated slip-ring assemblies.
Industrial Automation commands the broadest installation base, while Aerospace delivers the steepest expansion trajectory.
Application:
Customer type differentiation separates defense prime contractor specifications from broadcast operator procurement bundles.
- Broadcasting:Satellite uplink facilities and terrestrial transmission towers specify waveguide-based rotary joints for high-power RF signal transmission, with modular channel-count-flexible architectures enabling frequency band migration without platform redesign.
- Robotics:Industrial automation integrators are unbundling rotary joint procurement from complete robot platform purchases, negotiating direct supply agreements with specialized manufacturers for combined electrical and pneumatic rotating interfaces.
- Medical Imaging:CT scanner gantry rotation systems demand compact RF rotary joints with millions of revolution rotational life cycles, where material fatigue in electrical contacts imposes hard maintenance interval limits.
- Military Equipment:Phased array radar systems for continuous antenna rotation embed multi-channel RF rotary joints meeting MIL-DTL-38999 connector specifications, with open-architecture programs unbundling proprietary specifications from prime contractor platforms.
Military Equipment anchors premium pricing tiers, with Broadcasting gaining specification momentum fastest.
Connectivity:
Supply concentration in specialized materials shapes procurement risk profiles across transmission media categories.
- Copper:Beryllium copper contact interfaces deliver reliable electrical continuity in standard rotary joints, though concentrated mining and refining operations create input cost volatility that compresses margin predictability.
- Fiber Optic:Integrated fiber channels in modular rotary joint packages enable high-bandwidth data transmission immune to electromagnetic interference, commanding premium positioning in robotic automation integrator specification bundles.
- Waveguide:Hollow metallic transmission lines support high-power RF applications in satellite ground stations and radar systems, with specialized manufacturers in Germany and the United States qualifying for defense and telecommunications contracts.
- Others:Hybrid and emerging transmission technologies including coaxial combinations and printed circuit rotary interfaces.
Copper retains the largest installed base, with Fiber Optic expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotary joint manufacturing originated in German precision engineering clusters during the mid-20th century, with Munich and Stuttgart emerging as foundational centers for electromechanical rotating interface technology. This heritage established quality benchmarks that persist across contemporary defense and telecommunications procurement specifications.
United States
Defense radar modernization programs and IRA-funded grid infrastructure expansion drive procurement volumes for multi-channel RF rotary joints. FCC Part 15 emissions standards and ITAR-controlled export classifications filter supplier eligibility for military contracts. Manufacturing concentration in the Northeast Corridor and California defense corridors supports prime contractor integration timelines.
Germany
Satellite ground station operators and robotic welding cell integrators specify integrated slip-ring and rotary joint assemblies from Stuttgart and Munich engineering clusters. CE marking requirements under the Radio Equipment Directive mandate shielding architecture redesigns that elevate compliance costs. Precision manufacturing density enables rapid technical collaboration between specialists and system architects.
Japan
CT scanner OEMs in the Kanto region specify compact RF rotary joints for gantry rotation systems requiring millions of revolution life cycles. PMDA regulatory pathways for diagnostic equipment create certified demand channels distinct from industrial procurement patterns. METI industrial policy supports domestic precision electromechanical component manufacturing.
China
Telecommunications infrastructure deployment for 5G and satellite ground stations stimulates demand for Ka-band rotary joint configurations. MIIT spectrum allocation decisions and GB standards for electromagnetic compatibility shape product certification requirements. Yangtze River Delta manufacturing bases concentrate volume production for standardized compact rotary joint imports.
United Kingdom
Broadcast satellite uplink facilities and defense radar platforms procure waveguide-based rotary joints meeting MIL-SPEC connector standards. Open-architecture radar programs are unbundling proprietary specifications from prime contractor platforms, creating supplier qualification opportunities. London and Southeast England host system integrator engineering centers specifying rotating interfaces.
Rotary and RF Rotary Joints Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and channel-count dimensions. Defense-aerospace qualification investments concentrate procurement among ITAR-cleared manufacturers with MIL-SPEC testing infrastructure, while industrial automation segments fragment across price-competitive standardized imports. Three archetypes dominate: heritage defense contractors with platform-integrated specifications, precision engineering specialists serving satellite and medical verticals, and volume manufacturers supplying robotic automation integrators. Consolidation pressure manifests through strategic partnerships for multi-technology bundles and geographic expansion into precision engineering clusters.
Among heritage precision motion control specialists, Moog Inc. and Spinner GmbH exemplify the defense-aerospace archetype with established qualification pathways. Kadant Inc. occupies a position within industrial automation supply chains, representing the volume-manufacturing tier that competes on combined fluid-power and signal transfer platform integration. These three anchors illustrate how supplier positioning stratifies across certification burden and end-use specification complexity.
| Leading Market Players |
|---|
| Deublin Company |
| Cobham France SAS |
| Moog Inc. |
| Macartney Underwater Technology |
| Spinner GmbH |
| Kadant Inc. |
| Dynamic Sealing Technologies Inc. |
| Pasternack Enterprises Inc. |
| Columbus McKinnon Corporation |
| Others |
Value Chain & Pricing Dynamics
NATO defense procurement agencies and satellite ground station operators concentrate purchasing power around ITAR-cleared manufacturers, anchoring a three-tier pricing structure across premium, standard, and economy levels. Certification-grade stratification separates MIL-SPEC qualified suppliers from industrial automation commodity players, with price differentiation resting on electromagnetic compatibility compliance investment and rotational life cycle performance guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates rotary joint procurement, with premium tiers capturing defense-aerospace contracts demanding MIL-DTL-38999 connector compliance and ITAR-controlled export classifications. Price differentiation feeds from certification grade and volume scale, with Ka-band multi-channel architectures commanding substantial premiums over legacy single-channel units. Cost compression in the standard tier is intensifying because of standardized compact imports from Yangtze River Delta manufacturing bases. Industrial automation integrators exhibit highest price sensitivity, while defense primes prioritize performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from defense primes and satellite operators, with distribution running through qualified manufacturer representatives in Germany, the United States, and Japan. Beryllium copper contact interfaces and specialized high-frequency laminates draw from concentrated mining and refining operations in limited geographic zones. Single-source vulnerability persists around ITAR-cleared suppliers for military classifications. Precision engineering clusters in Munich and Stuttgart anchor European supply, with Northeast Corridor and California defense corridors supporting North American demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in modular RF rotary joint platforms where fiber optic convergence and embedded sensor integration enable premium positioning above commodity tiers. Ka-band frequency expansion and open-architecture radar unbundling shift procurement authority toward subsystem specialists with certification agility.
For Market Incumbents: Acquire waveguide manufacturing specialists and fiber optic integration capabilities to defend against modular unbundling by defense primes. ITAR clearance infrastructure represents a scarce asset that limits competitive entry; deepen this moat through parallel CE marking and FCC Part 15 pre-certification investments. Capacity addition in German precision engineering clusters preserves proximity advantages for satellite ground station and robotic welding cell demand. For New Entrants and Emerging Players: The mid-tier price-point gap between MIL-SPEC premium suppliers and standardized compact imports offers specification entry for PMDA-certified medical imaging rotary joints. Japan CT scanner OEMs present the most penetrable demand channel, with gantry rotation systems requiring millions of revolution life cycles that resist commodity substitution. A go-to-market angle anchored in electromagnetic simulation consulting services bypasses capital-intensive manufacturing qualification timelines. For Investors and Strategic Acquirers: Defense primes with platform-integrated specifications are the most active acquirer in this space, seeking to reclaim procurement authority from disintermediating subsystem suppliers. Long-term viability over a multi-year horizon rests on spectrum allocation decisions by national regulators and the trajectory of open-architecture radar standardization. The signal to monitor is unbundling velocity in NATO procurement programs, where second-source qualification cycles indicate shifting supplier power.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Channel Platform Development | Ka-band architectures displace legacy single-channel units in NATO defense procurement cycles. |
| Certification Pre-Investment | Parallel FCC Part 15 and CE marking tracks filter non-specialized competitors from European supply chains. |
| Fiber Optic Integration | Combined RF and optical channels command premium positioning in robotic automation specification bundles. |
| Precision Engineering Cluster Expansion | Munich and Stuttgart geographic density reduces logistics costs for satellite ground station integrators. |
| ITAR Clearance Infrastructure | Defense-controlled export classifications limit supplier base eligibility for military radar contracts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, satellite ground station engineers, robotic automation integrators, and medical device OEM procurement teams with secondary validation. Defense contract databases, FCC equipment authorization records, EU CE marking registries, and precision engineering trade association filings anchored supply-side characterization. Bottom-up installation base modeling and top-down addressable market triangulation cross-checked segment outputs.
Historical reference periods anchored volume and value trajectories across the projection horizon, with analytical frameworks modeling product type, industry vertical, application, and connectivity segmentation dimensions. CAGRs derived from fitted growth curves incorporating defense budget appropriation cycles, spectrum allocation decisions by national regulators, and industrial automation capital expenditure patterns. Ka-band frequency expansion rates and open-architecture radar program adoption curves served as industry-specific forecast inputs.
Caveats apply where raw material cost volatility in beryllium copper and high-frequency laminates, regulatory timeline extensions for multi-standard certification, or defense procurement program delays could materially shift the outlook. Forecasts reflect documented assumptions about NATO radar modernization velocity and telecommunications infrastructure deployment cadence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market