
 Silicon Hydride Market | 2026-2036
Silicon Hydride Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Hydride Market Analytics
Photovoltaics is rebalancing toward higher-efficiency cell architectures that consume more silane per watt. Wacker Chemie AG leverages its integrated polysilicon-to-silane production chain to secure feedstock consistency. Shin-Etsu Chemical Co., Ltd. anchors the Asia-Pacific supply base through massive chlorosilane derivative capacity. Elkem ASA competes on metallurgical-grade silicon sourcing that feeds hydride purification streams.
Silicon hydrides comprise a family of silicon-hydrogen compounds ranging from monosilane (SiH4, boiling point −112 °C) through higher homologs, produced chiefly via silane pyrolysis or magnesium silicide acid hydrolysis, serving primarily as precursor gases for chemical vapor deposition of silicon thin films. Semiconductor grade silane commands the deepest margin pools due to parts-per-billion purity requirements and handler certification barriers. Electronics end-use applications in flat-panel display manufacturing represent the fastest-expanding volume segment as OLED and microLED fabrication scales. Industrial grade product lines remain mature with pricing tethered to commodity chlorosilane benchmarks.
EPA hazardous air pollutant standards and OSHA process safety management rules govern U.S. silane storage and handling thresholds, while REACH authorization procedures in Europe restrict certain chlorosilane intermediate chemistries. China's SAMR enforces GB 19041 packaging codes for pyrophoric gas transport, and South Korea's MFDS monitors semiconductor material import quality declarations. Stakeholders must track evolving purity certifications as downstream customers consolidate approved supplier lists around single-source qualification protocols.
Market Dynamics
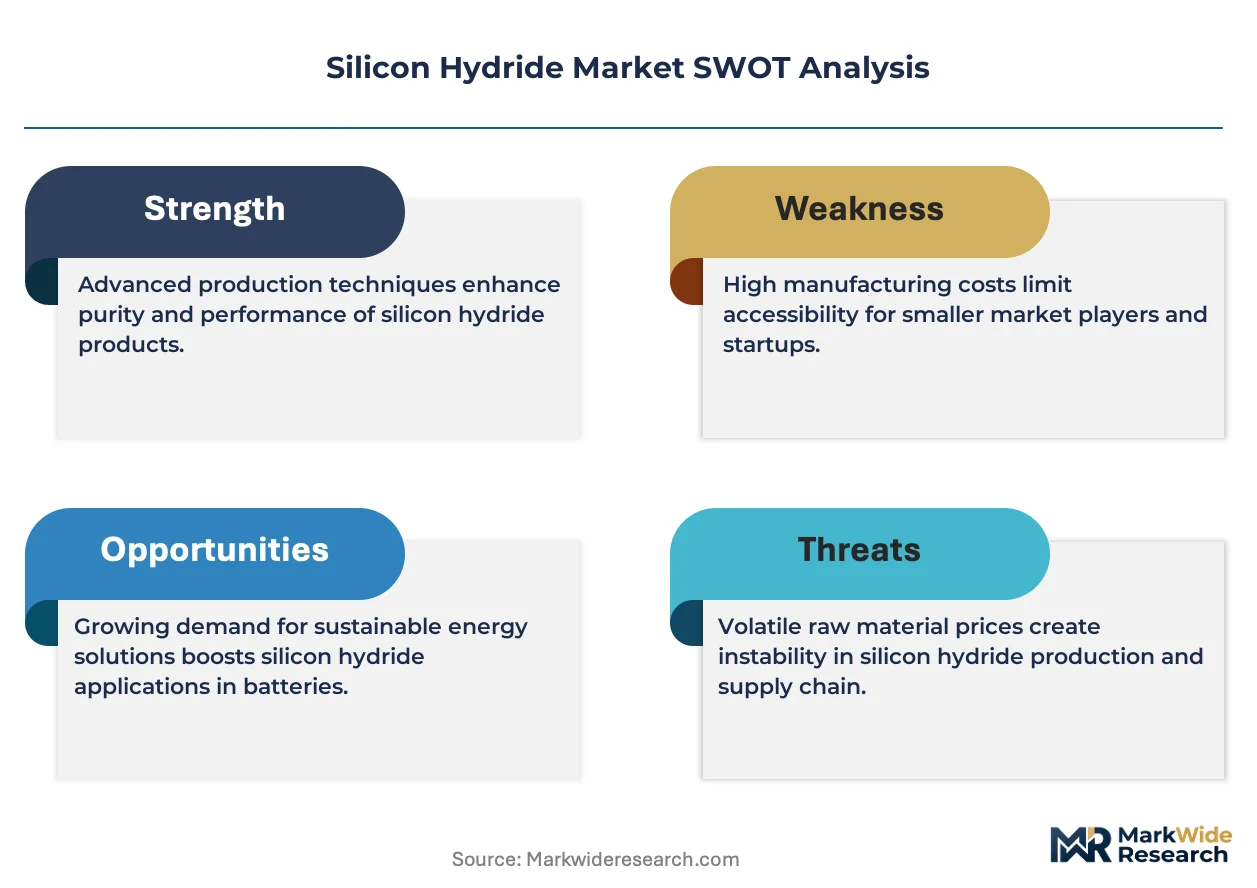
Semiconductor foundries are consolidating their silane supplier lists around single-source qualification protocols, compressing the vendor base while elevating purity certification barriers that lock out secondary producers.
Growth Catalysts
- Perovskite-silicon tandem cell commercialization:Next-generation photovoltaic architectures consume three to four times more silane per watt than conventional silicon cells, pulling volume from semiconductor-grade suppliers into solar manufacturing.
- China's dual carbon policy framework:Domestic polysilicon-to-silane capacity expansion receives preferential grid access and carbon credit allocations, accelerating captive supply buildout for photovoltaic wafer production zones.
- MicroLED display fabrication scaling:Samsung Display and LG Display are qualifying new silane sources for gallium nitride epitaxy support layers, opening a dedicated demand channel distinct from traditional LCD chemical vapor deposition.
Market Restraints
- Metallurgical-grade silicon feedstock volatility:Elkem ASA and Wacker Chemie AG face margin compression when ferrosilicon alloy demand spikes divert quartzite smelting capacity, disrupting hydride precursor supply schedules.
- East Asian manufacturing cluster concentration:Over seventy percent of semiconductor-grade silane purification capacity sits within a four-hundred-kilometer radius in South Korea's Gyeonggi Province, creating catastrophic disruption risk from seismic or geopolitical events.
- Chlorosilane intermediate substitution:Trichlorosilane remains entrenched in polysilicon production for commodity solar cells, limiting silane penetration in price-sensitive photovoltaic segments outside premium efficiency tiers.
Strategic Opportunities
- Indian photovoltaic manufacturing buildout:Production-linked incentive schemes for solar module assembly create first-mover advantage for silane distributors establishing local cylinder filling and gas management infrastructure.
- Solid-state battery silicon anode integration:Silane-derived amorphous silicon coatings promise tenfold capacity improvement over graphite, with QuantumScape and Solid Power actively qualifying precursor specifications.
- EU F-Gas Regulation phase-down:Perfluorinated greenhouse gas restrictions in semiconductor etching processes redirect capital toward silane-based atomic layer deposition alternatives for dielectric film formation.
Industry Challenges
- Parts-per-billion contamination control:Semiconductor customers now require sub-ten-ppt boron and phosphorus specifications that demand dedicated production trains and six-month qualification cycles for each new supply point.
- Pyrophoric gas logistics certification:Handler licensing under China's GB 19041 and South Korea's MFDS import declaration systems creates bottlenecks at port customs clearance, extending lead times for spot purchases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Hydride Market |
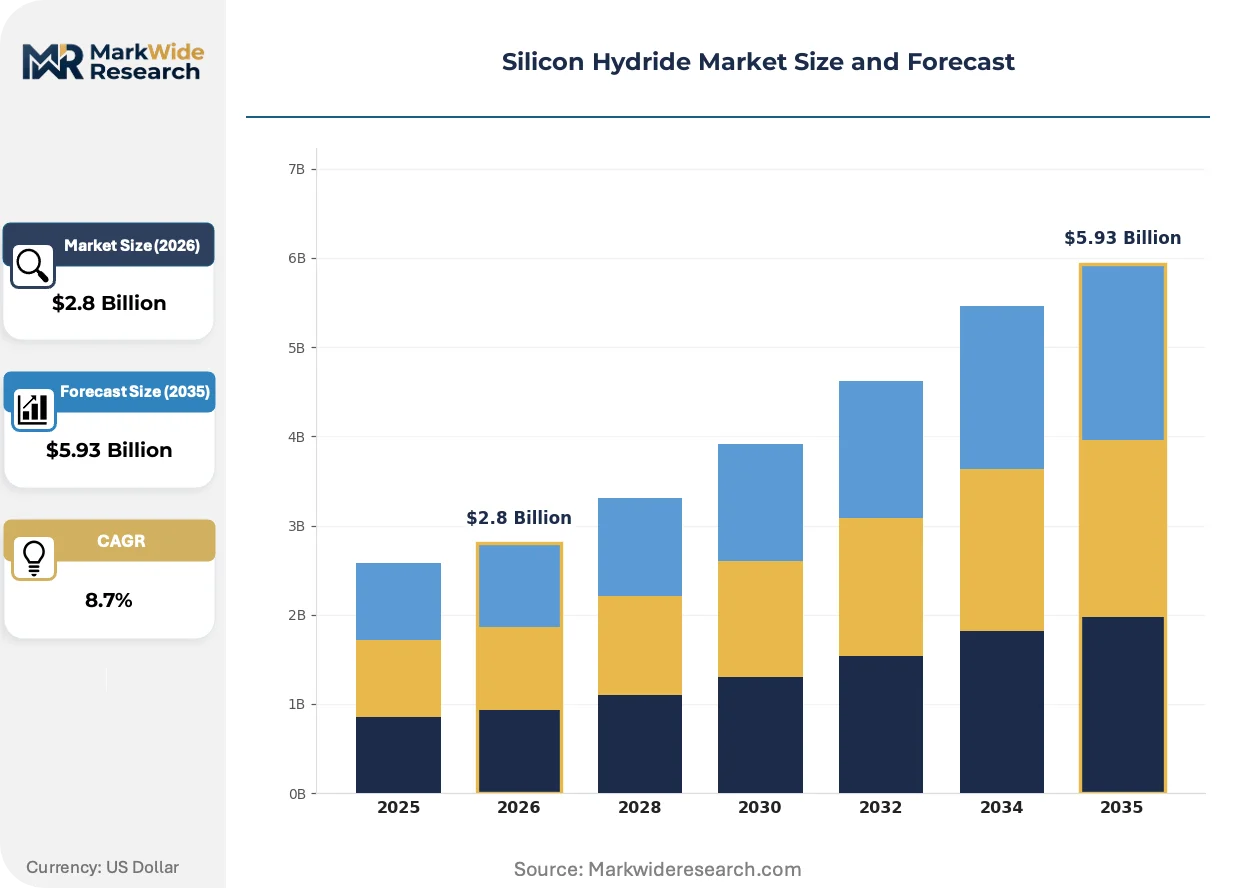
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silane, Disilane, Trisilane, Tetrasilane End Use Industry: Electronics, Photovoltaics, Automotive, Chemicals Grade: Industrial Grade, Research Grade, Semiconductor Grade, Cosmetic Grade Delivery Mode: Gas Cylinder, Liquid Tank, Bulk Supply, Microcontainer |
| Companies Covered | REC Silicon, Air Liquide, Linde, Inner Mongolia Xingyang Technology, CNS, Shin-Etsu Chemical Co., Ltd., Wacker Chemie AG, Elkem ASA, Denka Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Hydride Market Evolving Landscape
Plasma-enhanced deposition techniques are compressing film formation temperatures while tightening uniformity specifications, forcing silane suppliers to co-develop gas delivery systems with equipment manufacturers rather than selling commodity product alone.
Plasma-activated silane cracking is rewriting the economics of low-temperature polysilicon deposition for flexible electronics substrates. Display manufacturers in South Korea are adopting this approach for foldable OLED backplanes, enabling plastic substrate compatibility that thermal chemical vapor deposition cannot achieve. The technology is compressing capital requirements for new thin-film transistor lines while elevating gas purity demands.
REACH authorization procedures for chlorosilane intermediates are restricting certain process chemistries in European photovoltaic manufacturing. German and Norwegian polysilicon producers face reformulation costs or supply chain reconfiguration to maintain market access. Semiconductor material importers are responding by accelerating silane direct-sourcing to bypass chlorosilane conversion steps entirely.
Long-term take-or-pay contracting is displacing spot market purchases among tier-one semiconductor foundries. TSMC and Samsung Foundry now require five-year volume commitments with price escalation clauses tied to energy indices. This pattern concentrates procurement leverage with incumbents possessing integrated polysilicon assets while excluding traders and re-packagers from strategic supply relationships.
Silicon Hydride Market Segmentation
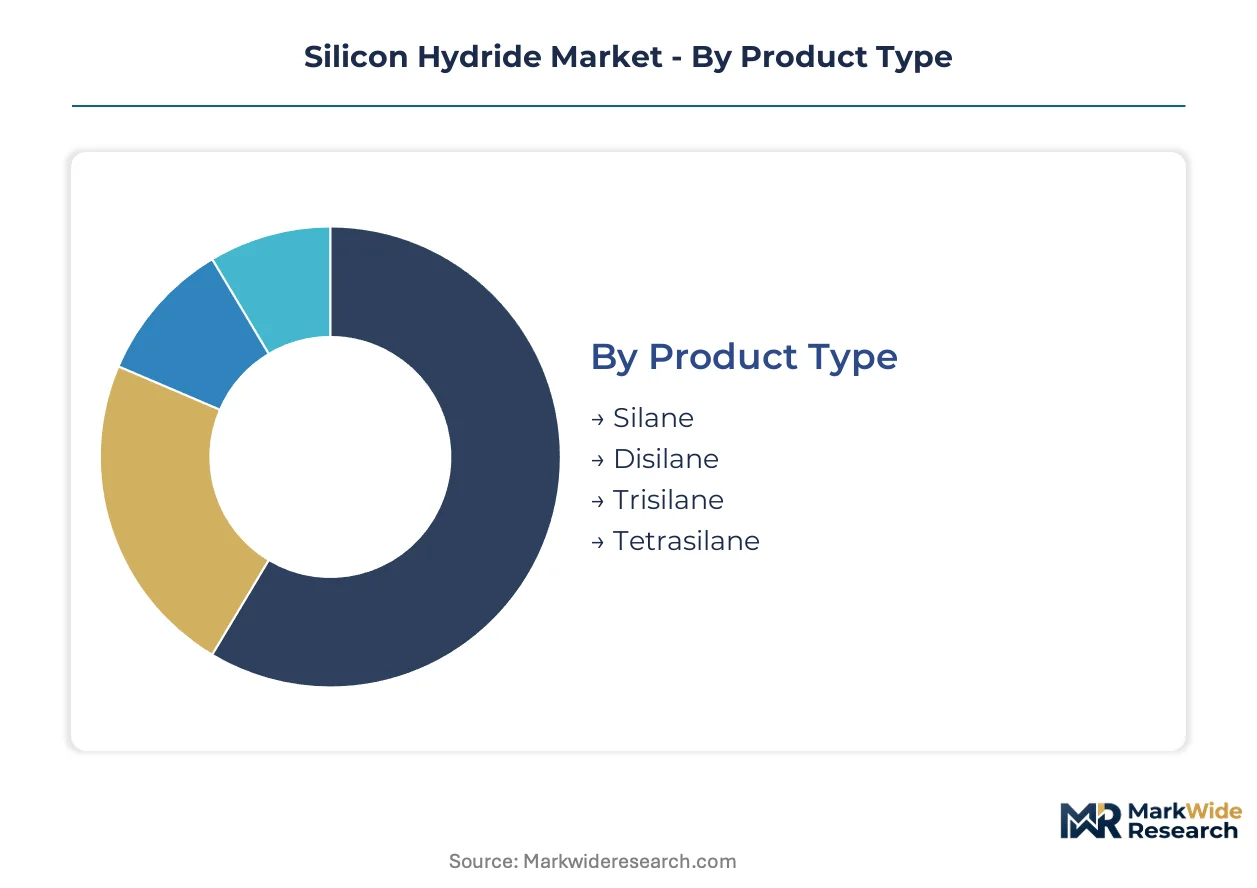
Silicon hydride procurement patterns diverge sharply across purity thresholds and delivery mechanisms. Semiconductor fabs impose single-source qualification protocols that lock in supplier relationships for years, while photovoltaic manufacturers prioritize volume scalability over certification depth.
Product Type:
Capital intensity peaks with higher-order silanes requiring dedicated pyrolysis trains and cryogenic distillation infrastructure.
- Silane:Monosilane serves as the foundational feedstock for chemical vapor deposition of amorphous and polycrystalline silicon thin films. Demand concentrates in South Korea's Gyeonggi Province foundry cluster, where Samsung Foundry and SK hynix enforce parts-per-billion purity specifications that exclude secondary producers.
- Disilane:This dimeric hydride enables low-temperature silicon epitaxy critical for flexible OLED backplanes. Plasma-activated cracking techniques at LG Display and Samsung Display facilities are expanding disilane consumption for plastic substrate compatibility.
- Trisilane:Higher homolog with specialized deposition kinetics for atomic layer deposition precursors.
- Tetrasilane:Niche product for experimental thin-film transistor architectures in research environments.
Silane absorbs the bulk of installed capacity; disilane is expanding most quickly.
End Use Industry:
Application maturity determines whether procurement prioritizes spot pricing or long-term contracting.
- Electronics:Flat-panel display manufacturing now constitutes the steepest expansion trajectory for silicon hydride consumption. MicroLED fabrication at Samsung Display and LG Display requires silane-derived gallium nitride support layers distinct from traditional LCD chemical vapor deposition chemistries.
- Photovoltaics:Perovskite-silicon tandem cell architectures consume three to four times more silane per watt than conventional silicon cells. China's photovoltaic wafer production zones in Xinjiang and Inner Mongolia are pulling semiconductor-grade supply into solar manufacturing.
- Automotive:Solid-state battery silicon anode development at QuantumScape and Solid Power is qualifying silane-derived amorphous silicon coatings.
- Chemicals:Mature segment for silane functionalization reagents and organosilane intermediates.
Electronics commands the deepest margin pools; photovoltaics is gaining share fastest.
Grade:
Certification depth creates tiered pricing structures that separate qualified suppliers from commodity competitors.
- Semiconductor Grade:Sub-ten-parts-per-trillion boron and phosphorus specifications demand dedicated production trains and six-month qualification cycles. TSMC and Samsung Foundry now require five-year take-or-pay commitments with energy-indexed price escalation clauses.
- Industrial Grade:Pricing remains tethered to commodity chlorosilane benchmarks with limited differentiation. Metallurgical-grade silicon feedstock volatility at Elkem ASA and Wacker Chemie AG disrupts hydride precursor supply schedules when ferrosilicon alloy demand spikes.
- Research Grade:Small-batch production for academic and national laboratory thin-film research.
- Cosmetic Grade:Emerging segment for silane-functionalized personal care formulations.
Semiconductor grade captures the highest absolute margins; industrial grade moves the largest absolute volumes.
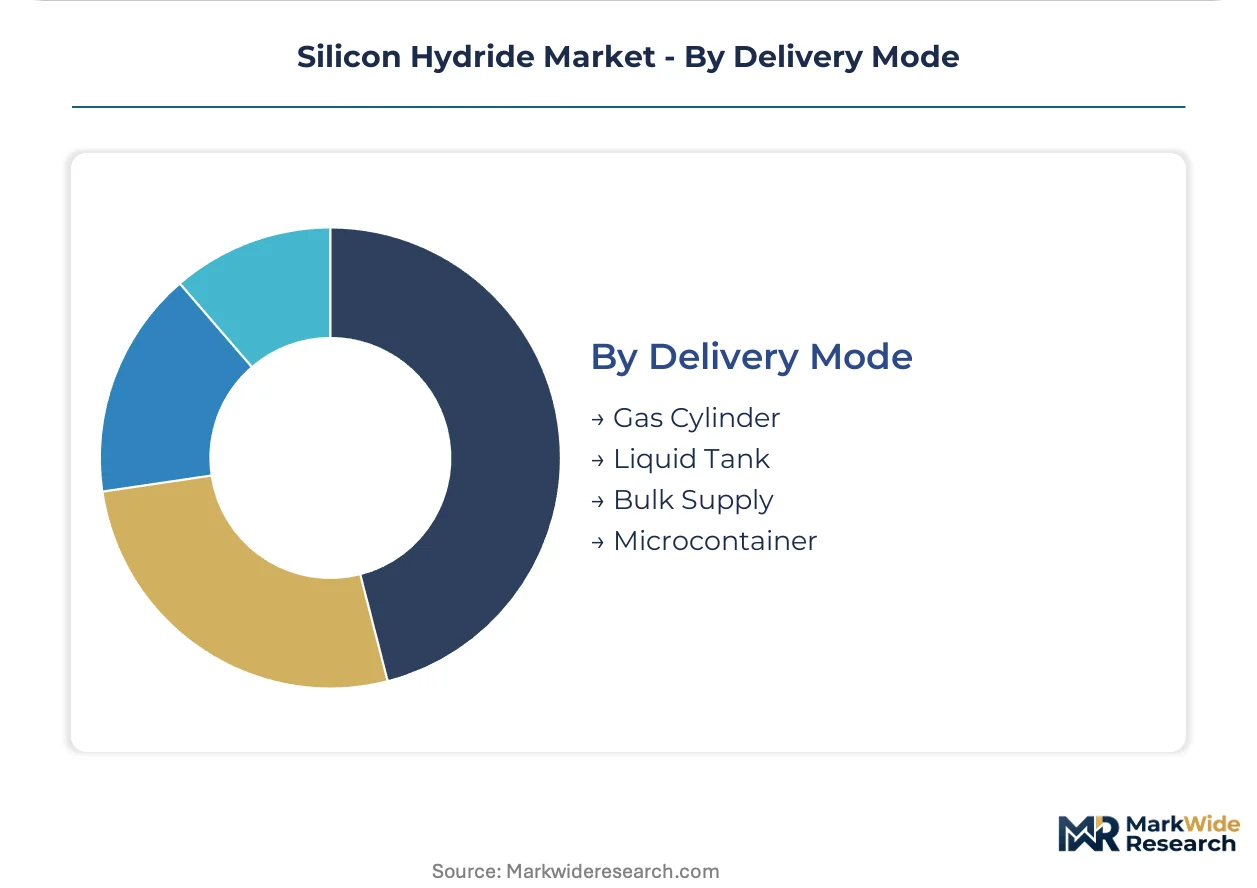
Delivery Mode:
Logistics infrastructure requirements vary with customer scale and pyrophoric handling certification.
- Gas Cylinder:Standard delivery for research facilities and mid-scale semiconductor fabs requiring frequent rotation. China's GB 19041 packaging codes and South Korea's MFDS import declarations create customs clearance bottlenecks for spot purchases.
- Bulk Supply:Pipeline delivery to integrated polysilicon-to-silane facilities. Wacker Chemie AG leverages this mode to secure feedstock consistency across its European and US production assets.
- Liquid Tank:Cryogenic storage for high-volume consumers with on-site vaporization infrastructure.
- Microcontainer:Specialized packaging for laboratory-scale research grade distribution.
Bulk supply anchors strategic relationships; gas cylinder distribution is fragmenting into regional service networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian chemical clusters while consumption spreads across semiconductor foundries and photovoltaic assembly zones. This geographic split shapes logistics networks and purity certification requirements.
China
Domestic polysilicon-to-silane capacity expansion accelerates under the dual carbon policy framework with preferential grid access for Xinjiang and Inner Mongolia production zones. SAMR enforces GB 19041 packaging codes for pyrophoric gas transport, tightening handler certification requirements. Photovoltaic wafer manufacturing in the Inner Mongolia corridor pulls semiconductor-grade supply into solar applications.
South Korea
Samsung Foundry and SK hynix in Gyeonggi Province enforce parts-per-billion purity specifications that exclude secondary producers from qualification. MFDS monitors semiconductor material import quality declarations, extending customs clearance timelines for spot purchases. Over seventy percent of regional purification capacity sits within a four-hundred-kilometer radius, concentrating catastrophic disruption risk.
United States
EPA hazardous air pollutant standards and OSHA process safety management rules govern silane storage thresholds at semiconductor fabrication facilities. Integrated polysilicon-to-silane producers leverage pipeline delivery infrastructure across Texas and Arizona manufacturing corridors. Solid-state battery developers in California and Colorado are qualifying silane-derived silicon anode precursors.
Germany
REACH authorization procedures restrict certain chlorosilane intermediate chemistries, forcing reformulation costs for polysilicon producers. Wacker Chemie AG anchors European supply through integrated production chains spanning Burghausen and Nünchritz sites. The EU F-Gas Regulation phase-down redirects capital toward silane-based atomic layer deposition alternatives for dielectric film formation.
Japan
METI industrial policy supports domestic semiconductor material supply chain resilience amid East Asian concentration risks. Display manufacturers in the Chubu region adopt plasma-activated silane cracking for flexible OLED backplane production. Shin-Etsu Chemical Co., Ltd. maintains chlorosilane derivative capacity serving both domestic and export markets.
Silicon Hydride Market Competitive Landscape
Top-tier vendors anchor integrated polysilicon-to-silane production, while regional gas distributors and re-packagers occupy secondary positions with limited qualification access. The vendor base compresses around single-source protocols at major semiconductor foundries, elevating barriers for new entrants. Three archetypes dominate: integrated chemical conglomerates with upstream silicon assets, industrial gas specialists with cylinder logistics networks, and regional chlorosilane converters. Competitive moves center on five-year take-or-pay contracting with energy-indexed escalation clauses and captive capacity expansion in photovoltaic manufacturing zones.
Among integrated chemical producers, Wacker Chemie AG and Shin-Etsu Chemical Co., Ltd. represent the archetype of backward-controlled supply chains securing feedstock consistency across multiple continents. Elkem ASA occupies a position tied to metallurgical-grade silicon sourcing that feeds hydride purification streams. These three exemplify how upstream asset control separates qualified suppliers from commodity competitors in procurement decisions at TSMC and Samsung Foundry.
| Leading Market Players |
|---|
| REC Silicon |
| Air Liquide |
| Linde |
| Inner Mongolia Xingyang Technology |
| CNS |
| Shin-Etsu Chemical Co., Ltd. |
| Wacker Chemie AG |
| Elkem ASA |
| Denka Company Limited |
| Others |
Value Network & Pricing Analysis
Captive polysilicon-to-silane integration anchors both supply security and pricing power for qualified suppliers serving semiconductor foundries. This backward-controlled structure locks in feedstock consistency while excluding secondary producers from margin-rich procurement relationships at TSMC and Samsung Foundry.
Pricing Analysis
Short lead-time premiums dominate spot market transactions where China's GB 19041 handler certification bottlenecks compress availability. Semiconductor-grade silane commands five-year take-or-pay contracts with energy-indexed escalation clauses, while industrial-grade product tracks commodity chlorosilane benchmarks. Price differentiation hinges on parts-per-billion purity certification and dedicated production train access. Cost compression in photovoltaic-grade supply intensifies as China's captive capacity expansion floods lower-tier segments. Photovoltaic manufacturers exhibit highest price sensitivity; semiconductor fabs prioritize qualification depth over unit cost.
Supply Chain Analysis
Dual-sourcing requirements at tier-one foundries mandate multi-supplier qualification despite geographic concentration risks. Purification capacity clusters in South Korea, China, and Germany, with over seventy percent of semiconductor-grade output sitting within Gyeonggi Province. Raw material flows draw from metallurgical-grade silicon smelters, magnesium silicide processors, and chlorosilane conversion facilities. Single-source vulnerability escalates from seismic exposure in the Korean foundry belt. Distribution runs through pipeline delivery at integrated producers and regional cylinder-filling networks for spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization procedures and China's evolving GB standards erect compliance moats that reward incumbent investment in certification infrastructure while filtering out undercapitalized entrants.
For Market Incumbents: Deploy five-year take-or-pay contracting to lock in procurement relationships before captive Chinese capacity matures. Expand cylinder-filling infrastructure in India's production-linked incentive corridors to preempt emerging photovoltaic demand. Chlorosilane intermediate substitution in commodity solar cells threatens margin pools; counter by deepening gallium nitride epitaxy qualifications at display manufacturers. Certification investment in sub-ten-ppt boron and phosphorus specifications separates qualified suppliers from commodity competitors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in semiconductor-grade silane creates white-space opportunity for industrial-grade specialists with purification upgrade pathways. Target India's solar module assembly zones where production-linked incentives attract first-mover gas management infrastructure. Solid-state battery silicon anode development at QuantumScape and Solid Power offers penetrable entry point with lower certification barriers than foundry supply. Pursue joint qualification programs with equipment manufacturers co-developing plasma-enhanced deposition systems. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated chemical conglomerates possessing upstream silicon assets and multi-continent production footprints. Long-term viability favors producers with captive polysilicon supply and established MFDS or SAMR import declaration systems. Acquisition target archetype: regional chlorosilane converters with upgradeable purification trains and existing handler licensing. Watch perovskite-silicon tandem cell commercialization as inflection signal pulling semiconductor-grade volume into solar manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Assets | Wacker Chemie AG secures feedstock consistency across Burghausen and Nünchritz production sites. |
| Long-term Supply Agreement with Foundries | TSMC and Samsung Foundry now require five-year take-or-pay commitments with energy-indexed escalation clauses. |
| Capacity Expansion in Photovoltaic Zones | China's dual carbon policy framework accelerates captive supply buildout for Xinjiang and Inner Mongolia wafer production. |
| Joint Venture for Plasma-Enhanced Systems | Display manufacturers in South Korea co-develop gas delivery infrastructure for flexible OLED backplane production. |
| Green Manufacturing Transition | EU F-Gas Regulation phase-down redirects capital toward silane-based atomic layer deposition alternatives. |
Research Methodology
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone for volume and value estimation. Primary interviews with plant managers at polysilicon facilities, procurement leads at semiconductor foundries, distribution channel partners, and technical R&D directors at deposition equipment manufacturers validated supply-side assumptions. Bottom-up and top-down triangulation reconciled production capacity data with end-use consumption patterns across electronics, photovoltaics, and emerging battery applications.
Bottom-up modeling tracked silane, disilane, and higher-order hydride volumes by grade tier, end-use industry, and delivery mode across the projection horizon. Top-down cross-checks applied energy-indexed cost structures to derive margin-consistent price points. Segmentation dimensions included purity certification level, regional production hub concentration, and customer qualification depth. CAGRs emerged from installed capacity expansion schedules and per-watt consumption coefficients for tandem cell and microLED architectures.
Inputs from SAMR regulatory filings and MFDS import declaration systems were available through the study window; gaps in real-time spot pricing data introduce uncertainty bands around short-term volatility assumptions. Deviation in perovskite-silicon tandem cell yield rates or seismic disruption in Gyeonggi Province would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Cadmium Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Liquid Film Photoresist Market