
 Oral Solid Dosage Pharmaceutical Formulation Market | 2026-2036
Oral Solid Dosage Pharmaceutical Formulation Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Solid Dosage Pharmaceutical Formulation Market Intelligence
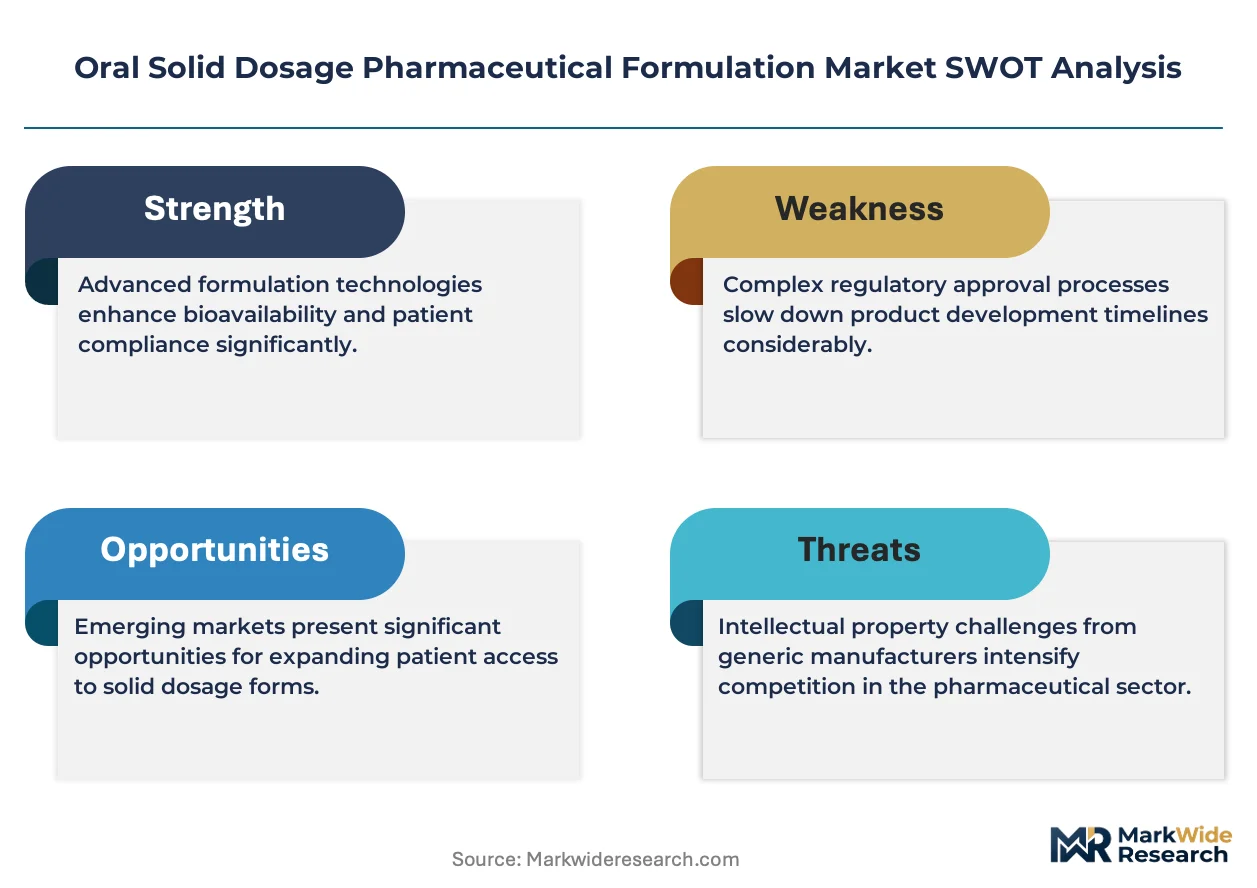
Good Manufacturing Practice (GMP) certification, as enforced by regulators like the US FDA and the EMA, is unwinding previous assumptions about process validation for excipient sourcing. This regulatory pressure creates advantages for companies with robust quality management systems. Pfizer leverages its extensive manufacturing network to ensure consistent compliance across its global supply chains. Novartis, in contrast, differentiates through its investment in novel formulation technologies for complex active pharmaceutical ingredients (APIs).
Oral solid dosage pharmaceutical formulation is the process of converting active pharmaceutical ingredients (APIs) and excipients into a stable, administrable solid unit. These formulations, created through methods like direct compression or wet granulation, are designed for controlled drug release and patient convenience. Tablets represent the largest and most mature product type, valued for cost-effective manufacturing at scale. Formulations for the central nervous system therapy area are growing, often utilizing specialized capsules to manage bioavailability and protect sensitive compounds.
Regulatory frameworks from the US FDA, Europe's EMA, and China's NMPA establish stringent requirements for drug product approval and manufacturing. The International Council for Harmonisation (ICH) guidelines further standardize quality and safety expectations, directly influencing formulation strategies and raw material selection. Consequently, drug developers must continually balance the pursuit of innovative delivery mechanisms, like multi-layer tablets, against the established cost efficiencies of conventional formulations.
Market Dynamics
The central force shaping the market is the harmonization of global regulatory standards. Guidelines from the International Council for Harmonisation (ICH), enforced by bodies like the US FDA and EMA, create a uniform quality expectation that elevates compliance costs but simplifies multi-market access.
Growth Catalysts
- Continuous Manufacturing:This technology streamlines production by integrating steps like blending, granulation, and compression, reducing batch failures and accelerating time-to-market for high-volume drugs like cardiovascular therapies.
- Chronic Disease Prevalence:A rising global incidence of chronic conditions, particularly central nervous system disorders and metabolic diseases, fuels sustained demand for daily, long-term oral medication regimens.
- Contract Manufacturing in India:Government support through policies like the Production Linked Incentive (PLI) scheme enhances India's position as a hub for cost-effective contract development and manufacturing, attracting international pharmaceutical partners.
Market Restraints
- API Complexity:The increasing use of complex and poorly soluble active pharmaceutical ingredients (APIs), particularly in oncology, presents significant formulation challenges that drive up R&D costs and timelines.
- Regulatory Scrutiny:Stringent requirements for demonstrating bioequivalence and stability, enforced by regulators like the US FDA and Europe's EMA, can lead to lengthy and expensive approval cycles for new formulations.
- Excipient Price Volatility:The supply of specialized, high-purity excipients is concentrated among a few suppliers, making formulators vulnerable to price fluctuations and supply chain disruptions for critical ingredients.
Strategic Opportunities
- Fixed-Dose Combinations:Developing single-tablet formulations that combine multiple APIs offers a clear path to improve patient adherence and create patent-protected products, especially in cardiovascular and infectious disease treatment.
- Personalized Medicine:The emergence of 3D printing technology creates an opportunity for on-demand manufacturing of tablets with patient-specific dosages, a valuable proposition for pediatric and geriatric care.
- Expansion in Latin America:Growing healthcare expenditure and regulatory modernization in countries like Brazil and Mexico present new market entry opportunities for established oral solid dosage products.
Industry Challenges
- Global Supply Chain Integrity:Ensuring consistent quality and traceability of raw materials sourced from numerous global suppliers is a major operational challenge, demanding robust qualification programs to meet GMP standards.
- Intellectual Property Navigation:The dense patent landscape around novel drug delivery systems, such as controlled-release coatings and multi-layer tablets, requires sophisticated legal and technical strategies to avoid infringement.
- Formulation Talent Scarcity:A shortage of scientists with expertise in advanced techniques like hot-melt extrusion and amorphous solid dispersions hinders the development of formulations for next-generation complex molecules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Solid Dosage Pharmaceutical Formulation Market |
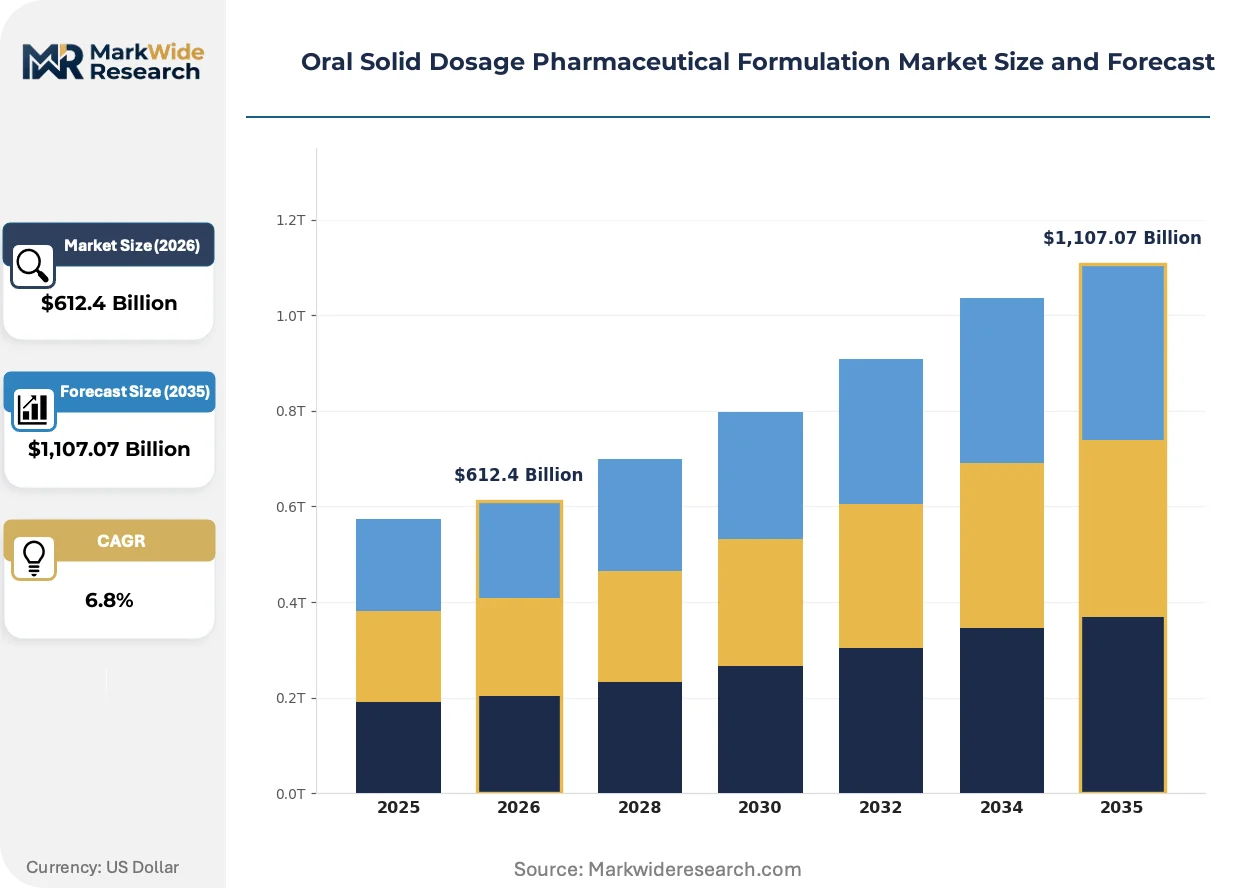
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
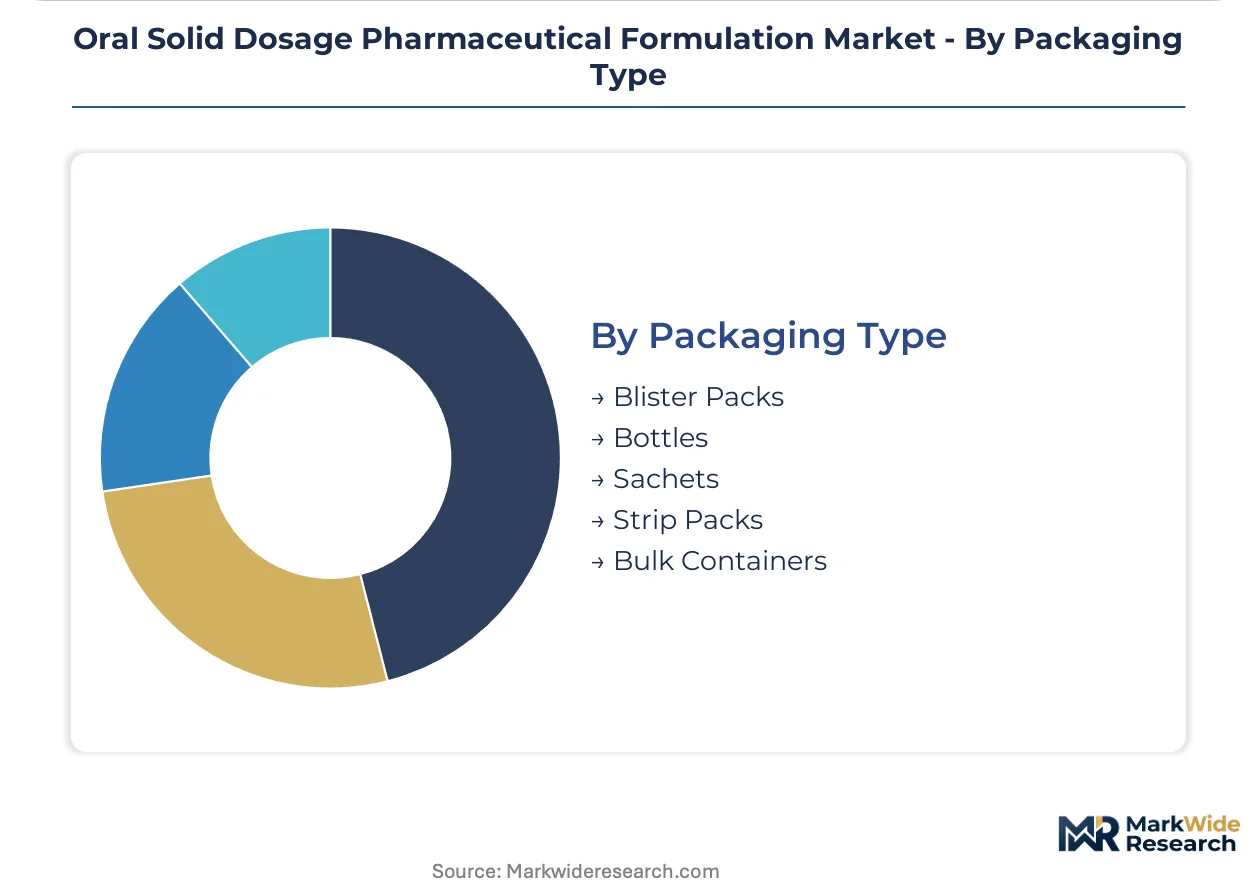
| Segmentation | Product Type: Tablets, Capsules, Powders, Granules, Pellets Therapy Area: Cardiovascular, Central Nervous System, Respiratory, Gastrointestinal, Dermatology End User: Hospitals, Retail Pharmacies, Clinics, Home Healthcare Providers, Online Pharmacies Packaging Type: Blister Packs, Bottles, Sachets, Strip Packs, Bulk Containers |
| Companies Covered | Pfizer, Novartis, Roche, Eli Lilly and Company, Merck & Co., AstraZeneca, GSK, Bristol-Myers Squibb, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Solid Dosage Pharmaceutical Formulation Market Strategic Shifts & Innovations
Balancing the pursuit of novel drug delivery mechanisms against the cost pressures of large-scale production defines current innovation. The primary focus is on technologies that enhance bioavailability and patient compliance while adhering to increasingly strict international quality standards.
Continuous manufacturing (CM) integrates disparate production stages into a single, automated flow. Major pharmaceutical producers are adopting CM for high-volume drugs to enhance process control and reduce waste. This integrated methodology is displacing traditional batch manufacturing, which is prone to longer production cycles and greater variability between batches.
Regulatory convergence under frameworks like the ICH Q12 guidelines is changing lifecycle management. This guidance provides a pathway for managing post-approval chemistry, manufacturing, and controls (CMC) changes more efficiently. Contract manufacturing organizations are most impacted, as they must upgrade quality systems to offer the flexibility that ICH Q12 enables for their clients.
A pronounced shift toward patient-centric design prioritizes attributes like ease of swallowing, taste-masking, and simplified dosing schedules. This focus disrupts the conventional, cost-first approach to formulation, particularly in specialty areas like pediatrics and geriatrics. The trend is highly visible in the development of orally disintegrating tablets (ODTs) and abuse-deterrent formulations for pain management.
Oral Solid Dosage Pharmaceutical Formulation Market Segmentation

Segmentation for oral solid dosage formulations highlights diverse product needs and patient groups. Understanding these distinct segments allows formulators to tailor drug delivery systems for optimal therapeutic outcomes. This granular view guides strategic investments in manufacturing capabilities and specialized excipients.
Product Type:
Domestic demand for oral solid dosage forms often favors established formats, while export markets increasingly seek innovative product types.
- Tablets:Tablets are compressed solid forms containing active pharmaceutical ingredients and excipients, designed for precise dosing and stability. Demand concentrates in India for cost-effective mass production, driven by its large patient population and contract manufacturing capabilities.
- Capsules:Capsules encapsulate APIs within a soluble shell, offering taste-masking and controlled release for sensitive compounds. Global demand for capsules is expanding in central nervous system therapies, where specialized formulations protect delicate APIs and enhance bioavailability.
- Powders:Powders provide flexible dosing for pediatric and geriatric patients, allowing for reconstitution or direct administration.
- Granules:Granules facilitate improved flowability and compressibility, serving as an intermediate for tablet manufacturing or direct oral administration.
- Pellets:Pellets enable multi-particulate drug delivery systems, offering sustained release and reduced dose dumping for various therapeutic areas.
Tablets command the established base. The steepest expansion runs through Capsules.
Therapy Area:
Formulation complexity varies significantly across different therapy areas, reflecting distinct patient needs and disease characteristics.
- Cardiovascular:Cardiovascular formulations target heart and blood vessel conditions, often requiring sustained release and fixed-dose combinations for chronic management. Demand is strong globally due to the high prevalence of chronic heart diseases, driving the need for convenient daily oral medications.
- Central Nervous System:Central Nervous System formulations address neurological and psychiatric disorders, frequently utilizing specialized capsules to overcome blood-brain barrier challenges. Investment in novel formulations is high due to the complexity of APIs and the need for enhanced bioavailability in this therapy area.
- Respiratory:Respiratory formulations manage conditions like asthma and COPD, often requiring precise dosing and patient-friendly oral options.
- Gastrointestinal:Gastrointestinal drugs treat digestive disorders, benefiting from targeted release formulations that protect APIs from stomach acid.
- Dermatology:Dermatology oral formulations complement topical treatments for systemic skin conditions, focusing on patient adherence and bioavailability.
Cardiovascular therapies generate substantial volume demand. Central Nervous System therapies drive innovation in complex API delivery.
End User:
The distribution channels for oral solid dosage forms reflect diverse patient access points and healthcare delivery models.
- Hospitals:Hospitals procure oral solid dosage formulations for inpatient treatment and discharge prescriptions, demanding high quality and consistent supply. Regulatory scrutiny on drug procurement and administration is particularly stringent within hospital settings, influencing supplier selection.
- Retail Pharmacies:Retail pharmacies serve as primary dispensing points for oral solid dosage forms, catering to a wide range of chronic and acute patient needs. This channel benefits from high patient footfall and convenience, particularly for long-term medication regimens across various geographies.
- Clinics:Clinics provide outpatient care and dispense oral medications, often focusing on specific therapy areas or patient demographics.
- Home Healthcare Providers:Home healthcare providers administer and manage medications for patients in their residences, requiring user-friendly and stable formulations.
- Online Pharmacies:Online pharmacies represent a rapidly expanding channel, offering convenience and broader access to oral solid dosage medications for consumers.
Retail Pharmacies and Hospitals account for the largest volume. Online Pharmacies are expanding most quickly.
Packaging Type:
Packaging choices for oral solid dosage forms are critical for drug stability, patient compliance, and supply chain integrity.
- Blister Packs:Blister packs offer individual dose protection, enhance patient adherence through calendarization, and prevent contamination. Their adoption is widespread across Europe and North America, driven by regulatory emphasis on child resistance and tamper evidence.
- Bottles:Bottles are cost-effective for high-volume oral solid dosage forms, providing protection against moisture and light for bulk distribution. This packaging type remains prevalent in markets like the US, where large prescription volumes and multi-dose requirements are common.
- Sachets:Sachets provide single-dose convenience for powders or granules, particularly useful for pediatric or dysphagic patients.
- Strip Packs:Strip packs offer an economical alternative to blisters, providing basic protection for individual doses in developing markets.
- Bulk Containers:Bulk containers are used for shipping large quantities of un-packaged tablets or capsules to contract manufacturers for final packaging.
Blister Packs and Bottles are the most prevalent packaging types. Sachets and Strip Packs serve important niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government support through policies like India's Production Linked Incentive (PLI) scheme enhances local manufacturing capabilities, influencing global oral solid dosage formulation supply chains. Regulatory bodies worldwide are harmonizing standards, simplifying multi-market access for compliant drug products. This global alignment encourages pharmaceutical companies to optimize production and distribution strategies across key regions.
United States
Demand for complex oral solid dosage forms grows due to chronic disease prevalence, especially in oncology. The US FDA's stringent bioequivalence requirements drive formulation innovation and quality control. Pharmaceutical research hubs in Boston and San Francisco attract significant investment.
Germany
Europe's aging population sustains demand for convenient daily oral medications, particularly for cardiovascular conditions. The EMA's robust regulatory framework ensures high standards for manufacturing and product approval. Bavaria and North Rhine-Westphalia serve as key centers for pharmaceutical R&D.
India
India's large domestic patient pool and strong contract manufacturing capabilities underpin its oral solid dosage market expansion. The CDSCO oversees drug product quality and manufacturing practices. Production clusters in Gujarat and Telangana are rapidly expanding for cost-effective generic and branded formulations.
China
The vast patient base in China, coupled with healthcare reforms, drives substantial demand for oral solid dosage medications. China's NMPA has intensified regulatory oversight, pushing for higher quality standards. Major pharmaceutical centers in the Yangtze River Delta focus on both domestic supply and export-oriented production.
Brazil
Growing healthcare expenditure and an expanding middle class in Brazil contribute to increased demand for oral solid dosage forms. ANVISA, the national health surveillance agency, regulates drug registration and manufacturing processes. São Paulo and Rio de Janeiro host significant pharmaceutical manufacturing operations for the Latin American market.
Oral Solid Dosage Pharmaceutical Formulation Market Key Industry Players
Listed leaders compete with private specialists across the oral solid dosage formulation value chain. The market structure exhibits a tiered consolidation, with large pharmaceutical corporations dominating high-volume and complex API formulations. Strategic archetypes include global pharmaceutical giants, specialized contract development and manufacturing organizations (CDMOs), and regional generic manufacturers. Geographic expansion and portfolio diversification represent dominant competitive moves for many market participants.
Within the global pharmaceutical giant archetype, Pfizer and Novartis exemplify companies with extensive manufacturing networks and diverse product portfolios. Pfizer leverages its established global supply chains to ensure consistent compliance and broad market access for its solid oral dosage forms. Novartis, a Swiss-based pharmaceutical corporation, differentiates through its significant investment in novel formulation technologies for complex active pharmaceutical ingredients. AstraZeneca, a UK-Swedish multinational, also occupies a position among these large players, focusing on therapeutic areas such as cardiovascular and oncology, which rely heavily on advanced oral solid dosage delivery.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Roche |
| Eli Lilly and Company |
| Merck & Co. |
| AstraZeneca |
| GSK |
| Bristol-Myers Squibb |
| AbbVie |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing scale in oral solid dosage production drives supply concentration and establishes competitive price floors for generic formulations. This scale also influences the cost structures for specialized excipients and active pharmaceutical ingredients (APIs).
Pricing Analysis
Certification level (US FDA, EMA GMP) creates the primary spread in oral solid dosage pricing. Transactional per-unit pricing dominates, influenced by batch size, API complexity, and formulation technology. Pricing pressure stems from generic competition and increasing raw material costs, particularly for specialized excipients. Retail pharmacies and hospitals prioritize cost-effectiveness for established products, making them highly price-sensitive, while specialized clinics seeking novel formulations exhibit lower sensitivity.
Supply Chain Analysis
Container availability and port congestion impact inbound logistics costs for specialized excipients and complex active pharmaceutical ingredients. Supply concentration for APIs primarily resides in India and China, with some high-value production in the United States. The oral solid dosage market depends on a consistent supply of high-purity excipients and specialized APIs. Single-source vulnerability for certain advanced excipients presents a structural risk. Distribution runs through a dual model of retail pharmacies for chronic care and hospitals for acute treatment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral solid dosage pharmaceutical formulation is at a platform-economics inflection, driven by the interoperability of continuous manufacturing systems with digital quality management ecosystems.
For Market Incumbents: Secure long-term contracts with key excipient suppliers to mitigate price volatility and supply chain disruptions. Diversify manufacturing footprints across regions like India and Europe to enhance resilience against geopolitical threats. Invest in advanced process analytical technologies for continuous manufacturing to maintain a competitive edge over emerging contract development and manufacturing organizations.
For New Entrants and Emerging Players: Expedited regulatory pathways for orphan drugs or pediatric formulations present a certification fast-track for new entrants. Target underpenetrated therapeutic areas, such as rare central nervous system disorders, with specialized capsule formulations. A value-based pricing model, emphasizing patient outcomes, offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Specialized contract development and manufacturing organizations (CDMOs) with expertise in complex API formulation represent an attractive acquisition target archetype. Long-term viability hinges on capabilities in continuous manufacturing and patient-centric drug design. The increasing number of US FDA approvals for novel oral solid dosage forms is a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Increases production capacity for high-demand oral solid dosage forms, supporting global market penetration. |
| Regulatory Approval Pathway | Accelerates market access for innovative formulations by navigating complex US FDA and EMA requirements. |
| Pipeline Diversification | Expands product offerings into new therapy areas, reducing reliance on single-product revenue streams. |
| Strategic Partnership | Leverages specialized expertise from CDMOs for complex API formulation and advanced delivery systems. |
| Green Manufacturing Transition | Enhances operational efficiency and meets evolving sustainability standards from European regulators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with robust secondary validation to inform the analysis. Interviews included drug development executives, regulatory affairs leads, hospital procurement managers, and contract manufacturing specialists. Secondary data sources encompassed US FDA filings, EMA submissions, ClinicalTrials.gov, and industry reports, enabling bottom-up and top-down triangulation.
The market forecast, developed across the analysis window, segments by product type, therapy area, end-user, and packaging type. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key forecast inputs included chronic disease prevalence rates and continuous manufacturing adoption trends for high-volume cardiovascular therapies.
Underlying assumptions cover stable regulatory environments and sustained pharmaceutical R&D investment, with deviation risk concentrated in unforeseen geopolitical events or rapid technological obsolescence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
OX40 Receptor Agonist Market