
 OX40 Receptor Agonist Market | 2026-2036
OX40 Receptor Agonist Market Size, Share, and Industry Trends Forecast 2026-2036
OX40 Receptor Agonist Market Analytics
Multi-source biologics sourcing is expanding across the OX40 receptor agonist landscape as developers diversify CDMO partnerships to mitigate supply risk for complex protein manufacturing. Bristol Myers Squibb leverages its cell therapy infrastructure to anchor large-scale GMP production of monoclonal antibody candidates. Merck sustains competitive pressure through vertical control over key upstream bioreactor capacity. Roche specializes in companion diagnostic integration, positioning its OX40 programs within biomarker-selected patient populations.
An OX40 receptor agonist is a biologic or small molecule that binds the tumor necrosis factor receptor superfamily member 4 (TNFRSF4/CD134) on activated T cells, delivering co-stimulatory signals that amplify effector function, cytokine production, and memory formation; these agents typically require mammalian cell culture expression systems and sub-nanomolar binding affinity to achieve therapeutic efficacy. The primary commercial purpose centers on reversing T-cell exhaustion in solid tumor microenvironments and restoring self-tolerance in autoimmune pathologies. Monoclonal antibodies command the dominant share of current development pipelines due to proven manufacturability and established regulatory familiarity, while small molecules attract investment for oral bioavailability and blood-brain barrier penetration in neuro-oncology indications. Intravenous delivery maintains clinical precedence in hospitalized oncology settings, though subcutaneous formulations are gaining traction in outpatient autoimmune protocols where patient convenience drives protocol adherence.
FDA breakthrough therapy designation and EMA PRIME eligibility are accelerating OX40 agonist development timelines by enabling rolling review and intensive regulatory dialogue before pivotal trial completion. ISO 14644 cleanroom standards and ICH Q5D guidelines on cell substrate qualification govern the manufacturing infrastructure investments required for commercial supply. The EU AI Act's risk classification framework for clinical decision support tools will shape how developers deploy machine learning algorithms for patient stratification in OX40 combination trials. Stakeholders must monitor evolving FDA guidance on dual immunotherapy combinations as agency expectations for safety database size and follow-up duration continue to tighten.
Market Dynamics
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing clinical trial timelines for OX40 agonists, while manufacturing capacity constraints at mammalian cell culture facilities create supply-side friction for monoclonal antibody candidates.
Growth Catalysts
- FDA Accelerated Approval Pathway:Rolling review mechanisms enable earlier commercial entry for breakthrough immunotherapies, reducing time-to-market for OX40 agonists demonstrating substantial improvement over available therapies.
- Autoimmune Protocol Expansion:Outpatient administration of subcutaneous formulations is driving protocol adherence in rheumatology and dermatology departments seeking alternatives to intravenous biologics.
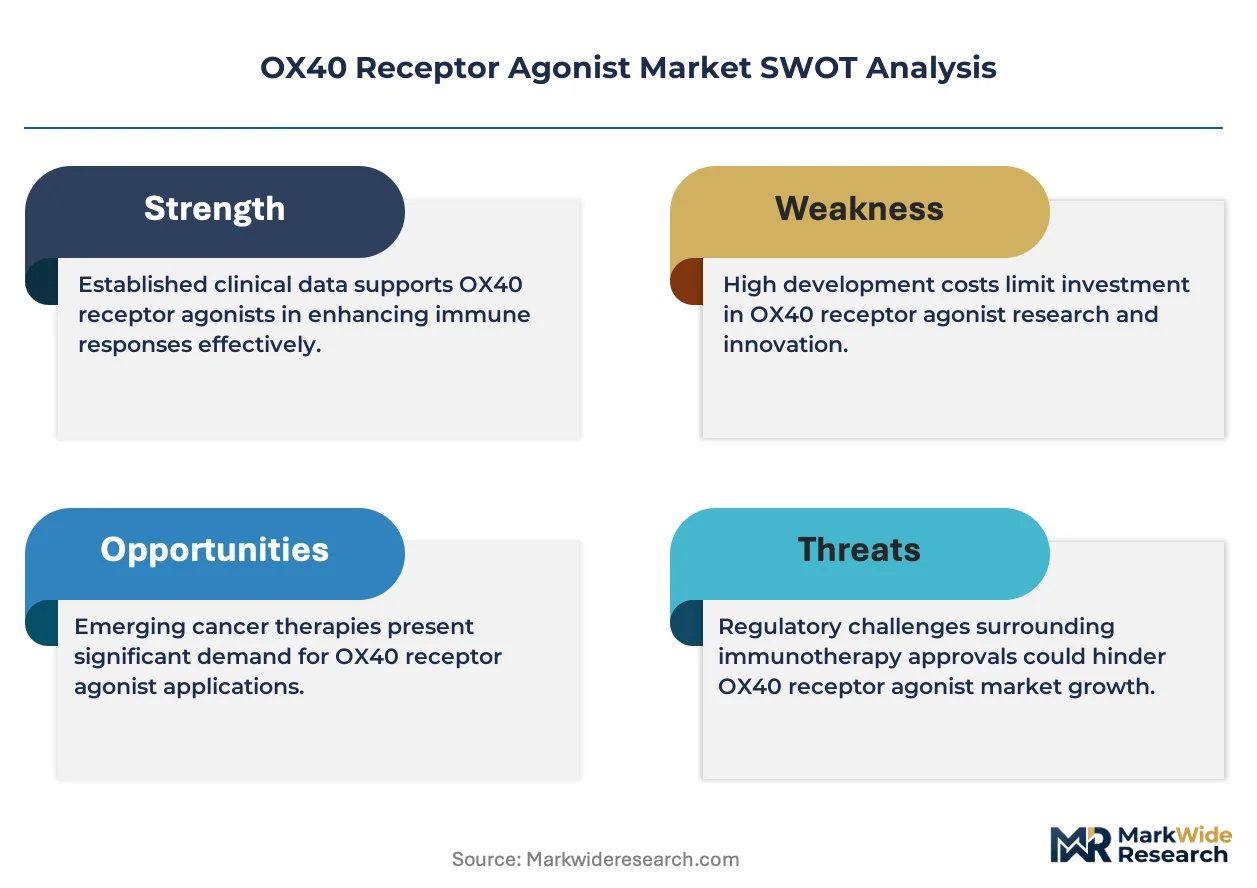
- Companion Diagnostic Integration:Biomarker-selected patient stratification is improving response rates in solid tumor trials, attracting payer support for precision immunotherapy approaches.
Market Restraints
- Bioreactor Capacity Concentration:Limited large-scale mammalian cell culture infrastructure in the United States and Europe creates bottlenecks for GMP production of complex glycoproteins.
- Dual Immunotherapy Safety Database Requirements:FDA tightening of follow-up duration expectations for combination trials extends development timelines and inflates clinical program costs.
- Substitution by PD-1/PD-L1 Inhibitors:Established checkpoint blockade therapies dominate first-line oncology protocols, limiting initial patient access for novel co-stimulatory agents.
Strategic Opportunities
- Neuro-oncology Blood-Brain Barrier Penetration:Small molecule OX40 agonists with oral bioavailability address unmet need in glioblastoma and brain metastases where large proteins fail to penetrate.
- EU AI Act Clinical Decision Support:Machine learning algorithms for patient stratification in combination trials gain regulatory clarity under risk classification frameworks, enabling predictive enrollment models.
- Academic Medical Center Partnerships:National Cancer Institute-funded investigator-initiated trials in the United States provide de-risked early-phase data for commercial licensing.
Industry Challenges
- Glycoengineering Talent Scarcity:Shortage of process development scientists with expertise in Fc-effector function optimization for agonist antibodies slows CMC timeline execution.
- ISO 14644 Cleanroom Capex Burden:Commercial-grade aseptic manufacturing facilities require substantial capital deployment before revenue-generating approval, straining development-stage balance sheets.
- ICH Q5D Cell Substrate Qualification Complexity:Extended characterization timelines for master cell banks and working cell banks delay initiation of pivotal clinical supply campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OX40 Receptor Agonist Market |
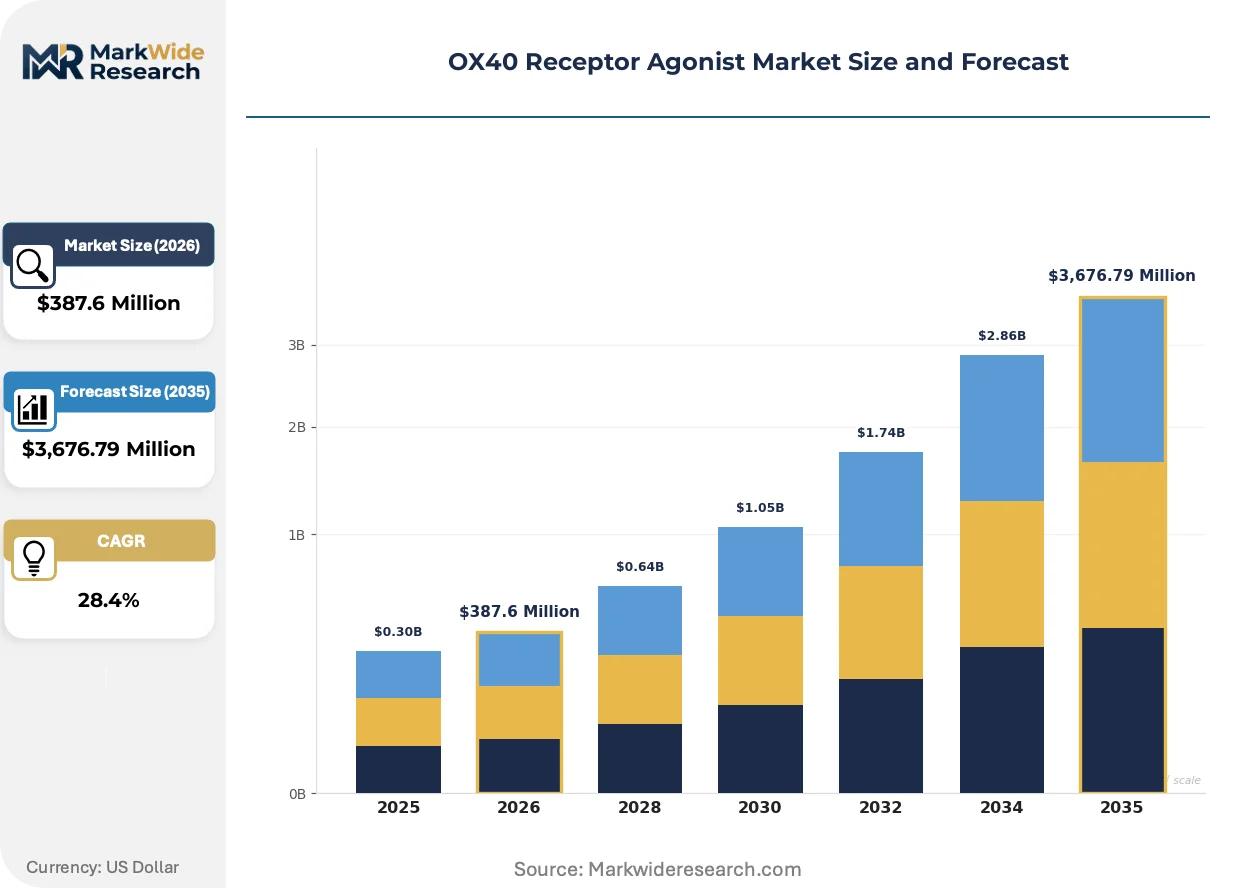
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $3,676.79 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Peptides, Fusion Proteins Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Allergies Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Specialty Clinics, Research Institutions, Homecare |
| Companies Covered | Merck, Pfizer, GlaxoSmithKline, Glenmark, AstraZeneca, Roche, Agenus, Bristol Myers Squibb, Sorrento Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OX40 Receptor Agonist Market Evolving Landscape
Decentralized manufacturing platforms and algorithmic patient selection are restructuring how OX40 agonists advance from discovery through commercial scale-up, compressing traditional biopharma development paradigms.
Continuous bioprocessing technology is decentralizing production economics for monoclonal antibody candidates. Mid-size biotech developers are adopting perfusion-based bioreactor systems to bypass large-scale stainless-steel facility requirements. This shift is enabling distributed manufacturing networks that reduce geographic concentration risk for clinical supply.
EMA's PRIME eligibility scheme is accelerating scientific advice and accelerated assessment pathways for advanced therapy medicinal products. Sponsors gain priority access to rapporteur appointment and centralized procedure support. Oncology developers targeting solid tumors with OX40 combinations are restructuring regulatory submission timelines around these enhanced engagement mechanisms.
Site-less clinical trial models are displacing traditional academic center enrollment for early-phase immunotherapy studies. Virtual patient monitoring and decentralized laboratory networks enable broader geographic recruitment. This pattern is most visible in United States-based phase I programs where community oncology practices participate alongside NCI-designated cancer centers.
OX40 Receptor Agonist Market Segmentation
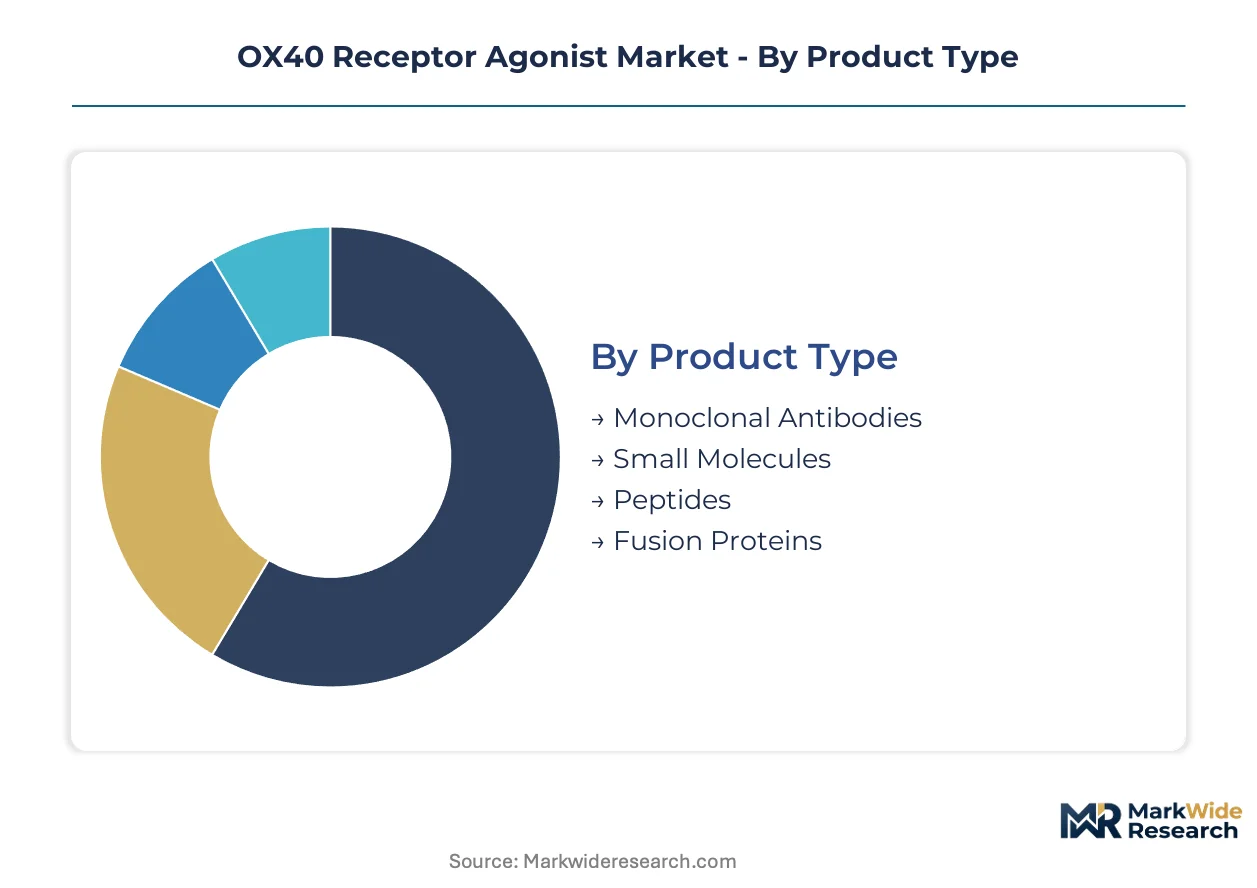
OX40 receptor agonist development pipelines fragment across molecular architectures and therapeutic applications, with each segment demanding distinct manufacturing infrastructure, regulatory pathways, and clinical positioning strategies. Supply chain configuration and patient access models diverge sharply between biologic and small molecule platforms.
Product Type:
Manufacturing capacity for complex glycoproteins concentrates at mammalian cell culture facilities operated by established biologics developers, creating asymmetric supply economics across molecular formats.
- Monoclonal Antibodies:These immunoglobulin-based therapeutics require CHO cell expression systems and protein A chromatography purification to achieve sub-nanomolar binding affinity against TNFRSF4. Demand concentrates in United States oncology departments at NCI-designated cancer centers where intravenous administration protocols dominate solid tumor trials. Fc-effector function engineering remains a critical differentiator for agonist potency.
- Small Molecules:Synthetic chemistry routes enable oral bioavailability and blood-brain barrier penetration unattainable with large proteins. Neuro-oncology applications in glioblastoma drive investment from developers seeking CNS indications where monoclonal antibodies fail to penetrate. FDA breakthrough therapy designations in this category target orphan indications with accelerated review timelines.
- Peptides:These short-chain amino acid constructs offer intermediate properties between antibodies and small molecules, with solid-phase synthesis enabling rapid lead optimization cycles.
- Fusion Proteins:Engineered constructs combining OX40 binding domains with Fc or cytokine moieties seek extended half-life and enhanced immune cell recruitment.
Today's leader: Monoclonal Antibodies. Tomorrow's challenger: Small Molecules.
Therapy Area:
Clinical trial investment and reimbursement dynamics vary dramatically across immunological indications, with oncology commanding premium pricing and autoimmune disorders offering volume expansion through outpatient administration.
- Oncology:Solid tumor microenvironments with T-cell exhaustion represent the primary commercial target for OX40 agonist combinations with checkpoint inhibitors. Academic medical centers in the United States anchor investigator-initiated trials funded through National Cancer Institute mechanisms. Companion diagnostic integration with PD-L1 or tumor mutational burden biomarkers shapes patient selection strategies.
- Autoimmune Disorders:Rheumatology and dermatology departments seek alternatives to established biologics through subcutaneous formulations that enable home administration. Protocol adherence improvements drive payer interest in self-injectable OX40 agonists for rheumatoid arthritis and psoriasis populations.
- Infectious Diseases:Vaccine adjuvant applications and chronic infection settings explore OX40 co-stimulation for memory T-cell expansion.
- Allergies:Desensitization protocols investigate agonist-mediated regulatory T-cell modulation for allergic rhinitis and food allergy indications.
Oncology retains revenue concentration. Autoimmune Disorders climb the fastest toward commercial scale.
Delivery Mode:
Route of administration determines site-of-care economics and patient compliance profiles, with hospital-based infusion centers requiring distinct supply chain configurations from retail pharmacy distribution.
- Intravenous:Hospital oncology units maintain clinical precedence for monoclonal antibody candidates, with centralized pharmacy compounding and infusion chair capacity constraining patient throughput. United States academic medical centers expand dedicated immuno-oncology infusion suites to accommodate combination therapy schedules.
- Subcutaneous:Prefilled syringe and autoinjector formats enable rheumatology and dermatology outpatient protocols where patient convenience drives adherence. EMA PRIME eligibility pathways accelerate assessment for self-administered autoimmune indications.
- Oral:Small molecule candidates targeting CNS penetration require formulation development for gastric stability and hepatic first-pass metabolism management.
- Intramuscular:Vaccine adjuvant applications and depot formulations explore sustained-release pharmacokinetics for infectious disease prophylaxis.
Intravenous anchors current revenue. Subcutaneous gains share fastest through autoimmune expansion.
End User:
Procurement authority and reimbursement pathways diverge across care settings, with hospital pharmacy and therapeutics committees controlling biologic access while specialty pharmacies manage outpatient distribution.
- Hospitals:Inpatient oncology departments and infusion centers command purchasing decisions for intravenous monoclonal antibodies, with pharmacy and therapeutics committees evaluating formulary placement against PD-1/PD-L1 comparator benchmarks. United States 340B drug pricing program participation shapes contract negotiation dynamics.
- Specialty Clinics:Rheumatology and dermatology group practices seek subcutaneous alternatives that reduce nursing burden and expand patient panel capacity. Reimbursement under Medicare Part B versus Part D creates site-of-care arbitrage opportunities.
- Research Institutions:National Cancer Institute-funded centers conduct early-phase investigator-initiated trials generating de-risked clinical data for commercial licensing.
- Homecare:Self-administration models for subcutaneous and oral formats require nursing support infrastructure and patient training programs.
Hospitals dominate current prescribing. Specialty Clinics represent the steepest expansion trajectory through outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Cancer Institute-funded translational research cluster in the United States concentrates early-phase investigator-initiated trials and shapes global clinical development patterns for OX40 receptor agonists.
United States
Academic medical centers in Boston, Houston, and San Francisco anchor the majority of phase I/II combination trials with checkpoint inhibitors. FDA breakthrough therapy designation compresses rolling review timelines for sponsors demonstrating substantial improvement over available therapies. The 340B drug pricing program participation shapes hospital pharmacy procurement negotiations for intravenous monoclonal antibodies.
Germany
Heidelberg and Munich-based university hospitals integrate EMA PRIME eligibility pathways into early regulatory strategy for solid tumor indications. The country's national pharmaceutical regulator emphasizes scientific advice priority access for advanced therapy medicinal products. Bavarian biotech clusters specialize in Fc-engineering process development for agonist antibody candidates.
Switzerland
Basel and Zurich pharmaceutical hubs concentrate companion diagnostic integration expertise for biomarker-selected patient stratification. Swissmedic maintains alignment with EMA centralized procedures while offering national scientific advice for complex glycoprotein manufacturing. The Lake Geneva region hosts specialized CDMO capacity for mammalian cell culture production.
United Kingdom
London and Cambridge immuno-oncology centers leverage MHRA innovation passports for enhanced regulatory engagement on combination therapy designs. The country's national pharmaceutical regulator participates in FDA project Orbis for concurrent oncology program review. The Golden Triangle biotech corridor attracts venture funding for subcutaneous formulation development.
Japan
Tokyo and Osaka academic hospitals conduct sakigake-designated trials for OX40 agonists addressing unmet need in gastric and lung cancers. PMDA consultation programs accelerate review for orphan indications with limited treatment options. The Kanto region concentrates perfusion-based bioreactor technology adoption for distributed manufacturing networks.
OX40 Receptor Agonist Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized indication niches and novel molecular formats beyond monoclonal antibodies. The development pipeline fragments across large-cap pharmaceutical developers with captive biologics infrastructure and mid-size biotechs relying on outsourced CDMO relationships. Three archetypes dominate: vertically integrated antibody specialists, small molecule discovery platforms, and cell therapy infrastructure deployers. Competitive positioning hinges on bioreactor capacity control and companion diagnostic co-development partnerships.
Among large-cap developers, Bristol Myers Squibb, Merck, and Roche exemplify distinct strategic archetypes in this landscape. Bristol Myers Squibb anchors the cell therapy infrastructure deployer position through integration of large-scale GMP production capabilities. Merck occupies the vertically integrated antibody specialist tier with upstream bioreactor capacity concentration. Roche represents the companion diagnostic integrator archetype, positioning programs within biomarker-selected populations. These three companies illustrate how manufacturing control, regulatory strategy, and patient selection technology differentiate competitive positioning in co-stimulatory immunotherapy development.
| Leading Market Players |
|---|
| Merck |
| Pfizer |
| GlaxoSmithKline |
| Glenmark |
| AstraZeneca |
| Roche |
| Agenus |
| Bristol Myers Squibb |
| Sorrento Therapeutics |
| Others |
Value Network & Pricing Analysis
Mammalian cell culture media costs cascade through CHO expression system economics to stratify monoclonal antibody pricing across premium GMP-grade, qualified clinical-grade, and research-use tiers. United States-based academic medical centers absorb premium pricing for FDA breakthrough therapy-designated candidates, while European hospital systems negotiate under EMA centralized procurement frameworks.
Pricing Analysis
Input-cost pass-through from bioreactor operations and protein A chromatography resin pricing shapes three-tier pricing structure across premium, standard, and economy levels for OX40 agonist candidates. Fc-engineering sophistication and companion diagnostic bundling differentiate premium tiers, while biosimilar pressure and PD-1/PD-L1 substitution constrain pricing power in first-line oncology. Cost compression in clinical-grade supply is intensifying because CDMO capacity scarcity concentrates negotiation leverage with contract manufacturers. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity, whereas NCI-funded investigator-initiated trials demonstrate lowest sensitivity due to non-commercial funding mechanisms.
Supply Chain Analysis
ISO 14644 cleanroom certification and ICH Q5D cell substrate qualification gate entry to commercial-grade supply, concentrating mammalian cell culture capacity in the United States, Switzerland, and Germany. CHO master cell banks, protein A chromatography resins, and single-use bioreactor bags constitute critical input dependencies. Single-source vulnerability pervades large-scale stainless-steel bioreactor networks, where limited qualified facilities create bottleneck risk for pivotal clinical supply. Distribution runs through centralized hospital pharmacy compounding for intravenous oncology formulations and specialty pharmacy channels for subcutaneous autoimmune protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation and EMA PRIME eligibility compound regulatory value, accelerating commercial entry timelines and compressing development risk for sponsors demonstrating substantial improvement over available therapies.
For Market Incumbents: Lock in bioreactor capacity through long-term CDMO offtake agreements or captive facility investment, securing GMP supply for combination trial expansion. Counter small molecule neuro-oncology substitution threats by deepening Fc-engineering differentiation and companion diagnostic co-development partnerships. Prioritize ISO 14644 cleanroom certification investment to maintain quality-tier positioning against emerging entrants. For New Entrants and Emerging Players: The price-point gap between premium antibody candidates and economy-tier research reagents opens white-space opportunity in oral small molecule formats for CNS indications. Target autoimmune subcutaneous protocols where patient convenience drives adherence and payer receptivity exceeds saturated oncology markets. Pursue site-less clinical trial models to bypass established academic center enrollment bottlenecks and accelerate early-phase data generation. For Investors and Strategic Acquirers: Consolidation pressure builds where glycoengineering talent scarcity constrains CMC execution for mid-size biotechs lacking process development depth. Five-to-ten year viability favors platforms with demonstrated regulatory pathway navigation and manufacturing control rather than single-asset candidates. Acquisition target archetype: mid-size developers with EMA PRIME eligibility and distributed perfusion-based manufacturing networks. Watch FDA guidance evolution on dual immunotherapy safety database requirements as inflection signal for combination trial economics.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Site-less trial models expand geographic recruitment beyond NCI-designated cancer centers. |
| Manufacturing Scale-Up | Perfusion-based bioreactor adoption bypasses stainless-steel facility concentration risk. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation enables rolling review before pivotal completion. |
| Companion Diagnostic Integration | Biomarker-selected stratification improves response rates and payer support. |
| Pipeline Diversification | Small molecule CNS programs address glioblastma penetration where antibodies fail. |
Research Methodology
Bottom-up oncology and autoimmune protocol modeling reconciled against top-down CDMO capacity and bioreactor utilization tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Top-down supply-side assessment of mammalian cell culture facility capacity and perfusion technology adoption patterns triangulates against bottom-up demand estimation.
The input-output matrix framing connects patient population incidence, treatment line positioning, and administration route preferences to manufacturing throughput requirements and pricing tier elasticity. Segmentation dimensions span molecular format, therapy area, delivery mode, and end-user setting across the projection horizon. CAGRs derive from modeled patient flow through treatment lines, adjusted for regulatory approval probability and competitive entry assumptions. Forecast inputs incorporate checkpoint inhibitor combination penetration rates and subcutaneous formulation adoption curves in rheumatology and dermatology.
The model assumes a particular technology adoption path; alternative pathways for continuous bioprocessing and decentralized manufacturing would alter the outlook for capacity economics and supply chain risk distribution. Forecasts reflect assumptions regarding regulatory pathway efficiency, manufacturing scale-up success, and competitive substitution dynamics. A model refresh is warranted upon material change in FDA guidance on dual immunotherapy safety requirements or EMA PRIME eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Global Recombinant Vaccines Market