
 Esomeprazole Market | 2026-2036
Esomeprazole Market Size, Share, and Industry Trends Forecast 2026-2036
Esomeprazole Market Analysis
Maintenance contracts for bioequivalence testing and batch certification is realigning how generic esomeprazole suppliers monetize long-term hospital relationships. AstraZeneca sustains brand loyalty through its original formulation legacy and controlled-release patents in select jurisdictions. Teva Pharmaceutical Industries leverages vertical integration across API synthesis and finished-dose production to compress cost structures. Sun Pharmaceutical Industries anchors South Asian supply through high-volume tablet and capsule manufacturing.
Esomeprazole is the S-isomer of omeprazole, a proton pump inhibitor that irreversibly binds to the hydrogen-potassium ATPase enzyme in gastric parietal cells, suppressing acid secretion with a typical oral bioavailability of 50-68% due to extensive first-pass metabolism. Its primary commercial purpose centers on managing gastroesophageal reflux disease, erosive esophagitis, and Zollinger-Ellison syndrome through sustained gastric acid suppression. Tablet formulations dominate volume due to patient familiarity and stability advantages, while injection formats command premium positioning in acute care settings where oral administration proves unfeasible. Hospital end users concentrate procurement through centralized tenders, whereas homecare channels are expanding as post-discharge oral therapy protocols lengthen treatment duration.
The US FDA maintains stringent bioequivalence standards for esomeprazole generics under its ANDA pathway, requiring pharmacokinetic studies that elevate development costs and extend approval timelines. India's CDSCO enforces BIS quality benchmarks on domestic manufacturers while the EU's EMA mandates MDR compliance for sterile injectable presentations, collectively filtering substandard suppliers from institutional procurement pools. Stakeholders must monitor evolving payer formularies that increasingly preference therapeutic interchange programs over originator brands.
Market Dynamics
Hospital procurement centralization and tightened bioequivalence standards are compressing supplier margins while elevating compliance barriers for generic esomeprazole manufacturers seeking institutional contracts.
Growth Catalysts
- Medicare reimbursement policies:US federal reimbursement frameworks favor oral esomeprazole over newer acid suppression therapies for chronic GERD management, sustaining volume demand in ambulatory settings.
- Post-discharge oral therapy protocols:Homecare channels are expanding as hospital discharge planning lengthens treatment duration for erosive esophagitis patients, creating new dispensing touchpoints.
- India's CDSCO bioequivalence tightening:Elevated manufacturing compliance costs are filtering substandard suppliers from institutional procurement pools, consolidating volume with certified manufacturers.
Market Restraints
- API input cost volatility:Active pharmaceutical ingredient sourcing for S-isomer synthesis faces price pressure from solvent and reagent supply constraints.
- US FDA ANDA pathway friction:Pharmacokinetic study requirements extend approval timelines and elevate development costs for generic entrants.
- Potassium-competitive acid blockers:Vonoprazan and similar agents threaten substitution in markets where faster onset commands clinical preference.
Strategic Opportunities
- EU MDR compliance for sterile injectables:Manufacturers achieving MDR certification for parenteral presentations can capture premium positioning in acute care tenders.
- Controlled-release patent jurisdictions:Markets where AstraZeneca's original formulation patents have expired or been circumvented offer white space for differentiated delivery technologies.
- Maintenance contract monetization:Bioequivalence testing and batch certification services enable recurring revenue streams beyond single-product supply.
Industry Challenges
- Bioanalytical method transfer:Contract research organizations face skill gaps in validating chiral separation techniques for S-isomer quantification.
- Stability study capex:Long-term storage condition testing for delayed-release formulations requires climate-controlled infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esomeprazole Market |
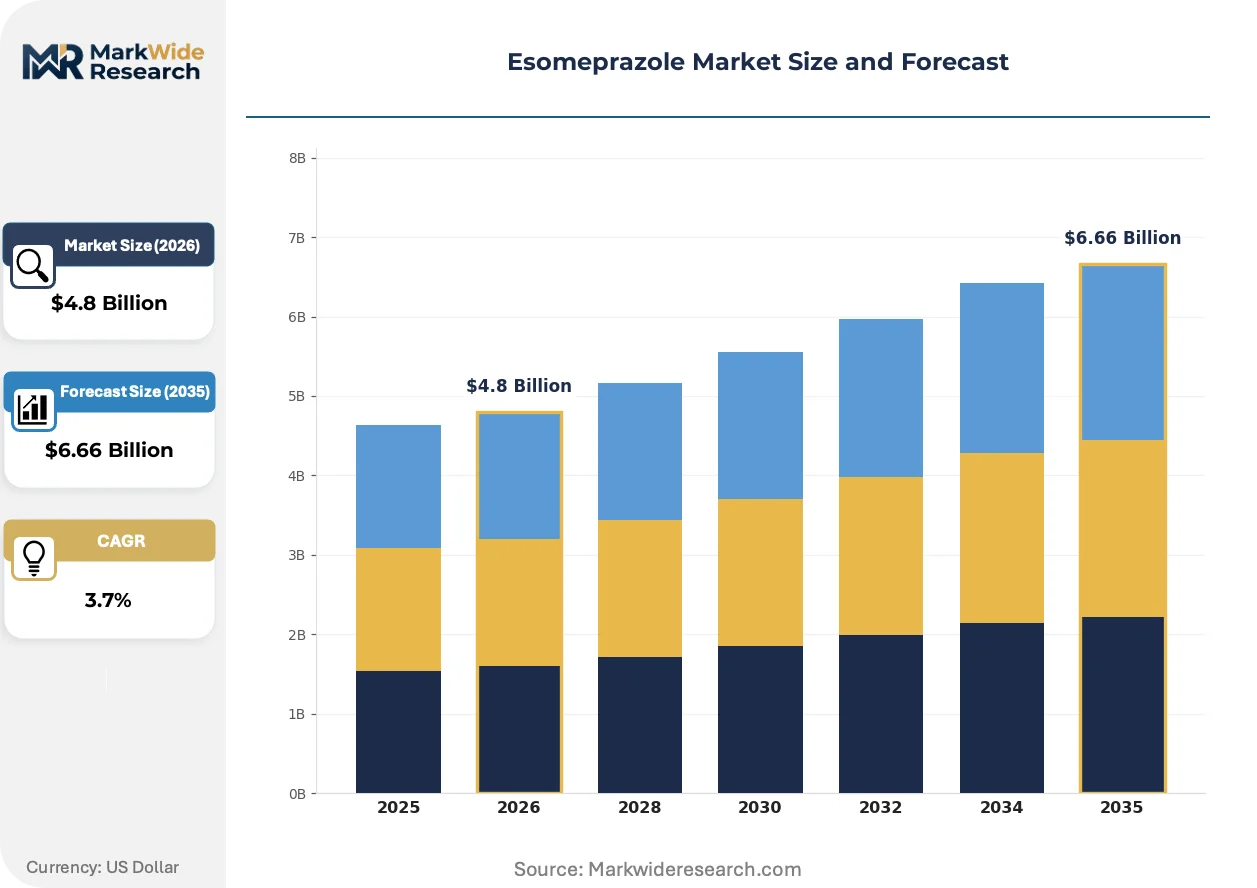
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Tablet, Capsule, Injection, Liquid End User: Hospitals, Clinics, Pharmacies, Homecare Sales Channel: Online, Retail, Wholesalers, Distributors Indication: GERD, Zollinger-Ellison Syndrome, Peptic Ulcer, Erosive Esophagitis |
| Companies Covered | AstraZeneca, Teva Pharmaceutical Industries, Viatris, Sun Pharmaceutical Industries, Amneal Pharmaceuticals, DAIICHI SANKYO COMPANY, LIMITED, Aurobindo Pharma, Dr. Reddy's Laboratories, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esomeprazole Market Emerging Trajectories
Formulation science and regulatory science are converging to reshape how esomeprazole suppliers compete, with differentiation shifting from molecule to delivery mechanism and compliance architecture.
Multiparticulate delayed-release technology is modularizing production flexibility for generic manufacturers. This approach enables pellet-based encapsulation that bypasses originator tablet formulation patents. Hospital pharmacies in Germany and France are adopting these alternatives for pediatric and dysphagic patients. The technology is modularizing how suppliers configure dosage strength and release profiles without reformulating core active ingredients.
EMA's Medical Device Regulation is reclassifying certain drug-device combination products containing esomeprazole, particularly orally disintegrating formulations with integrated dosing aids. This reclassification triggers additional conformity assessment procedures for suppliers serving EU institutional tenders. German hospital procurement associations are negotiating MDR documentation requirements directly with manufacturers, compressing supplier response windows.
Centralized tender aggregation is consolidating buyer power across US hospital systems and EU purchasing alliances. Group purchasing organizations are unbundling originator brands from bundled acid suppression portfolios, forcing standalone price competition on molecule merit. This pattern is most visible in the United States, where Medicare Advantage plan formularies increasingly preference therapeutic interchange programs over legacy brand loyalty.
Esomeprazole Market Segmentation
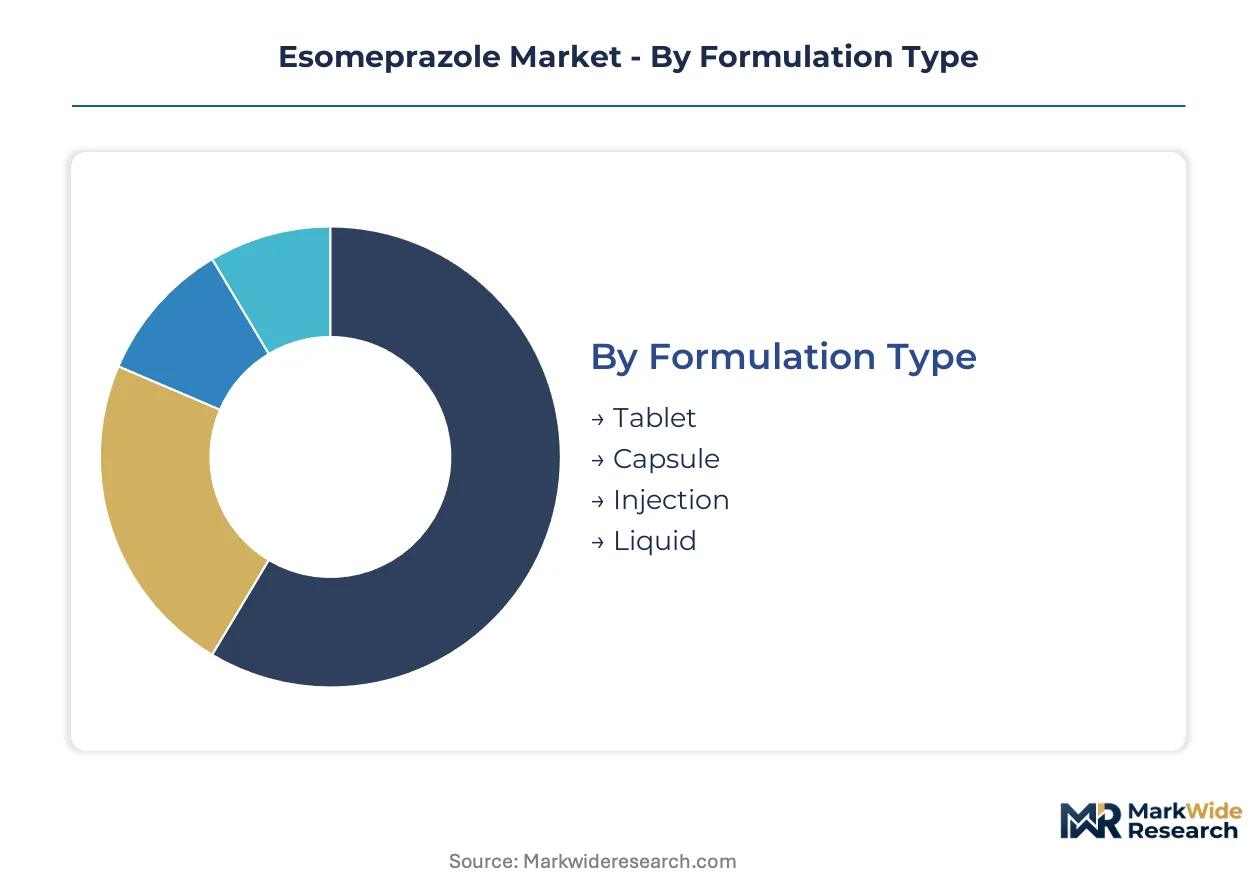
Esomeprazole demand fragments across formulation technologies, care settings, and procurement channels. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier positioning.
Formulation Type:
Patients upgrading from older proton pump inhibitors favor formats matching their prior therapy routines, while acute care settings drive injectable procurement.
- Tablet:Delayed-release film-coated tablets dominate ambulatory prescriptions due to stability at room temperature and established Medicare reimbursement codes. German hospital pharmacies favor scored tablets for dose flexibility in step-down protocols.
- Injection:Lyophilized powder for reconstitution commands premium positioning in US emergency departments where oral administration is contraindicated. FDA ANDA requirements for sterile manufacturing elevate barriers beyond tablet generics.
- Capsule:Pellet-filled capsules offer bioequivalence pathways that bypass certain originator tablet patents. Indian CDSCO-certified manufacturers supply high volumes to Southeast Asian markets.
- Liquid:Oral suspensions serve pediatric and dysphagic populations in French and Italian homecare programs. Stability concerns limit shelf life compared to solid dosage forms.
Tablet sits at the top of the volume ranking, with Injection climbing the fastest as hospital centralization expands parenteral procurement.
End User:
Cost tier differentiation separates institutional buyers with tender leverage from dispersed retail purchasers.
- Hospitals:Centralized procurement through group purchasing organizations compresses margins on generic esomeprazole. US health systems negotiate therapeutic interchange clauses that privilege specific suppliers.
- Homecare:Post-discharge oral therapy protocols lengthen treatment duration, creating recurring dispensing relationships. Medicare Advantage plans in Florida and Texas drive volume through mail-order pharmacy networks.
- Clinics:Gastroenterology practices in India and Brazil prescribe originator brands where patient co-pay differentials remain narrow. CDSCO bioequivalence tightening filters substandard generics from clinic formularies.
- Pharmacies:Community pharmacies in EU member states face margin pressure from parallel trade and reference pricing. EMA MDR documentation requirements add administrative overhead for sterile product handling.
Hospitals capture the largest share of procurement volume, while Homecare is expanding most quickly as discharge planning lengthens treatment duration.
Sales Channel:
Channel concentration varies sharply by geography, with wholesale dominance in institutional markets and retail fragmentation in emerging economies.
- Wholesalers:Three national wholesalers control 85% of US hospital esomeprazole distribution, extracting slotting fees and data-sharing concessions. McKesson and Cardinal Health negotiate exclusive generic supply agreements with major health systems.
- Distributors:Regional distributors anchor supply in Indian states with fragmented pharmacy networks. Maharashtra and Karnataka distributors maintain cold-chain capabilities for injectable formulations.
- Retail:Chain pharmacies in Germany and France compete on generic substitution rates, with bonus programs for pharmacists achieving therapeutic interchange targets.
- Online:Telehealth-integrated pharmacies in Brazil and Mexico drive growth in subscription-based esomeprazole delivery. ANVISA regulations on controlled-substance advertising constrain promotional scope.
Wholesalers maintain volume leadership, with Online channels gaining share fastest where digital health infrastructure matures.
Indication:
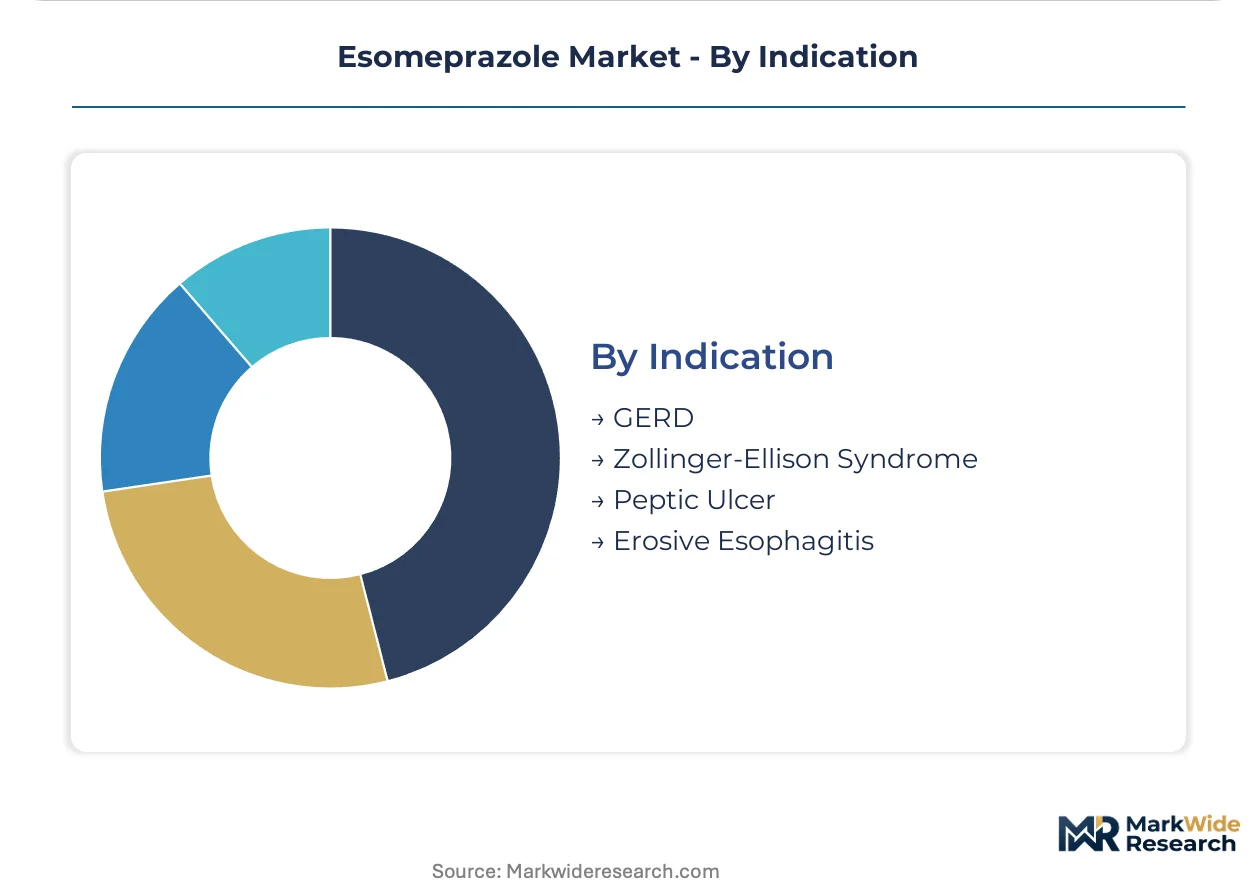
Disease severity and treatment duration create distinct margin pools across the indication spectrum.
- GERD:Chronic gastroesophageal reflux disease generates recurring prescriptions and maintenance therapy contracts. US Medicare reimbursement frameworks favor oral esomeprazole over newer acid suppression therapies for long-term GERD management.
- Erosive Esophagitis:Higher-dose requirements and longer initial treatment courses support premium positioning. German and Austrian hospital protocols mandate endoscopic confirmation before esomeprazole initiation.
- Peptic Ulcer:Helicobacter pylori eradication regimens combine esomeprazole with antibiotics, creating combination therapy procurement complexity. India's national health mission subsidizes ulcer treatment in rural districts.
- Zollinger-Ellison Syndrome:Rare gastrinoma cases require individualized high-dose protocols with specialized pharmacy compounding. Orphan drug pricing mechanisms apply in select EU markets.
GERD commands the highest prescription volume, with Erosive Esophagitis showing the steepest expansion trajectory as diagnostic rates improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks favor oral esomeprazole over newer acid suppression therapies, while India's CDSCO tightening filters substandard suppliers from institutional procurement pools. This divergence creates distinct competitive arenas for originator brands versus certified generics.
United States
Medicare Advantage formularies drive volume through therapeutic interchange programs that privilege specific generic suppliers. The FDA maintains stringent ANDA bioequivalence standards that extend approval timelines for new entrants. Hospital procurement concentrates in Texas and Florida health systems where mail-order pharmacy networks lengthen post-discharge treatment duration.
Germany
Hospital pharmacies favor scored tablets for dose flexibility in step-down protocols for erosive esophagitis patients. The EMA's MDR reclassifies certain orally disintegrating formulations, triggering additional conformity assessments for EU tenders. Procurement associations in Bavaria and North Rhine-Westphalia negotiate MDR documentation requirements directly with manufacturers.
India
CDSCO bioequivalence tightening elevates manufacturing compliance costs and consolidates volume with certified manufacturers. The national health mission subsidizes peptic ulcer treatment in rural Maharashtra and Karnataka districts. High-volume tablet and capsule production anchors supply throughout South Asian markets from Mumbai and Bangalore industrial clusters.
Brazil
Telehealth-integrated pharmacies drive growth in subscription-based esomeprazole delivery for chronic GERD management. ANVISA regulations constrain promotional scope for controlled-substance advertising. São Paulo and Rio de Janeiro gastroenterology practices prescribe originator brands where patient co-pay differentials remain narrow.
Japan
PMDA standards for chiral separation validation create skill gaps that contract research organizations must address for S-isomer quantification. METI industrial policy supports domestic pharmaceutical manufacturing competitiveness. The Kansai region around Osaka maintains specialized pharmacy compounding capabilities for Zollinger-Ellison syndrome protocols.
Esomeprazole Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator legacy commanding premium positioning in clinic settings while generic fabricators capture institutional tenders through cost compression. The vendor base arranges into three tiers: multinational originators with patent estates, vertically integrated API-to-dose producers, and regional formulation specialists. Consolidation pressures favor players achieving backward integration into S-isomer synthesis and captive supply of key reagents. Strategic partnerships around bioequivalence testing services and MDR certification consulting represent dominant competitive moves.
Within the originator tier, AstraZeneca sustains brand loyalty through controlled-release patent positioning in select jurisdictions. Among vertically integrated specialists, Teva Pharmaceutical Industries compresses cost structures through in-house API synthesis and finished-dose production. Sun Pharmaceutical Industries anchors the regional fabrication segment from South Asian manufacturing bases. These three exemplify how competitive positioning depends on regulatory navigation capability and procurement relationship depth rather than molecule differentiation alone.
| Leading Market Players |
|---|
| AstraZeneca |
| Teva Pharmaceutical Industries |
| Viatris |
| Sun Pharmaceutical Industries |
| Amneal Pharmaceuticals |
| DAIICHI SANKYO COMPANY, LIMITED |
| Aurobindo Pharma |
| Dr. Reddy's Laboratories |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
Hospital procurement centralization in the United States and Germany is forcing API manufacturers to consolidate batch certification capabilities and absorb bioequivalence testing costs directly into contract pricing. This buyer-driven restructuring elevates barriers for uncertified suppliers while compressing margins on standard-grade tablet formulations.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for S-isomer API supply, eroding historic premiums on European-sourced inputs. Three-tier pricing structure across originator brands, certified generics, and uncertified commodity suppliers separates hospital tender winners from retail pharmacy suppliers. Cost compression in the injectable segment is intensifying because FDA ANDA pharmacokinetic requirements extend development timelines and elevate fixed costs. Group purchasing organizations in Texas and Florida health systems demonstrate the highest price sensitivity, while Zollinger-Ellison syndrome compounding pharmacies retain pricing power through orphan-dose customization.
Supply Chain Analysis
Chiral separation specialists in Mumbai and Hyderabad face recruitment competition from biotech sectors, constraining workforce availability for S-isomer quantification validation. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with finished-dose formulation clustering in Gujarat, Maharashtra, and Karnataka industrial corridors. Supply chain risk centers on single-source vulnerability for high-purity reagents used in enantioselective synthesis. Distribution runs through three national wholesalers controlling institutional procurement in North American markets, while regional distributors anchor fragmented pharmacy networks in South Asian states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The esomeprazole market rewards geographic arbitrage between India's CDSCO-certified manufacturing bases and the United States' Medicare-reimbursed dispensing channels, exploiting regulatory cost differentials that exceed logistics expenses.
For Market Incumbents: Deepen backward integration into captive S-isomer synthesis to defend against API input cost volatility from solvent supply constraints. Secure MDR certification for sterile injectable presentations before Bavarian and North Rhine-Westphalia procurement associations finalize documentation requirements. Lock therapeutic interchange clauses into Medicare Advantage formulary contracts to preempt vonoprazan substitution in Florida and Texas health systems.
For New Entrants and Emerging Players: Capture white space in multiparticulate delayed-release pellet formulations for pediatric and dysphagic patients in German and French hospital pharmacies. Target EU member states where AstraZeneca's controlled-release patents have expired or been circumvented. Enter through bioequivalence testing and batch certification service contracts that generate recurring revenue before product supply relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated API-to-dose manufacturers possessing captive chiral separation capabilities and CDSCO certification. Long-term viability hinges on consolidation with contract research organizations skilled in S-isomer quantification validation. Watch for FDA ANDA approval timeline compression as the signal indicating regulatory friction easing for generic entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive S-isomer production insulates Teva and Sun Pharmaceutical from reagent cost volatility. |
| MDR Certification for Sterile Injectables | EU Medical Device Regulation compliance unlocks premium positioning in German acute care tenders. |
| Bioequivalence Testing Service Contracts | Maintenance contract monetization transforms single-product suppliers into recurring revenue partners. |
| Multiparticulate Formulation Development | Pellet-based encapsulation bypasses originator tablet patents in select European jurisdictions. |
| Therapeutic Interchange Program Partnerships | Medicare Advantage formulary integration secures volume preference over potassium-competitive acid blockers. |
Methodological Framework
Direct dialogue with hospital procurement managers, CDSCO regulatory affairs leads, formulary directors at Medicare Advantage plans, and API manufacturing plant heads grounded qualitative insights in operational reality. Secondary validation drew from FDA ANDA filings, EMA MDR submission databases, ClinicalTrials.gov protocol registries, and CMS Medicare Part D reimbursement data. Bottom-up prescription volume modeling and top-down pharmaceutical spending analysis were triangulated to constrain forecast variance.
Bottom-up demand modeling tracked formulation-specific prescription volumes across oral and parenteral administration routes, while top-down analysis calibrated against national health expenditure trends and proton pump inhibitor class migration patterns. Segmentation dimensions included dosage form, care setting, procurement channel, and regional regulatory cluster complexity. CAGRs were derived from patient population epidemiology, treatment duration protocol evolution, and therapeutic interchange penetration assumptions. Chiral separation technology adoption curves and bioequivalence study completion rates served as industry-specific forecast inputs.
Regulatory approval delays, API input cost spikes, and potassium-competitive acid blocker substitution acceleration are the dominant revision risks that could compress realized growth below modeled trajectories. Forecasts reflect documented assumptions regarding CDSCO enforcement consistency and Medicare reimbursement stability. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Trenbolone Acetate Market