
 Global Lipid Disorder Treatment Market | 2026-2036
Global Lipid Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lipid Disorder Treatment Market Foresight
Next-generation LDL-C lowering thresholds are reorganizing competitive dynamics across the lipid disorder treatment landscape. Pfizer leverages its manufacturing scale to supply oral statin formulations across diverse channel structures. Amgen competes through concentrated R&D intensity in injectable PCSK9 inhibitor platforms. Sanofi anchors European market access through established relationships with cardiology clinics and specialty hospitals.
Lipid disorder treatment encompasses pharmacological interventions targeting abnormal cholesterol and triglyceride levels, including small-molecule drugs and monoclonal antibodies that modulate HMG-CoA reductase activity or enhance LDL receptor recycling. These therapies reduce atherosclerotic cardiovascular disease risk in patient populations with familial or acquired dyslipidemias. PCSK9 inhibitors command premium positioning within the product type architecture due to their efficacy in statin-intolerant patients. The therapy area segment shows mixed dyslipidemia expanding fastest as polygenic risk scores enable earlier identification. Oral tablets dominate delivery mode volumes, though injectable solutions capture disproportionate margin pools in severe hypercholesterolemia cases.
The FDA mandates cardiovascular outcome trials for novel lipid-lowering mechanisms, while the EMA enforces post-authorization safety monitoring through its pharmacovigilance framework. Japan's PMDA applies distinct ethnic bridging study requirements that shape regional development timelines and market entry sequencing. Stakeholders must monitor evolving LDL-C target guidelines from cardiology societies and their direct impact on reimbursement thresholds across national health systems.
Market Dynamics
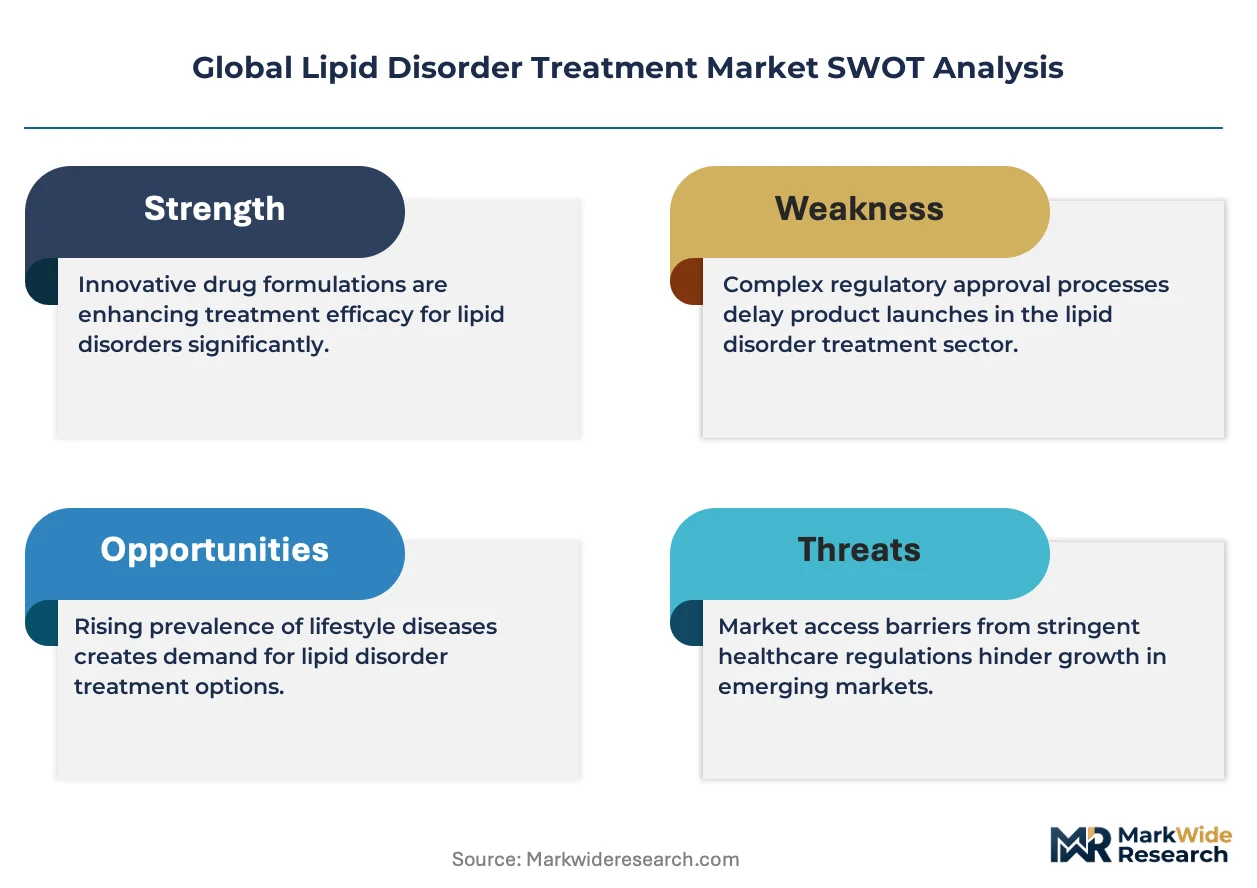
FDA-mandated cardiovascular outcome trials for novel lipid-lowering mechanisms are extending development timelines and reshaping competitive entry sequencing across the treatment landscape.
Growth Catalysts
- LDL-C Target Intensification:Cardiology societies in the United States, Germany, and Japan are lowering therapeutic thresholds, expanding addressable patient pools for combination therapies.
- EMA Pharmacovigilance Framework:Post-authorization safety monitoring requirements are building prescriber confidence in biologic therapies, accelerating hospital formulary adoption of injectable platforms.
- Polygenic Risk Scoring:Genetic screening technologies are identifying mixed dyslipidemia cases earlier, creating preventive treatment windows before cardiovascular events manifest.
Market Restraints
- Biologic Manufacturing Concentration:Injectable PCSK9 inhibitor production clusters among limited contract manufacturing organizations in Switzerland and Ireland, creating supply vulnerability.
- Statin Tolerance Substitution:Generic atorvastatin and rosuvastatin formulations continue capturing primary prevention prescriptions, compressing premium therapy penetration in mild-to-moderate cases.
- PMDA Ethnic Bridging Requirements:Japan's distinct clinical study mandates add 18-24 months to development timelines, delaying Asia-Pacific revenue recognition for novel mechanisms.
Strategic Opportunities
- Oral PCSK9 Small Molecules:Non-injectable LDL receptor recycling enhancers are advancing through Phase III, promising to unlock primary care channel access currently blocked by biologic cold-chain requirements.
- Triglyceride-Focused Indications:Severe hypertriglyceridemia represents an underpenetrated segment with no approved biologic therapies, offering first-mover positioning for apoC-III or ANGPTL3 inhibitors.
- Specialty Hospital Infusion Centers:Cardiology clinics in Germany are expanding in-house biologic administration capabilities, creating direct-to-physician distribution channels that bypass traditional pharmacy benefit managers.
Industry Challenges
- Cardiovascular Outcome Trial Execution:Event-driven study designs require 3-5 year follow-up periods, straining R&D capital allocation and delaying proof-of-concept monetization.
- Reimbursement Evidence Generation:National health systems in France and Italy demand incremental cost-effectiveness thresholds that legacy statin comparators complicate, requiring extensive real-world evidence programs.
- Cold-Chain Logistics Integration:Injectable biologics require temperature-controlled distribution infrastructure that many retail pharmacy networks lack, limiting patient access in rural geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lipid Disorder Treatment Market |
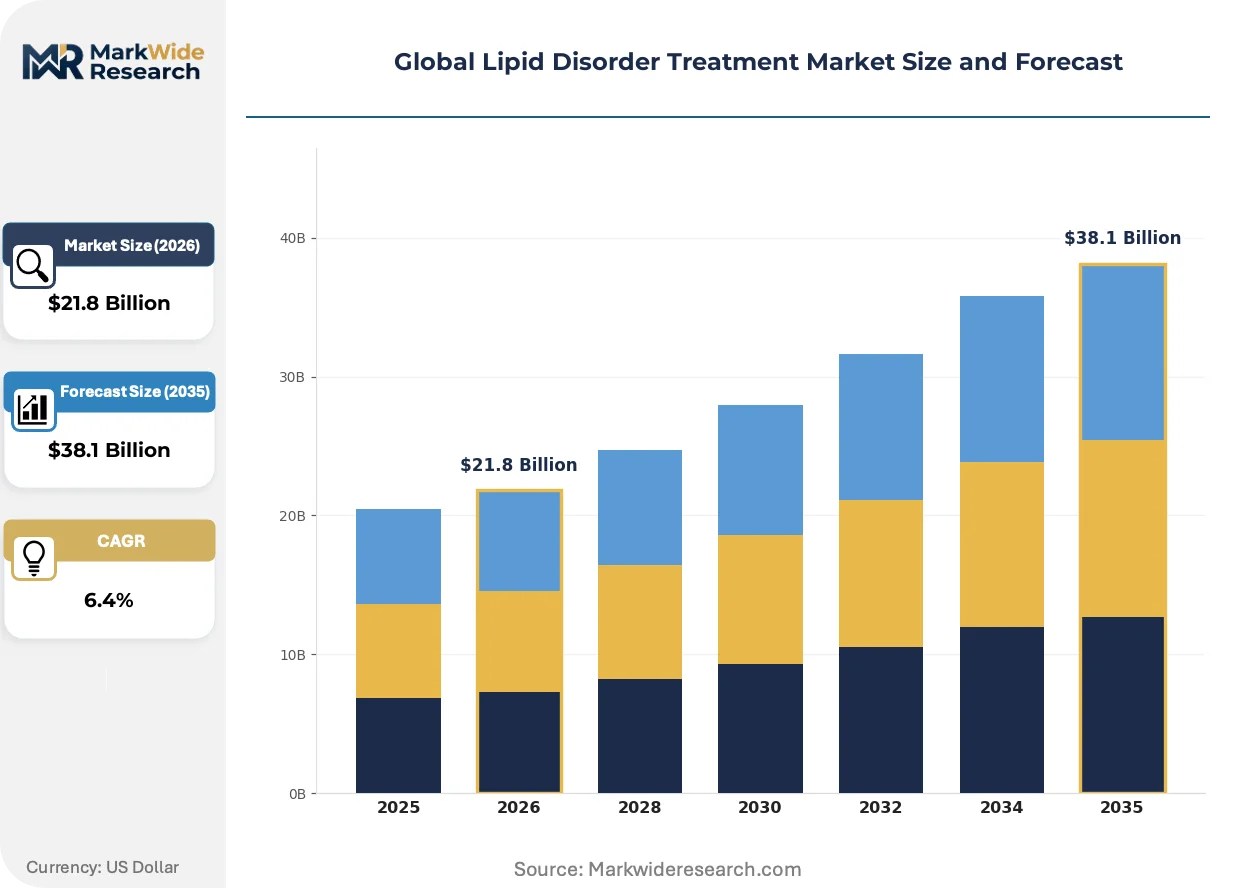
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, Fibrates, Niacin, PCSK9 Inhibitors, Bile Acid Sequestrants Therapy Area: Hypercholesterolemia, Hypertriglyceridemia, Mixed Dyslipidemia, Familial Hyperlipoproteinemia End User: Cardiology Clinics, Specialty Hospitals, Outpatient Facilities, Diagnostic Laboratories Delivery Mode: Oral Tablets, Injectable Solutions, Transdermal Patches, Sublingual Films |
| Companies Covered | Pfizer, Novartis AG, Merck & Co., AstraZeneca, Amgen, Regeneron Pharmaceuticals, Sanofi, AbbVie, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lipid Disorder Treatment Market Shifts & Advancements
Next-generation lipid disorder therapies are converging around patient convenience and cardiovascular risk precision, with oral formulations and genetic stratification displacing one-size-fits-all injectable protocols.
RNA interference platforms targeting hepatic PCSK9 expression are miniaturizing from quarterly to semi-annual dosing intervals. Specialty hospitals in the United States and Japan are piloting these extended-interval therapies for familial hypercholesterolemia patients with demonstrated statin intolerance. This dosing compression is reducing clinic visit burden while maintaining LDL-C suppression, fundamentally restructuring patient adherence economics and site-of-care revenue models.
The FDA's tightened cardiovascular outcome study requirements for novel mechanisms are forcing developers to embed hard endpoint adjudication earlier in Phase II programs. This regulatory elevation is extending pre-NDA timelines by 12-18 months and concentrating investment among sponsors with existing cardiovascular outcome infrastructure. Small-molecule programs targeting oral administration are disproportionately affected, as they must now demonstrate non-inferiority to injectable biologics on MACE reduction rather than surrogate lipid endpoints alone.
Cardiology clinics are consolidating procurement authority previously dispersed across hospital pharmacy committees and individual prescribers. Integrated delivery networks in Germany and the United States are negotiating direct contracts with manufacturers for PCSK9 inhibitor formularies, displacing traditional wholesale distribution. This channel concentration is most visible in severe hypercholesterolemia cases where biologic therapy selection follows institutional protocol rather than individual physician preference.
Global Lipid Disorder Treatment Market Segmentation
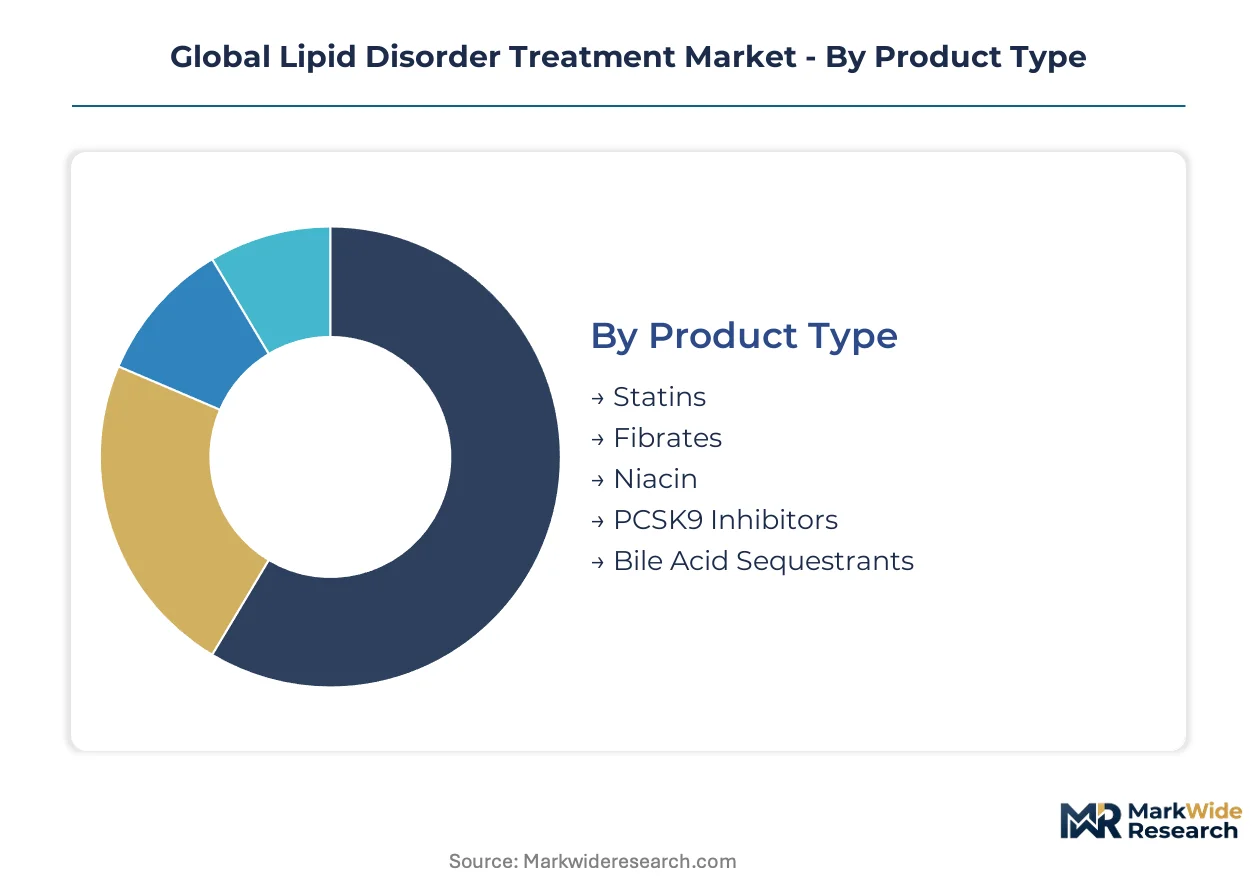
Segmentation in lipid disorder treatment determines channel access, pricing power, and clinical positioning. Product type and delivery mode dictate whether therapies reach patients through primary care networks or specialty infusion centers, while therapy area stratification shapes reimbursement negotiation leverage.
Product Type:
Channel-mix patterns vary sharply across pharmacological classes, with oral formulations dominating retail pharmacy volumes while biologics concentrate in hospital-based procurement.
- Statins:Small-molecule HMG-CoA reductase inhibitors remain the volume foundation across primary prevention populations. Demand concentrates in the United States and Germany where generic atorvastatin and rosuvastatin formulations capture first-line prescriptions through retail pharmacy networks, though margin compression limits manufacturer investment in next-generation iterations.
- PCSK9 Inhibitors:Monoclonal antibodies enhancing LDL receptor recycling command premium positioning in statin-intolerant or familial hypercholesterolemia cases. Specialty hospitals in Japan and Germany drive procurement through direct manufacturer contracts, bypassing traditional pharmacy benefit managers for severe patient cohorts.
- Fibrates:Peroxisome proliferator-activated receptor agonists targeting triglyceride reduction flow through cardiology clinic dispensing in mixed dyslipidemia protocols.
- Niacin:B-vitamin derivatives with modest HDL-raising effects have retreated to niche use in combination regimens through outpatient facilities.
- Bile Acid Sequestrants:Resin-based intestinal bile acid binders serve pediatric and pregnancy-contraindicated populations through specialty hospital formularies.
Statins dominate installed base. PCSK9 inhibitors are where expansion concentrates.
Therapy Area:
Cost-tier stratification separates preventive mass-market interventions from premium biologic therapies reserved for genetic or refractory conditions.
- Mixed Dyslipidemia:Concurrent elevation of LDL-C and triglycerides is expanding most quickly as polygenic risk scoring identifies at-risk patients earlier. Cardiology clinics in the United States are piloting combination protocols that pair low-dose statins with emerging RNA interference platforms, creating preventive treatment windows before first cardiovascular events.
- Hypercholesterolemia:Elevated LDL-C represents the largest addressable population across all channel structures. Demand clusters in Germany and Japan where national cholesterol screening programs drive systematic identification, though reimbursement thresholds vary sharply between primary prevention and established coronary artery disease cohorts.
- Hypertriglyceridemia:Isolated triglyceride elevation remains underpenetrated by biologic therapies, with fibrates and prescription omega-3 fatty acids dominating outpatient prescribing.
- Familial Hyperlipoproteinemia:Genetic dyslipidemias requiring specialized lipid clinic management concentrate in academic medical centers with cascade screening capabilities.
Hypercholesterolemia captures the greatest prescription volume. Mixed dyslipidemia shows the steepest expansion trajectory.
End User:
Customer-type concentration is shifting procurement authority toward integrated delivery networks with protocol-driven formulary control.
- Specialty Hospitals:Academic medical centers and dedicated cardiovascular institutes command biologic therapy selection for severe familial cases. German cardiology clusters are expanding in-house infusion capabilities, creating direct-to-physician distribution channels that displace wholesale intermediaries.
- Cardiology Clinics:Outpatient specialist practices are consolidating prescribing authority for combination therapies and patient monitoring. United States integrated delivery networks now negotiate PCSK9 inhibitor contracts at system level rather than individual practice discretion.
- Outpatient Facilities:Community-based primary care sites handle stable statin maintenance through retail pharmacy dispensing.
- Diagnostic Laboratories:Reference labs are embedding pharmacogenomic testing to stratify statin metabolism variants, influencing downstream therapy selection.
Cardiology clinics dominate prescription origination. Specialty hospitals are where biologic margin pools accumulate.
Delivery Mode:
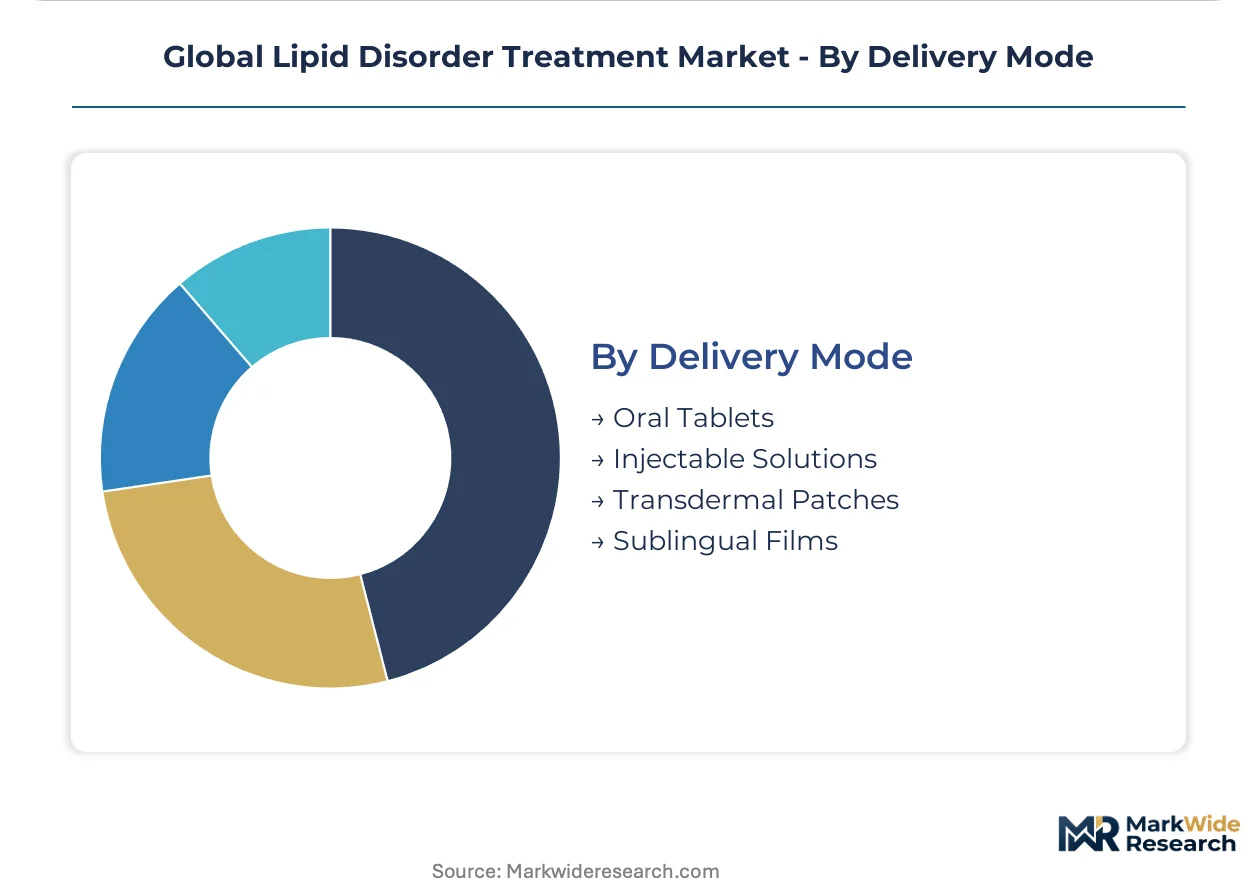
Supply concentration and cold-chain requirements create sharp access boundaries between administration settings.
- Oral Tablets:Small-molecule formulations enable broad primary care access without specialized infrastructure. United States retail pharmacy networks handle the majority of statin and fibrate dispensing, with mail-order channels capturing maintenance therapy refills.
- Injectable Solutions:Biologic therapies require temperature-controlled distribution and administration supervision that limits rural penetration. Japan's PMDA-mandated ethnic bridging studies have concentrated PCSK9 inhibitor launch sequencing in urban specialty hospitals with established cold-chain partnerships.
- Transdermal Patches:Alternative absorption routes for niacin derivatives serve compliance-challenged populations in outpatient settings.
- Sublingual Films:Rapid-dissolve formulations for acute lipid management remain limited to hospital emergency protocols.
Oral tablets dominate patient reach. Injectable solutions command disproportionate revenue per treated patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in lipid disorder therapies reflect concentrated manufacturing in Switzerland and Ireland against dominant consumption in the United States, Germany, and Japan. Specialty biologics move through temperature-controlled corridors while oral generics circulate through decentralized pharmacy networks.
United States
FDA cardiovascular outcome trial mandates extend development timelines for novel mechanisms, channeling investment toward sponsors with established adjudication infrastructure. Integrated delivery networks in Texas and California now negotiate PCSK9 inhibitor formularies at system level, displacing wholesale distribution for severe hypercholesterolemia cases. The Cleveland Clinic and Mayo Clinic anchor specialty hospital procurement authority for familial cases.
Germany
EMA pharmacovigilance frameworks accelerate hospital formulary adoption of injectable biologics through enhanced prescriber confidence. Cardiology clusters in Bavaria and North Rhine-Westphalia are expanding in-house infusion capabilities, creating direct-to-physician channels that bypass pharmacy benefit managers. National cholesterol screening programs drive systematic patient identification across statutory health insurance pools.
Japan
PMDA ethnic bridging study requirements add 18-24 months to development timelines, concentrating launch sequencing in Tokyo and Osaka academic medical centers with established cold-chain partnerships. Severe familial hypercholesterolemia cases cluster in Kanto region specialty hospitals. The country's aging demographic expands addressable pools for combination therapies beyond statin monotherapy.
Switzerland
Contract manufacturing concentration for injectable PCSK9 inhibitors creates supply vulnerability amid limited production sites. Swissmedic regulatory alignment with EMA standards facilitates parallel market access negotiations. Basel and Zurich anchor biologic production clusters serving European hospital networks.
United Kingdom
NICE cost-effectiveness thresholds complicate reimbursement for premium biologics against generic statin comparators. London and Manchester cardiology clinics pilot polygenic risk scoring protocols that identify mixed dyslipidemia earlier. Post-authorization studies now dominate evidence generation requirements for formulary inclusion.
Global Lipid Disorder Treatment Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates commanding cardiovascular outcome trial infrastructure and biologic manufacturing scale. Three archetypes define competitive positioning: statin volume leaders leveraging generic manufacturing depth, PCSK9 biologic specialists concentrating on specialty hospital channels, and emerging oral small-molecule developers targeting primary care access. Dominant competitive moves include strategic partnerships for RNA interference platform access and geographic expansion through integrated delivery network contracting.
Among diversified pharmaceutical conglomerates, Pfizer anchors statin volume leadership through manufacturing scale across oral formulation networks, while Novartis and AstraZeneca occupy positions bridging small-molecule and biologic portfolios. Amgen and Regeneron Pharmaceuticals exemplify the biologic specialist archetype with concentrated R&D intensity in injectable LDL receptor recycling platforms. Sanofi represents European market access anchoring through established cardiology clinic relationships.
| Leading Market Players |
|---|
| Pfizer |
| Novartis AG |
| Merck & Co. |
| AstraZeneca |
| Amgen |
| Regeneron Pharmaceuticals |
| Sanofi |
| AbbVie |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between specialty hospitals and biologic manufacturers lock in multi-year supply access while stabilizing unit cost visibility against volatile cold-chain logistics. These contracts concentrate procurement power among German and Japanese cardiology clusters, compressing margin flexibility for injectable PCSK9 inhibitor suppliers.
Pricing Analysis
Specialty hospital buyers anchor three-tier pricing structure across premium biologic, standard combination, and economy generic statin levels. Price differentiation rests on FDA cardiovascular outcome trial certification status and volume scale through integrated delivery networks. Pricing pressure stems from generic atorvastatin substitution in primary prevention populations. Retail pharmacy channels exhibit highest price sensitivity; specialty hospital formulary committees demonstrate lowest sensitivity due to protocol-driven therapy selection.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp pharmaceutical corridors and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for temperature-sensitive biologics. Manufacturing concentrates in Switzerland, Ireland, and the United States. Raw material dependencies include monoclonal antibody cell lines, sterile filtration membranes, and pharmaceutical-grade excipients. Single-source vulnerability permeates PCSK9 inhibitor fill-finish capacity. Distribution runs through specialty hospital direct contracting and wholesale pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as polygenic risk scoring fragments patient identification across diagnostic laboratories, cardiology clinics, and primary care networks, creating niche positioning for targeted therapy developers.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into active pharmaceutical ingredient production in Switzerland and Ireland. Secure cardiovascular outcome trial infrastructure against emerging oral small-molecule substitutes. Prioritize formulary lock-in with German integrated delivery networks before channel consolidation completes. For New Entrants and Emerging Players: Patient adherence monitoring services represent an under-served layer where incumbents lack dedicated platforms. Severe hypertriglyceridemia offers the most penetrable therapy area with no approved biologic competition. Deploy direct-to-physician distribution through German cardiology clinic infusion centers to bypass established pharmacy benefit manager relationships. For Investors and Strategic Acquirers: Capital is best deployed toward RNA interference platform specialists with Phase III cardiovascular outcome data and existing specialty hospital contracts. Long-term viability favors developers with demonstrated LDL-C suppression durability and semi-annual dosing regimens. Watch for FDA guidance shifts on surrogate endpoint acceptability as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | FDA-mandated MACE studies extend timelines but secure premium reimbursement positioning for novel mechanisms. |
| Oral Small-Molecule Development | Non-injectable PCSK9 programs unlock primary care channel access currently blocked by cold-chain requirements. |
| Specialty Hospital Direct Contracting | Bypassing pharmacy benefit managers captures margin pools in severe familial hypercholesterolemia cases. |
| RNA Interference Platform Licensing | Extended-interval dosing reduces clinic visit burden while maintaining LDL-C suppression economics. |
| Polygenic Risk Score Integration | Diagnostic laboratory partnerships enable earlier mixed dyslipidemia identification before first cardiovascular events. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population estimates and top-down revenue triangulation cross-checked segmentation outputs.
Sensitivity analysis tested forecast robustness across LDL-C target guideline scenarios and reimbursement threshold variations. Segmentation dimensions modeled include product type, therapy area, delivery mode, end user, and regional regulatory cluster. CAGRs derived from event-driven study timeline assumptions and biologic adoption curve parameters. Forecast inputs incorporated cardiovascular outcome trial completion probabilities and specialty hospital formulary expansion rates.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA frameworks; material policy shifts on cardiovascular outcome requirements or ethnic bridging mandates would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market