
 Asia-Pacific Over-The-Counter (OTC) Drugs Market | 2026-2036
Asia-Pacific Over-The-Counter (OTC) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Over-The-Counter (OTC) Drugs Market Outlook
Pharmaceutical-grade formulation standards is bifurcating the Asia-Pacific OTC drugs landscape into premium-certified and mass-market tiers. GlaxoSmithKline leverages its respiratory portfolio to anchor shelf presence across Southeast Asian pharmacy chains. Johnson & Johnson sustains brand trust through dermatological and pediatric OTC lines with established quality certifications. Takeda Pharmaceutical Company dominates gastrointestinal OTC segments in Japan and extends its reach through localized manufacturing partnerships.
Over-the-counter drugs are non-prescription pharmaceutical products containing active ingredients at dosages deemed safe for self-administration without physician supervision, typically manufactured through direct compression or wet granulation processes for tablet and capsule forms. Their primary commercial purpose is to enable consumers to treat minor ailments, manage chronic symptoms, and reduce healthcare system burdens through accessible self-care. Pain relievers command the largest revenue pool across the region due to high frequency of musculoskeletal complaints and headache disorders among aging workforces. Online retail represents the fastest-expanding sales channel, driven by pharmacy app proliferation and regulatory acceptance of telepharmacy consultations in markets like South Korea and Australia.
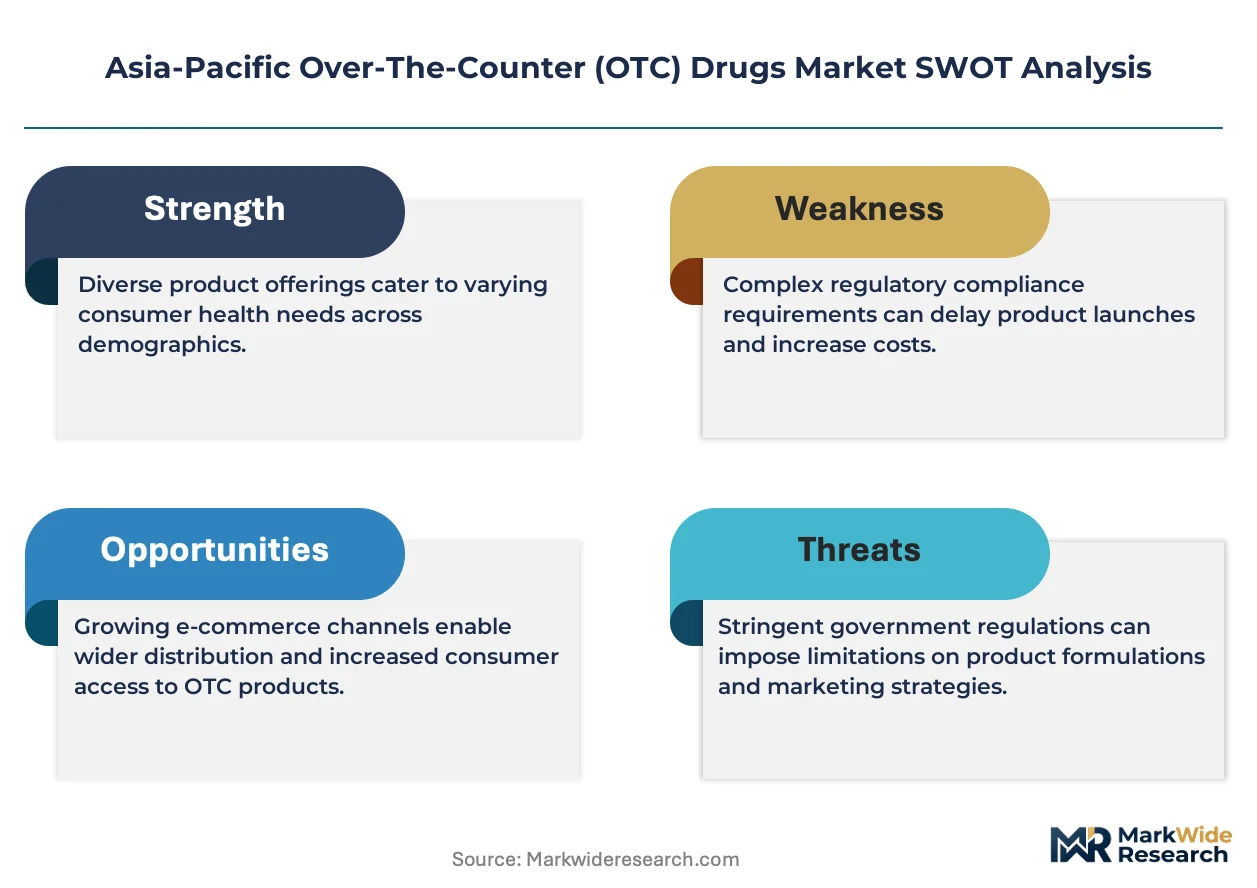
Japan's PMDA maintains stringent stability-testing requirements for OTC switch applications, while Australia's TGA enforces complementary medicine labeling rules that shape product claims and packaging formats across the region. India's CDSCO has accelerated OTC categorization reforms under its Drugs and Cosmetics Act amendments, creating clearer pathways for prescription-to-OTC switches. China's NMPA integrates traditional medicine ingredients into its OTC monograph system, influencing formulation strategies for both domestic and multinational manufacturers. Stakeholders must monitor evolving switch regulations and e-pharmacy compliance frameworks to capture positioning in markets where digital distribution and self-care autonomy are converging.
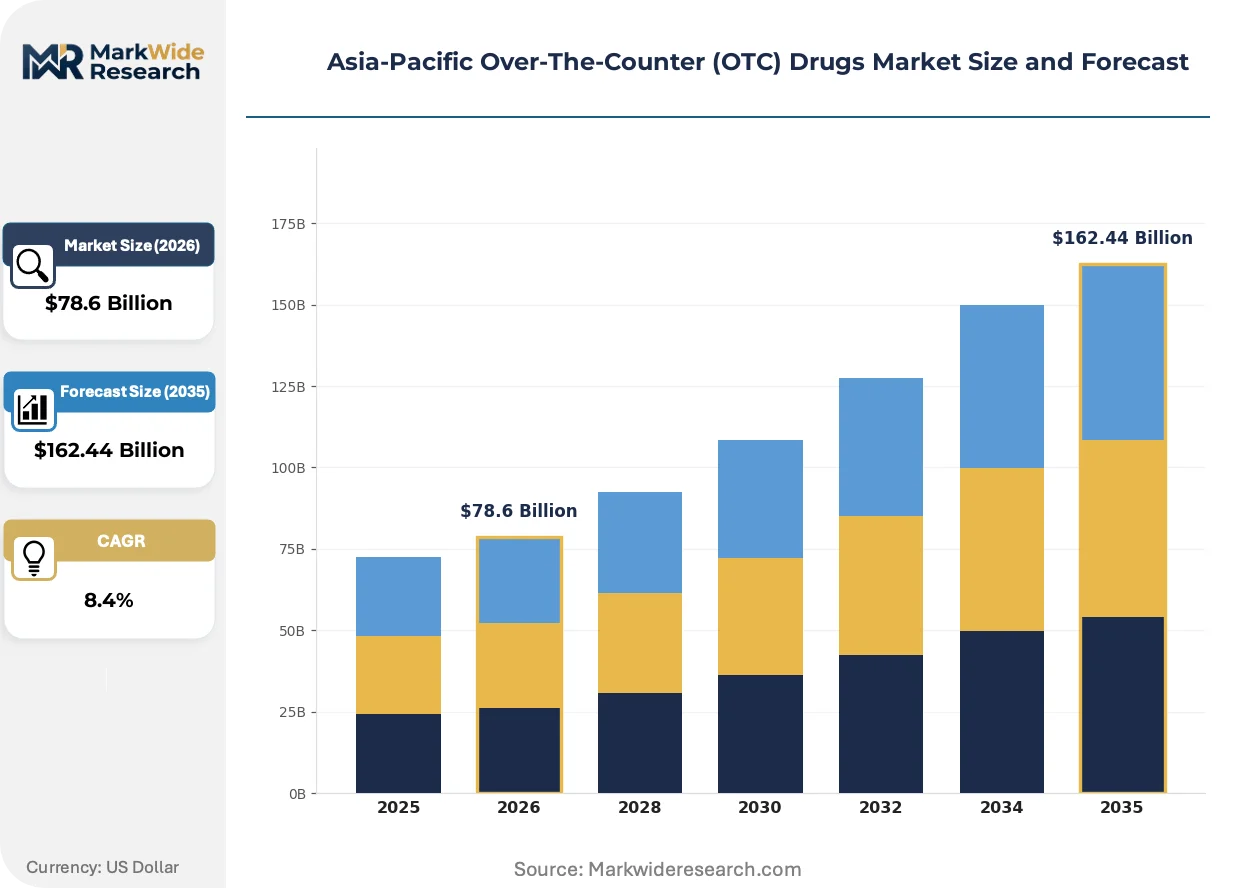
Market Dynamics
Self-medication autonomy among Asia-Pacific working-age adults is compressing traditional pharmacy visit patterns and elevating digital-first purchase behaviors across urban corridors. CDSCO's OTC categorization reforms and TGA's labeling mandates are simultaneously expanding accessible product categories while raising compliance barriers for new formulation entrants.
Growth Catalysts
- Telepharmacy Regulatory Acceptance:South Korea's MFDS and Australia's TGA have formalized remote consultation frameworks, enabling pharmacy apps to dispense non-prescription analgesics without physical counter visits.
- India's Tier-2 Manufacturing Clusters:Pharmaceutical production is concentrating around Hyderabad and Ahmedabad, generating economies of scale for generic OTC tablet and capsule output destined for Southeast Asian export markets.
- Prescription-to-OTC Switch Pathways:Japan's PMDA has streamlined stability-testing protocols for certain analgesic categories, accelerating commercial availability of formerly restricted formulations.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70 percent of paracetamol and ibuprofen raw material supply originates from Chinese chemical manufacturers, creating vulnerability to export quota fluctuations.
- Labeling Compliance Cost Escalation:Australia's TGA complementary medicine rules and India's CDSCO amendment requirements impose multilingual packaging obligations that disproportionately burden mid-scale entrants.
- Traditional Medicine Substitution:China's NMPA-registered herbal preparations compete directly with synthetic OTC categories for gastrointestinal and respiratory symptom management.
Strategic Opportunities
- Vietnam's Underpenetrated Pharmacy Networks:Provincial cities outside Hanoi and Ho Chi Minh City lack organized retail pharmacy coverage, creating first-mover potential for e-pharmacy platforms with cold-chain logistics.
- Pediatric Formulation Gaps:Dissolvable tablet and liquid suspension formats for children remain underserved across Indonesia and Philippines, where birth rates sustain addressable demand pools.
- Cross-Border E-Commerce Corridors:China's NMPA has piloted bonded zone clearance mechanisms for OTC imports through Hainan and Guangdong digital pharmacy channels.
Industry Challenges
- Pharmaceutical Formulation Talent Scarcity:Southeast Asian markets face acute shortages of stability-testing specialists capable of meeting PMDA and TGA documentation standards for OTC switch applications.
- Legacy Distribution System Integration:Wholesaler networks in India and Indonesia resist direct-to-consumer platform adoption, requiring hybrid fulfillment architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Over-The-Counter (OTC) Drugs Market |
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $162.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cough and Cold Medications, Digestive Aids, Allergy Medications Sales Channel: Pharmacies, Supermarkets, Online Retail, Convenience Stores End User: Adults, Children, Elderly, Athletes Application: Self-Medication, Preventive Care, Symptom Relief, Health Maintenance |
| Companies Covered | GlaxoSmithKline, Johnson & Johnson, Novartis, Bayer, Pfizer, Sanofi, Takeda Pharmaceutical Company, Reckitt Benckiser, Kalbe Farma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Over-The-Counter (OTC) Drugs Market Strategic Shifts
Digitally-enabled self-diagnosis tools and portable diagnostic peripherals are rewiring how Asia-Pacific consumers identify ailments and select corresponding OTC interventions. Formulation science and packaging engineering are converging to serve mobile-first purchasing patterns.
Blister packaging with embedded NFC authentication chips is miniaturizing anti-counterfeiting infrastructure for high-value respiratory and dermatological OTC lines. Pharmacy chains in Singapore and urban China are deploying these verification layers at scale. The technology is compressing trust-building timelines for new market entrants competing against established brand portfolios.
Japan's PMDA has implemented post-market surveillance mandates requiring real-world adverse event reporting for all switched OTC products, fundamentally altering lifecycle management obligations. Manufacturers must now maintain pharmacovigilance infrastructure equivalent to prescription drug standards. This regulatory compression is filtering formulation investment toward lower-risk therapeutic categories with cleaner safety profiles.
Subscription-based replenishment models for chronic symptom management are displacing episodic pharmacy visits among Australia's aging workforce and South Korea's office-employee segments. Pharmacy apps bundle automated delivery with dosage reminders, capturing recurring revenue streams. This behavioral shift is most pronounced in metropolitan Sydney, Melbourne, Seoul, and Busan corridors where smartphone penetration and logistics density enable seamless execution.
Asia-Pacific Over-The-Counter (OTC) Drugs Market Segmentation
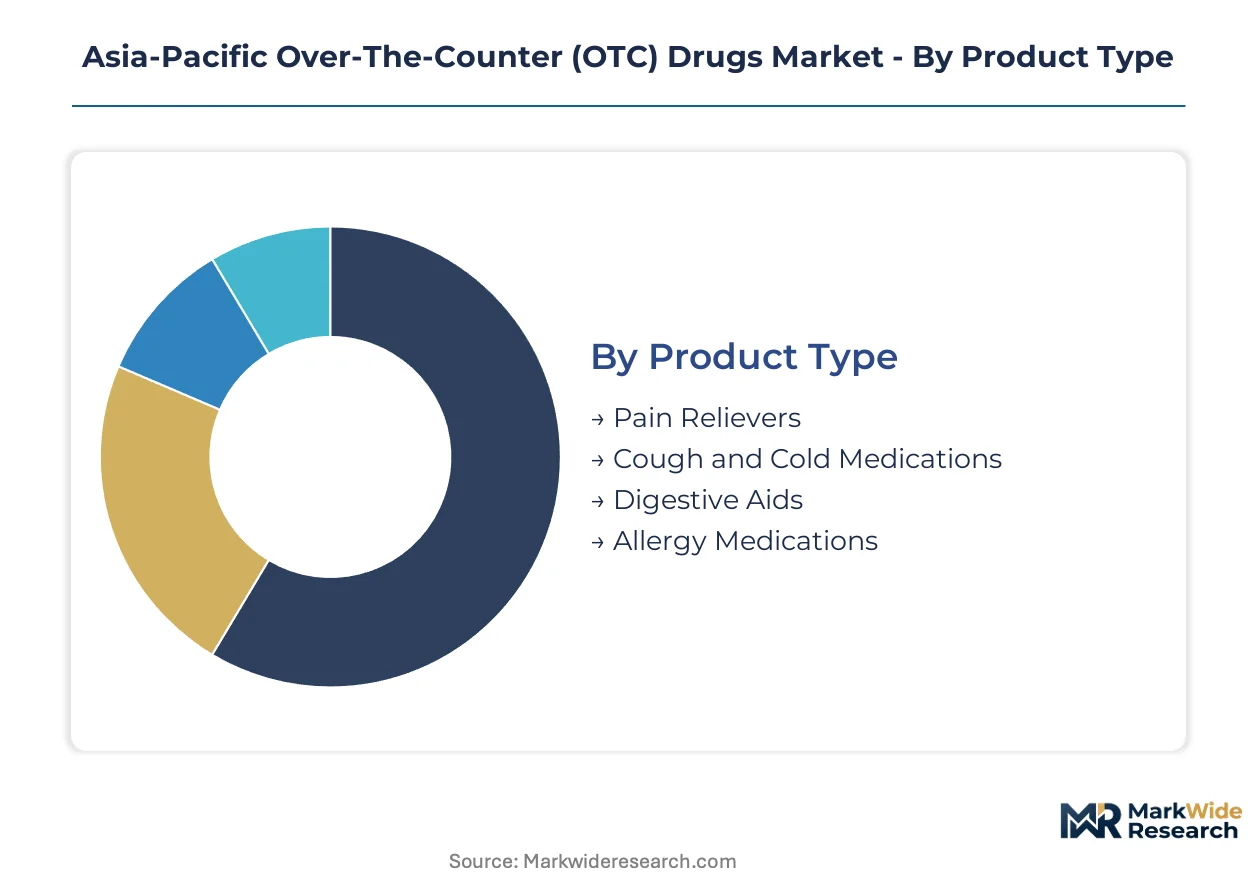
OTC drug segmentation across Asia-Pacific reflects divergent regulatory pathways for self-administered therapeutics. India's CDSCO categorization reforms and Australia's TGA labeling mandates create tiered compliance burdens that reshape competitive positioning across product categories and distribution channels.
Product Type:
Regulatory differentiation separates prescription-to-OTC switch candidates from legacy non-prescription categories, with stability-testing requirements from Japan's PMDA and China's NMPA determining which formulations achieve commercial scale.
- Pain Relievers:Non-steroidal anti-inflammatory drugs and acetaminophen-based formulations manufactured through direct compression processes dominate manufacturing output across India's Hyderabad and Ahmedabad clusters. Demand concentrates among aging workforces in Japan and South Korea where musculoskeletal complaints drive repeat purchase frequency, though API supply concentration in Chinese chemical manufacturers creates vulnerability to export quota fluctuations.
- Cough and Cold Medications:Respiratory symptom management products face heightened scrutiny under Australia's TGA complementary medicine rules and China's NMPA-registered herbal preparation competition. Southeast Asian pharmacy chains anchor shelf presence for these seasonal categories, with GlaxoSmithKline leveraging portfolio breadth to secure retail positioning across urban corridors.
- Digestive Aids:Gastrointestinal OTC segments command established manufacturing partnerships in Japan where Takeda Pharmaceutical Company extends localized production reach.
- Allergy Medications:Antihistamine formulations compete against traditional medicine substitutes in Chinese markets under NMPA monograph integration policies.
Pain Relievers handles the majority of throughput; Online Retail through pharmacy apps is the fastest mover on share.
Sales Channel:
Channel economics stratify around fulfillment infrastructure investment, with cold-chain logistics capabilities and telepharmacy regulatory acceptance determining which platforms capture working-age adult self-medication autonomy.
- Pharmacies:Licensed retail outlets across South Korea and Australia now operate under formalized remote consultation frameworks from MFDS and TGA, enabling digital-first dispensing without physical counter visits while maintaining compliance documentation.
- Supermarkets:Mass-market shelf space for analgesic and dermatological lines concentrates in Australia's Coles and Woolworths networks, with Johnson & Johnson sustaining brand trust through quality certification visibility.
- Online Retail:Pharmacy app proliferation in South Korea and subscription-based replenishment models in Australia's Sydney and Melbourne corridors capture recurring revenue through automated delivery with dosage reminders.
- Convenience Stores:24-hour accessibility in Japan's urban centers and Southeast Asian transit hubs serves episodic symptom management for commuter populations.
Pharmacies retain the dominant share of transaction volume; Online Retail is expanding most quickly as telepharmacy frameworks mature.
End User:
Demographic targeting shapes formulation specifications, with pediatric and elderly segments imposing distinct stability-testing and packaging compliance obligations under PMDA and TGA documentation standards.
- Adults:Working-age populations across Southeast Asian urban centers drive self-medication autonomy trends, compressing traditional pharmacy visit patterns through smartphone-enabled diagnosis and purchase behaviors.
- Children:Dissolvable tablet and liquid suspension formats remain underserved across Indonesia and Philippines where birth rates sustain addressable demand pools, creating formulation gaps for entrants with pediatric-specific manufacturing capabilities.
- Elderly:Chronic symptom management requirements in Japan and Australia's aging workforces sustain subscription-based replenishment adoption through pharmacy app bundling.
- Athletes:Sports-specific analgesic and topical anti-inflammatory demand concentrates in South Korea's fitness culture and Australia's organized athletics participation.
Adults generate the highest absolute transaction volume; Children represents the steepest expansion trajectory as pediatric formulation investments accelerate.
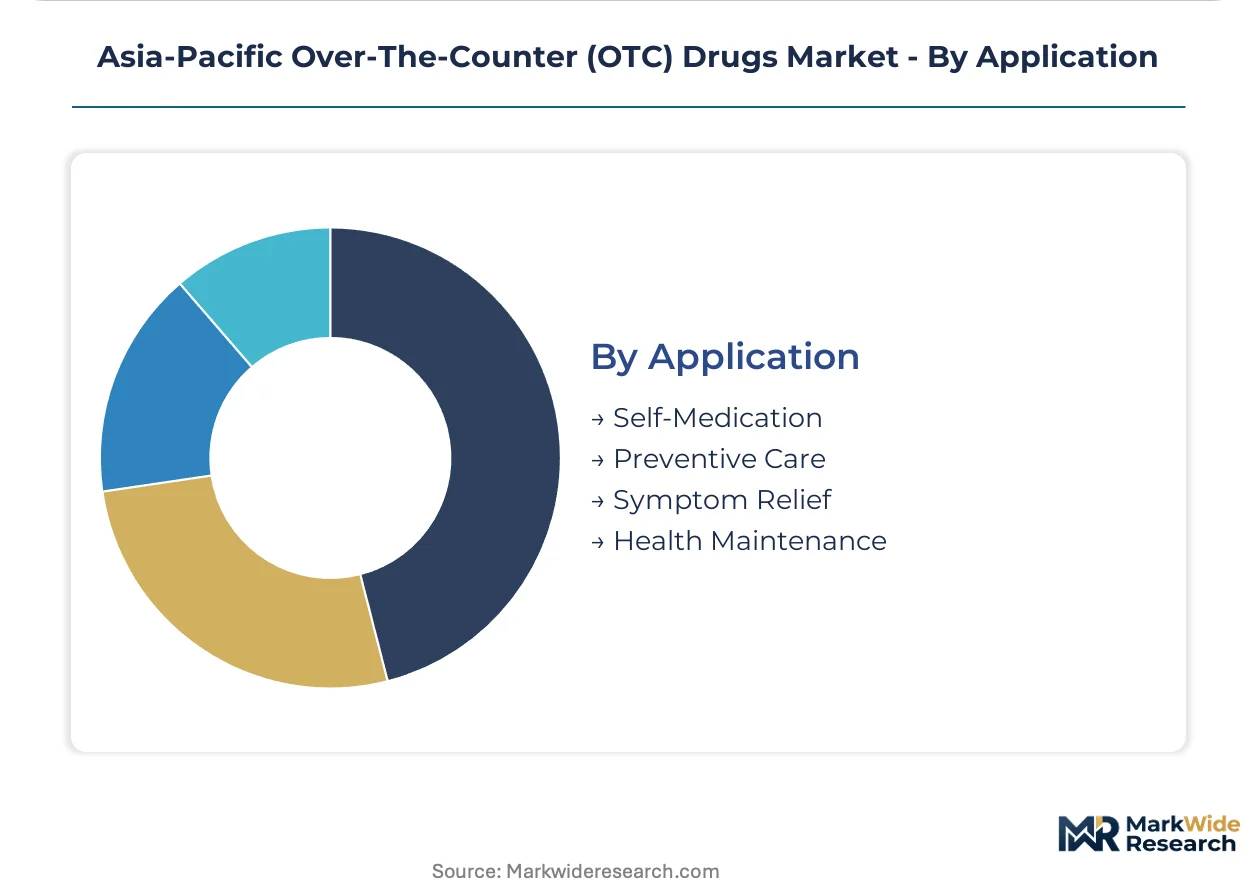
Application:
Usage intent determines packaging engineering and dosage form selection, with preventive care and health maintenance applications requiring distinct shelf-life validation compared to acute symptom relief categories.
- Self-Medication:Consumer-directed treatment of minor ailments without physician supervision anchors the commercial purpose of OTC categories, with China's NMPA and India's CDSCO creating clearer prescription-to-OTC switch pathways under recent amendments.
- Preventive Care:Proactive health maintenance formulations face competition from traditional medicine substitutes in Chinese markets where herbal preparations compete for gastrointestinal and respiratory symptom management positioning.
- Symptom Relief:Acute intervention for headache disorders and musculoskeletal complaints drives pain reliever category concentration among aging workforces.
- Health Maintenance:Long-term wellness product adoption correlates with Australia's subscription-based replenishment model penetration and South Korea's office-employee smartphone utilization patterns.
Self-Medication commands the foundational revenue base; Preventive Care is gaining share fastest as wellness positioning reshapes marketing investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across the Asia-Pacific OTC drugs landscape reveal concentrated API sourcing from Chinese chemical manufacturers balanced against formulation and packaging capabilities in India, Japan, and Australia. Trade flows in finished dosage forms increasingly favor regional hub-and-spoke distribution models.
China
Domestic demand for gastrointestinal and respiratory OTC categories competes against traditional medicine substitutes under NMPA monograph integration policies. The regulator's bonded zone clearance pilots in Hainan and Guangdong enable cross-border e-pharmacy imports. Manufacturing concentrates in Yangtze River Delta chemical corridors supplying paracetamol and ibuprofen APIs to regional formulation plants.
India
Tier-2 pharmaceutical clusters around Hyderabad and Ahmedabad generate economies of scale for generic tablet and capsule output destined for Southeast Asian markets. CDSCO's accelerated OTC categorization reforms under Drugs and Cosmetics Act amendments clarify prescription-to-OTC switch pathways. Export-oriented production from Gujarat-based facilities supplies regulated markets in Australia and South Africa.
Japan
Aging workforce demographics sustain chronic symptom management demand through subscription-based pharmacy app models in Tokyo and Osaka corridors. PMDA maintains stringent stability-testing requirements for OTC switch applications with post-market surveillance mandates equivalent to prescription drug standards. Kanto region formulation specialists face talent scarcity for documentation-intensive regulatory submissions.
Australia
Telepharmacy regulatory acceptance under TGA frameworks enables remote consultation and dispensing without physical pharmacy visits. Complementary medicine labeling rules impose multilingual packaging obligations that reshape product claims across Coles and Woolworths retail networks. Melbourne and Sydney logistics density supports automated replenishment execution for aging workforce segments.
South Korea
MFDS formalized remote consultation frameworks accelerate pharmacy app proliferation for non-prescription analgesic dispensing. Seoul and Busan metropolitan corridors exhibit highest smartphone-enabled self-diagnosis and purchase compression. Fitness culture drives sports-specific topical anti-inflammatory demand distinct from general pain reliever categories.
Asia-Pacific Over-The-Counter (OTC) Drugs Market Competitive Environment
Concentration sits with multinational pharmaceutical conglomerates possessing respiratory and dermatological portfolio breadth alongside established quality certification visibility. The competitive structure tiers between premium-certified formulation specialists and mass-market generic manufacturers. Three archetypes dominate: science-driven switch specialists, brand-trust incumbents with pediatric lines, and scale-oriented API-integrated formulators. Dominant competitive moves include strategic partnerships for localized manufacturing access and portfolio diversification into subscription-based chronic care models.
Within the multinational tier, GlaxoSmithKline and Johnson & Johnson exemplify divergent positioning strategies. GlaxoSmithKline anchors shelf presence through respiratory portfolio depth across Southeast Asian pharmacy chains. Johnson & Johnson occupies a position emphasizing dermatological and pediatric line trust transmission through visible quality certifications. Takeda Pharmaceutical Company represents the regional specialist archetype with gastrointestinal segment concentration and Japanese market embeddedness.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Johnson & Johnson |
| Novartis |
| Bayer |
| Pfizer |
| Sanofi |
| Takeda Pharmaceutical Company |
| Reckitt Benckiser |
| Kalbe Farma |
| Others |
Value Chain & Pricing Dynamics
Paracetamol and ibuprofen API substitution from Indian contract manufacturers is displacing Chinese chemical supplier dominance while simultaneously compressing landed costs for Southeast Asian formulators and redrawing procurement geography toward Hyderabad and Ahmedabad production clusters.
Pricing Analysis
Pharmacy chains and e-pharmacy platforms anchor a three-tier pricing structure across premium-certified, standard-formulation, and economy-generic levels. Price differentiation hinges on TGA and PMDA certification tier and volume procurement scale from tier-2 manufacturing clusters. Cost compression in economy-tier analgesics is intensifying because of API oversupply from Indian generic producers. Hospital procurement committees exhibit highest price sensitivity; premium dermatological lines for pediatric segments show lowest.
Supply Chain Analysis
Strategic stockpiling of respiratory API inputs dominates inventory strategy ahead of seasonal demand surges, contrasting with just-in-time replenishment for chronic pain reliever categories. Active pharmaceutical ingredient supply concentrates in China and India, with formulation finishing in Japan and Australia. Paracetamol, ibuprofen, and excipient inputs feed from Yangtze River Delta chemical corridors. Single-source vulnerability from Chinese API export quotas threatens regional tablet output. Distribution runs through hybrid wholesaler-platform fulfillment architectures in India and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telepharmacy platform interoperability between South Korea's MFDS-registered apps and Australia's TGA frameworks is creating cross-border prescription-to-OTC switch data liquidity, transforming competitive moats from brand recognition into ecosystem integration depth.
For Market Incumbents: Shield respiratory portfolio shelf presence through NFC-enabled blister packaging investments that compress trust-building timelines for new entrants. Anchor localized manufacturing partnerships in Vietnam's underpenetrated provincial corridors before e-pharmacy platforms establish cold-chain dominance. Certification investment in PMDA stability-testing documentation remains the critical lever against mid-scale generic challengers.
For New Entrants and Emerging Players: Pediatric dissolvable tablet formulation gaps in Indonesia and Philippines represent the most penetrable white-space target, where birth rates sustain demand pools underserved by incumbent liquid suspension portfolios. Subscription-based chronic symptom management for Australia's aging workforce offers second entry angle. Go-to-market execution should prioritize direct-to-consumer pharmacy app partnerships over legacy wholesaler integration.
For Investors and Strategic Acquirers: Capital is best deployed toward API-integrated formulators with captive paracetamol and ibuprofen supply from Indian tier-2 clusters. Long-term viability over the projection horizon rests on regulatory switch pathway expertise and telepharmacy platform interoperability capabilities. Watch for MFDS-TGA mutual recognition agreement progress as inflection indicator for cross-border digital pharmacy consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Switch Pathway Investment | PMDA stability-testing documentation accelerates prescription-to-OTC commercial availability timelines. |
| Telepharmacy Platform Integration | MFDS and TGA framework interoperability enables remote consultation revenue capture in Seoul and Sydney corridors. |
| Pediatric Formulation Capacity Addition | Dissolvable tablet manufacturing in Indonesia addresses birth-rate-sustained demand pools underserved by incumbents. |
| API Backward Integration | Captive paracetamol supply from Hyderabad clusters insulates against Chinese export quota volatility. |
| NFC Authentication Packaging Deployment | Embedded chip blister packs compress trust-building timelines for respiratory line market entry. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of CDSCO regulatory filings, TGA complementary medicine registers, NMPA OTC monograph updates, and pharmaceutical customs data. Primary interviews engaged regulatory affairs leads at multinational formulators, pharmacy chain procurement directors, telepharmacy platform operators, and API contract manufacturing executives. Secondary validation drew from PMDA adverse event surveillance reports, MFDS remote consultation framework documents, and India Drugs and Cosmetics Act amendment records. Bottom-up volume triangulation across dosage form categories was cross-checked against top-down regional demand aggregation.
Segmentation dimensions modeled span product type, sales channel, end user demographic, and application intent across the projection horizon. Analytical framework derived CAGRs through regression of historical switch pathway approval timelines against telepharmacy regulatory acceptance trajectories. Industry-specific forecast inputs incorporated API price volatility indices from Chinese chemical export data and pharmacy app penetration rates from South Korean and Australian digital health surveys.
Underlying assumptions cover sustained telepharmacy regulatory harmonization and API supply continuity from Indian tier-2 clusters, with deviation risk concentrated in PMDA-TGA documentation standard divergence and Chinese export quota policy shifts. Revision becomes warranted when cross-border e-pharmacy bonded zone clearance mechanisms stall or API concentration thresholds breach single-source dependency thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Isotretinoin Drugs Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Global Anesthesia Drugs Market