
 Ulnar Nerve Treatment Market | 2026-2036
Ulnar Nerve Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ulnar Nerve Treatment Market Outlook
Outpatient surgical migration is repositioning how ulnar nerve interventions are delivered across health systems. Pfizer leverages its neurology portfolio breadth to sustain formulary positioning for perioperative pain management in nerve decompression protocols. Johnson & Johnson anchors its presence through orthopedic and surgical instruments that support minimally invasive transposition techniques. Teva Pharmaceuticals competes on generic analgesic and anti-inflammatory supply to cost-sensitive ambulatory settings.
Ulnar nerve treatment encompasses surgical decompression, transposition, and medical management of entrapment neuropathies affecting the cubital tunnel and Guyon's canal, typically involving nerve conduction velocity thresholds below 50 meters per second for diagnostic confirmation. The primary purpose is restoration of sensory and motor function while preventing irreversible axonal loss. Surgery and medication segments dominate current revenue pools, though telehealth delivery modes represent the fastest structural expansion as remote postoperative monitoring and rehabilitation coaching reduce readmission exposure. Procedure-type segmentation shows decompression maintaining volume leadership while transposition commands premium pricing due to technical complexity and longer operative time.
FDA device clearance requirements and CMS procedural coding decisions directly shape which interventions achieve scalable reimbursement in US ambulatory settings. ISO 13485 quality management standards govern surgical instrument manufacturing for nerve procedures, creating compliance barriers for new instrument suppliers. State-level certificate-of-need regulations in concentrated US markets constrain ambulatory center expansion, preserving hospital leverage in specific geographies. Stakeholders must monitor whether payer preference shifts toward bundled payments for complete episodes of ulnar nerve care will reshape site-of-service economics and technology procurement criteria.
Market Dynamics
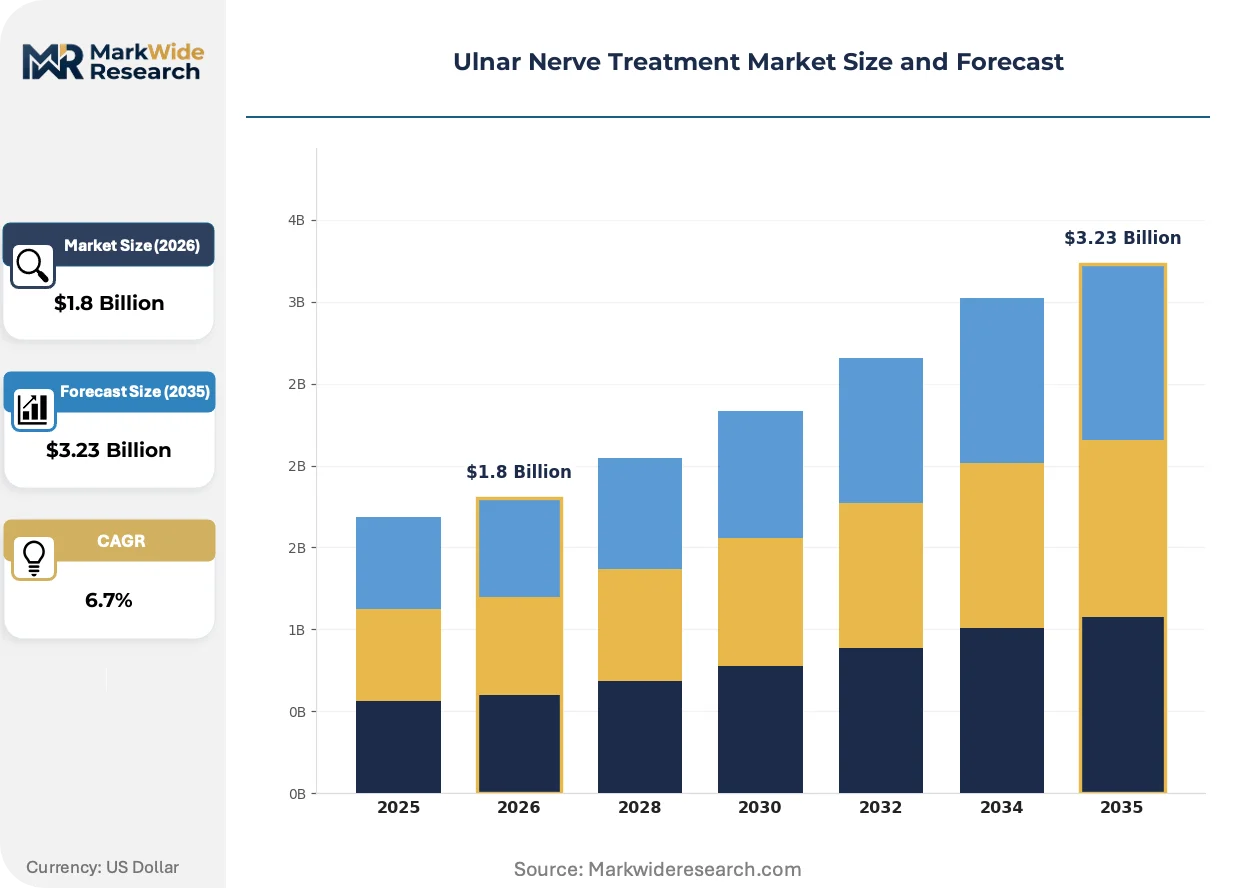
Outpatient migration of ulnar nerve procedures is compressing traditional hospital revenue models while expanding ambulatory surgical center capacity. CMS reimbursement recalibration for same-day nerve decompression is accelerating site-of-service displacement faster than infrastructure adaptation.
Growth Catalysts
- CMS Outpatient Prospective Payment System expansion:Reimbursement parity for cubital tunnel release performed in ambulatory settings draws surgical volume away from inpatient facilities. ASCs in Texas and Florida report capacity additions specifically targeting nerve entrapment cases.
- Endoscopic decompression instrumentation:Smaller incision profiles reduce operative time and postsurgical morbidity. Surgeons trained in minimally invasive techniques convert open transposition volume to endoscopic release at accelerating rates.
- Ambulatory surgical center certificate-of-need deregulation:States including Arizona and Nevada eliminated CON requirements, permitting rapid facility expansion where hospital systems previously held geographic monopolies on nerve procedures.
Market Restraints
- Specialized microsurgical instrument supply concentration:German and Japanese manufacturers control premium nerve retractor and decompression tool production. Tariff exposure and single-source dependencies create procurement vulnerability for US ASCs.
- FDA 510(k) clearance timelines for novel nerve conduits:Bioresorbable synthetic grafts face extended premarket notification review periods. Device developers absorb 18-24 month regulatory delays before commercial ambulatory deployment.
- Physical therapy substitution for mild entrapment:Conservative management with splinting and nerve gliding protocols captures early-stage cubital tunnel cases before surgical candidacy. Orthopedic practices report 30-40% of referred patients triaged to non-operative pathways.
Strategic Opportunities
- Telehealth-enabled remote postoperative monitoring:Wearable sensors tracking grip strength and sensory recovery reduce geographic barriers to specialized follow-up. Rural patients in Montana and Wyoming access urban nerve specialists through asynchronous video assessment platforms.
- Biologic nerve wrap adoption in revision surgery:Acellular dermal matrices and amniotic membrane products address scarred recurrent entrapment cases. Product differentiation concentrates in high-complexity tertiary referral centers.
- India's medical tourism infrastructure for nerve reconstruction:Cost arbitrage for complex transposition and grafting procedures attracts self-pay patients from Gulf states and Southeast Asia. Mumbai and Chennai facilities market bundled surgical packages below US deductible thresholds.
Industry Challenges
- Peripheral nerve surgery fellowship pipeline constraints:Accredited training positions produce fewer than 50 new hand and peripheral nerve specialists annually. Community hospitals compete for limited talent through recruitment incentives and equipment capital commitments.
- ISO 13485 quality management system implementation costs:Domestic instrument startups face $400,000-$600,000 initial certification investments. Compliance timelines extend 12-18 months before commercial manufacturing authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ulnar Nerve Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Medication, Therapy, Rehabilitation Delivery Mode: In-hospital, Outpatient, Homecare, Telehealth End User: Clinics, Hospitals, Rehabilitation Centers, Home Care Providers Procedure Type: Carpal Tunnel Release, Ulnar Nerve Transposition, Decompression, Surgical Repair |
| Companies Covered | Teva Pharmaceuticals, Pfizer, Johnson & Johnson, GSK, Bayer, Endo International, Allied Chemicals & Pharmaceuticals, Saol Therapeutics, Apotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ulnar Nerve Treatment Market Strategic Shifts
Minimally invasive technique maturation is redistributing surgical competence across provider types while compressing recovery expectations. Technology convergence between imaging, instrumentation, and biologics is creating new intervention categories at the boundary between conservative and operative management.
Ultrasound-guided hydrodissection is decentralizing diagnostic and therapeutic nerve procedures from operating rooms to office-based settings. Hand surgeons and physiatrists adopt portable high-frequency transducers for real-time cubital tunnel visualization. The technique enables same-visit intervention without facility fees, compressing revenue per case while expanding access volume.
FDA breakthrough device designation pathways for nerve regeneration products are compressing premarket review timelines for qualified innovations. Biologic conduit manufacturers submit rolling data packages rather than complete premarket approval applications. The policy shift advantages sponsors with existing orthopedic biologics portfolios over de novo entrants.
Patient-directed scheduling through direct-to-ambulatory-center referral platforms is fragmenting traditional physician-hospital alignment. Self-referred individuals in Colorado and Washington research nerve entrapment symptoms online and book ASC consultations without primary care gatekeeping. This behavioral shift pressures specialists to maintain digital presence and transparent pricing disclosure.
Ulnar Nerve Treatment Market Segmentation
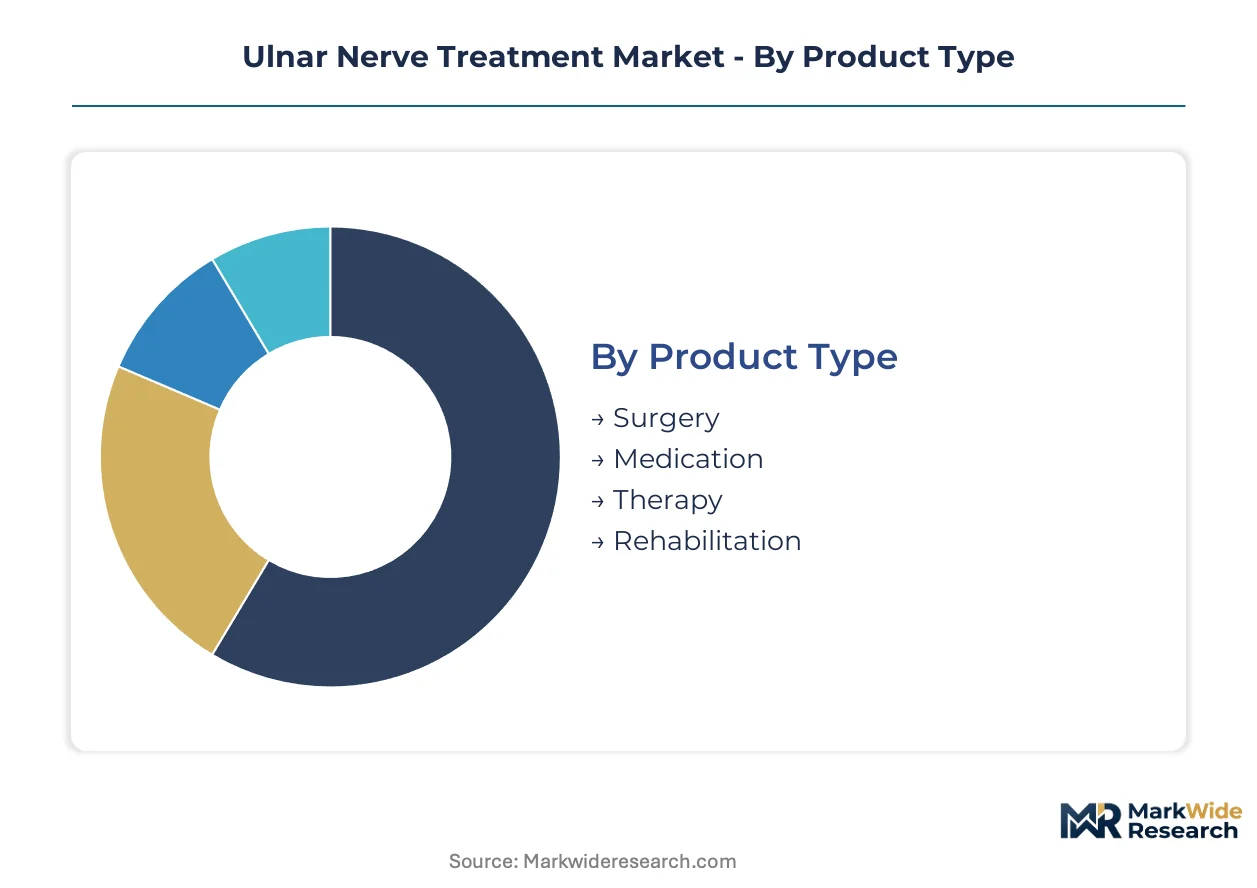
Segmentation in ulnar nerve treatment reveals how procedure economics and site-of-service regulations partition revenue across intervention types. Understanding these divides clarifies where capital deployment yields fastest returns.
Product Type:
Upgrade cycles in ulnar nerve treatment track minimally invasive technique maturation and biologic conduit approval timelines, with surgical portfolios refreshing faster than pharmaceutical alternatives.
- Surgery:Open and endoscopic decompression, transposition, and neurolysis procedures utilizing microsurgical instrumentation and nerve conduits. Demand clusters in ambulatory surgical centers across Texas and Florida where CMS reimbursement parity accelerates same-day discharge protocols.
- Medication:Perioperative analgesics, neuropathic pain agents, and anti-inflammatory protocols supporting surgical recovery and conservative management. Prescription volumes concentrate in hospital outpatient departments managing complex polytrauma cases with concurrent nerve injuries.
- Therapy:Nerve gliding exercises, splinting protocols, and ultrasound-guided hydrodissection delivered in office-based settings. Conservative triage captures 30-40% of early-stage cubital tunnel referrals before surgical candidacy.
- Rehabilitation:Postoperative occupational therapy focusing on grip strength recovery and sensory re-education. Service lines expand fastest through telehealth-enabled remote monitoring platforms reaching rural Montana and Wyoming patients.
Volume placements concentrate in Surgery; the faster expansion belongs to Rehabilitation.
Delivery Mode:
Cost tier stratification in delivery mode reflects facility fee differentials and anesthesia staffing requirements, with lower-acuity settings capturing margin from compressed reimbursement schedules.
- In-hospital:Inpatient admissions for complex revision transposition, multilevel nerve grafting, and trauma-related ulnar nerve exploration. Academic medical centers in California and New York maintain these capabilities for tertiary referral cases.
- Outpatient:Ambulatory surgical center-based cubital tunnel release and simple decompression without overnight stay. Certificate-of-need deregulation in Arizona and Nevada permits rapid capacity expansion outside hospital system control.
- Homecare:Visiting nurse services for wound management and medication administration following nerve procedures. Medicare Advantage plans in Pennsylvania and Ohio drive utilization through bundled payment incentives.
- Telehealth:Asynchronous video assessment, wearable sensor monitoring, and remote rehabilitation coaching. The segment climbs fastest as grip strength tracking devices enable specialist oversight without geographic proximity.
Revenue concentration sits with Outpatient; the steepest expansion trajectory is Telehealth.
End User:
Customer type segmentation exposes how referral pattern fragmentation and direct-to-consumer scheduling reshape traditional physician-hospital alignment.
- Clinics:Hand surgery and physiatry practices performing office-based diagnostic injections and hydrodissection. Self-referred patients in Colorado and Washington bypass primary care gatekeeping through direct online booking platforms.
- Hospitals:Inpatient surgical departments and hospital outpatient departments managing workers' compensation and trauma cases. Facilities compete for limited fellowship-trained peripheral nerve specialists through recruitment incentives.
- Rehabilitation Centers:Dedicated occupational therapy facilities providing intensive postoperative sensory and motor retraining. Urban centers in Illinois and Massachusetts concentrate specialized equipment for nerve recovery protocols.
- Home Care Providers:Agencies delivering nursing and therapy services in residential settings. Growth tracks telehealth platform integration enabling remote specialist supervision of distributed care teams.
Procedure throughput concentrates in Hospitals; the fastest share gain belongs to Clinics.
Procedure Type:
Maturity gradients in procedure type separate established open techniques from emerging minimally invasive alternatives, with pricing power correlating to technical complexity and training scarcity.
- Carpal Tunnel Release:Median nerve decompression at the wrist, often performed concomitantly with ulnar procedures in double crush presentations. High-volume community hospitals in Michigan and Wisconsin maintain dedicated hand surgery service lines.
- Ulnar Nerve Transposition:Anterior submuscular or subcutaneous relocation of the nerve to relieve cubital tunnel compression. Tertiary centers command premium reimbursement for revision cases requiring biologic nerve wraps.
- Decompression:Simple release of the cubital tunnel retinaculum without nerve mobilization. Endoscopic instrumentation converts open volume to minimally invasive approaches at accelerating rates.
- Surgical Repair:Nerve grafting, neurorrhaphy, and conduit placement for laceration or severe entrapment sequelae. Complex reconstruction concentrates in academic referral networks with microsurgical fellowship programs.
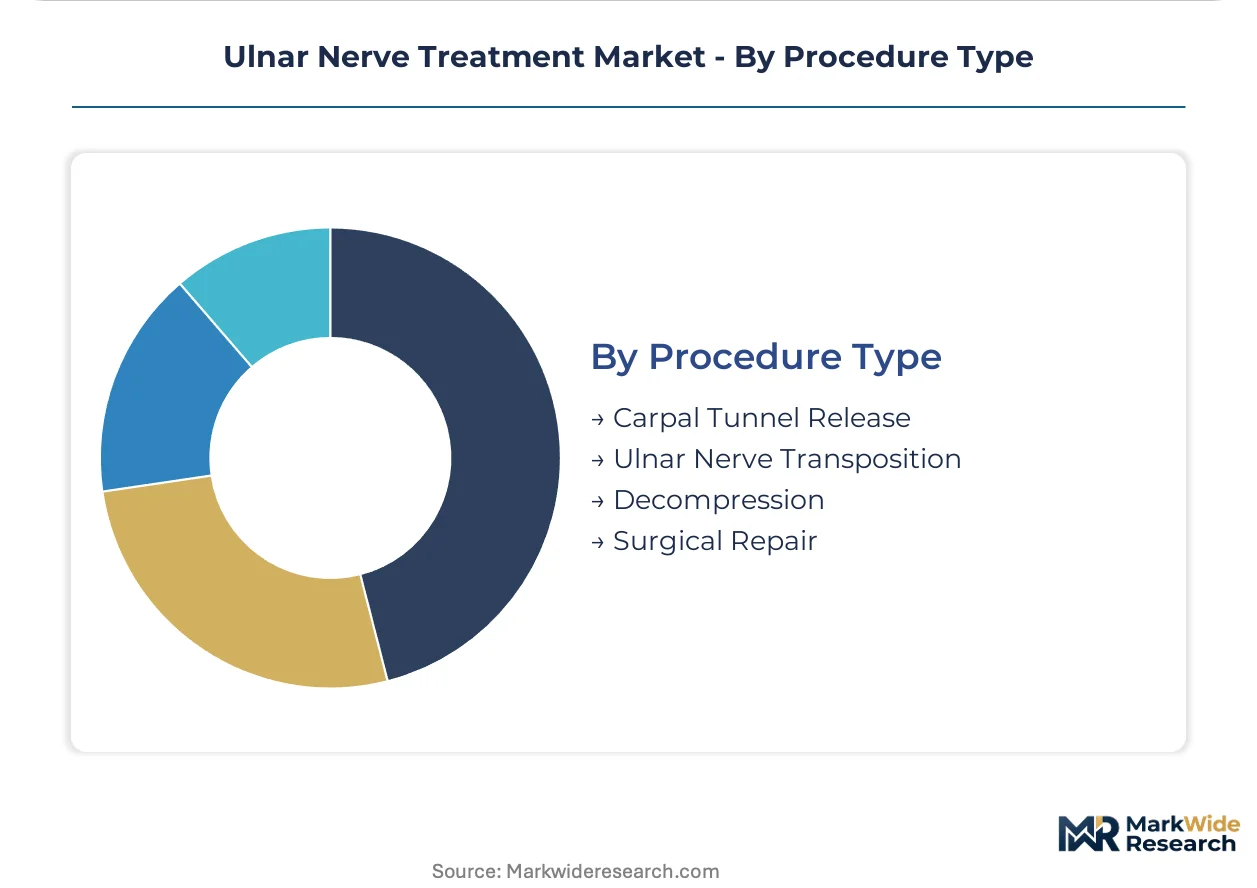
Case volume concentrates in Decompression; the premium pricing expansion belongs to Ulnar Nerve Transposition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of microsurgical instruments and nerve conduits concentrates in Germany and Japan, while procedure volume and revenue generation tilts toward the United States where ambulatory migration accelerates fastest.
United States
CMS reimbursement parity for cubital tunnel release in ambulatory surgical centers draws surgical volume from inpatient facilities. FDA 510(k) clearance pathways govern nerve conduit commercialization timelines. Texas and Florida ASCs report dedicated capacity additions targeting nerve entrapment cases specifically.
Germany
Specialized microsurgical instrument manufacturing anchors supply-side concentration for premium nerve retractors and decompression tools. ISO 13485 quality management standards create compliance barriers for new market entrants. Bavarian and Baden-Württemberg industrial clusters maintain precision instrument production for global export.
Japan
PMDA regulatory frameworks shape bioresorbable synthetic graft approval timelines for domestic and export markets. METI industrial policy supports medical device manufacturing competitiveness. Tokyo-Osaka corridor concentrations supply advanced endoscopic instrumentation to Asian surgical centers.
India
Cost arbitrage for complex transposition and grafting procedures attracts self-pay medical tourism from Gulf states and Southeast Asia. CDSCO medical device regulations govern import and domestic manufacturing authorization. Mumbai and Chennai facilities market bundled surgical packages below US deductible thresholds.
United Kingdom
NHS England commissioning frameworks determine reimbursement rates for cubital tunnel procedures across hospital and community settings. MHRA post-Brexit regulatory autonomy shapes device approval timelines. London and Manchester tertiary centers concentrate fellowship-trained peripheral nerve specialists for complex revision cases.
Ulnar Nerve Treatment Market Competitive Environment
Top-tier vendors anchor pharmaceutical and device portfolios, while mid-tier specialists concentrate on generic supply and regional instrument fabrication. The competitive structure stratifies across three archetypes: diversified pharmaceutical conglomerates with neurology breadth, orthopedic-surgical device manufacturers with minimally invasive platforms, and generic-focused pharmaceutical suppliers serving cost-sensitive ambulatory settings. Dominant competitive moves include portfolio diversification into adjacent nerve entrapment indications and strategic partnerships with ambulatory surgical center networks.
Among diversified pharmaceutical conglomerates, Pfizer and Johnson & Johnson exemplify archetype positioning through formulary anchoring and surgical instrument platform breadth respectively. Teva Pharmaceuticals occupies a position within the generic-supply tier serving cost-sensitive settings. These three entities represent the spectrum from premium-branded perioperative management through device-integrated surgical solutions to commoditized analgesic supply.
| Leading Market Players |
|---|
| Teva Pharmaceuticals |
| Pfizer |
| Johnson & Johnson |
| GSK |
| Bayer |
| Endo International |
| Allied Chemicals & Pharmaceuticals |
| Saol Therapeutics |
| Apotex |
| Others |
Value Chain & Pricing Dynamics
Family-owned German and Japanese precision instrument manufacturers anchor premium nerve retractor production, translating concentrated supply ownership into disciplined pricing power across ambulatory surgical center procurement cycles.
Pricing Analysis
Margin tightening in standard surgical instrumentation reflects generic instrument import competition from Chinese manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified German retractors from mid-tier Korean alternatives and unbranded Asian supply. Pricing pressure stems from ASC group purchasing organization consolidation demanding volume discounts. Hospital outpatient departments exhibit lowest price sensitivity due to pass-through reimbursement mechanics, while independent ASCs in deregulated states negotiate aggressively.
Supply Chain Analysis
Bioresorbable synthetic conduit feedstock rests on German specialty polymer producers and Japanese precision extrusion houses. Raw material dependencies span medical-grade polylactic acid, porcine-derived acellular matrices, and high-purity titanium for microsurgical instrumentation. Single-source vulnerability concentrates in nerve wrap biologics where amniotic membrane processors maintain geographic monopolies. Distribution runs through orthopedic distributor networks serving hospital systems and direct-to-ASC contracts bypassing traditional warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
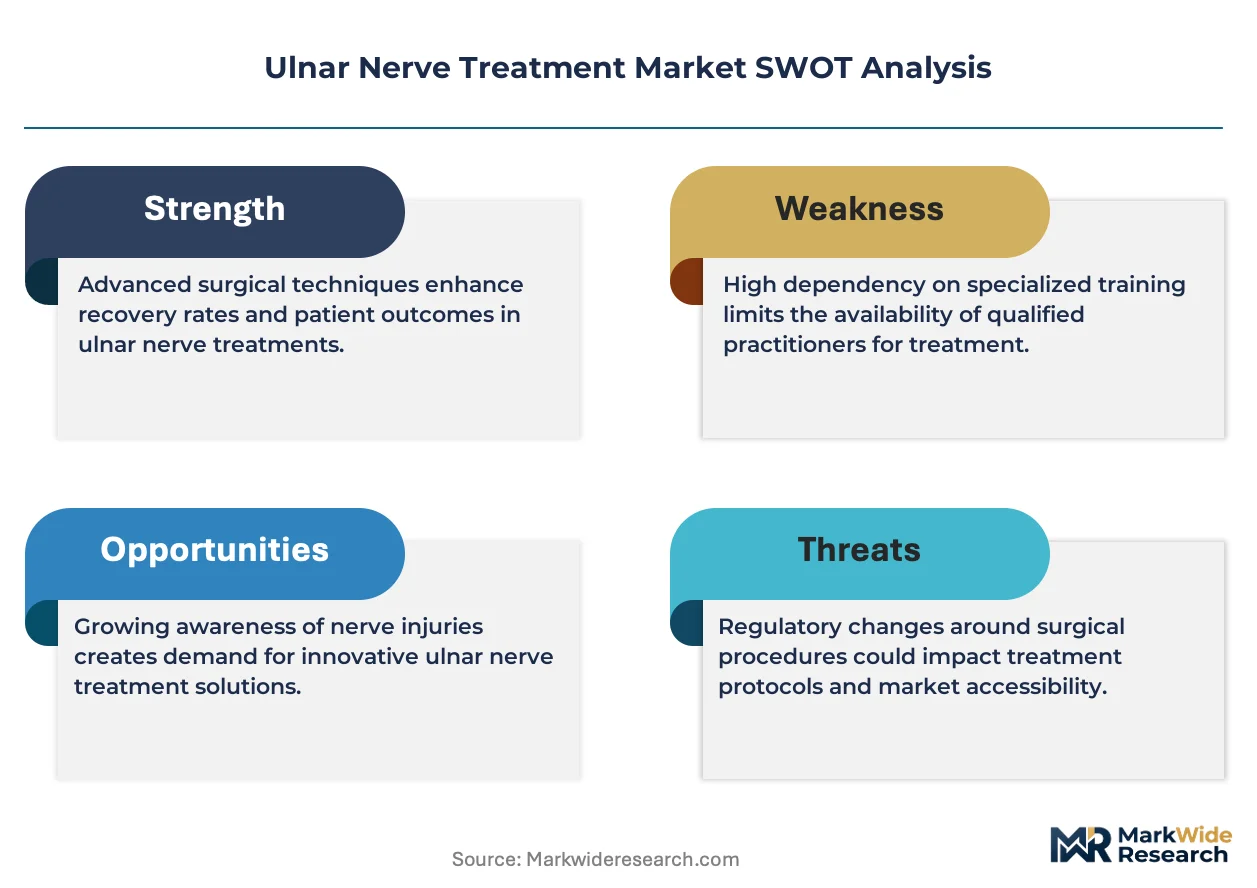
Fellowship-trained peripheral nerve specialist scarcity constrains surgical capacity expansion, propping reimbursement rates for complex transposition procedures against outpatient migration pressure.
For Market Incumbents: Extend biologic nerve wrap portfolios into revision surgery indications before generic conduit competition materializes. Anchor hospital system contracts through exclusive instrumentation leasing arrangements that lock out emerging German and Japanese competitors. Vertical integration into amniotic membrane sourcing mitigates single-supplier risk for high-margin biologic products. For New Entrants and Emerging Players: Launch via telehealth-enabled remote monitoring platforms targeting rural Montana and Wyoming geographies where specialist access gaps persist. White-space concentrates in wearable grip strength sensors for postoperative rehabilitation tracking. Direct-to-ambulatory-center sales models bypass entrenched distributor relationships controlling hospital procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor microsurgical instrument specialists in Baden-Württemberg industrial clusters facing tariff exposure and energy cost compression. Long-term viability hinges on ambulatory surgical center volume sustainability beyond certificate-of-need deregulation waves. Watch FDA breakthrough device designation velocity for nerve regeneration biologics as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket review compresses 18-24 month timelines for biologic conduit developers. |
| ASC Network Partnership | Exclusive supply agreements with Texas and Florida ambulatory chains secure volume commitments. |
| Telehealth Platform Integration | Wearable sensor partnerships enable remote postoperative monitoring reducing readmission exposure. |
| Biologic Nerve Wrap Expansion | Acellular dermal matrices address scarred revision cases commanding premium reimbursement. |
| Certificate-of-Need Deregulation Response | Rapid facility licensing in Arizona and Nevada captures outpatient migration ahead of hospital systems. |
Study Parameters
Independent corroboration across hand surgery fellowship program directors, ASC operations executives, and orthopedic distributor account managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, CMS Medicare cost reports, and state-level certificate-of-need regulatory filings. Bottom-up procedure volume estimates triangulate against top-down pharmaceutical and device revenue disclosures.
Rate-of-change decomposition across the analysis window separates volume drivers from pricing dynamics. Segmentation dimensions span procedure type, site-of-service delivery mode, and biologic versus synthetic conduit material class. CAGRs derive from surgical volume trend extrapolation moderated by reimbursement parity implementation timelines and training pipeline constraints.
CMS reimbursement recalibration, FDA premarket review timeline volatility, and fellowship training position expansion are the dominant revision risks. Forecasts embed assumptions around ambulatory surgical center capacity licensing velocity and biologic conduit approval cadence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neuro Critical Care Market
Neurology
Narcolepsy Treatment Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Movement Disorder Market
Neurology
Vocal Cord Paralysis Market
Neurology
Global Neuroblastoma Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Transcranial Doppler Market
Neurology
Labyrinthitis Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
CNS Lymphoma Market
Neurology
Acute Repetitive Seizures Market
Neurology
CNS Therapeutics Market
Neurology
Spinal Cord Trauma Treatment Market