
 Tranquilizer Drugs Market | 2026-2036
Tranquilizer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Tranquilizer Drugs Market Analytics
Psychiatrist prescribing capacity is unwinding as a growth constraint across mature markets, with training pipeline expansions in the United Kingdom and Germany gradually easing access bottlenecks. Pfizer Inc. leverages its manufacturing scale to sustain bulk benzodiazepine supply contracts with national health systems. Sun Pharmaceutical Industries Inc. anchors its position through cost-competitive generic barbiturate production for emerging markets. Eli Lilly and Company differentiates via R&D intensity in non-benzodiazepine sedative mechanisms.
Tranquilizer drugs comprise centrally acting depressants formulated as tablets, injectable solutions, oral solutions, or sublingual films, primarily indicated for anxiety disorders, sleep disorders, muscle spasms, and seizure management through GABA receptor modulation or related neurochemical pathways. Benzodiazepines dominate current revenue pools due to entrenched clinical familiarity and broad-spectrum efficacy, while non-benzodiazepine sedatives represent the fastest-expanding category as physicians seek reduced dependency profiles. Hospital procurement of injectable formulations commands premium pricing, whereas home care tablet consumption drives aggregate volume.
FDA scheduling under the Controlled Substances Act and DEA production quotas directly shape manufacturing volumes and distribution channel rigor for US-market tranquilizers. EMA pharmacovigilance requirements and national reimbursement frameworks across Germany, France, and Italy govern European market access and formulary placement. Stakeholders must monitor evolving scheduling reclassifications and dependency-risk labeling mandates that could abruptly reshape prescriber behavior and product-level demand trajectories.
Market Dynamics
DEA manufacturing quotas and FDA scheduling under the Controlled Substances Act impose rigid supply ceilings that prevent volume elasticity even when outpatient psychiatric demand surges. These regulatory hard caps force manufacturers to allocate production across formulations months in advance, creating structural mismatches between prescription rates and available inventory.
Growth Catalysts
- Outpatient psychiatric expansion:Community mental health centers in the United States are extending prescribing authority to nurse practitioners, amplifying benzodiazepine access without psychiatrist bottlenecks.
- EMA pharmacovigilance harmonization:Streamlined adverse-event reporting across Germany, France, and Italy accelerates formulary approvals for novel non-benzodiazepine sedatives.
- Injectable formulation demand:Hospital emergency departments favor rapid-onset intramuscular tranquilizers for acute agitation management, sustaining premium pricing tiers.
Market Restraints
- Active pharmaceutical ingredient concentration:Three Indian bulk manufacturers control global benzodiazepine precursor supply, exposing formulators to geopolitical disruption risk.
- DEA quota rigidity:Annual production ceilings for Schedule IV substances prevent manufacturers from responding to demand spikes caused by seasonal anxiety disorder flare-ups.
- Cognitive behavioral therapy substitution:First-line anxiety treatment guidelines in the United Kingdom now prioritize psychotherapy over pharmacological intervention, compressing new-patient prescription volumes.
Strategic Opportunities
- Brazilian private insurance expansion:ANVISA fast-track pathways for anxiolytic generics align with rising middle-class enrollment in supplemental health plans.
- Telehealth prescribing platforms:Direct-to-patient digital pharmacies bypass traditional wholesale distribution, capturing margin previously lost to pharmacy benefit managers.
- Dual orexin receptor antagonist development:Convergence of sleep-science neurobiology and GABA-sparing mechanisms opens insomnia indications without dependency stigma.
Industry Challenges
- Controlled-substance compliance staffing:Manufacturers struggle to recruit qualified DEA registrars for inventory tracking and diversion-monitoring programs.
- Legacy manufacturing equipment retrofitting:Conversion of standard tablet lines to tamper-resistant abuse-deterrent formats requires capital outlays that strain mid-tier generic producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tranquilizer Drugs Market |
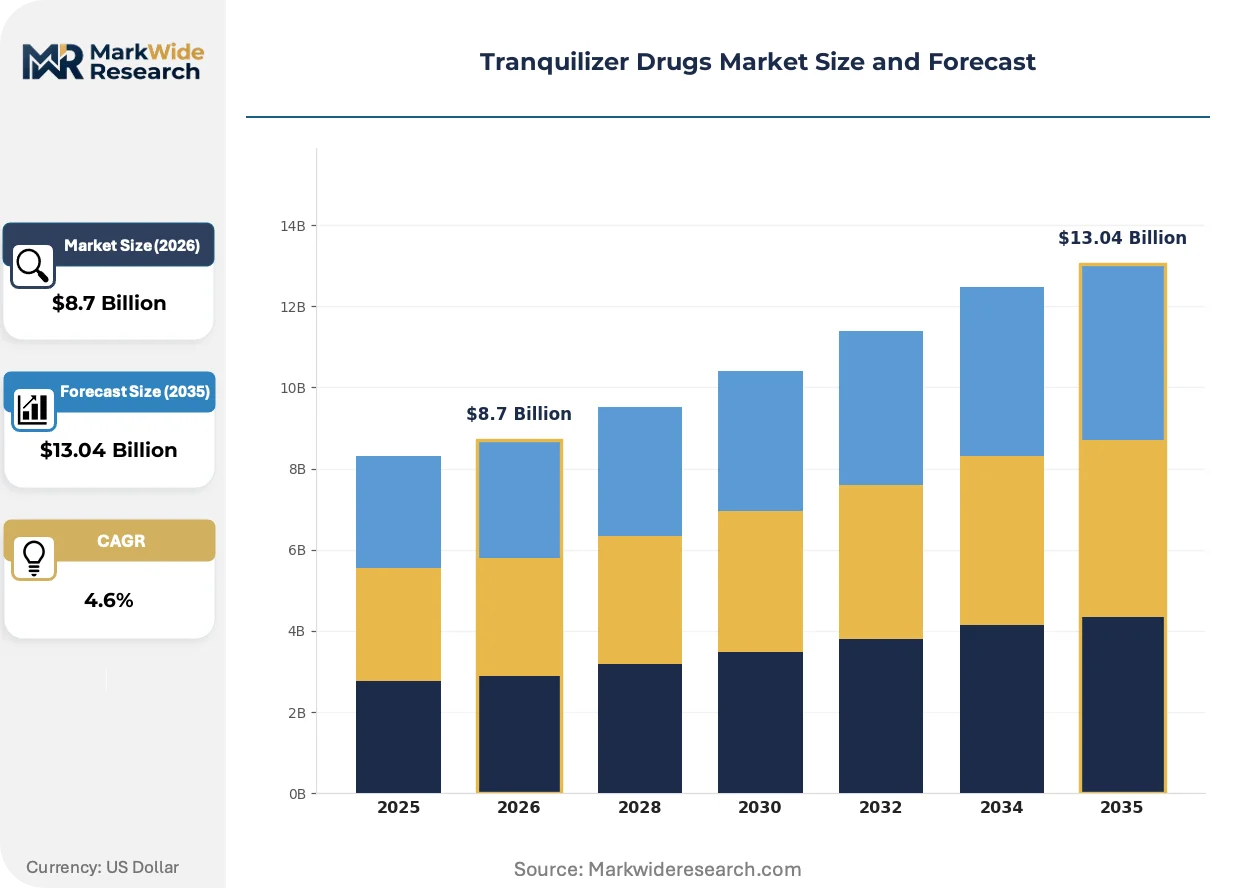
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barbiturates, Benzodiazepines, Non-Benzodiazepine Sedatives, Others Therapeutic Use: Anxiety Disorders, Sleep Disorders, Muscle Spasms, Seizures Formulation Type: Tablets, Injectable Solutions, Oral Solutions, Sublingual Films End User: Hospitals, Home Care, Outpatient Clinics, Rehabilitation Centers |
| Companies Covered | Johnson & Johnson, GlaxoSmithKline plc, Pfizer Inc., Sun Pharmaceutical Industries Inc., F. Hoffmann-La Roche Ltd., Eli Lilly and Company, Merck & Co. Inc., Bristol-Myers Squibb Company, AstraZeneca Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tranquilizer Drugs Market Evolving Landscape
Formulation science and distribution architecture are diverging sharply from legacy benzodiazepine paradigms as prescribers and regulators jointly pressure dependency reduction. This shift rewards innovators who can deliver rapid anxiolysis without reinforcing GABA receptor downregulation.
Pharmacogenomic-guided dosing algorithms are bifurcating prescriber behavior between standardized empirical titration and metabolite-testing-informed personalization. Psychiatric practices in the Netherlands and Australia are piloting CYP2C19 screening for clonazepam responders, compressing trial-and-error periods from weeks to days. This precision approach is bifurcating the market into high-touch specialty clinics and volume-driven primary care, with diverging reimbursement pathways for each.
REACH authorization requirements for novel chemical entities are tightening toxicological data standards for sedative-hypnotic candidates seeking European market access. EMA's 2023 updated guideline on non-clinical abuse liability assessment now mandates self-administration studies in non-human primates for all GABA-active compounds, extending development timelines by 18-24 months. German and French regulators are applying these standards retroactively to pending applications, forcing sponsors to supplement dossiers with costly behavioral pharmacology packages.
Hospital procurement committees are consolidating anesthesia and emergency psychiatry tranquilizer purchasing under single-source contracts with mandatory therapeutic interchange protocols. This buyer concentration is displacing individual physician formulary autonomy in favor of pharmacy-driven standardization, most visible in National Health Service trusts across England and Scotland where midazolam has displaced lorazepam for procedural sedation based on unit-cost metrics rather than clinical preference.
Tranquilizer Drugs Market Segmentation
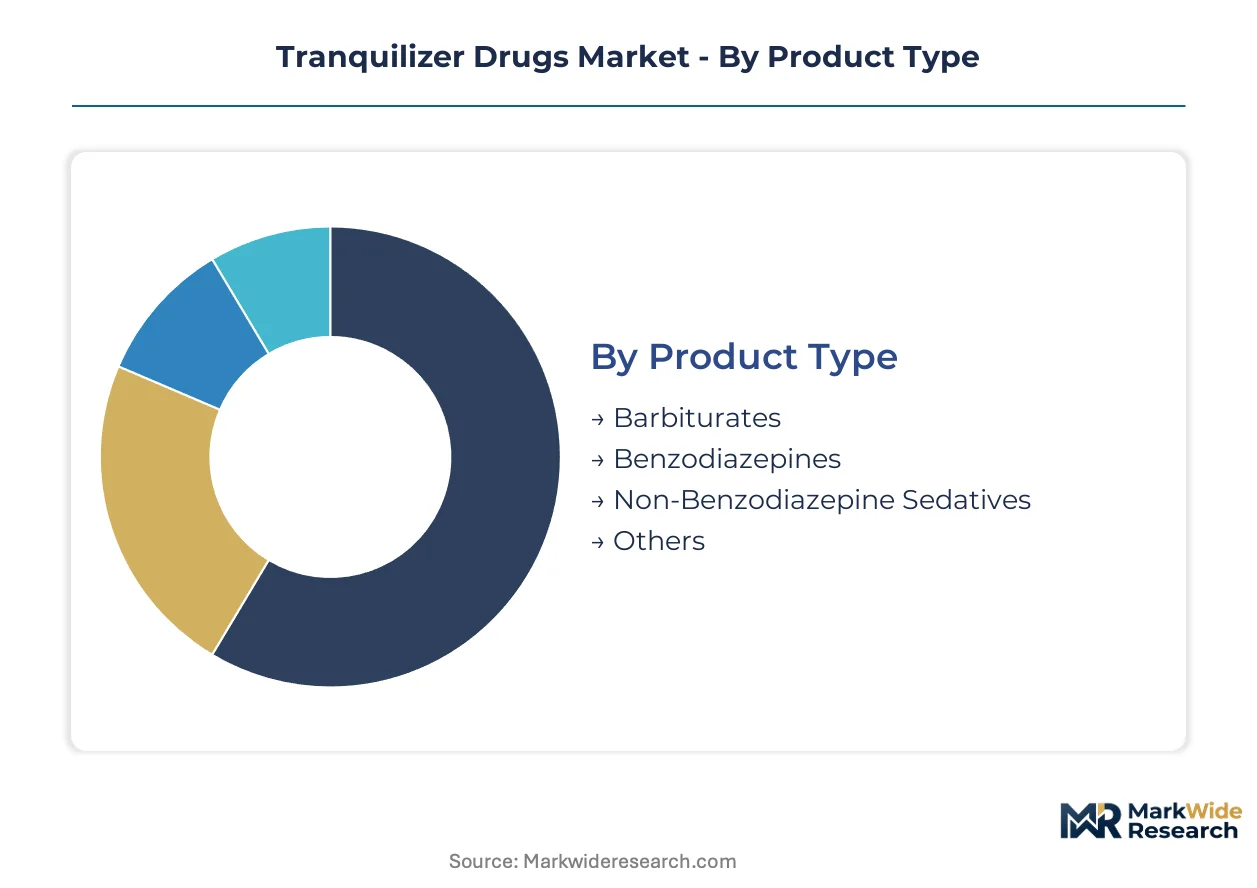
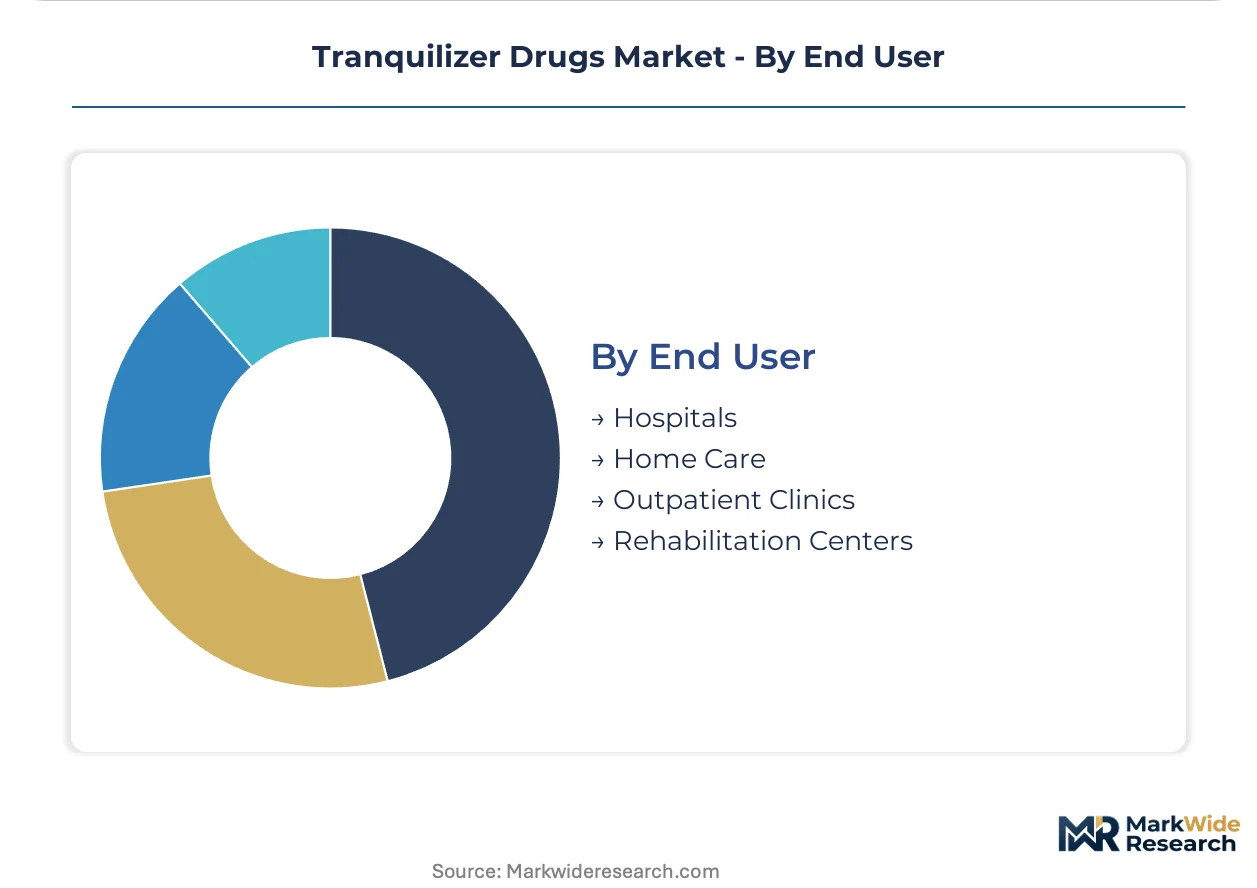
Segmentation in tranquilizer drugs reveals divergent regulatory exposures and margin architectures across therapeutic applications. Each dimension carries distinct supply chain rigidity and prescriber access patterns that shape competitive positioning.
Product Type:
Domestic manufacturing concentrates benzodiazepine API production in India and China, while non-benzodiazepine sedatives flow through European and North American formulation centers.
- Benzodiazepines:GABA-A receptor modulators including diazepam, lorazepam, and alprazolam dominate hospital formularies through rapid anxiolytic onset. United States outpatient clinics generate concentrated demand volume under DEA Schedule IV quotas that constrain supply elasticity.
- Non-Benzodiazepine Sedatives:Dual orexin receptor antagonists and melatonin agonists deliver sleep induction without GABA receptor engagement. German and French reimbursement frameworks accelerate formulary placement for these dependency-sparing alternatives.
- Barbiturates:Legacy GABA-active compounds now restricted to seizure management and anesthesia induction in controlled hospital settings.
- Others:Botanical sedatives and combination therapies occupying niche positions in markets with restrictive controlled-substance frameworks.
Benzodiazepines command the established base. The steepest expansion runs through non-benzodiazepine sedatives.
Therapeutic Use:
Cost tier separation is pronounced: hospital-administered seizure protocols carry premium pricing, while home care anxiety maintenance operates on thin generic margins.
- Anxiety Disorders:Generalized anxiety and panic disorder indications drive the largest prescription volumes through primary care and psychiatric specialty channels. United Kingdom NICE guidelines now prioritize cognitive behavioral therapy as first-line intervention, compressing new-patient pharmacological starts.
- Sleep Disorders:Insomnia and circadian rhythm disruption represent the fastest-climbing indication category as aging populations seek non-habit-forming hypnotics. Australian TGA fast-track pathways for novel sleep mechanisms accelerate market entry timelines.
- Muscle Spasms:Acute spasticity and chronic musculoskeletal indications concentrate in post-surgical and neurology patient populations.
- Seizures:Emergency seizure termination and chronic epilepsy management require intravenous and rectal formulations with stringent bioequivalence standards.
Anxiety disorders anchor volume throughput. Sleep disorder applications are gaining share fastest.
Formulation Type:
Volume concentration tilts toward oral solids, yet margin concentration favors sterile injectables with complex manufacturing requirements.
- Tablets:Compressed solid dosages dominate home care consumption through cost-efficient manufacturing and patient self-administration. Indian generic producers supply bulk tablet volumes to emerging markets under WHO prequalification programs.
- Injectable Solutions:Intramuscular and intravenous formulations command hospital procurement premiums for acute agitation and procedural sedation. United States 503B compounding facilities face heightened FDA inspection intensity for sterile tranquilizer production.
- Oral Solutions:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties.
- Sublingual Films:Rapid-dissolve polymer matrices enable buccal absorption for patients requiring fast onset without injection.
Tablets sustain aggregate volume. Injectable solutions capture margin concentration.
End User:
Customer type determines channel architecture: institutional procurement committees negotiate bulk contracts, while retail pharmacy dispensing operates through fragmented wholesale networks.
- Hospitals:Emergency departments and anesthesia units drive concentrated demand for rapid-onset intramuscular formulations. NHS England trusts have consolidated midazolam purchasing under single-source agreements with mandatory therapeutic interchange.
- Outpatient Clinics:Community mental health centers and psychiatric practices generate recurring prescription volumes for maintenance anxiolytic therapy. United States nurse practitioner prescribing authority expansion amplifies access without psychiatrist bottlenecks.
- Home Care:Patient-directed oral medication consumption spreads volume across dispersed retail pharmacy networks.
- Rehabilitation Centers:Substance use disorder facilities manage benzodiazepine tapering protocols with specialized oversight requirements.
Hospitals anchor premium pricing. Outpatient clinics drive volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA scheduling under the Controlled Substances Act and DEA manufacturing quotas anchor supply dynamics in the United States, while EMA pharmacovigilance frameworks govern European market access. National reimbursement policies and prescriber training pipelines create divergent growth trajectories across mature markets.
United States
Outpatient psychiatric expansion drives benzodiazepine volume through nurse practitioner prescribing authority in community mental health centers. DEA production quotas for Schedule IV substances create rigid supply ceilings that prevent manufacturers from responding to seasonal demand spikes. New Jersey and North Carolina host concentrated pharmaceutical formulation clusters serving national distribution networks.
Germany
Psychiatrist training pipeline expansions gradually ease access bottlenecks across Bavaria and North Rhine-Westphalia. EMA pharmacovigilance harmonization accelerates formulary approvals for novel non-benzodiazepine sedatives through streamlined adverse-event reporting. Frankfurt and Munich anchor hospital procurement consolidation under single-source contracts with mandatory therapeutic interchange protocols.
United Kingdom
NICE guidelines now prioritize cognitive behavioral therapy over pharmacological intervention for first-line anxiety treatment, compressing new-patient prescription volumes. NHS England trusts have consolidated midazolam purchasing under centralized agreements displacing individual physician formulary autonomy. London and Greater Manchester concentrate psychiatric specialty practices piloting pharmacogenomic-guided dosing algorithms.
India
Cost-competitive generic barbiturate production serves emerging market demand through WHO prequalification programs. CDSCO regulatory pathways govern bulk active pharmaceutical ingredient manufacturing concentrated in Gujarat and Maharashtra. Hyderabad and Mumbai house formulation facilities supplying benzodiazepine precursors to global formulators.
Brazil
ANVISA fast-track pathways for anxiolytic generics align with rising middle-class enrollment in supplemental health plans. São Paulo and Rio de Janeiro anchor private insurance expansion driving access to non-benzodiazepine sedative alternatives. National health system procurement increasingly favors domestic manufacturing partnerships for hospital-administered injectable formulations.
Tranquilizer Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the tranquilizer drugs market. The competitive structure consolidates around multinational pharmaceutical conglomerates with manufacturing scale, mid-tier generic specialists with cost positioning, and research-intensive innovators developing GABA-sparing mechanisms. Strategic moves center on portfolio diversification into non-benzodiazepine sedatives and geographic expansion through emerging market partnerships.
Among research-intensive innovators, Eli Lilly and Company exemplifies R&D intensity in novel sedative mechanisms, while Pfizer Inc. anchors the scale-driven tier through manufacturing breadth. Sun Pharmaceutical Industries Inc. represents the cost-competitive generic archetype serving volume-driven emerging markets. These three players collectively illustrate the tripartite competitive structure shaping supply dynamics and pricing architecture across therapeutic categories.
| Leading Market Players |
|---|
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Inc. |
| F. Hoffmann-La Roche Ltd. |
| Eli Lilly and Company |
| Merck & Co. Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca Plc |
| Others |
Value Network & Pricing Analysis
Non-benzodiazepine sedative substitution for legacy benzodiazepines is redrawing API sourcing maps from Indian bulk manufacturers toward European formulation centers, simultaneously elevating R&D amortization costs and compressing generic tablet margins through prescriber preference shifts.
Pricing Analysis
United States hospital procurement premiums for injectable midazolam run 40-60% above German NHS trust unit costs for equivalent lorazepam formulations. Three-tier pricing structure across premium patented orexin antagonists, standard branded benzodiazepines, and economy Indian-sourced generics captures divergent value pools. Pricing pressure stems from therapeutic interchange protocols mandating lowest-cost alternatives in NHS England and Scottish trusts. Home care tablet consumers exhibit highest price sensitivity, while emergency department purchasers prioritize rapid onset over unit economics.
Supply Chain Analysis
Container availability constraints on Mumbai-Rotterdam and Shanghai-Hamburg lanes inflate inbound logistics costs for European formulators sourcing benzodiazepine precursors. API manufacturing concentrates in Gujarat and Maharashtra, China synthetic chemistry hubs, and Swiss high-potency facilities. Finished formulation draws from Indian oral solid dose lines, German sterile injectable plants, and North American 503B compounding operations. Single-source vulnerability runs through three Indian bulk manufacturers controlling global benzodiazepine precursor supply. Distribution runs through national wholesale distributors, hospital GPO contracts, and emerging direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified DEA registrar scarcity constrains mid-tier generic manufacturers seeking compliance staffing for controlled-substance tracking programs, creating competitive moats for incumbents with established diversion-monitoring infrastructure.
For Market Incumbents: Secure backward integration into tamper-resistant abuse-deterrent formulation capabilities before FDA mandates retrofit existing tablet lines. Acquire pharmacogenomic testing partnerships to capture high-touch specialty clinic volumes as CYP2C19-guided dosing bifurcates prescriber behavior. Defend against Sun Pharmaceutical cost pressure by locking multi-year DEA quota allocations with advance production scheduling. For New Entrants and Emerging Players: ANVISA fast-track certification for anxiolytic generics opens Brazilian private insurance channels with minimal incumbent saturation. Target Australian TGA sleep disorder pathways where orexin antagonist demand outpaces domestic supply. Pursue telehealth direct-to-patient distribution to bypass pharmacy benefit manager margin extraction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier generic houses holding Indian API tolling agreements but lacking abuse-deterrent formulation capabilities. Five-to-ten year viability hinges on portfolio migration toward GABA-sparing mechanisms and dependency-reduction labeling. Watch for EMA scheduling reclassification signals that would abruptly reshape prescriber behavior and product-level demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Quota Pre-Allocation | Secures manufacturing volumes before annual Schedule IV ceiling determinations lock competitors out. |
| Pharmacogenomic Testing Partnership | Captures high-margin specialty clinic volumes through CYP2C19-guided clonazepam personalization in Netherlands and Australia. |
| Tamper-Resistant Formulation Retrofit | Meets anticipated FDA abuse-deterrent mandates without capital strain that would cripple mid-tier generic producers. |
| ANVISA Fast-Track Registration | Aligns with Brazilian middle-class supplemental health plan enrollment growth for anxiolytic generic access. |
| Dual Orexin Receptor Antagonist R&D | Opens insomnia indications without benzodiazepine dependency stigma through GABA-sparing neurobiological mechanisms. |
Research Methodology
Desk research of FDA scheduling determinations, DEA quota publications, and EMA pharmacovigilance guidelines preceded structured interviews with regulatory affairs leads, hospital formulary directors, and controlled-substance compliance officers. Secondary validation drew from ClinicalTrials.gov sedative-hypnotic entries, national reimbursement databases, and WHO prequalification records. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation anchored market size estimation.
Variance decomposition across product type, therapeutic indication, formulation format, and end-user channel shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectories and pricing elasticity assumptions for each regulatory cluster. Modeled inputs included DEA manufacturing quota fluctuations, EMA abuse liability assessment timelines, and prescriber substitution patterns between benzodiazepine and non-benzodiazepine categories.
Decision-makers should treat outputs as directional under stable DEA scheduling and unaltered EMA pharmacovigilance standards; material deviation would warrant model refresh. Forecasts assume continued nurse practitioner prescribing authority expansion and unimpeded Indian API supply flows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Anticancer Drugs Market