
 US and Canada Skin Cancer Dermatology Market | 2026-2036
US and Canada Skin Cancer Dermatology Market Size, Share, and Industry Trends Forecast 2026-2036
US and Canada Skin Cancer Dermatology Market Intelligence
Canada is tilting toward expanded teledermatology infrastructure that bridges rural patient access to specialist consultation. Canfield Scientific, Inc. leverages its imaging platform to anchor clinical workflows across North American academic medical centers. FotoFinder Systems, Inc. sustains competitive positioning through precision dermoscopy hardware with integrated documentation software. SkinIO differentiates by deploying AI-assisted full-body photography networks that streamline screening throughput in high-volume dermatology practices.
US and Canada skin cancer dermatology encompasses the clinical diagnosis, staging, and therapeutic management of malignant cutaneous neoplasms, principally through histopathological confirmation, surgical excision with margin control, and adjuvant systemic or localized therapy. The field relies on dermoscopic criteria such as the ABCDE rule and pattern analysis algorithms to triage suspicious lesions for biopsy. Biologic therapies command premium reimbursement profiles due to checkpoint inhibitor mechanisms in advanced melanoma, while phototherapy devices retain strong installed bases for actinic keratosis and superficial basal cell carcinoma management. Surgical procedures maintain dominant procedural volume across both countries, though immunotherapy application in melanoma represents the fastest-expanding therapeutic category by patient enrollment.
FDA regulates device-based diagnostics through the 510(k) and De Novo pathways, directly shaping market access timelines for AI-dermoscopy platforms seeking clinical claims. Health Canada and the FDA jointly enforce post-market surveillance for biologic safety signals, creating compliance obligations that favor established manufacturers with pharmacovigilance infrastructure. Stakeholders must monitor evolving reimbursement determinations from CMS and provincial health plans as they adjudicate coverage for combination immunotherapy regimens versus monotherapy standards.
Market Dynamics
AI-enabled dermoscopy platforms are compressing diagnostic timelines from weeks to same-day assessments, forcing dermatology clinics to reconfigure clinical workflows around automated triage systems rather than traditional sequential specialist referral chains.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage for teledermatology consultations removes financial barriers for rural patient populations across the US, accelerating virtual care adoption in underserved counties.
- Melanoma incidence trajectory:Rising case volumes in sun-belt states including Texas, Arizona, and Florida sustain procedural demand for Mohs micrographic surgery and sentinel lymph node biopsy.
- Checkpoint inhibitor protocols:Pembrolizumab and nivolumab combination regimens for Stage III-IV melanoma extend survival curves, driving oncology-dermatology co-management models in academic medical centers.
Market Restraints
- Pathologist workforce constraints:Dermatopathology fellowship vacancies limit diagnostic throughput in community hospital systems, creating biopsy result backlogs exceeding fourteen days.
- Device validation costs:FDA 510(k) clinical evidence requirements for AI-dermoscopy algorithms impose seven-figure premarket expenditure burdens on software developers.
- Geographic access inequity:Northern Ontario and rural Montana lack board-certified dermatologists within 100-mile radii, forcing primary care physicians to manage complex lesions without specialist backup.
Strategic Opportunities
- Manitoba-Saskatchewan corridor:Provincial health authority procurement of mobile dermoscopy units addresses specialist deserts through rotating clinic models in First Nations communities.
- Pharmacy-based screening:Shoppers Drug Mart and CVS Health pilot lesion photography kiosks that route images to asynchronous dermatologist review, capturing pre-symptomatic patient touchpoints.
- IRA domestic manufacturing incentives:Biologic production tax credits encourage Bristol Myers Squibb and Merck to expand checkpoint inhibitor fill-finish capacity at existing US facilities.
Industry Challenges
- Interoperability fragmentation:Proprietary image formats from Canfield, FotoFinder, and SkinIO prevent seamless exchange of longitudinal lesion photography across health system EHRs.
- AI liability frameworks:Unclear malpractice allocation between algorithm developers and deploying physicians slows institutional adoption of autonomous diagnostic tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Canada Skin Cancer Dermatology Market |
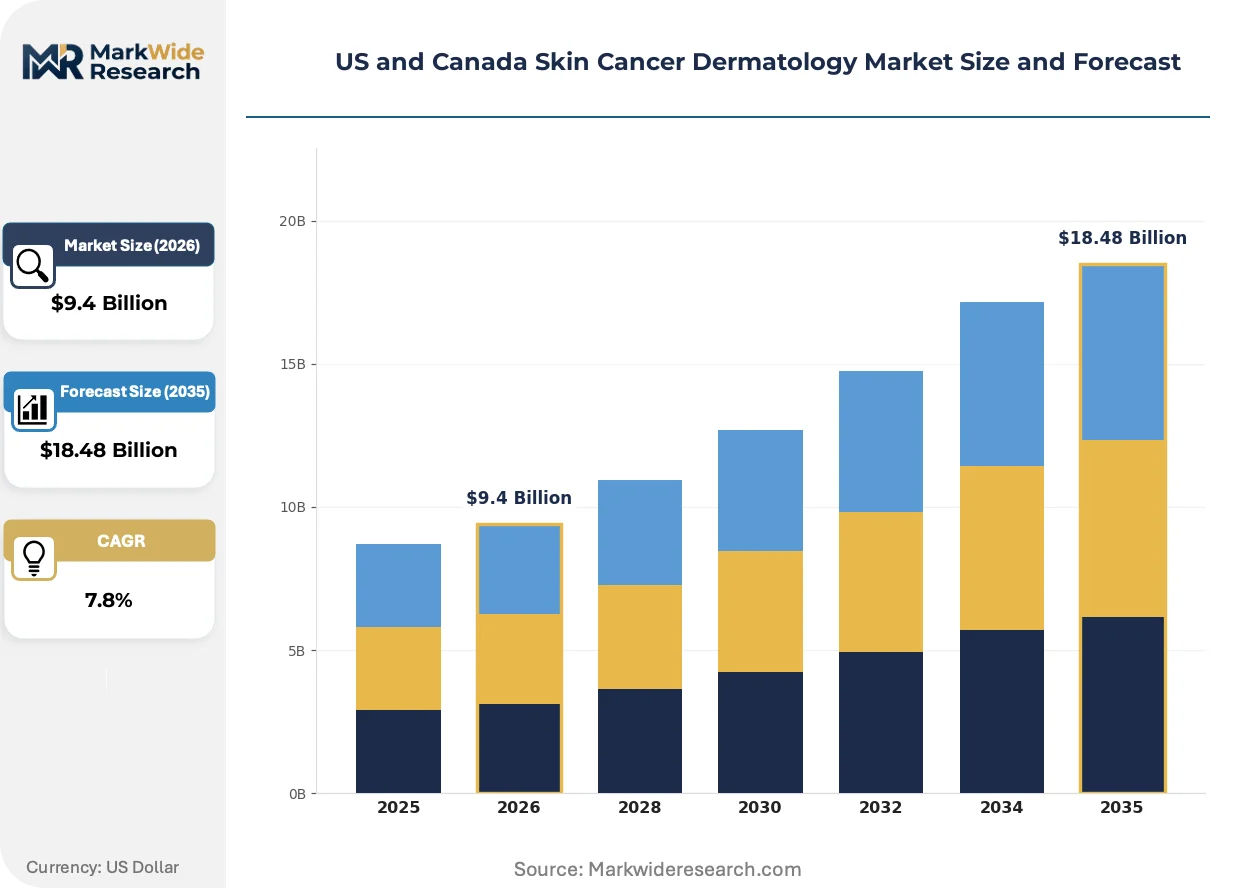
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $18.48 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Surgical Procedures, Phototherapy Devices, Biologic Therapies Application: Melanoma, Basal Cell Carcinoma, Squamous Cell Carcinoma, Atypical Nevi End User: Hospital Settings, Dermatology Clinics, Oncology Centers, Home Care Technology: Laser Therapy, Chemotherapy, Immunotherapy, Cryotherapy |
| Companies Covered | Firefly, SkinIO, Canfield Scientific, Inc., FotoFinder Systems, Inc., 3Gen, MetaOptima, Agilent Technologies, SkinVision, Speclipse, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Canada Skin Cancer Dermatology Market Strategic Shifts & Innovations
Multimodal diagnostic platforms are fusing dermoscopic imaging with genomic risk scoring, collapsing the traditional separation between visual assessment and molecular prognostication in melanoma management.
Convolutional neural networks trained on annotated lesion databases are collapsing the diagnostic accuracy gap between algorithmic assessment and specialist dermatologist evaluation. Community health centers in Michigan and Ohio deploy these tools for same-day biopsy decisions. The compression of triage timelines is reallocating specialist capacity toward complex surgical cases rather than benign lesion exclusion.
FDA's evolving guidance on Software as a Medical Device creates premarket clarity for adaptive algorithms that improve through real-world use. Health Canada coordinates parallel review pathways for synchronized US-Canada market entry. Device developers now structure clinical validation studies to satisfy both regulators simultaneously, reducing duplicate evidence generation costs.
Employer-sponsored screening programs are displacing reactive patient-initiated visits as the primary melanoma detection channel. Fortune 500 occupational health departments in California and Ontario contract with dermatology groups for on-site full-body photography. This procurement model concentrates annual screening volume into discrete contractual relationships rather than dispersed fee-for-service encounters.
US and Canada Skin Cancer Dermatology Market Segmentation
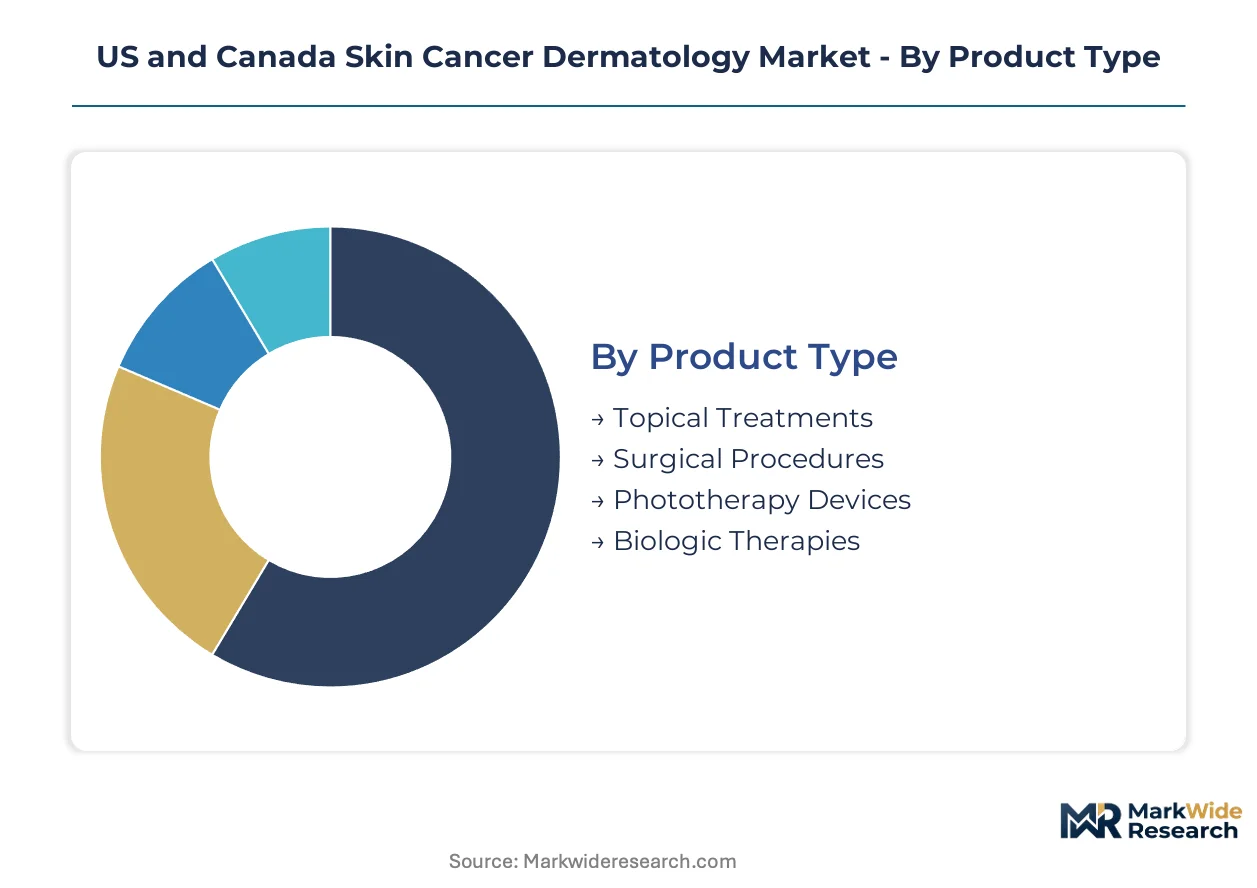
Segmentation in skin cancer dermatology reveals how clinical workflows, reimbursement structures, and technology access shape purchasing decisions across the US and Canada. Understanding these divides exposes where capital flows concentrate and where service gaps persist.
Product Type:
The use-case spectrum spans outpatient management to inpatient intervention, with each modality carrying distinct margin profiles and facility requirements.
- Surgical Procedures:Mohs micrographic surgery and wide local excision dominate procedural volume across Texas and Ontario hospital networks. Academic medical centers in sun-belt states sustain double-digit annual case growth for margin-controlled excision techniques.
- Biologic Therapies:Checkpoint inhibitors and targeted monoclonal antibodies command premium reimbursement through Medicare Part B and provincial formularies. Oncology-dermatology co-management models in California and Quebec accelerate enrollment for pembrolizumab-nivolumab combination protocols.
- Topical Treatments:Imiquimod and 5-fluorouracil formulations address superficial basal cell carcinoma in community dermatology practices with lower capital barriers.
- Phototherapy Devices:Narrowband UVB and PDT systems retain installed bases for actinic keratosis management in Medicare-certified outpatient clinics.
The dominant share belongs to Surgical Procedures, while Biologic Therapies is closing the gap fastest.
Application:
Malignancy severity determines treatment intensity and dictates whether care routes through general dermatology or specialized oncology units.
- Melanoma:Stage III-IV disease drives the most complex care coordination, requiring sentinel lymph node biopsy, systemic immunotherapy, and longitudinal surveillance. Arizona and Florida oncology centers report the highest per-patient procedure counts for advanced disease management.
- Basal Cell Carcinoma:High prevalence but low mortality creates volume-heavy, margin-compressed service lines in community dermatology practices across the US Midwest and Canadian prairies.
- Squamous Cell Carcinoma:Cutaneous SCC with high-risk features demands multidisciplinary management in academic medical center settings.
- Atypical Nevi:Dysplastic nevus monitoring generates recurring dermoscopy volume and biopsy referrals in cosmetic dermatology practices.
Melanoma captures the highest per-case revenue, though Basal Cell Carcinoma generates the greatest aggregate procedure volume.
End User:
Facility type determines technology procurement authority and patient access pathways.
- Hospital Settings:Integrated health systems in metropolitan Texas and Ontario anchor high-complexity surgical oncology and clinical trial enrollment for novel immunotherapy combinations.
- Dermatology Clinics:Independent and group practices in California and Quebec drive dermoscopy device adoption and teledermatology platform integration.
- Oncology Centers:Dedicated cancer institutes manage Stage III-IV melanoma biologic therapy administration and adverse event monitoring.
- Home Care:Topical therapy self-administration and remote lesion photography expand rural patient access in Montana and northern Ontario.
Hospital Settings retain the largest capital equipment budgets, while Dermatology Clinics are expanding fastest through private equity consolidation.
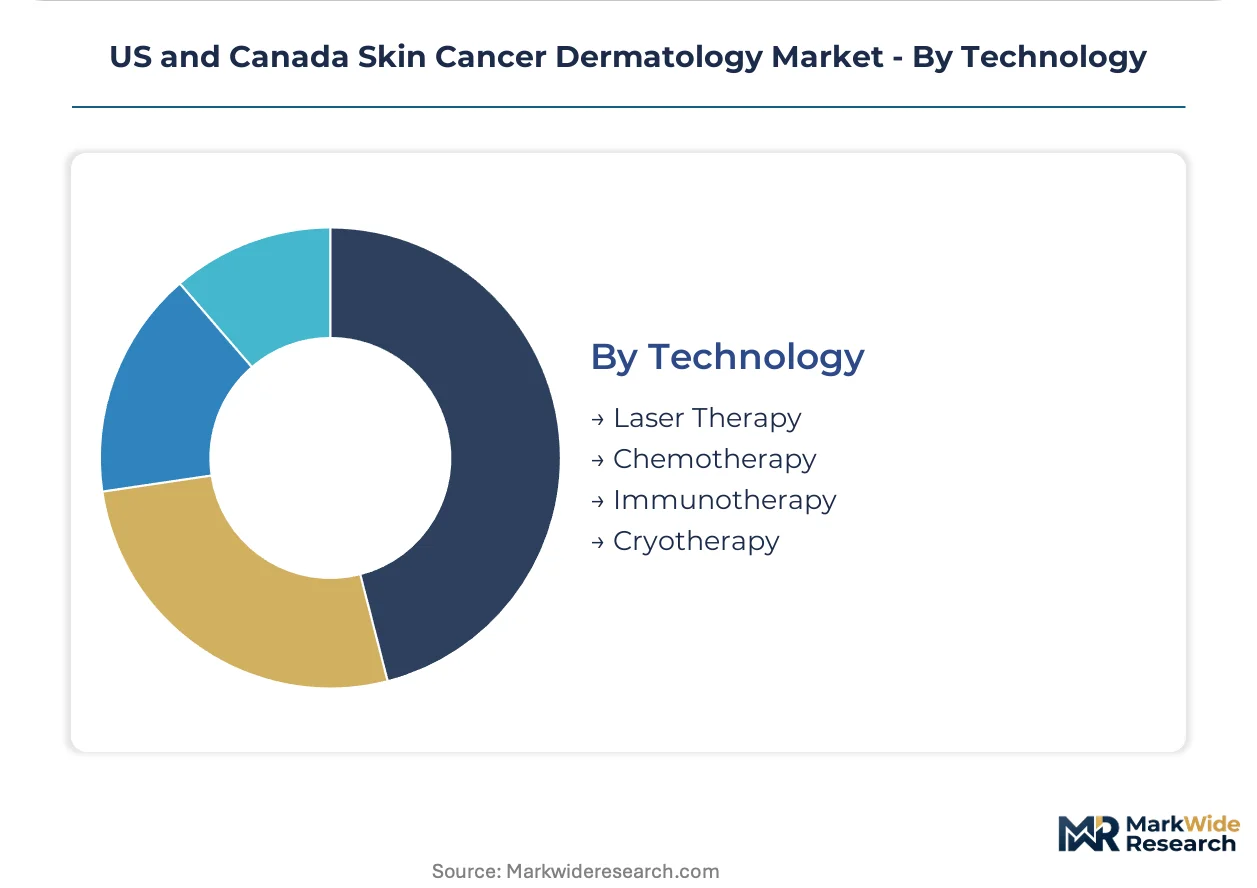
Technology:
Therapeutic modality selection follows lesion depth, histology, and patient comorbidity profiles.
- Immunotherapy:Anti-PD-1 and anti-CTLA-4 agents have transformed Stage III-IV melanoma survival curves, concentrating treatment delivery at academic medical centers with infusion capacity and oncology pharmacy infrastructure.
- Laser Therapy:Ablative and vascular lasers address select premalignant lesions and post-surgical scar revision in cosmetic dermatology practices.
- Chemotherapy:Systemic cytotoxic agents retain niche application for rare aggressive cutaneous malignancies and combination protocols.
- Cryotherapy:Liquid nitrogen destruction remains ubiquitous for actinic keratosis and selected superficial lesions in primary care and dermatology settings.
Immunotherapy commands the steepest expenditure trajectory, while Cryotherapy maintains the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA and Health Canada jointly govern device approvals across the US-Canada corridor, creating synchronized regulatory timelines for diagnostic platforms. Market concentration clusters in sun-belt metropolitan areas and Canadian provincial capitals with academic medical center density.
Texas
Texas sustains the highest Mohs micrographic surgery volume in the US, driven by elevated UV exposure and aging demographic migration. The Texas Medical Board enforces continuing education mandates for teledermatology licensing. Houston and Dallas anchor integrated dermatology-oncology networks that enroll patients in checkpoint inhibitor clinical trials.
Ontario
Ontario's provincial health authority funds mobile dermoscopy units serving First Nations communities in northern reaches. Health Canada coordinates parallel FDA review pathways for AI-dermoscopy algorithms. Toronto's University Health Network concentrates biologic therapy administration for Stage III-IV melanoma patients.
California
California leads employer-sponsored screening program adoption among Fortune 500 technology firms. The Medical Board of California regulates asynchronous teledermatology consultations with specific documentation requirements. Los Angeles and San Francisco Bay Area dermatology groups contract directly with occupational health departments for on-site full-body photography.
Florida
Florida reports the nation's highest per-capita melanoma incidence among retirees and seasonal residents. State Medicaid expansion under CMS guidance extends teledermatology reimbursement to rural counties. Miami and Tampa academic medical centers sustain double-digit annual growth in sentinel lymph node biopsy procedures.
Quebec
Quebec's provincial formulary prioritizes pembrolizumab-nivolumab combination protocols for advanced melanoma. The Collège des médecins du Québec sets practice standards for AI-assisted diagnostic tools. Montreal's McGill University Health Centre anchors oncology-dermatology co-management models for complex cutaneous malignancies.
US and Canada Skin Cancer Dermatology Market Key Industry Players
Imaging platform developers and AI-enabled screening specialists split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: precision hardware fabricators, software-centric algorithm developers, and integrated full-body photography networks. Consolidation pressure favors established manufacturers with pharmacovigilance infrastructure and regulatory submission expertise. Dominant competitive moves include strategic partnerships with academic medical centers and portfolio diversification into teledermatology workflow integration.
Within the imaging platform tier, Canfield Scientific, Inc. and FotoFinder Systems, Inc. occupy positions as precision hardware specialists serving North American academic medical centers. SkinIO exemplifies the AI-enabled screening network archetype, deploying automated full-body photography systems that streamline diagnostic throughput in high-volume practices. These three companies represent the dominant competitive positioning visible across the US and Canada dermatology device landscape.
| Leading Market Players |
|---|
| Firefly |
| SkinIO |
| Canfield Scientific, Inc. |
| FotoFinder Systems, Inc. |
| 3Gen |
| MetaOptima |
| Agilent Technologies |
| SkinVision |
| Speclipse, Inc. |
| Others |
Cost & Logistics Intelligence
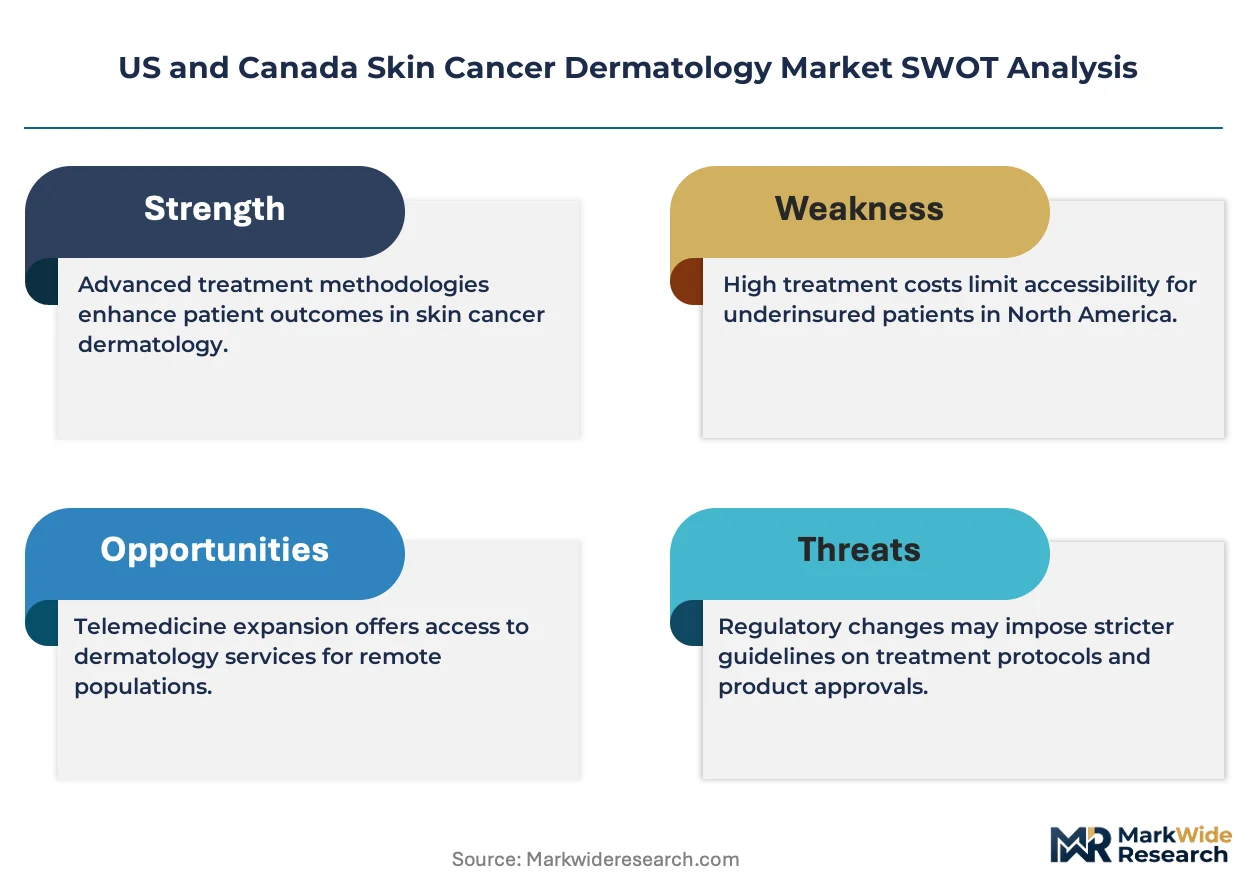
FDA 510(k) validation costs for AI-dermoscopy algorithms create a regulatory chokepoint that compresses margin spreads between premium imaging platforms and economy-tier alternatives while forcing device developers toward outsourced manufacturing partnerships in lower-cost jurisdictions.
Pricing Analysis
Texas hospital networks command 15-25% premiums over rural Montana clinics for identical Mohs micrographic surgery procedures due to specialist density and integrated oncology infrastructure. Pricing stratifies across premium, standard, and economy tiers based on certification grade (FDA 510(k) versus De Novo pathway) and after-sales service bundling. Cost compression in the economy tier intensifies because primary care physicians in underserved counties substitute teledermatology consultations for in-person specialist visits. Community dermatology practices in the Canadian prairies exhibit the highest price sensitivity, while academic medical centers in sun-belt states demonstrate the least.
Supply Chain Analysis
Optical sensor arrays and precision dermoscopy lenses draw from specialized component manufacturers in Germany, Japan, and the USA, with final assembly concentrating in facilities with ISO 13485 certification. German optical foundries and Japanese precision machining houses anchor upstream feedstock for high-resolution imaging hardware. Single-source vulnerability runs through Taiwan-based semiconductor fabricators supplying image processing chipsets for AI-enabled platforms. Distribution runs through authorized medical device distributors serving hospital purchasing committees and dermatology group procurement officers across North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private equity consolidation of dermatology clinics across Texas and Ontario has shifted bargaining power toward scaled buyer groups, compressing equipment vendor margins and favoring suppliers with integrated teledermatology workflow capabilities.
For Market Incumbents: Build regulatory submission expertise as a moat against emerging AI-software developers lacking pharmacovigilance infrastructure. Deepen backward integration into cloud-based image storage to capture recurring SaaS revenue from health systems. Expand fill-finish capacity for checkpoint inhibitors at existing US facilities to leverage IRA domestic manufacturing incentives against European biologic suppliers. For New Entrants and Emerging Players: Establish a beachhead in pharmacy-based screening kiosks at Shoppers Drug Mart and CVS Health locations, where asynchronous dermatologist review models bypass traditional clinic infrastructure requirements. Target the Manitoba-Saskatchewan corridor for mobile dermoscopy unit deployment, where provincial health authority procurement addresses specialist deserts through rotating clinic models. Pursue direct-to-employer contracts with Fortune 500 occupational health departments rather than fee-for-service patient acquisition. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors platform-integrated hardware vendors over standalone software developers. Long-term viability over the next decade hinges on interoperability capabilities that resolve proprietary image format fragmentation across Canfield, FotoFinder, and SkinIO ecosystems. Watch for Health Canada-FDA synchronized review pathway announcements as an inflection indicator for accelerated market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Accelerates market access for novel AI-dermoscopy algorithms beyond 510(k) equivalence pathways. |
| Hospital System Partnership | Locks in exclusive equipment procurement contracts with integrated Texas oncology-dermatology networks. |
| Software Companion Development | Enables seamless EHR integration for longitudinal lesion photography across proprietary imaging platforms. |
| Reimbursement Strategy | Secures CMS coverage determinations for teledermatology consultations in rural underserved counties. |
| CE Marking Pathway | Facilitates parallel Health Canada review for synchronized US-Canada commercialization timelines. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic directors, hospital purchasing committee members, biomedical engineers at imaging platform developers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and De Novo submission databases, Health Canada medical device licenses, CMS Medicare reimbursement determinations, and hospital procurement records. Bottom-up installation base estimates for dermoscopy devices were triangulated against top-down market size calculations derived from procedure volume data.
Calibration against historical adoption curves for diagnostic imaging technologies informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (surgical, biologic, topical, phototherapy), application severity (melanoma, basal cell carcinoma, squamous cell carcinoma, atypical nevi), end-user facility type, and technology modality. CAGRs were derived from elasticity-adjusted procedure volume projections and reimbursement trend analysis. Forecast inputs incorporated checkpoint inhibitor protocol expansion rates and AI-dermoscopy regulatory clearance timelines.
Stress conditions across Medicare reimbursement compression, FDA validation timeline extension, and dermatopathologist workforce contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding teledermatology adoption curves and immunotherapy enrollment trajectories. Cross-checking against provincial health authority procurement announcements in Ontario and Quebec is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Erythema Treatment Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Scar Treatment Oils Market
Dermatology
Global Hirsutism Market
Dermatology
Dermabrasion Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Australia Skin Laser Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Scar Treatment Market
Dermatology
Microdermabrasion Market
Dermatology
Global Dermatology Cro Market
Dermatology
Global Rosacea Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Dermatology Devices Market