
 Anti-Obesity Drugs Market | 2026-2036
Anti-Obesity Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Obesity Drugs Market Intelligence
The expansion of direct-to-consumer marketing for weight management therapies is narrowing the historical focus on treating only obesity-related comorbidities. Novo Nordisk sustains its market leadership through early mover advantage in the GLP-1 agonist space. Eli Lilly competes directly with a strong pipeline of similar mechanism-of-action drugs. Pfizer positions itself with a focus on developing next-generation oral formulations to challenge the dominance of injectables.
Anti-obesity drugs are pharmaceutical agents designed to induce weight loss by altering appetite, metabolism, or nutrient absorption. These therapies, such as GLP-1 agonists, function by mimicking incretin hormones to enhance insulin secretion and promote satiety. GLP-1 Agonists currently dominate the drug class segment due to superior efficacy and cardiovascular benefits. The mode of administration is shifting as research into effective oral tablets aims to displace the current standard of injectable solutions.
Regulatory pathways for these drugs are stringent, with agencies like the US FDA and Europe's EMA requiring extensive clinical trials focused on both efficacy and long-term cardiovascular safety. Approval processes set by China's NMPA are also becoming a critical factor for market access in Asia. Future investment decisions hinge on navigating these complex regulatory landscapes and demonstrating clear health economic benefits to payers.
Market Dynamics
The central dynamic in the anti-obesity drug market is the paradigm shift from treating obesity as a comorbidity to managing it as a chronic disease. This change, propelled by the high efficacy of GLP-1 agonists, is expanding the addressable patient population beyond severely obese individuals.
Growth Catalysts
- Expanded Insurance Coverage:Payers are increasingly covering anti-obesity medications as a preventative health measure, particularly in the United States, reducing the financial barrier for patients and encouraging long-term treatment adherence.
- Direct-to-Consumer Channels:The rise of telehealth platforms and direct-to-consumer marketing empowers patients to seek treatment proactively, accelerating demand outside of traditional specialist-centric care models.
- GLP-1 Agonist Efficacy:The superior weight loss outcomes and demonstrated cardiovascular benefits of GLP-1 agonist therapies are driving both physician and patient preference, establishing a new standard of care for medical weight management.
Market Restraints
- High Treatment Costs:The substantial out-of-pocket expense for uninsured or underinsured patients remains a significant barrier to access, limiting market penetration despite high clinical demand for these therapies.
- Manufacturing Bottlenecks:Supply chain constraints and complex manufacturing processes for injectable GLP-1 agonists create production shortages, failing to meet the full scope of global demand and leading to access issues.
- Regulatory Scrutiny on Safety:Stringent requirements from agencies like the US FDA and Europe's EMA for long-term cardiovascular outcome trials (CVOTs) create high development hurdles and extend timelines for new market entrants.
Strategic Opportunities
- Oral Formulation Development:Creating effective and safe oral alternatives to injectables presents a major opportunity to capture patients who are averse to needles, significantly improving treatment convenience and adherence.
- Expansion into Asian Markets:Untapped patient populations in countries like China and India, where obesity rates are rising alongside disposable income, offer substantial growth potential for pharmaceutical firms.
- Combination Therapies:Exploring therapies that combine GLP-1 agonism with other mechanisms, such as amylin or GIP agonism, provides a pathway to achieve even greater efficacy and address different patient metabolic profiles.
Industry Challenges
- Cold-Chain Logistics Complexity:Ensuring the integrity of injectable biologic drugs requires a sophisticated and expensive cold-chain distribution network, posing a significant operational challenge as volumes scale globally.
- Managing Public Perception:Navigating the public discourse surrounding the use of these drugs for aesthetic purposes versus medical necessity is a critical challenge for maintaining long-term market legitimacy and payer support.
- Intellectual Property Litigation:The high commercial value of leading GLP-1 agonists is attracting intense patent litigation from generic and biosimilar developers, creating uncertainty around future market exclusivity for innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Obesity Drugs Market |
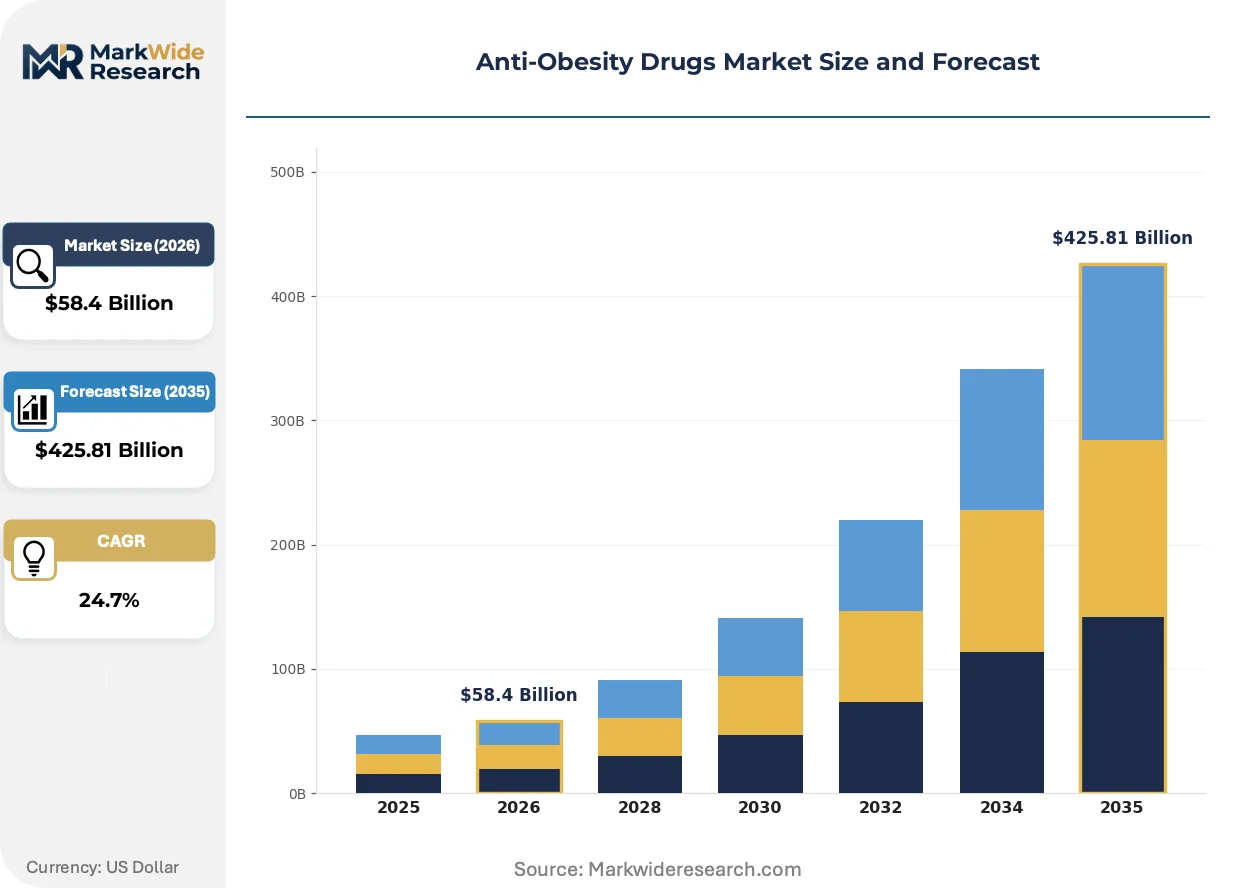
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $425.81 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: GLP-1 Agonists, Lipase Inhibitors, Appetite Suppressants, Combination Drugs, Serotonin Agonists Therapy Area: Weight Management, Metabolic Syndrome, Type 2 Diabetes, Cardiovascular Risk Reduction, Appetite Control End User: Hospitals, Ambulatory Surgical Centers, Wellness Clinics, Home Care, Specialty Pharmacies Mode of Administration: Oral Tablets, Injectable Solutions, Transdermal Patches, Sublingual Films, Nasal Sprays |
| Companies Covered | Structure Therapeutics, Merck, Eli Lilly, Roche, AstraZeneca, Novo Nordisk, Viking Therapeutics, Innovent Biologics, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Obesity Drugs Market Strategic Shifts & Innovations
The convergence of metabolic science and consumer-driven healthcare is redefining the anti-obesity drug market. Innovations are focused on improving patient experience and expanding therapeutic benefits beyond simple weight reduction, embedding these drugs into broader chronic disease management protocols.
Next-generation oral formulations of peptide-based therapies represent a significant product evolution. Patients seeking greater convenience and discretion are driving early interest in these pill-based alternatives to injectables. The distinction between injectable-only and oral treatment pathways for chronic weight management is collapsing, challenging the foundational delivery methods that have dominated the market to date.
Regulatory frameworks are increasingly emphasizing long-term health outcomes over simple efficacy metrics. The US FDA's requirement for extensive cardiovascular outcome trials (CVOTs) for new anti-obesity drugs sets a high bar for market entry. This mandate forces developers to demonstrate tangible health benefits, such as reduced risk of heart attack or stroke, which in turn justifies premium pricing and secures favorable formulary status with payers.
A notable demand-side shift is the move from physician-gatekept prescriptions to patient-initiated treatment requests through digital health channels. This trend, most visible in the United States, disintermediates traditional primary care pathways as patients use telehealth services and online pharmacies to access medications. This consumer-led model is fueled by aggressive social media and direct-to-consumer advertising campaigns that build brand awareness and drive patient inquiries.
Anti-Obesity Drugs Market Segmentation
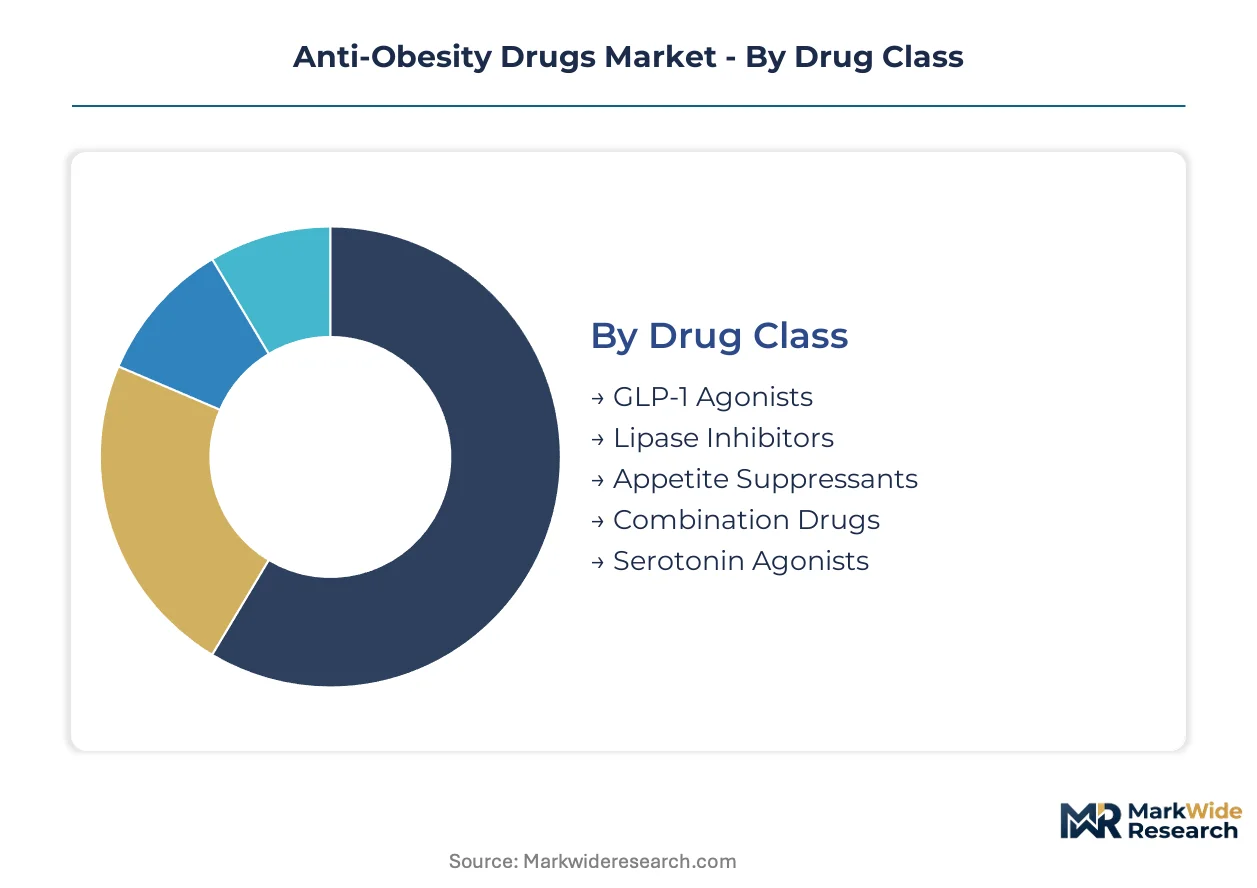
The Anti-Obesity Drugs Market segmentation provides a granular view of therapeutic approaches, patient demographics, and delivery mechanisms. Understanding these distinct categories helps pharmaceutical firms tailor development strategies and distribution channels for optimal market penetration.
Drug Class:
The anti-obesity drug market's segmentation by drug class reflects a maturity spectrum, from established mechanisms to advanced therapeutic innovations.
- GLP-1 Agonists:These pharmaceutical agents mimic incretin hormones, enhancing insulin secretion and promoting satiety, leading to superior weight loss and cardiovascular benefits. Demand concentrates in the United States, driven by high prevalence rates and patient awareness of efficacy.
- Combination Drugs:These therapies combine multiple mechanisms of action, such as GLP-1 agonism with GIP agonism, to achieve greater efficacy and address diverse metabolic profiles. Investment decisions hinge on demonstrating clear health economic benefits to payers.
- Lipase Inhibitors:These drugs reduce the absorption of dietary fats in the intestine, offering a non-systemic approach to weight management.
- Appetite Suppressants:These medications act on the central nervous system to reduce hunger and increase feelings of fullness.
- Serotonin Agonists:This class of drugs targets serotonin receptors in the brain to modulate appetite and food intake.
GLP-1 Agonists retains volume leadership; Combination Drugs holds the steepest expansion curve.
Therapy Area:
Segmentation by therapy area highlights the diverse application focus of anti-obesity drugs, moving beyond simple weight reduction.
- Weight Management:This area encompasses the primary use of anti-obesity drugs to induce and maintain weight loss for individuals with obesity or overweight conditions. The paradigm shift to managing obesity as a chronic disease expands the addressable patient population.
- Cardiovascular Risk Reduction:GLP-1 agonist therapies demonstrate significant cardiovascular benefits, reducing the risk of heart attack and stroke in patients with obesity. Regulatory agencies like the US FDA mandate extensive clinical trials for these long-term outcomes.
- Metabolic Syndrome:Anti-obesity drugs address components of metabolic syndrome, including high blood sugar, elevated blood pressure, and abnormal cholesterol levels.
- Type 2 Diabetes:Many anti-obesity medications, particularly GLP-1 agonists, are also approved for the management of type 2 diabetes due to their glucose-lowering effects.
- Appetite Control:This therapy area focuses on medications specifically designed to regulate hunger and satiety signals, aiding in dietary adherence.
Weight Management therapies drive broad market penetration, while Cardiovascular Risk Reduction solutions gain increasing adoption among specialists.
End User:
The end-user segmentation reveals evolving customer types and access points for anti-obesity therapies across healthcare settings.
- Wellness Clinics:These facilities increasingly offer preventative weight management solutions, positioning themselves as primary growth catalysts for anti-obesity drugs. Direct-to-consumer marketing strategies support patient engagement in these settings.
- Specialty Pharmacies:These pharmacies manage complex drug regimens and often provide patient support programs, becoming critical access points for high-cost, specialized anti-obesity medications. Telehealth platforms direct patients to these channels.
- Hospitals:Hospitals administer anti-obesity medications, particularly for patients with severe obesity or those undergoing bariatric surgery.
- Ambulatory Surgical Centers:These centers may prescribe anti-obesity drugs as part of pre- or post-surgical weight management protocols.
- Home Care:Patients self-administer injectable anti-obesity drugs at home, requiring specific training and ongoing support from healthcare providers.
Wellness Clinics are expanding patient reach, and Specialty Pharmacies are emerging as critical direct-to-consumer access points.
Mode of Administration:
The mode of administration segmentation reflects volume preferences and technological advancements in drug delivery.
- Injectable Solutions:These include pre-filled pens and vials for subcutaneous administration, currently dominating the GLP-1 agonist market due to established efficacy and delivery. Cold-chain logistics complexity remains a significant operational challenge for these biologic drugs.
- Oral Tablets:Next-generation oral formulations represent a significant product evolution, offering greater convenience and discretion for patients averse to needles. Development efforts aim to displace current injectable standards, expanding market access.
- Transdermal Patches:These patches deliver medication through the skin, providing a continuous and convenient administration method.
- Sublingual Films:These thin films dissolve under the tongue, allowing for rapid absorption of the active pharmaceutical ingredient.
- Nasal Sprays:Nasal sprays offer an alternative non-injectable route for systemic drug delivery, potentially improving patient adherence.
Injectable Solutions maintain their market dominance, but Oral Tablets are poised to revolutionize patient convenience and adherence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for anti-obesity drugs varies significantly across regions, with some markets demonstrating high price sensitivity while others prioritize access regardless of cost. The United States exhibits lower price elasticity due to high prevalence and strong insurance coverage. Conversely, emerging Asian markets often show greater sensitivity to out-of-pocket expenses.
United States
High prevalence rates and patient awareness drive significant demand for anti-obesity drugs. Expanded insurance coverage, particularly for preventative care, reduces financial barriers for patients. Major biotech hubs like Boston and San Francisco are centers for GLP-1 agonist research and development. The US FDA's stringent regulatory requirements for long-term cardiovascular safety shape product development.
China
Rising disposable incomes and increasing obesity rates fuel a growing market for anti-obesity drugs. The NMPA's approval processes are becoming critical for market access, influencing investment decisions by pharmaceutical firms. Shanghai's pharmaceutical innovation zones attract significant investment in metabolic disease therapies. Local companies are also developing novel solutions for the domestic market.
Germany
A robust healthcare system and a strong focus on chronic disease management support the adoption of advanced anti-obesity treatments. The EMA's stringent regulatory pathways ensure high safety and efficacy standards for new drug approvals across the European Union. Frankfurt's pharmaceutical industry contributes to European drug distribution and research. German payers increasingly cover these medications.
Japan
An aging population and increasing rates of metabolic disorders contribute to the demand for effective weight management solutions. PMDA guidelines emphasize long-term safety and cardiovascular outcomes for new drug approvals. Tokyo's research institutions are exploring novel therapeutic approaches for obesity. Pharmaceutical companies actively engage in clinical trials here.
India
Untapped patient populations and a rising middle class are creating substantial growth potential for anti-obesity drugs. The CDSCO's focus on affordable healthcare influences drug pricing and market entry strategies for both domestic and international players. Hyderabad's Pharma City is a key manufacturing hub for generic and patented medications. Patient awareness campaigns also support market expansion.
Anti-Obesity Drugs Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic market structure. The anti-obesity drug market is currently characterized by a tiered structure, with established pharmaceutical giants leading in R&D and market penetration. Strategic archetypes include innovative drug developers, generic manufacturers, and specialized wellness solution providers. Dominant competitive moves involve extensive R&D investment in novel drug classes and strategic partnerships aimed at expanding market access and securing regulatory approvals globally.
Within the innovative drug developer tier, Eli Lilly and Novo Nordisk exemplify market leadership through their advanced GLP-1 agonist portfolios and early mover advantages. Both companies are major pharmaceutical corporations, consistently investing in large-scale clinical trials and global distribution networks. Pfizer, another significant pharmaceutical corporation, occupies a position focused on next-generation oral formulations, challenging the dominance of injectable solutions. These organizations leverage their extensive research capabilities and established regulatory expertise to navigate complex approval processes worldwide. Their strategic focus on pipeline development and market expansion shapes the competitive dynamics.
| Leading Market Players |
|---|
| Structure Therapeutics |
| Merck |
| Eli Lilly |
| Roche |
| AstraZeneca |
| Novo Nordisk |
| Viking Therapeutics |
| Innovent Biologics |
| Pfizer |
| Others |
Cost & Logistics Intelligence
High-purity active pharmaceutical ingredient (API) sourcing in China and India directly influences the margin capture for innovative drug developers. Complex manufacturing for GLP-1 agonists further concentrates pricing power with established pharmaceutical giants.
Pricing Analysis
Long-term patient adherence to chronic anti-obesity treatments drives sustained revenue streams for pharmaceutical firms. The dominant pricing model is value-based, reflecting superior efficacy and demonstrated cardiovascular benefits. Price differentiation stems from regulatory approvals like US FDA designations and the strong brand premium of established GLP-1 agonists. Pricing pressure arises from payers demanding clear health economic benefits, making uninsured patients highly price-sensitive, while insured individuals show lower sensitivity.
Supply Chain Analysis
Stringent US FDA and European EMA quality controls restrict the flow of pharmaceutical ingredients and finished products into regulated markets. Geographic supply concentrates in China and India for key APIs, while complex biologic manufacturing resides in the US and Europe. Raw material dependencies include specialized excipients and pre-filled syringe components for injectables. Manufacturing bottlenecks represent a significant structural risk, impacting global availability, with distribution running through specialty pharmacies and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-obesity drugs market presents a strong defensive moat, primarily due to significant regulatory entrenchment. Extensive clinical trials, particularly for long-term cardiovascular outcomes, create substantial barriers to entry and high switching costs for patients.
For Market Incumbents: Pre-empt emerging oral formulation competition by accelerating internal R&D for next-generation non-injectable therapies. Expand global manufacturing capacity for existing GLP-1 agonists to address persistent supply bottlenecks and secure market share. Invest in comprehensive real-world evidence studies to further demonstrate long-term cardiovascular benefits, reinforcing payer support against potential cost-containment pressures. Control distribution channels through strategic partnerships with specialty pharmacies.
For New Entrants and Emerging Players: Pursue white-space opportunities in combination therapies, leveraging novel mechanisms to achieve superior efficacy beyond GLP-1 agonism. Target underpenetrated Asian markets like China and India, where rising disposable incomes and obesity rates offer substantial patient populations. Develop differentiated oral formulations to capture patients averse to injectables, offering a compelling convenience-led go-to-market angle. Focus on demonstrating clear health economic benefits to secure payer acceptance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with biotech startups developing novel anti-obesity mechanisms or specialized wellness clinic chains. The market offers long-term viability, driven by the shift to chronic disease management and an expanding addressable patient population over the next decade. Identify acquisition targets with advanced oral formulation pipelines or unique combination therapy assets demonstrating superior efficacy. Monitor successful Phase 3 clinical trial readouts for oral GLP-1 agonists as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerating Phase 3 trials for novel oral formulations can redefine patient adherence for pharmaceutical firms. |
| Manufacturing Scale-Up | Expanding GLP-1 agonist production capacity addresses global demand and mitigates supply chain bottlenecks. |
| Licensing Agreement | Securing rights to next-generation mechanisms from biotech firms diversifies therapeutic portfolios for pharmaceutical corporations. |
| Pipeline Diversification | Investing in non-GLP-1 targets addresses broader metabolic profiles and reduces reliance on a single drug class. |
| Regulatory Approval Pathway | Navigating NMPA and PMDA processes unlocks substantial growth potential in Asian markets for pharmaceutical companies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather comprehensive primary insights for this analysis. Interviews included drug development executives, regulatory affairs leads, formulary directors, and wellness clinic operators. Secondary validation drew from US FDA filings, EMA submissions, ClinicalTrials.gov, and pharmaceutical industry reports. This approach ensured bottom-up and top-down triangulation across diverse data points.
Quantitative models were calibrated using historical market trends and projected pipeline advancements across the analysis window. Segmentation dimensions included drug class, therapy area, end user, mode of administration, and regional regulatory clusters. Compound annual growth rates were derived from projected patient adoption rates and anticipated product launches. Key forecast inputs incorporated clinical trial success rates and evolving payer reimbursement policies.
Sensitivities concentrate around unforeseen regulatory changes and major clinical trial failures for late-stage pipeline drugs. Forecasts reflect assumptions documented from current market dynamics and expected technological advancements. Material shifts in major payer coverage decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global Blood Plasma Derivatives Market