
 Direct Oral Anticoagulants Market | 2026-2036
Direct Oral Anticoagulants Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Oral Anticoagulants Market Outlook
Hospital buying consolidation is pivoting as integrated delivery networks narrow anticoagulant formularies to two or three preferred agents. Johnson & Johnson leverages its cardiovascular portfolio breadth to sustain hospital contract positioning. Bristol-Myers Squibb anchors Medicaid and Medicare Part D access through extensive rebate structures. Boehringer Ingelheim competes on thrombin reversal agent availability, differentiating its dabigatran franchise in emergency settings.
Direct oral anticoagulants are small-molecule inhibitors targeting either factor Xa or thrombin, formulated for fixed-dose oral administration without routine coagulation monitoring, replacing vitamin K antagonists in stroke prevention and venous thromboembolism management. Apixaban and rivaroxaban now dominate new prescriptions among factor Xa inhibitors due to accumulated real-world safety data and once-daily or twice-daily dosing flexibility. The geriatric patient segment generates concentrated volume as aging populations with atrial fibrillation require long-term therapy, while online pharmacies represent the fastest-expanding distribution channel driven by mail-order benefit designs and chronic disease management programs.
FDA label expansions and EMA pharmacovigilance requirements shape clinical trial investment and post-market surveillance obligations for manufacturers. The European MDR intensifies device-drug combination scrutiny where DOACs pair with delivery systems or monitoring technologies. Stakeholders must monitor CMS national coverage determinations and FDA guidance on switching studies as biosimilar and generic entrants approach the market horizon.
Market Dynamics
Hospital formulary consolidation by integrated delivery networks is compressing competitive access for direct oral anticoagulants, forcing manufacturers to secure preferred status through bundled cardiovascular contracts and emergency reversal agent availability rather than standalone pricing.
Growth Catalysts
- Medicare Part D reimbursement:US outpatient DOAC initiation policies accelerate prescriber conversion from warfarin in atrial fibrillation patients.
- EMA pharmacovigilance frameworks:Post-market surveillance obligations build prescriber confidence through accumulated real-world safety databases.
- Geriatric population concentration:Aging demographics with chronic anticoagulation needs generate sustained volume for stroke prevention therapies.
Market Restraints
- Rebate-dependent access structures:Extensive Medicaid and Medicare rebate requirements compress net margins for manufacturers competing on formulary placement.
- Thrombin reversal agent supply concentration:Emergency setting differentiation depends on single-source reversal agent availability, creating dependency risk.
- Warfarin substitution persistence:Decades of clinical familiarity and established monitoring infrastructure sustain vitamin K antagonist use in cost-sensitive settings.
Strategic Opportunities
- Mail-order pharmacy channel expansion:Chronic disease management programs and benefit design shifts favor online pharmacy distribution for long-term therapy adherence.
- Device-drug combination innovation:European MDR scrutiny creates first-mover advantage for manufacturers pairing DOACs with delivery systems or monitoring technologies.
- Japan's aging demographic:METI healthcare policy prioritization of stroke prevention creates concentrated demand for oral anticoagulation in East Asian geriatric populations.
Industry Challenges
- Switching study design complexity:FDA guidance on biosimilar and generic switching studies demands extensive clinical trial investment before market entry.
- Integrated network contract negotiation:Narrowed formularies to two or three preferred agents intensifies competitive bidding and threatens margin sustainability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Oral Anticoagulants Market |
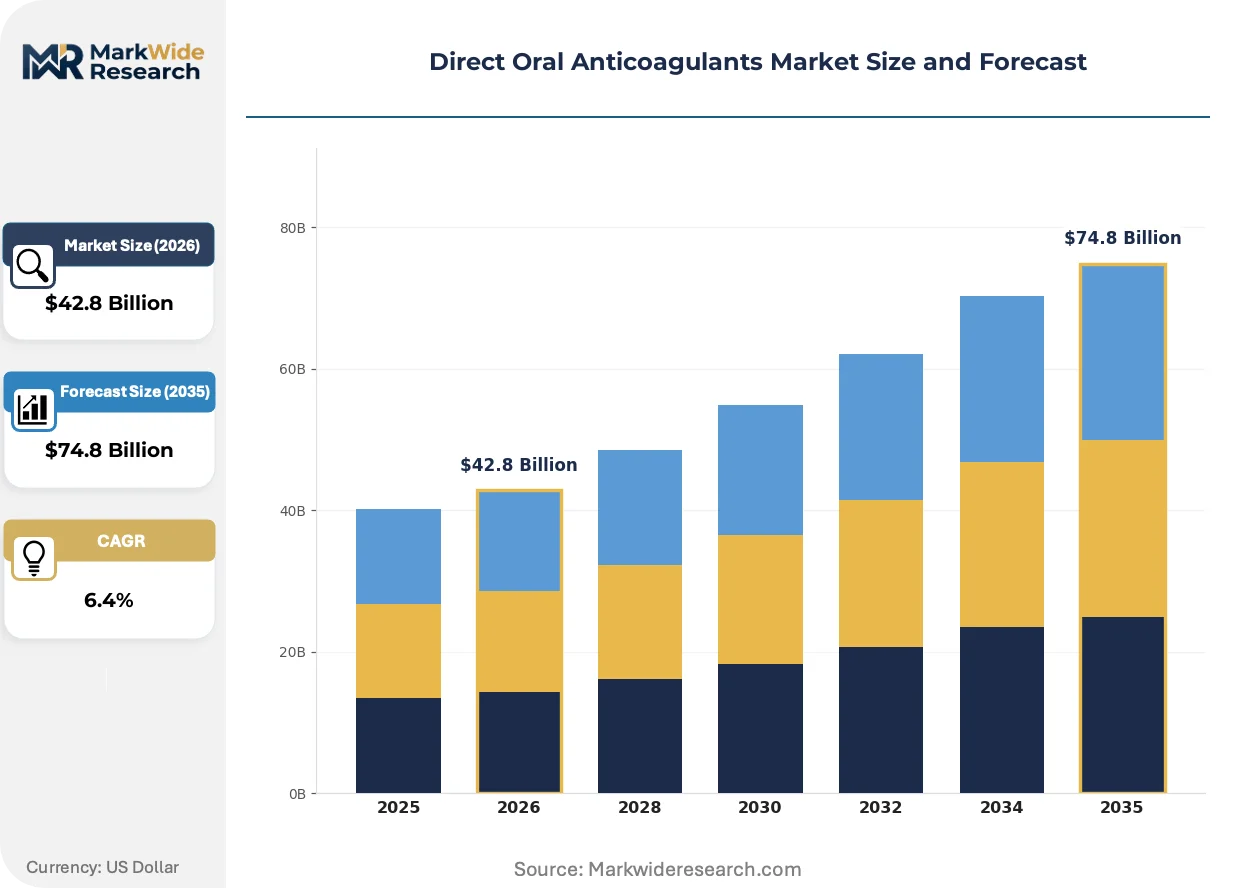
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dabigatran, Rivaroxaban, Apixaban, Edoxaban Indication: Atrial Fibrillation, Deep Vein Thrombosis, Pulmonary Embolism, Postoperative Thromboprophylaxis Patient Type: Geriatric Patients, Patients with Atrial Fibrillation, Patients with Thromboembolic Disorders, Surgical Patients Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Johnson & Johnson, Daiichi Sankyo Company Ltd., Bristol-Myers Squibb, Sanofi, GlaxoSmithKline, Pfizer Inc., Boehringer Ingelheim, Abbott Laboratories, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Oral Anticoagulants Market Strategic Shifts
Real-world evidence generation and digital adherence monitoring are reshaping how direct oral anticoagulants demonstrate value and sustain long-term patient retention in competitive formularies.
Point-of-care coagulation monitoring technology is integrating with smartphone-connected testing devices to enable patient self-management without routine laboratory visits. Geriatric patients and rural healthcare providers are adopting these systems fastest, drawn by reduced travel burden and immediate result availability. This integration is compressing the traditional laboratory testing infrastructure and shifting clinical oversight toward remote monitoring platforms.
EMA's Medical Device Regulation intensifies scrutiny of combination products where anticoagulants pair with automated delivery or adherence-tracking systems. Manufacturers must now submit joint technical documentation spanning pharmaceutical and device quality standards, extending approval timelines by twelve to eighteen months. Cardiology-focused companies with existing device competencies are responding by building in-house regulatory affairs capabilities for dual-submission pathways.
Hospital buying committees are consolidating anticoagulant procurement decisions at integrated delivery network level rather than individual facility pharmacy committees. This concentration displaces traditional pharmaceutical rep-driven prescriber influence with centralized value-analysis teams evaluating total cost of bleeding complications and reversal agent access. The United States exhibits this pattern most acutely, where three-network concentration in major metropolitan markets now dictates regional prescribing patterns.
Direct Oral Anticoagulants Market Segmentation
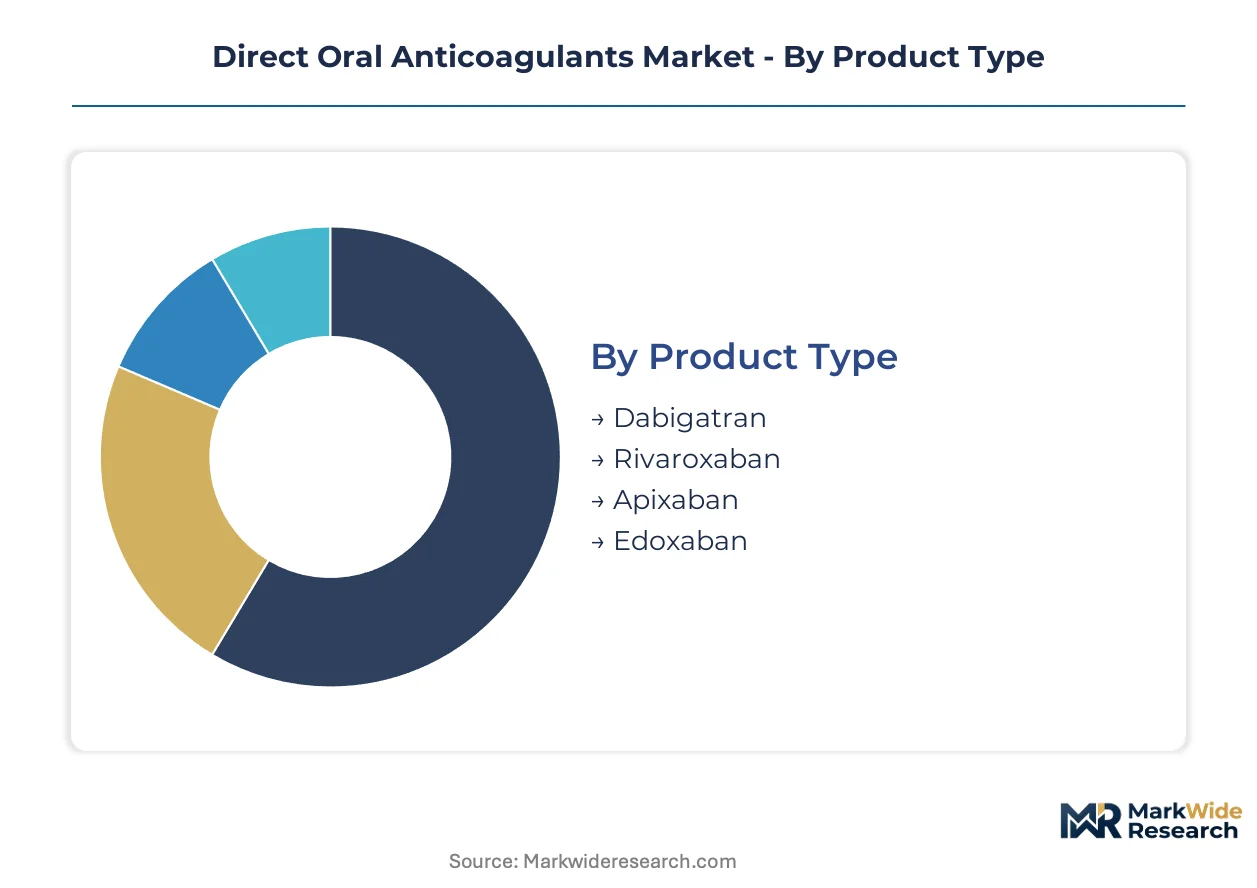
Anticoagulant manufacturers compete across four distinct segmentation axes that determine pricing power, prescriber access, and long-term patient retention. Product type and indication splits reveal where clinical evidence investments yield formulary placement, while patient type and distribution channel segmentation exposes reimbursement-driven demand concentration.
Product Type:
Factor Xa inhibitors command premium positioning against direct thrombin inhibitors due to accumulated real-world safety databases and flexible dosing regimens.
- Apixaban:Twice-daily dosing with established renal clearance pathways concentrates demand among elderly patients with fluctuating kidney function. Medicare Part D formularies favor apixaban for stroke prevention in atrial fibrillation due to reduced intracranial hemorrhage rates versus warfarin.
- Rivaroxaban:Once-daily administration improves adherence in chronic therapy settings. Hospital formularies select rivaroxaban for venous thromboembolism treatment based on single-tablet loading dose protocols and emergency department discharge efficiency.
- Dabigatran:Direct thrombin inhibition with specific reversal agent availability differentiates emergency setting access. Boehringer Ingelheim's idarucizumab supply anchors hospital contract positioning.
- Edoxaban:Once-daily factor Xa inhibition with reduced renal clearance burden serves Japanese and European markets where regulatory pathways favor streamlined pharmacovigilance.
Apixaban and rivaroxaban absorb the bulk of installed manufacturing capacity; edoxaban is expanding most quickly in Asia-Pacific markets.
Indication:
Stroke prevention versus acute thrombosis management creates divergent clinical trial investment requirements and prescriber education needs.
- Atrial Fibrillation:Chronic oral anticoagulation for stroke prevention generates sustained prescription volume in aging populations. FDA label expansions and EMA pharmacovigilance frameworks accelerate prescriber conversion from vitamin K antagonists.
- Deep Vein Thrombosis:Acute treatment and extended prophylaxis require rapid onset formulations. Hospital-based initiation protocols favor agents with predictable pharmacokinetics and minimal drug-drug interaction profiles.
- Pulmonary Embolism:High-risk acute management demands parenteral-to-oral transition pathways. Mortality outcome data drives formulary selection in intensive care settings.
- Postoperative Thromboprophylaxis:Orthopedic and abdominal surgery protocols specify short-duration prophylaxis. Cost-sensitive institutional purchasing compresses margins for manufacturers competing on surgical ward access.
Atrial fibrillation stroke prevention captures the largest share of prescription volume; postoperative thromboprophylaxis is gaining share fastest as enhanced recovery after surgery protocols standardize anticoagulant use.
Patient Type:
Age-related physiological changes and comorbidity burden determine dosing complexity and monitoring requirements across patient populations.
- Geriatric Patients:Polypharmacy interactions and fall risk complicate therapy selection. Renal function decline necessitates dose adjustments and periodic monitoring.
- Patients with Atrial Fibrillation:CHA2DS2-VASc score stratification identifies candidates for long-term anticoagulation. Bleeding risk assessment tools guide agent selection.
- Patients with Thromboembolic Disorders:Recurrent event history and hereditary thrombophilia influence duration of therapy decisions.
- Surgical Patients:Perioperative bridging protocols require reversible agents with predictable offset. Anesthesiology and surgery department coordination determines formulary inclusion.
Geriatric patients absorb the bulk of chronic therapy prescriptions; surgical patients are climbing fastest as preoperative risk stratification expands anticoagulant initiation.
Distribution Channel:
Reimbursement structure and therapy duration determine channel economics and patient adherence program design.
- Hospital Pharmacies:Integrated delivery network formulary consolidation compresses competitive access to two or three preferred agents. Emergency reversal agent availability anchors contract negotiations.
- Retail Pharmacies:Community-based chronic therapy dispensing supports patient counseling and adherence monitoring. Medicare Part D benefit designs favor retail network participation.
- Online Pharmacies:Mail-order benefit structures and 90-day supply incentives reduce patient cost burden. Chronic disease management programs integrate digital adherence tracking.
- Direct Sales:Institutional purchasing agreements and specialty pharmacy relationships serve closed health system environments.
Hospital pharmacies absorb the bulk of acute initiation volume; online pharmacies are expanding most quickly as mail-order benefit designs penetrate Medicare Advantage plans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for direct oral anticoagulants clusters in the United States, Germany, Japan, Switzerland, and India, with regulatory pathways and reimbursement structures shaping regional market penetration.
United States
Medicare Part D reimbursement policies accelerate outpatient DOAC initiation for atrial fibrillation patients, displacing warfarin in chronic stroke prevention. FDA label expansions for factor Xa inhibitors build prescriber confidence through accumulated real-world safety databases. The Boston-Cambridge pharmaceutical corridor hosts clinical trial operations and medical affairs functions for multiple manufacturers competing on formulary placement.
Germany
EMA pharmacovigilance frameworks and the Medical Device Regulation intensify post-market surveillance obligations for anticoagulant manufacturers. Federal Joint Committee (G-BA) health technology assessments determine reimbursement eligibility for novel oral anticoagulants. The Rhine-Main biopharma cluster concentrates regulatory affairs expertise and pharmacovigilance operations serving European markets.
Japan
METI healthcare policy prioritization of stroke prevention in aging populations creates concentrated demand for oral anticoagulation therapies. PMDA streamlined review pathways for cardiovascular drugs accelerate market entry for agents with established global safety profiles. The Kansai-Osaka pharmaceutical manufacturing belt houses formulation facilities serving domestic and Asia-Pacific export markets.
Switzerland
Swissmedic regulatory efficiency and bilateral recognition agreements with EMA attract European headquarters functions for anticoagulant developers. Pricing and reimbursement negotiations with health insurers emphasize total cost of care including bleeding complication management. The Basel pharmaceutical hub concentrates cardiovascular research operations and medical science liaison teams.
India
CDSCO abbreviated approval pathways for drugs with established USFDA or EMA authorization enable rapid market entry for generic DOAC formulations. Central Drugs Standard Control Organization manufacturing facility inspections intensify as export-oriented production scales for regulated markets. The Hyderabad-Visakhapatnam bulk drug corridor expands active pharmaceutical ingredient capacity for factor Xa inhibitor intermediates.
Direct Oral Anticoagulants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biosimilar development and regional licensing arrangements. The vendor base concentrates among integrated pharmaceutical conglomerates with cardiovascular portfolio breadth and specialized anticoagulant developers with reversal agent capabilities. Three archetypes dominate: diversified conglomerates leveraging hospital contract bundling, thrombin-focused specialists differentiating on emergency reversal availability, and factor Xa innovators competing on real-world safety databases. Competitive moves center on integrated delivery network formulary consolidation and bundled cardiovascular service contracts.
Among diversified pharmaceutical conglomerates, Johnson & Johnson and Bristol-Myers Squibb occupy positions exemplifying hospital contract breadth and government payer rebate structuring respectively. Boehringer Ingelheim represents the thrombin-inhibition archetype with differentiated emergency setting access. These three anchors illustrate how competitive positioning depends on portfolio integration depth rather than standalone anticoagulant pricing power.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Daiichi Sankyo Company Ltd. |
| Bristol-Myers Squibb |
| Sanofi |
| GlaxoSmithKline |
| Pfizer Inc. |
| Boehringer Ingelheim |
| Abbott Laboratories |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Specialized organic synthesis chemists in the Hyderabad-Visakhapatnam corridor anchor active pharmaceutical ingredient production cost structures, with labor-cost differentials between Indian bulk manufacturers and Swiss formulation facilities driving 40-60% spreads between economy-tier generics and premium-branded factor Xa inhibitors.
Pricing Analysis
Volume concentration in Medicare Part D formularies compresses margins on high-unit chronic therapies, while emergency reversal agent bundling preserves premium positioning for thrombin-focused portfolios. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA approval pathway and pharmacovigilance database depth. Pricing pressure stems from integrated delivery network formulary narrowing to two preferred agents. Medicaid rebate-dependent access structures render government payers most price-sensitive; hospital emergency departments least sensitive due to reversal agent availability requirements.
Supply Chain Analysis
Dual-sourcing mandates from FDA and EMA inspectors force manufacturers to qualify backup API suppliers in India and Switzerland alongside primary German and Japanese synthesis partners. Factor Xa inhibitor production draws from pyrazole and chlorothiophene intermediate streams, with idarucizumab reversal agent supply tethered to single-source biologics capacity. Single-source vulnerability concentrates in Boehringer Ingelheim's idarucizumab manufacturing. Distribution runs through integrated delivery network central warehouses for hospital initiation, with mail-order pharmacies capturing chronic therapy refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated delivery network formulary consolidation to two or three preferred agents functions as a forced exit mechanism, pressuring standalone anticoagulant developers without cardiovascular portfolio breadth or reversal agent capabilities to seek acquisition or abandon the category.
For Market Incumbents: To counter biosimilar and generic entrants approaching the market horizon, Johnson & Johnson and Bristol-Myers Squibb should deepen hospital contract bundling across cardiovascular portfolios while investing in digital adherence monitoring platforms that demonstrate real-world outcome differentiation. Securing preferred status through bundled contracts rather than standalone pricing preserves margin sustainability.
For New Entrants and Emerging Players: Launch via online pharmacy channel partnerships targeting Medicare Advantage mail-order benefit designs, where formulary access barriers are lower than hospital procurement. White-space targets include Japan's aging geriatric population and postoperative thromboprophylaxis protocols in cost-sensitive surgical settings. Pursue CDSCO abbreviated approval pathways in India to establish API supply relationships before seeking regulated market entry.
For Investors and Strategic Acquirers: Re-rating potential sits with thrombin-focused specialists possessing idarucizumab-equivalent reversal agent capabilities given FDA guidance complexity on switching studies that extends generic development timelines. Five-to-ten year viability favors developers with dual-submission competency under European MDR for device-drug combinations. Monitor CMS national coverage determinations on outpatient DOAC initiation as the signal for prescriber conversion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reversal Agent Supply Security | Emergency department formulary placement hinges on idarucizumab or andexanet alfa availability guarantees. |
| Real-World Evidence Generation | Post-market surveillance databases under EMA pharmacovigilance frameworks build prescriber confidence against warfarin. |
| Mail-Order Pharmacy Integration | Medicare Advantage benefit designs favor 90-day supply channels with digital adherence tracking capabilities. |
| Device-Drug Combination Development | European MDR joint technical documentation requirements create twelve-to-eighteen month first-mover regulatory advantages. |
| Integrated Network Contract Bundling | Hospital value-analysis teams evaluate total bleeding complication costs rather than per-unit anticoagulant pricing. |
Study Parameters
Document review covered FDA label expansion filings, EMA pharmacovigilance assessment reports, ClinicalTrials.gov protocol registrations, and integrated delivery network formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from CMS Medicare Part D utilization data, SEC 10-K pharmaceutical segment disclosures, and GPO contract repositories. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue segmentation.
Output metrics span value projections and unit demand across the analysis window, with segmentation modeling across factor Xa versus thrombin inhibition mechanisms, stroke prevention versus acute thrombosis indications, geriatric versus surgical patient populations, and hospital versus online pharmacy distribution channels. CAGRs derive from polynomial trend fitting to historical prescription data adjusted for demographic aging trajectories and regulatory label expansion schedules. Forecast inputs incorporate Medicare reimbursement policy shifts and EMA Medical Device Regulation implementation timelines.
Generic switching study design complexity, thrombin reversal agent supply disruption, and CMS national coverage determination revision are the dominant revision risks to the outlook. Deviation in integrated delivery network formulary consolidation speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market