
 Pharmaceutical Manufacturing Market | 2026-2036
Pharmaceutical Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Manufacturing Market Analytics
Biologics contract manufacturing revenue is rewriting margin distribution across the pharmaceutical value chain. Lonza leverages its mammalian cell culture infrastructure to dominate high-complexity monoclonal antibody production. Samsung Biologics sustains capacity leadership through single-use bioreactor scale-outs in South Korea. Pfizer anchors North American biologics supply with integrated fill-finish networks.
Pharmaceutical manufacturing encompasses the industrial synthesis, purification, formulation, and packaging of drug substances into finished dosage forms, with biologics requiring mammalian or microbial cell culture at controlled temperatures between 35°C and 37°C and pH ranges of 6.8 to 7.4 to maintain protein integrity. The primary commercial purpose is to convert raw chemical or biological starting materials into regulatory-compliant medicines for human therapeutic use. Active Pharmaceutical Ingredients command the largest value share due to synthetic complexity and regulatory filing requirements, while continuous processing represents the fastest-expanding manufacturing technology as firms pursue real-time quality assurance and reduced batch failure rates. Injectables capture disproportionate capital allocation because sterile formulation demands isolate barrier technology and automated visual inspection systems.
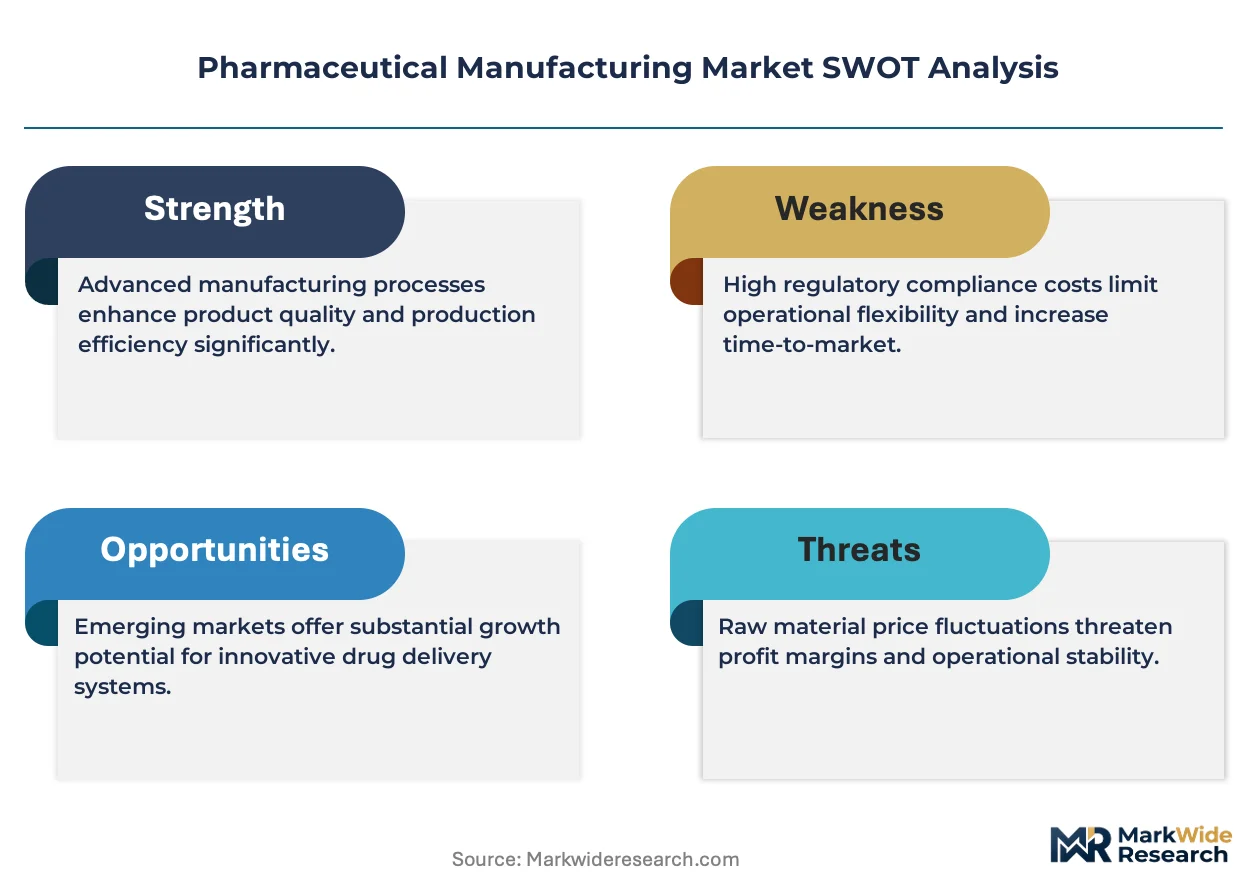
The FDA enforces Current Good Manufacturing Practice through facility inspections and warning letters that directly determine market access for US-bound products, while the EMA's Good Manufacturing Practice guidelines and the EU's Falsified Medicines Directive mandate serialization and anti-tampering verification across European supply chains. India's CDSCO aligns with WHO prequalification standards to facilitate export eligibility for domestic manufacturers. Stakeholders must monitor how the FDA's advanced manufacturing technologies designations and the EU AI Act's deployment rules for automated process control reshape capital deployment priorities for new facility builds.
Market Dynamics
The FDA's Quality Management Maturity program is forcing pharmaceutical manufacturers to upgrade facility infrastructure ahead of inspection cycles, while biotech firms expand proprietary API capacity and reshape procurement patterns across the value chain.
Growth Catalysts
- Biotech Pipeline Expansion:Emerging biotech companies are building captive manufacturing capabilities for complex biologics, driving demand for mammalian cell culture infrastructure and specialized CDMO partnerships.
- EMA Falsified Medicines Directive:Serialization mandates across European supply chains are accelerating investments in automated packaging lines and track-and-trace systems at contract manufacturing sites.
- Sterile Injectable Capacity:India-based contract manufacturers are expanding isolator-based filling lines to serve European and North American clients seeking redundant supply sources for critical medicines.
Market Restraints
- Specialized Raw Material Concentration:Cell culture media and single-use bioreactor components depend on concentrated suppliers in Germany and the United States, creating vulnerability to export restrictions.
- Facility Qualification Timelines:FDA pre-approval inspections and EMA site certifications impose 18-to-24-month validation cycles that delay revenue recognition for new manufacturing assets.
- Plasma-Derived Substitution:Recombinant protein technologies are displacing fractionated plasma products in multiple therapeutic categories, stranding capacity at legacy plasma processing facilities.
Strategic Opportunities
- Continuous Processing Adoption:Real-time release testing and flow chemistry integration offer quality assurance advantages that batch manufacturers struggle to match.
- India PLI Scheme:Production-linked incentives for active pharmaceutical ingredients are attracting greenfield investments in Kharagpur and Visakhapatnam manufacturing clusters.
- Personalized Medicine Infrastructure:Autologous cell therapy manufacturing requires distributed cleanroom networks that existing CDMOs can retrofit for patient-specific batch sizes.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Mammalian cell line development and scale-up optimization require specialized expertise that universities produce insufficiently relative to facility expansion rates.
- Legacy System Integration:Paper-based batch records and isolated equipment controllers obstruct data integrity compliance for manufacturers pursuing FDA advanced manufacturing designations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Manufacturing Market |
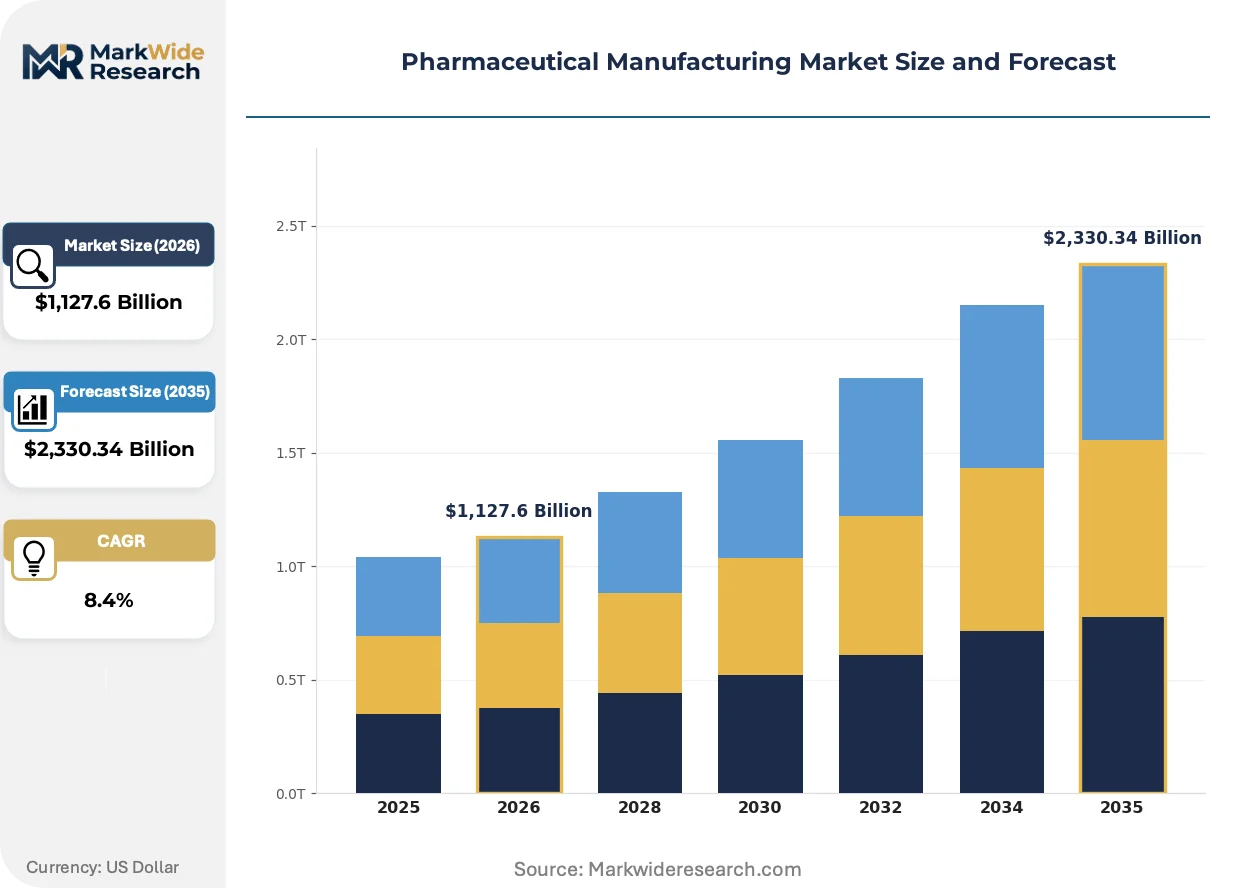
| Market Size in 2026 | $1,127.6 Billion |
| Market Size in 2035 | $2,330.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pharmaceutical Ingredients, Biologics, Generics, Over-the-Counter Manufacturing Technology: Continuous Processing, Batch Processing, Fermentation, Filtration End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Research Institutions Formulation Type: Tablets, Injectables, Liquids, Topicals |
| Companies Covered | Johnson & Johnson, Merck & Co., Pfizer, AbbVie, AstraZeneca, Roche, Novartis, Samsung Biologics, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Manufacturing Market Evolving Landscape
Digital twin technology is virtualizing process development workflows, while regulatory agencies accelerate guidance for continuous manufacturing and real-time quality verification systems.
Digital twin platforms are replicating bioreactor performance and purification train behavior before physical validation runs. Large-molecule developers at mid-cap biotechs are deploying these tools to compress timeline risk on first-in-human programs. This capability is virtualizing capital allocation decisions by allowing firms to model facility utilization and debottlenecking scenarios without committing to steel-in-the-ground investments.
The EU AI Act's deployment rules for automated process control systems are establishing conformity assessment requirements for machine learning models that adjust bioreactor parameters in real time. Pharmaceutical manufacturers must document algorithm training datasets and validation protocols to maintain GMP compliance. High-complexity biologics facilities in Ireland and the Netherlands are prioritizing explainable AI architectures that satisfy both process analytical technology goals and regulatory audit trails.
CDMO selection criteria now weight geographic redundancy and dual-sourcing capability above unit cost optimization. Biotech procurement teams are splitting commercial batches across multiple contract manufacturers to mitigate single-site regulatory action risk. This pattern is most pronounced among sponsors preparing for FDA pre-approval inspections, where supply continuity assumptions factor heavily into reimbursement negotiations with pharmacy benefit managers.
Pharmaceutical Manufacturing Market Segmentation
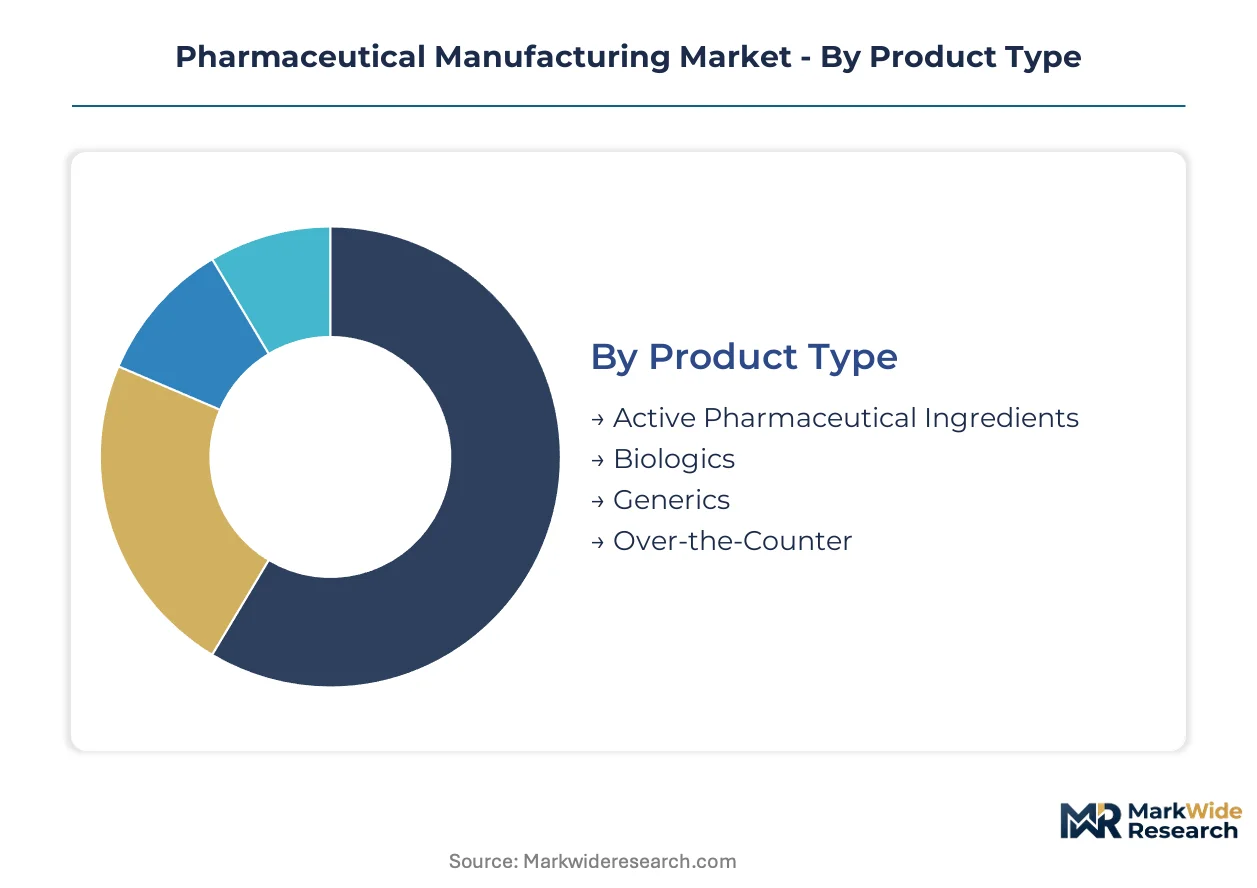
Segmentation in pharmaceutical manufacturing reveals how capital allocation, regulatory burden, and technical capability distribute across distinct production modes and customer relationships. Understanding these divides explains why API suppliers command pricing power while biologics manufacturers absorb disproportionate facility investment.
Product Type:
Cost tier determines margin structure and capital intensity across pharmaceutical output categories, with synthetic complexity and regulatory filing burden as the primary differentiators.
- Active Pharmaceutical Ingredients:Synthetic organic molecules and chemically derived drug substances requiring multi-step synthesis, crystallization, and impurity profiling. Demand concentrates in India and China where CDMOs serve European and North American innovators seeking cost-competitive small-molecule supply.
- Biologics:Therapeutic proteins manufactured through mammalian cell culture or microbial fermentation under tightly controlled environmental parameters. Investment flows toward South Korean and Irish facilities where single-use bioreactor infrastructure supports monoclonal antibody commercialization.
- Generics:Off-patent small-molecule formulations competing on manufacturing efficiency and regulatory filing speed.
- Over-the-Counter:Consumer-directed medicines with lower regulatory barriers and higher volume throughput requirements.
Active Pharmaceutical Ingredients commands the established base. The steepest expansion runs through Biologics.
Manufacturing Technology:
Process maturity separates legacy batch infrastructure from emerging continuous platforms that promise real-time quality assurance and reduced failure rates.
- Continuous Processing:Integrated flow chemistry and real-time release testing systems that eliminate discrete batch boundaries. FDA advanced manufacturing designations are accelerating adoption among sponsors seeking competitive differentiation in pre-approval inspection cycles.
- Batch Processing:Discrete unit operations with defined start and end points, validated through traditional process analytical technology protocols.
- Fermentation:Microbial cell culture systems for antibiotic and recombinant protein production.
- Filtration:Tangential flow and depth filtration operations for biologics purification and viral clearance.
Batch Processing retains the installed base. Continuous Processing is gaining share fastest among new facility investments.
End User:
Customer type dictates contract structure, quality agreement complexity, and geographic sourcing strategy across the pharmaceutical value chain.
- Pharmaceutical Companies:Integrated innovators with captive manufacturing networks and outsourced capacity for peak demand or specialized modalities. Procurement teams prioritize dual-sourcing and geographic redundancy to mitigate regulatory action risk.
- Biotech Firms:Emerging developers building proprietary pipeline capacity for complex biologics. Mammalian cell culture infrastructure investments are reshaping API procurement patterns as these firms expand beyond discovery-stage outsourcing.
- Contract Manufacturers:CDMOs serving multiple sponsors under quality agreements and facility sharing arrangements.
- Research Institutions:Academic and government laboratories requiring small-scale GMP manufacturing for clinical trial materials.
Pharmaceutical Companies anchor the demand base. Biotech Firms show the steepest capacity expansion trajectory.
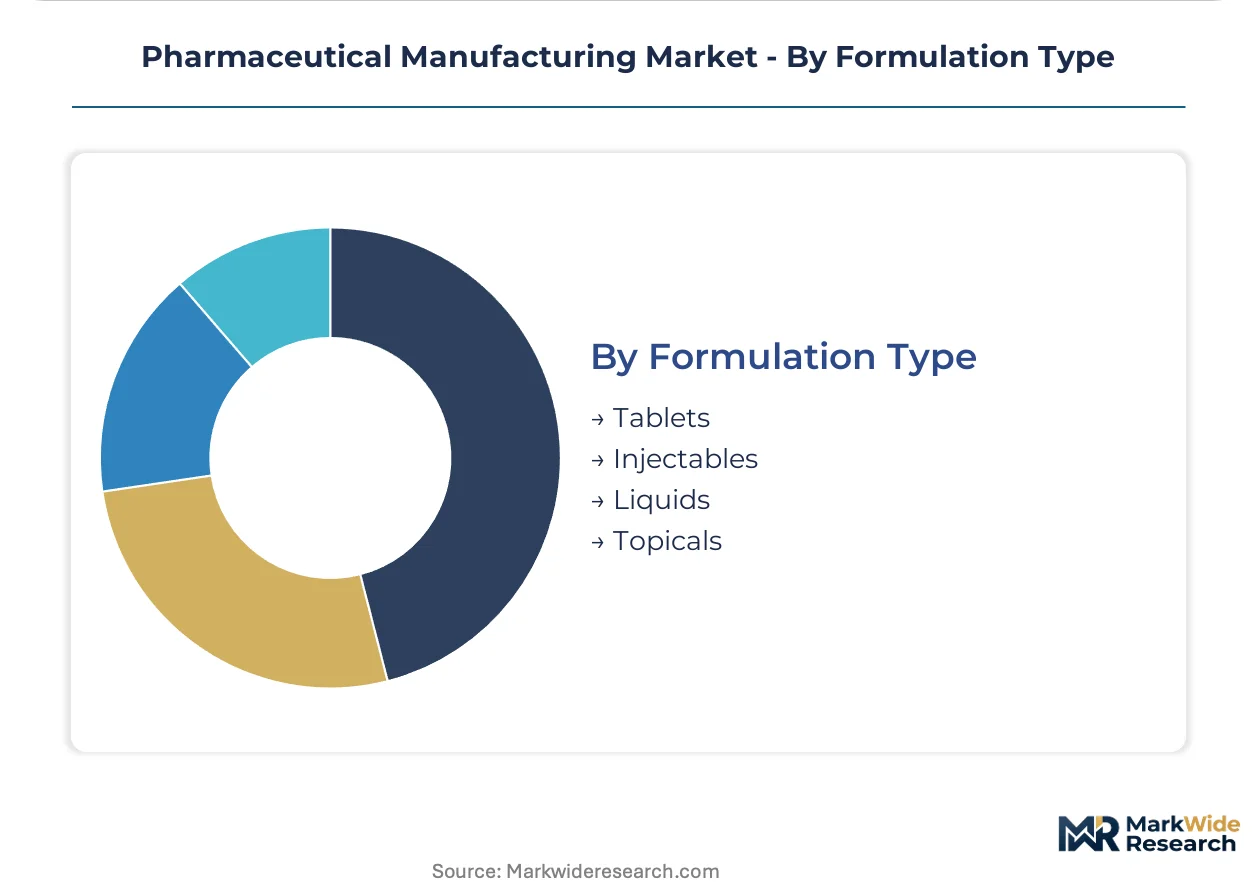
Formulation Type:
Delivery modality determines cleanroom classification, barrier technology requirements, and capital deployment intensity across finished dosage manufacturing.
- Injectables:Sterile liquid and lyophilized products requiring isolator-based filling lines and automated visual inspection. India-based contract manufacturers are expanding capacity to serve European and North American clients seeking redundant supply for critical medicines.
- Tablets:Solid oral dosage forms produced through granulation, compression, and film coating operations. High-volume production concentrates in established manufacturing clusters with mature regulatory track records.
- Liquids:Oral solutions and suspensions with moderate sterility requirements and higher shipping costs per dose.
- Topicals:Transdermal and dermal preparations requiring specialized mixing equipment and viscosity control.
Tablets represent the volume foundation. Injectables capture disproportionate capital allocation for capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis capacity clusters in India and China, while biologics manufacturing concentrates in Switzerland, Ireland, and South Korea where mammalian cell culture infrastructure attracts multinational investment.
United States
FDA pre-approval inspections and the Quality Management Maturity program drive facility upgrade cycles among domestic manufacturers. The Inflation Reduction Act's drug pricing provisions are reshaping capital allocation toward high-complexity biologics. Greater Boston and the Research Triangle anchor cell therapy manufacturing expansion.
Switzerland
Swissmedic's streamlined approval pathways attract biologics commercialization for European launch sequences. The country's bilateral recognition agreements with FDA and EMA reduce duplicate facility inspections. Basel and the Lake Geneva region concentrate monoclonal antibody production infrastructure.
India
CDSCO alignment with WHO prequalification standards enables export eligibility for sterile injectable manufacturers serving European and North American clients. The PLI scheme for active pharmaceutical ingredients attracts greenfield investments in Kharagpur and Visakhapatnam clusters. Contract manufacturers expand isolator-based filling lines for redundant supply assurance.
Germany
EMA centralized procedures position German facilities as launch markets for novel biologics seeking European approval. The country's dual vocational training system supplies bioprocess engineering talent for cell culture scale-up operations. Frankfurt-Rhine-Main and Munich regions host fill-finish networks for parenteral products.
South Korea
MFDS regulatory convergence with ICH guidelines accelerates multinational biologics filing strategies through Korean manufacturing sites. Samsung Biologics sustains capacity leadership through single-use bioreactor scale-outs. The Songdo and Incheon free economic zones concentrate contract manufacturing infrastructure for monoclonal antibody exports.
Pharmaceutical Manufacturing Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized biologics contract manufacturers split the market based on modality complexity and capital intensity requirements. The structure concentrates among players with captive mammalian cell culture infrastructure or regulatory-tracked sterile formulation networks. Two strategic archetypes dominate: vertically integrated innovators with global manufacturing footprints, and modality-focused CDMOs with platform standardization advantages. Competitive moves center on capacity expansion in low-cost jurisdictions and technology licensing for continuous processing platforms.
Among integrated innovators, Johnson & Johnson and Pfizer occupy positions defined by biologics commercialization scale and fill-finish network density. Lonza exemplifies the specialized CDMO archetype through mammalian cell culture infrastructure dominance. Samsung Biologics anchors the Asia-Pacific contract manufacturing tier with single-use bioreactor capacity leadership.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Merck & Co. |
| Pfizer |
| AbbVie |
| AstraZeneca |
| Roche |
| Novartis |
| Samsung Biologics |
| Lonza |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and US suppliers for cell culture media and single-use bioreactor components determines both pricing tier spreads and supply chain shape across pharmaceutical manufacturing, forcing buyers to absorb premium sourcing costs or accept extended qualification timelines for alternative vendors.
Pricing Analysis
The FDA's Quality Management Maturity program dictates the pricing tier structure across contract manufacturing services. Three-tier pricing structure across premium, standard, and economy levels separates FDA-inspected facilities with advanced manufacturing designations from standard GMP-compliant sites and emerging economy-tier producers in India. Cost compression in the economy tier is intensifying because European and North American sponsors demand redundant supply sources for critical medicines. Biotech firms with commercial-stage assets show the least price sensitivity due to reimbursement negotiation pressures, while generic pharmaceutical companies exhibit acute cost consciousness in procurement decisions.
Supply Chain Analysis
Upstream feedstock for mammalian cell culture draws from concentrated suppliers in Germany, the United States, and South Korea. Cell culture media, single-use bioreactor bags, and chromatography resins rest on specialized chemical and polymer production anchored in these jurisdictions. Single-source vulnerability creates exposure to export restriction cascades when geopolitical tensions escalate. Distribution runs through CDMO networks with facility sharing arrangements and quality agreement frameworks that segment supply by regulatory jurisdiction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical manufacturing exhibits structural fragmentation across modality complexity tiers, with autologous cell therapy and continuous processing platforms creating niches that specialized players can occupy without confronting integrated conglomerates directly.
For Market Incumbents: Pre-empt emerging biotech captive manufacturing buildouts by expanding mammalian cell culture capacity in Ireland and South Korea before facility qualification timelines extend. Lock in long-term quality agreements with sponsors preparing for FDA pre-approval inspections. Defend against Samsung Biologics scale-outs by standardizing platform processes that reduce batch-to-batch variability for monoclonal antibody clients.
For New Entrants and Emerging Players: India's Visakhapatnam and Kharagpur clusters offer underpenetrated API manufacturing capacity where PLI scheme incentives offset qualification timeline disadvantages. Target sterile injectable contract manufacturing for European sponsors seeking geographic redundancy outside Switzerland and Germany. Establish go-to-market positioning through WHO prequalification alignment that unlocks export eligibility for domestic Indian manufacturers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized CDMOs with mammalian cell culture platform standardization. Long-term viability hinges on continuous processing technology licensing positions and regulatory-tracked facility networks. Monitor FDA advanced manufacturing designation awards as the inflection signal for which technology platforms will capture pre-approval inspection preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Adoption | FDA advanced manufacturing designations accelerate regulatory approval pathways for sponsors deploying real-time release testing. |
| Single-Use Bioreactor Scale-Out | Samsung Biologics sustains capacity leadership through modular expansion in Songdo free economic zones. |
| Isolator-Based Filling Line Investment | Indian CDMOs capture European and North American sterile injectable demand through redundant supply assurance. |
| Digital Twin Platform Deployment | Mid-cap biotechs compress first-in-human timeline risk through virtualized process development workflows. |
| Explainable AI Architecture Implementation | Irish and Dutch facilities satisfy EU AI Act conformity assessments for automated bioreactor parameter adjustment. |
Research Methodology
Initial hypotheses were tested against primary input from bioprocess engineering directors, regulatory affairs leads at CDMOs, biotech procurement managers, and hospital pharmacy formulary directors and refined through secondary validation against FDA warning letter databases, EMA inspection outcome reports, ClinicalTrials.gov manufacturing facility disclosures, and WHO prequalification lists. Bottom-up capacity utilization modeling triangulated with top-down pharmaceutical spending flow analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, manufacturing technology, end user category, formulation type, and regional regulatory cluster. CAGRs were derived from facility expansion pipeline tracking and sponsor outsourcing intention surveys. Forecast inputs incorporated biotech pipeline stage transitions and CDMO quality agreement renewal rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging biotechs building captive manufacturing would shift outcomes through demand destruction for contract services. Cross-checking against FDA pre-approval inspection scheduling data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Small Molecule CDMO Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market