
 Lipid Injectable Market | 2026-2036
Lipid Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Lipid Injectable Market Foresight
Hospital procurement channels for lipid injectables is fragmenting as group purchasing organizations lose leverage to direct manufacturer contracts and specialty distributors. Fresenius Kabi anchors European supply through captive manufacturing of parenteral nutrition emulsions. Pfizer Inc. leverages its sterile injectable infrastructure to dominate hospital formulary access in North America. B. Braun Melsungen AG competes on integrated delivery systems that pair lipid emulsions with infusion pumps.
Lipid injectables are sterile oil-in-water emulsions or lipid-based solutions formulated for intravenous administration, typically containing soybean oil, safflower oil, or medium-chain triglycerides emulsified with egg phospholipids and stabilized at pH 7.5-8.5 for vascular compatibility. These formulations deliver essential fatty acids, caloric density, or lipophilic APIs directly into systemic circulation when enteral absorption fails. Emulsions command the largest revenue pool in nutritional support applications, while chemotherapy lipid formulations represent the fastest-expanding segment driven by oncology pipeline demand. Hospitals remain the dominant end-user channel, though homecare infusion of lipid-based parenteral nutrition is eroding institutional share as ambulatory protocols mature.
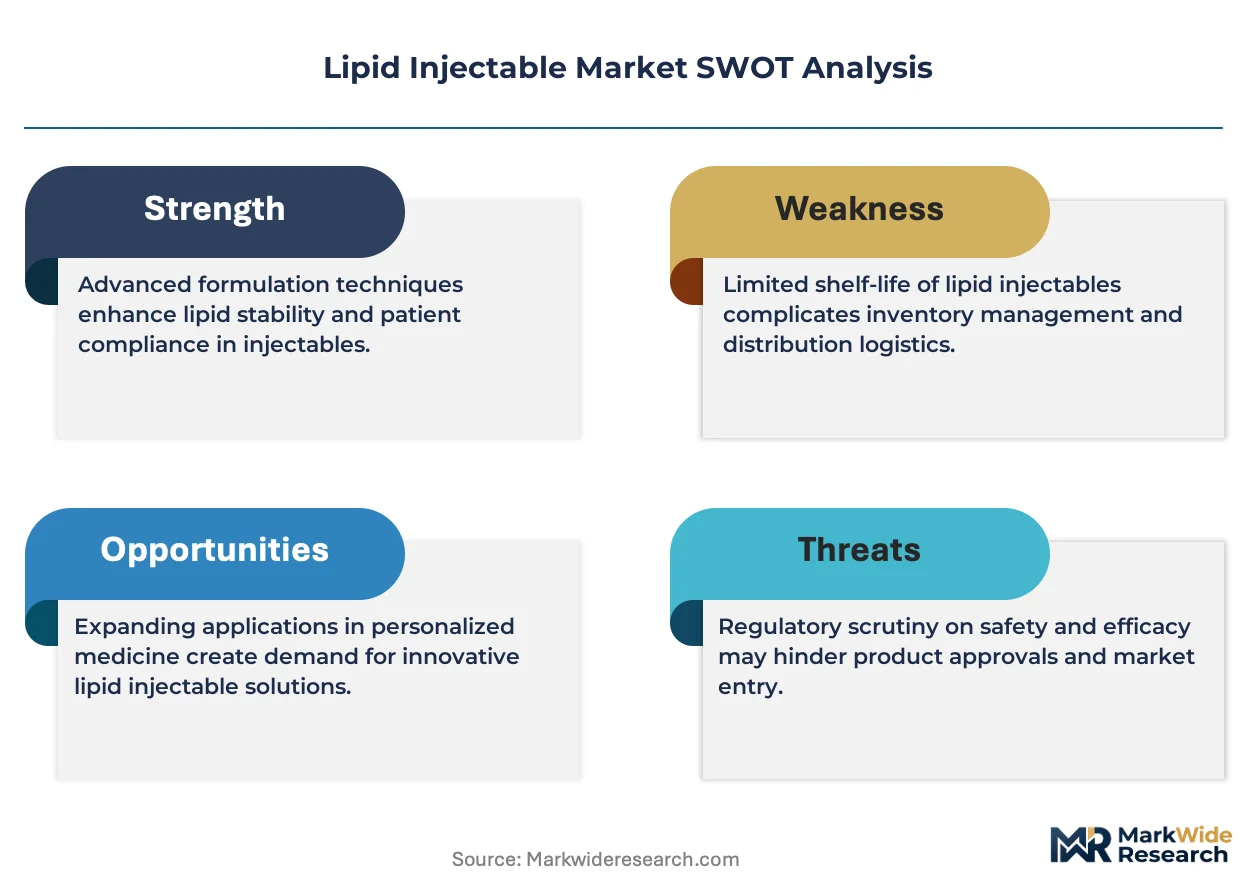
FDA enforces sterility and pyrogenicity standards under 21 CFR, while EMA's Good Manufacturing Practice guidelines mandate lipid particle size distribution controls for batch release. The EU F-Gas Regulation and US EPA environmental compliance frameworks are pressuring manufacturers to reformulate propellants and packaging materials. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and Ph. Eur. monographs for lipid injectable excipients, as divergence in particle-size acceptance criteria threatens cross-Atlantic product registrations and supply continuity.
Market Dynamics
Hospital procurement channels for lipid injectables are fragmenting as group purchasing organizations lose leverage to direct manufacturer contracts and specialty distributors, fundamentally reshaping how sterile emulsions reach end-users.
Growth Catalysts
- FDA sterility mandates under 21 CFR:Tightened pyrogenicity standards are forcing manufacturing upgrades that favor capital-rich suppliers capable of automated aseptic processing.
- Home infusion services:Ambulatory parenteral nutrition protocols are extending therapy duration outside institutional settings, creating pull-through demand for shelf-stable lipid emulsion formulations.
- Soybean oil supply concentration in Argentina and Brazil:Captive agricultural processing agreements are securing input cost advantages for integrated manufacturers.
Market Restraints
- Egg phospholipid input volatility:Supply concentration among European and Asian egg processing facilities creates formulation cost instability for emulsion manufacturers.
- EMA particle-size distribution controls:Batch release testing under Good Manufacturing Practice guidelines extends production cycles and raises working capital requirements.
- Peripheral parenteral nutrition substitution:Enteral feeding tube advances and improved gut absorption protocols are compressing addressable volume for intravenous lipid delivery.
Strategic Opportunities
- India's hospital infrastructure expansion:Government-funded critical care bed additions in tier-2 and tier-3 cities are creating first-mover advantages for parenteral nutrition suppliers establishing local distribution.
- Fish oil-based omega-3 emulsions:Anti-inflammatory lipid profiles are opening oncology and critical care applications beyond standard nutritional support.
- EU F-Gas Regulation compliance incentives:Reformulation subsidies for sustainable propellant and packaging alternatives are lowering barrier-to-entry for green chemistry entrants.
Industry Challenges
- Aseptic manufacturing technician scarcity:Specialized cleanroom operations and sterile compounding expertise gaps are constraining production scale-up across multiple facilities.
- USP-NF and Ph. Eur. monograph divergence:Particle-size acceptance criteria misalignment between American and European pharmacopeias is forcing dual validation runs and threatening cross-Atlantic product registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipid Injectable Market |
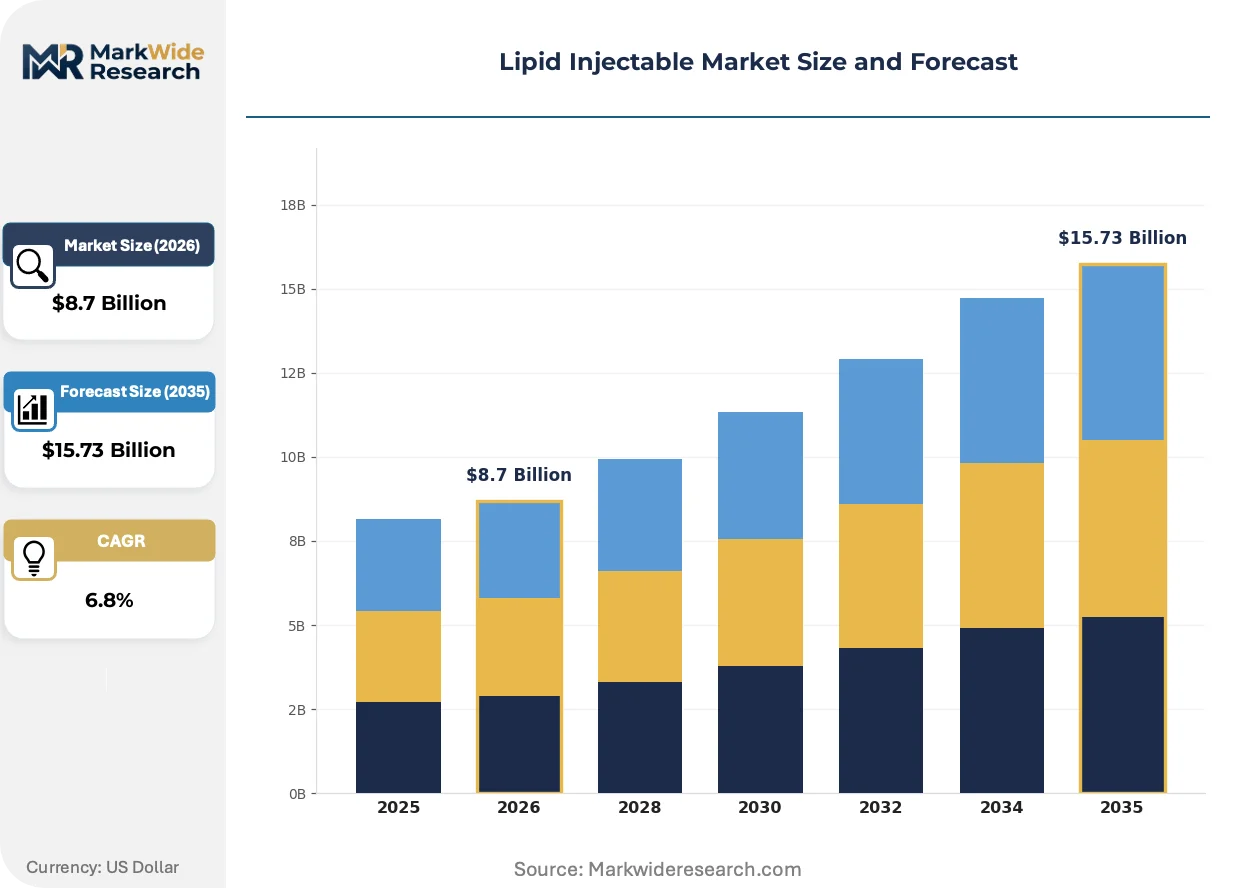
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Solutions, Infusions, Formulations Application: Nutritional Support, Anesthesia, Chemotherapy, Pain Management End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Packaging Type: Vials, Ampoules, Bags, Syringes |
| Companies Covered | Pfizer Inc., Grifols, S.A., Fresenius Kabi, Sandoz International GmbH, Teva Pharmaceutical Industries Ltd., Baxter International Inc., Abbott Laboratories, Aspen Pharmacare Holdings Ltd., B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipid Injectable Market Shifts & Advancements
Formulation science and delivery mechanisms are converging to expand lipid injectables beyond nutritional support into targeted therapeutic carriers, with manufacturing automation and regulatory harmonization as parallel enabling forces.
Structured lipid emulsions combining medium-chain triglycerides with long-chain fatty acids are hybridizing caloric density and metabolic clearance profiles. Intensive care units in academic medical centers are adopting these hybrid formulations for hepatic-compromised patients at accelerating rates. This hybridization is compressing demand for legacy soybean-only emulsions while raising formulation complexity barriers for commodity suppliers.
EMA's evolving Good Manufacturing Practice guidelines for lipid-based drug carriers are mandating real-time particle-size monitoring during production. Manufacturers must retrofit continuous manufacturing lines with in-process analytical technology or risk batch rejection. Oncology lipid formulations face the steepest compliance burden, driving contract manufacturing organization consolidation in the Netherlands and Germany.
Hospital formulary committees are unbundling parenteral nutrition contracts from infusion pump procurement, reversing decade-old bundled pricing structures. Specialty distributors are capturing margin previously held by group purchasing organizations through direct manufacturer agreements and just-in-time inventory guarantees. This disintermediation is most pronounced in United States metropolitan markets where home infusion providers operate independent of hospital supply chains.
Lipid Injectable Market Segmentation
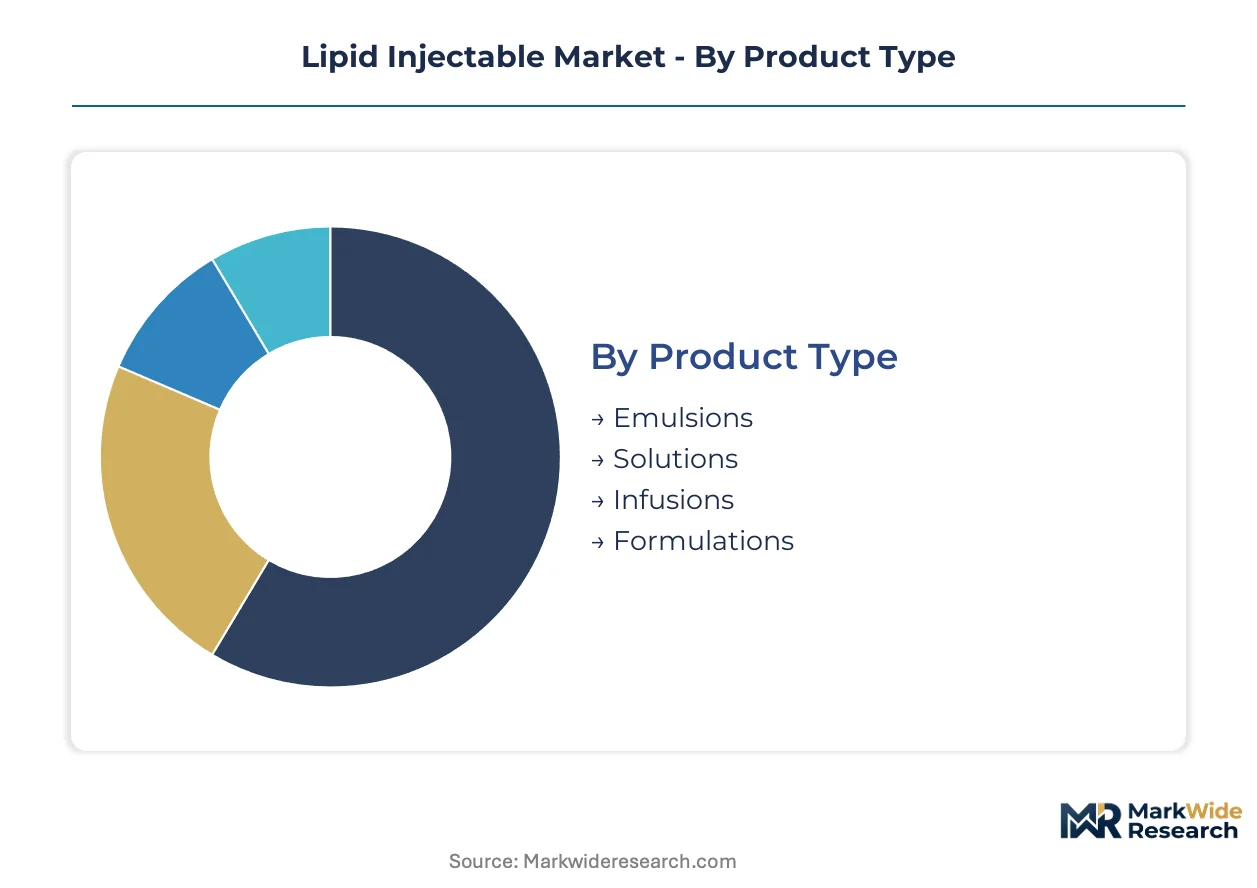
Lipid injectable segmentation reveals how formulation chemistry, clinical setting, and delivery format intersect to determine procurement patterns. Each dimension carries distinct regulatory, margin, and supply chain implications for manufacturers and distributors.
Product Type:
Use-case spectrum spans nutritional replenishment through targeted drug delivery, with formulation complexity determining manufacturing barriers and pricing tiers.
- Emulsions:Oil-in-water dispersions containing soybean, safflower, or medium-chain triglycerides stabilized with egg phospholipids at pH 7.5-8.5. Hospital parenteral nutrition departments in the United States concentrate procurement here, driven by surgical volume recovery and ICU caloric support protocols. Established volume favors emulsions; emerging adoption favors formulations.
- Solutions:Homogeneous lipid-based preparations without dispersed phase, typically for lipophilic API solubilization. Compounding pharmacies and oncology infusion centers in Germany and the Netherlands are expanding orders for chemotherapy-compatible lipid solutions as EMA particle-size controls tighten. Steepest expansion trajectory sits with solutions as oncology pipeline demand accelerates.
- Infusions:Large-volume sterile lipid preparations for continuous intravenous administration.
- Formulations:Custom-engineered lipid carriers for specific therapeutic payloads or metabolic profiles.
Margin concentration tracks formulation sophistication, with commodity emulsions facing price compression and specialized formulations commanding premium positioning.
Application:
Clinical indication determines reimbursement pathway, prescriber specialty, and competitive intensity across institutional and ambulatory channels.
- Nutritional Support:Essential fatty acid and caloric density delivery for patients with failed enteral absorption. Home infusion services in the United States are scaling ambulatory parenteral nutrition protocols, pulling demand outside hospital walls as shelf-stable formulations mature.
- Chemotherapy:Lipid-based drug carriers for oncology APIs with poor aqueous solubility. Academic medical centers in Germany and the Netherlands are adopting these carriers fastest, driven by EMA Good Manufacturing Practice mandates for real-time particle-size monitoring during production.
- Anesthesia:Lipid emulsion vehicles for intravenous anesthetic agents.
- Pain Management:Lipid formulations for lipophilic analgesic delivery.
Revenue scale clusters in nutritional support; therapeutic expansion concentrates in chemotherapy applications.
End User:
Site-of-care migration is fragmenting procurement channels and reshaping inventory requirements across the customer base.
- Hospitals:Dominant institutional purchasers with formulary committees unbundling parenteral nutrition from infusion pump contracts. United States metropolitan health systems are shifting toward direct manufacturer agreements, bypassing group purchasing organizations.
- Homecare:Independent infusion providers operating outside hospital supply chains. Specialty distributors are capturing margin here through just-in-time inventory guarantees in United States ambulatory markets.
- Clinics:Outpatient settings with limited sterile compounding capabilities.
- Rehabilitation Centers:Long-term care facilities with extended parenteral nutrition protocols.
Procurement leverage concentrates with hospitals; growth velocity favors homecare channels.
Packaging Type:
Container format dictates sterilization method, shelf stability, and point-of-use workflow efficiency.
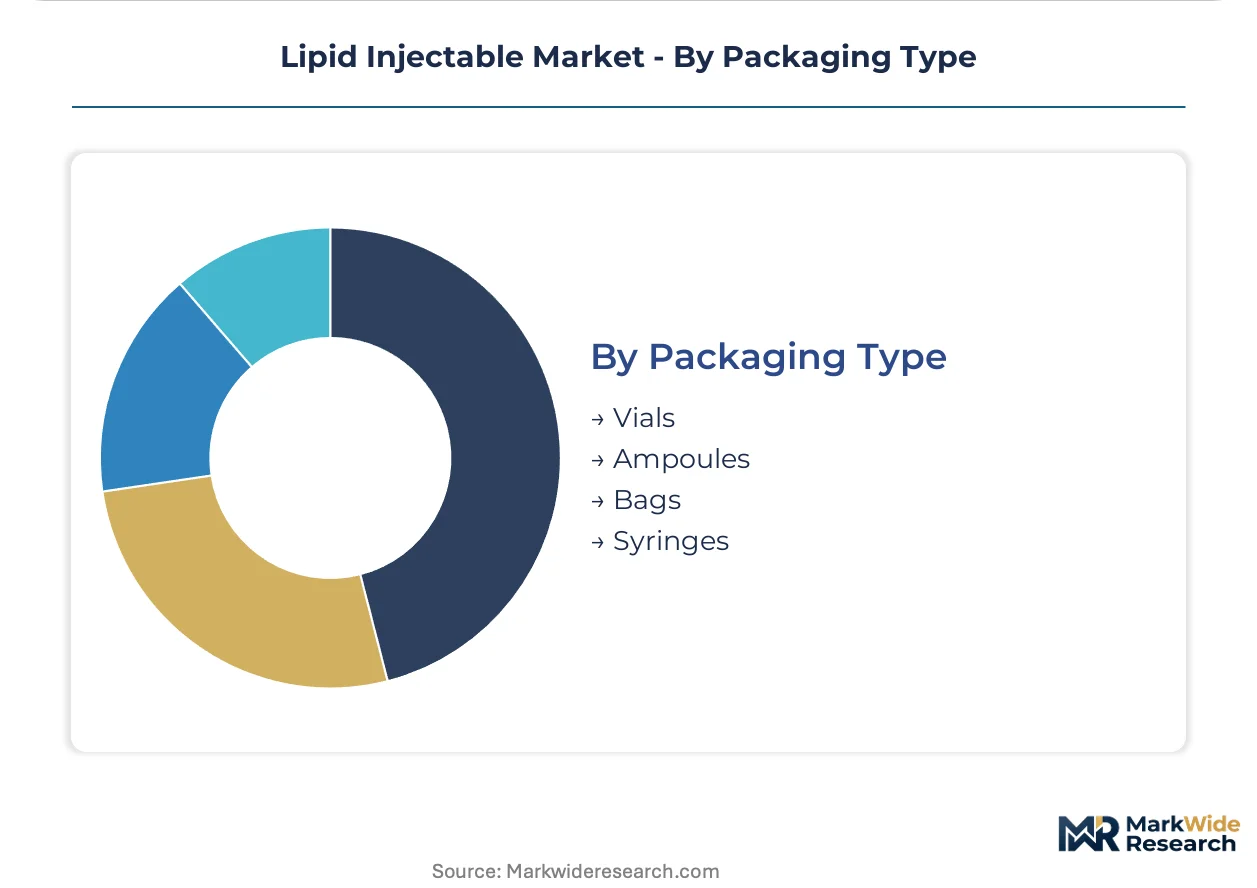
- Bags:Flexible containers for large-volume parenteral nutrition infusion. Hospital pharmacies in the United States prioritize bags for automated compounding compatibility and reduced nursing preparation time.
- Vials:Multi-dose glass containers for pharmacy compounding and dose customization. European compounding facilities under EMA guidelines favor vials for batch flexibility and particle-size verification before final container transfer.
- Ampoules:Single-unit glass containers for immediate use.
- Syringes:Pre-filled delivery systems for emergency or ambulatory administration.
Operational scale drives bag adoption; flexibility requirements sustain vial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by double-digit margins, while procurement leverage concentrates with hospital formulary committees in both markets. This asymmetry shapes manufacturer investment priorities and regulatory compliance strategies across major demand centers.
United States
Home infusion services and long-term care facilities are scaling lipid-based therapeutic delivery as ambulatory parenteral nutrition protocols mature. FDA sterility mandates under 21 CFR are tightening manufacturing standards and favoring capital-rich suppliers. Metropolitan health systems in Chicago and Houston are bypassing group purchasing organizations for direct manufacturer contracts.
Germany
Academic medical centers in Berlin and Munich are adopting chemotherapy lipid formulations fastest among European institutions. EMA Good Manufacturing Practice guidelines mandate real-time particle-size monitoring during production, extending batch release cycles. The Rhine-Ruhr industrial corridor hosts contract manufacturing organization consolidation serving oncology lipid demand.
India
Government-funded critical care bed additions in tier-2 and tier-3 cities are creating first-mover advantages for parenteral nutrition suppliers. CDSCO stability-testing requirements for lipid-based drug carriers are tightening local manufacturing standards. Maharashtra and Gujarat industrial clusters are attracting distribution partnerships from multinational sterile injectable manufacturers.
Netherlands
Compounding pharmacies and oncology infusion centers in Amsterdam and Rotterdam are expanding orders for chemotherapy-compatible lipid solutions. EMA particle-size distribution controls are raising working capital requirements for batch release. The Eindhoven-Tilburg corridor is consolidating contract manufacturing capacity for lipid-based drug carriers.
Japan
Intensive care units in Tokyo and Osaka academic medical centers are adopting structured lipid emulsions for hepatic-compromised patients. PMDA guidelines for sterile oil-in-water emulsions are harmonizing with USP-NF monographs on particle-size acceptance criteria. The Kansai region is emerging as a formulation R&D cluster for hybrid lipid emulsions.
Lipid Injectable Market Competitive Landscape
Integrated pharmaceutical conglomerates and sterile injectable specialists split the market between formulary dominance and manufacturing precision. Hospital procurement channel fragmentation is eroding group purchasing organization leverage and opening margin capture opportunities for direct manufacturer relationships. Three archetypes prevail: capital-rich diversified pharmacos with sterile infrastructure, captive parenteral nutrition manufacturers with agricultural supply integration, and precision compounding specialists with oncology formulation expertise. Competitive moves concentrate on capacity expansion in high-barrier aseptic facilities and strategic partnerships with home infusion distributors.
Among diversified pharmaceutical manufacturers with sterile injectable infrastructure, Pfizer Inc. and Baxter International Inc. exemplify the formulary-access archetype through hospital supply chain penetration. Fresenius Kabi occupies a distinct position as a European-anchored integrated manufacturer with captive agricultural processing agreements securing input cost advantages. B. Braun Melsungen AG represents the delivery-system pairing strategy, competing through integrated infusion pump and lipid emulsion bundling despite hospital committee unbundling trends.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Grifols, S.A. |
| Fresenius Kabi |
| Sandoz International GmbH |
| Teva Pharmaceutical Industries Ltd. |
| Baxter International Inc. |
| Abbott Laboratories |
| Aspen Pharmacare Holdings Ltd. |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Argentine and Brazilian soybean oil processing concentration hands integrated manufacturers captive input cost advantages that downstream formulators cannot replicate, concentrating margin pools with suppliers controlling agricultural supply chains rather than compounding pharmacies or distributors.
Pricing Analysis
Configured-to-order pricing for patient-specific parenteral nutrition formulations commands 40-60% premiums over standard soybean emulsion SKUs. Three-tier pricing structure across premium structured lipids, standard nutritional emulsions, and economy multi-source generics tracks FDA certification tier and volume commitment scale. Cost compression in commodity emulsions is intensifying because hospital formulary committees unbundle contracts from infusion pump procurement. Home infusion providers exhibit highest price sensitivity; academic medical centers with restricted drug budgets show lowest.
Supply Chain Analysis
Upstream feedstock sourcing for lipid injectables draws from Argentina, Brazil, and Ukraine for refined vegetable oils, with European and Asian facilities dominating egg phospholipid extraction. Manufacturing rests on soybean oil, safflower oil, and medium-chain triglyceride inputs alongside egg-derived emulsifiers. Single-source vulnerability concentrates in phospholipid supply where European processors control 70% of pharmaceutical-grade output. Distribution runs through specialty distributors capturing margin from disintermediated group purchasing organizations in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic manufacturing technician scarcity constrains production scale-up across sterile emulsion facilities, creating durable competitive moats for capital-rich suppliers with automated cleanroom infrastructure and validated training pipelines.
For Market Incumbents: Insulate formulation margins by securing captive soybean processing agreements in Argentina and Brazil while retrofitting continuous manufacturing lines with real-time particle-size monitoring to preempt EMA batch rejection risk. Backward integration into agricultural supply chains and automation capital deployment represent the critical defensive levers against emerging green chemistry entrants capturing EU F-Gas reformulation subsidies. For New Entrants and Emerging Players: Pursue India's tier-2 and tier-3 hospital infrastructure expansion where government-funded critical care bed additions outpace established distribution networks. Fish oil-based omega-3 emulsions for oncology and critical care applications offer the most penetrable white space beyond commodity nutritional support. Partner with Maharashtra and Gujarat industrial clusters for CDSCO-compliant local manufacturing rather than import-dependent models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturing organizations in the Netherlands and Germany consolidating oncology lipid formulation capacity. Long-term viability hinges on exposure to therapeutic drug delivery rather than nutritional support commoditization. Monitor EMA-USP pharmacopeial harmonization progress on particle-size acceptance criteria as the signal for cross-Atlantic registration friction and supply consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Manufacturing Automation | FDA sterility mandates under 21 CFR favor capital-rich suppliers with validated cleanroom infrastructure. |
| Captive Agricultural Supply Agreements | Argentine and Brazilian soybean processing integration secures input cost advantages against commodity purchasers. |
| Real-Time Particle-Size Monitoring | EMA Good Manufacturing Practice guidelines mandate in-process analytical technology retrofitting for batch release. |
| Home Infusion Distribution Partnerships | Specialty distributors capture margin from unbundled hospital contracts in United States ambulatory markets. |
| Fish Oil Omega-3 Formulation Development | Anti-inflammatory lipid profiles open oncology and critical care applications beyond standard nutritional support. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, parenteral nutrition compounding pharmacists, sterile manufacturing operations directors, and regulatory affairs specialists anchors the qualitative findings against FDA 483 inspection observations, EMA Good Manufacturing Practice guidance documents, and USP-NF monograph revision records. Bottom-up demand modeling triangulates against top-down pharmaceutical trade flow analysis.
Calibration against historical volume trajectories and surgical procedure recovery patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, application, end-user channel, and packaging format alongside regional regulatory cluster differentiation. CAGRs derive from patient population epidemiology, enteral feeding substitution rates, and oncology pipeline lipid carrier adoption curves.
Sensitivities concentrate around EMA-USP pharmacopeial divergence on particle-size acceptance criteria, egg phospholipid supply disruptions, and peripheral parenteral nutrition substitution by enteral protocols. Forecasts reflect documented assumptions on surgical volume recovery and home infusion service expansion. Cross-checking against hospital procurement database benchmarks and GPO contract renewal patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Trisenox Market