
 Middle East and Africa Psychedelic Drugs Market | 2026-2036
Middle East and Africa Psychedelic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Psychedelic Drugs Market Foresight
Clinical trial sponsorship revenue is tilting toward investigator-initiated studies as pharmaceutical partners retreat from direct site funding. Janssen Global Services leverages its parent Johnson & Johnson's psychiatric infrastructure to sustain large-scale ketamine derivative trials across the region. COMPASS Pathways anchors its presence through proprietary psilocybin formulation partnerships with academic medical centers. Cybin Corp. differentiates by specializing in sublingual delivery technologies that bypass first-pass metabolism constraints.
Psychedelic drugs comprise serotonergic hallucinogens and dissociative anesthetics synthesized through semi-synthetic or biosynthetic routes, typically requiring GMP-certified production with stability specifications below 25 degrees Celsius for active pharmaceutical ingredients; their primary commercial purpose centers on adjunctive psychotherapy for treatment-resistant psychiatric conditions. Psilocybin dominates current pipeline value given its natural-source extraction scalability and established safety profile across Phase II trials. LSD occupies a narrower but higher-margin position in microdosing research protocols at Israeli and South African universities. The intravenous delivery mode captures premium reimbursement where clinic infrastructure permits supervised administration, while oral formulations penetrate outpatient rehabilitation settings more rapidly.
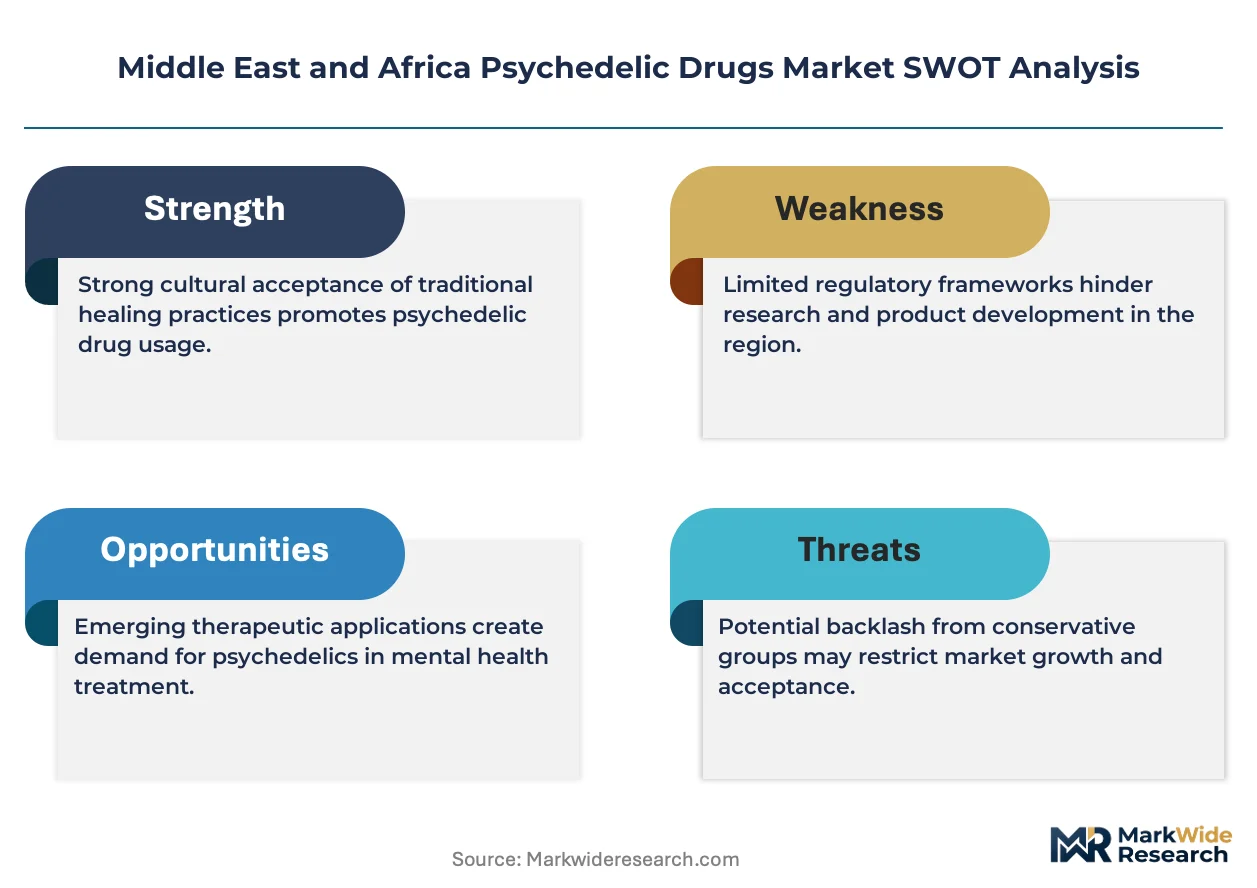
South Africa's SAHPRA governs clinical trial authorizations with a risk-based framework that accelerates psychedelic compound evaluation for mental health indications. Israel's Ministry of Health and Egypt's national pharmaceutical regulator maintain parallel compassionate-use pathways that shape product registration sequencing across the region. The WHO's substance scheduling conventions intersect with national narcotics control boards to determine import licensing requirements for research-grade materials. Stakeholders must monitor how compassionate-use program expansions in Israel and South Africa reshape patient-access expectations before formal marketing authorization completion.
Market Dynamics
Investigator-initiated trial sponsorship is displacing pharmaceutical-direct funding across Middle East and Africa psychedelic research, compressing traditional site-fee structures while elevating academic medical centers as gatekeepers for compound access.
Growth Catalysts
- SAHPRA Risk-Based Framework:South Africa's accelerated evaluation pathway for mental health indications reduces trial authorization timelines, drawing sponsor investment toward Cape Town and Johannesburg academic clusters.
- Natural-Source Extraction Scalability:Biosynthetic psilocybin production methods are lowering active pharmaceutical ingredient costs, enabling broader patient access across outpatient rehabilitation settings.
- Compassionate-Use Program Expansions:Israel's Ministry of Health and Egypt's national pharmaceutical regulator are creating pre-authorization patient access channels that reshape registration sequencing expectations.
Market Restraints
- Import Licensing Friction:WHO substance scheduling conventions intersect with national narcotics control boards, creating multi-month delays for research-grade material clearance into South Africa and Egypt.
- Cold-Chain Infrastructure Gaps:Stability specifications below 25 degrees Celsius for active pharmaceutical ingredients strain distribution networks outside major urban corridors.
- Psychiatrist Workforce Concentration:Clinical psychiatry departments capable of supervising psychedelic-assisted therapy concentrate in three South African university hospitals, limiting trial site expansion.
Strategic Opportunities
- Sublingual Delivery Convergence:Combination of sublingual formulation technology with telehealth supervision protocols opens outpatient markets beyond traditional clinic infrastructure.
- Egyptian Regulatory Tailwind:Emerging protocols under the national pharmaceutical regulator signal potential first-mover advantage for sponsors establishing manufacturing partnerships in North Africa.
- Microdosing Research Protocols:LSD microdosing studies at Israeli universities represent an underexploited application segment with higher-margin positioning than standard-dose trials.
Industry Challenges
- GMP Certification Timelines:Semi-synthetic and biosynthetic production facilities face extended validation periods for active pharmaceutical ingredient certification.
- Psychotherapist Training Bottlenecks:Shortage of practitioners certified in psychedelic-assisted therapy protocols constrains patient throughput per trial site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Psychedelic Drugs Market |
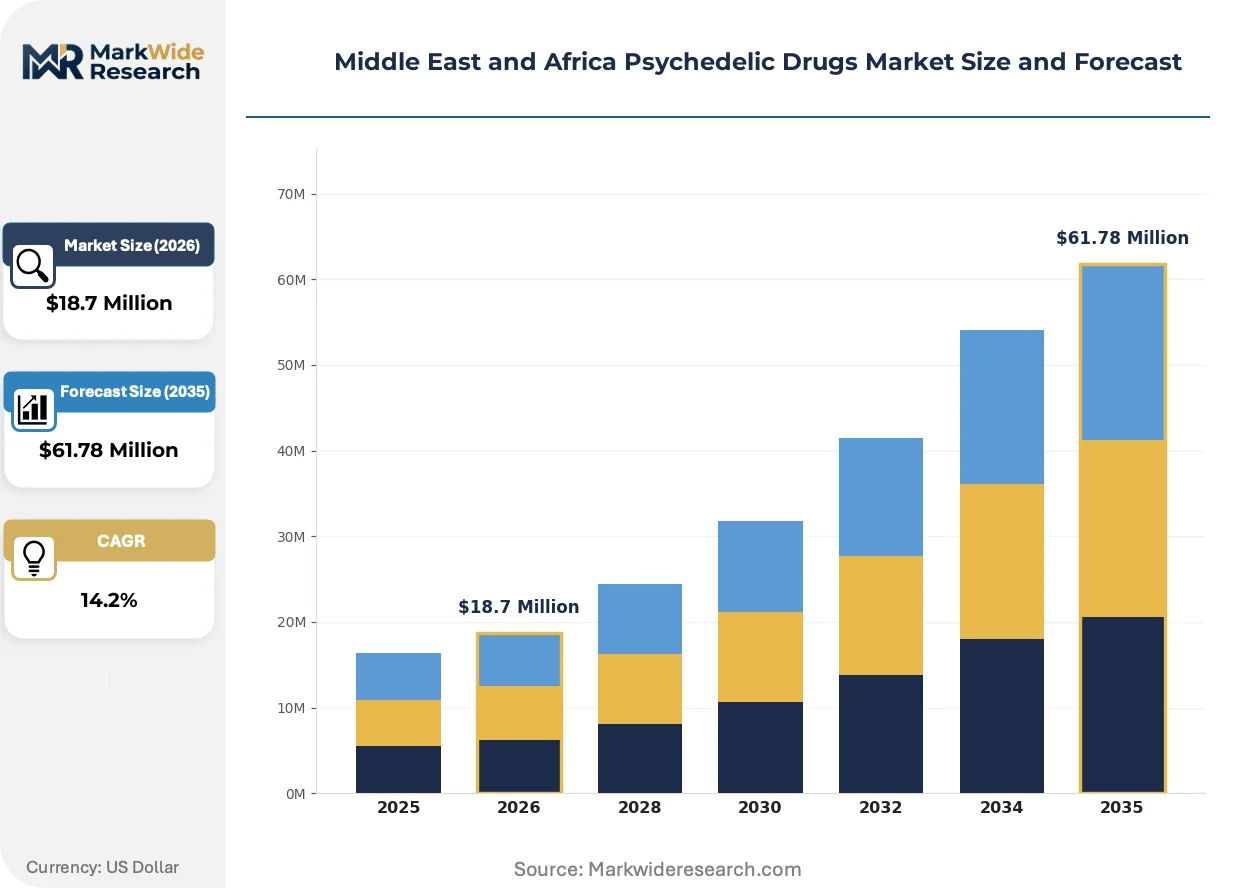
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psilocybin, LSD, Mescaline, DMT Delivery Mode: Oral, Intravenous, Inhalation, Sublingual End User: Clinics, Research Institutions, Rehabilitation Centers, Universities Therapy Area: Mental Health, Substance Abuse, Pain Management, Trauma |
| Companies Covered | Janssen Global Services, LLC, Hikma Pharmaceuticals PLC, Pfizer Inc., F. Hoffmann-La Roche Ltd, Jazz Pharmaceuticals Inc., COMPASS Pathways, Johnson & Johnson, AstraZeneca, Cybin Corp., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Psychedelic Drugs Market Shifts & Advancements
Synthesis and delivery technologies are compressing cost structures while regulatory pathways fragment across national jurisdictions, forcing sponsors to architect multi-country development strategies rather than single-market approaches.
Biosynthetic psilocybin production is collapsing the cost differential between natural extraction and chemical synthesis routes. Academic medical centers in South Africa are adopting these methods to secure supply chain autonomy for multi-year trials. This technology is collapsing traditional API sourcing dependencies on European contract manufacturers.
SAHPRA's risk-based evaluation framework is accelerating compound-specific authorization timelines for treatment-resistant depression indications. The industrial consequence is a geographic rebalancing of trial investment toward Cape Town and Johannesburg. Psychiatric research units at University of Cape Town and Stellenbosch University are responding by expanding dedicated psychedelic therapy facilities.
Patient access expectations are shifting ahead of formal marketing authorization completion. Compassionate-use pathways in Israel and South Africa are creating demand pressure that outpaces regulatory timelines. This pattern concentrates most visibly in Tel Aviv academic hospitals where pre-authorization access programs have operated since 2021.
Middle East and Africa Psychedelic Drugs Market Segmentation
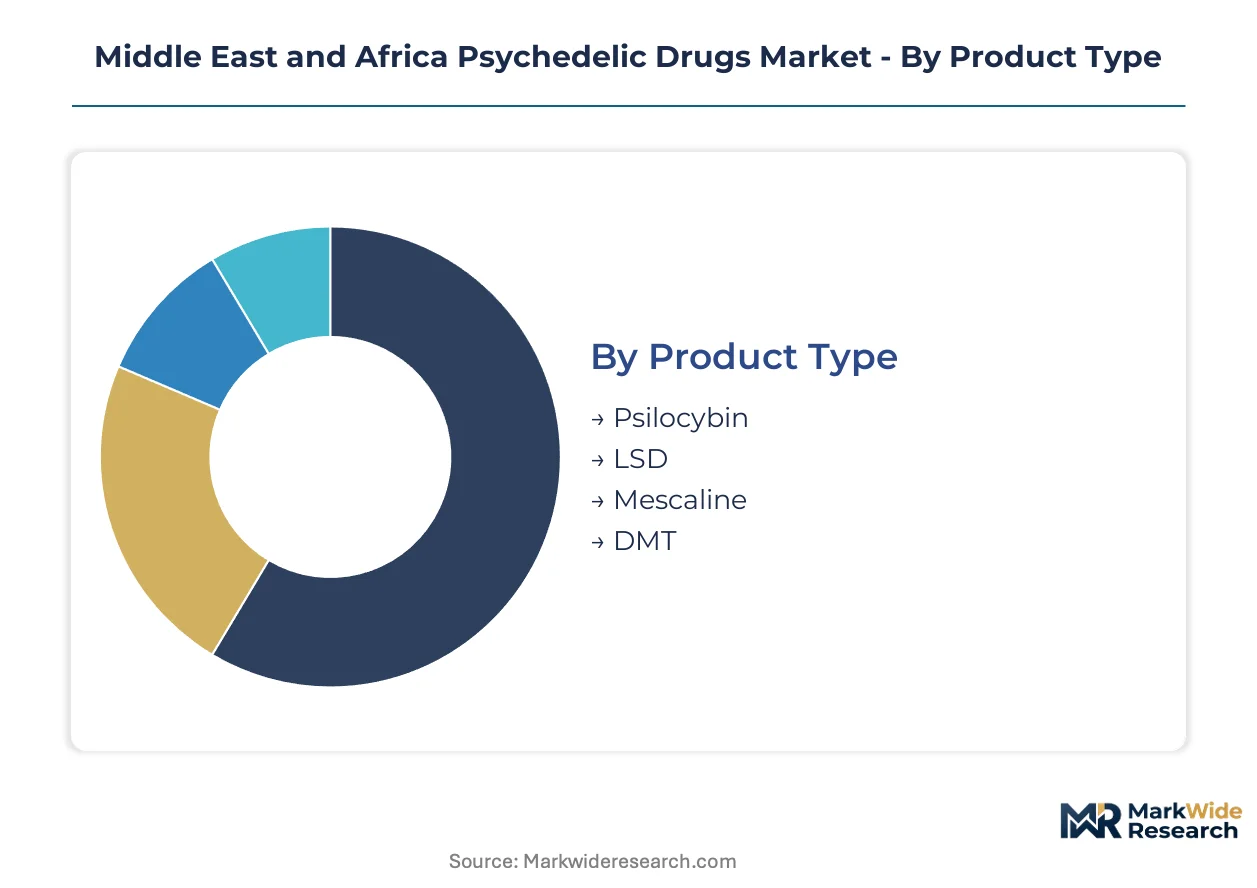
Segmentation in this market reveals how compound characteristics, administration protocols, and institutional capabilities intersect to determine commercial viability. Understanding these divisions helps sponsors align development timelines with infrastructure realities across South Africa, Egypt, and Israel.
Product Type:
Cycle times vary sharply: natural-extraction compounds turn inventory faster than synthetic routes requiring extended GMP validation.
- Psilocybin:Biosynthetic production methods are collapsing cost differentials against chemical synthesis, with University of Cape Town and Stellenbosch University medical centers securing multi-year supply autonomy. Demand concentrates in South African academic clusters where SAHPRA's risk-based framework accelerates trial authorizations for treatment-resistant depression protocols.
- LSD:Microdosing research protocols at Israeli universities occupy a narrower but higher-margin position than standard-dose trials, with Tel Aviv academic hospitals operating pre-authorization access programs. The synthetic route demands lengthier stability validation but commands premium positioning in investigator-initiated studies.
- Mescaline:Natural-source scarcity limits pipeline activity to specialized ethnopharmacology units at select research institutions.
- DMT:Rapid onset characteristics suit inhalation delivery development, though import licensing friction through national narcotics control boards constrains material availability.
Psilocybin anchors the volume base while LSD gains share at the steepest rate.
Delivery Mode:
Cost tiers separate premium supervised administration from scalable outpatient formats.
- Intravenous:Captures premium reimbursement where clinic infrastructure permits supervised administration, with Johannesburg and Cape Town academic medical centers maintaining dedicated psychedelic therapy facilities. Cold-chain requirements below 25 degrees Celsius strain distribution networks outside major urban corridors.
- Sublingual:Cybin Corp.'s specialization in sublingual technologies bypasses first-pass metabolism constraints, opening outpatient markets beyond traditional clinic infrastructure when combined with telehealth supervision protocols.
- Oral:Penetrates rehabilitation settings rapidly due to minimal equipment requirements, though bioavailability variability complicates dosing standardization.
- Inhalation:Rapid onset suits DMT protocols but demands specialized ventilation infrastructure rarely available outside research institutions.
Intravenous formats dominate current revenue while sublingual delivery climbs the fastest.
End User:
Customer type determines funding source stability and trial design flexibility.
- Research Institutions:Investigator-initiated trial sponsorship is displacing pharmaceutical-direct funding, elevating academic medical centers as gatekeepers for compound access across South Africa's university hospital network.
- Clinics:Supervised administration infrastructure concentrates in three South African university hospitals, limiting site expansion despite compassionate-use program demand pressure.
- Universities:Israeli and South African academic centers drive microdosing protocol development with higher-margin positioning than standard therapeutic trials.
- Rehabilitation Centers:Oral formulation demand concentrates here, though psychotherapist training bottlenecks constrain patient throughput.
Research institutions anchor the volume base while clinics expand most quickly.
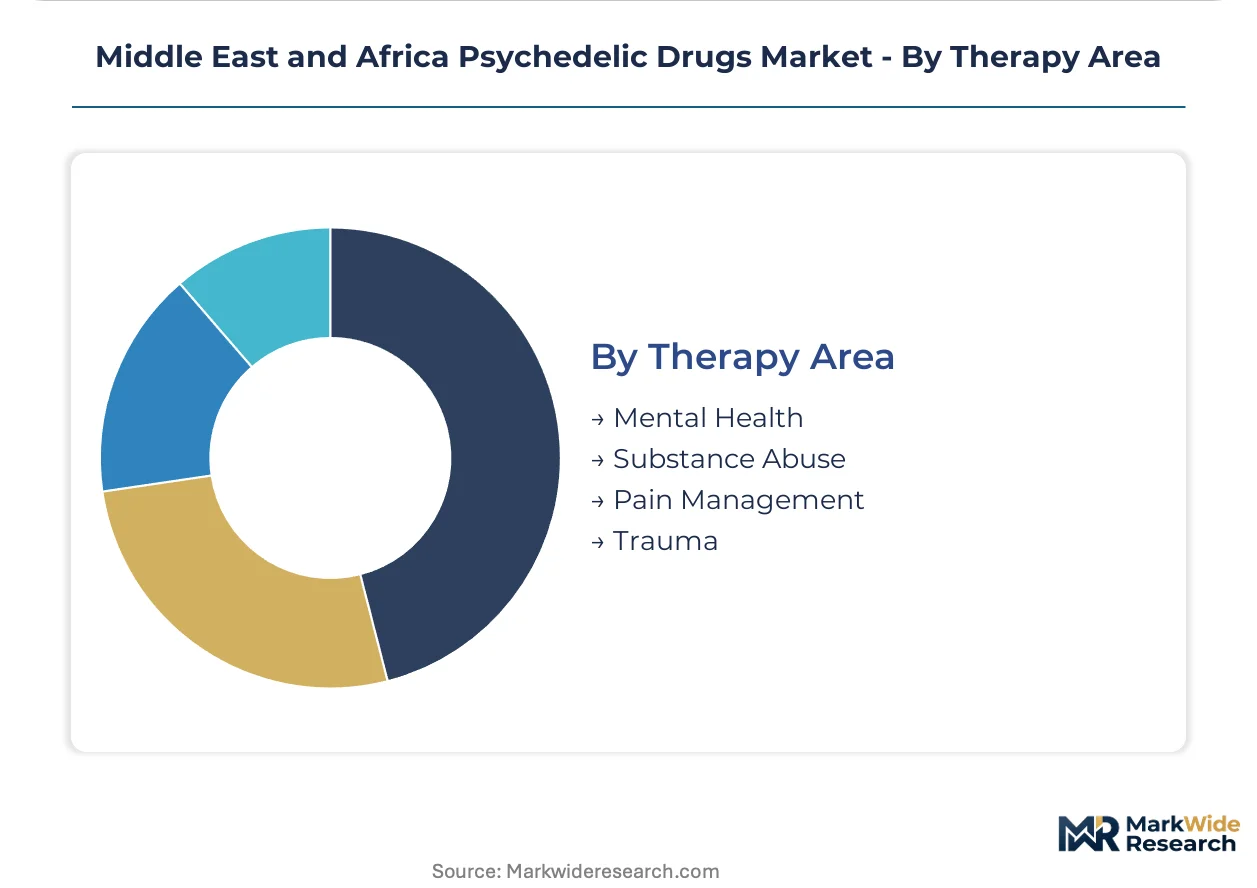
Therapy Area:
Maturity curves separate established psychiatric indications from emerging applications.
- Mental Health:Treatment-resistant depression anchors SAHPRA's accelerated evaluation pathway, with Cape Town and Johannesburg psychiatric research units expanding dedicated facilities.
- Substance Abuse:Adjunctive psychotherapy protocols show promise but face extended validation timelines against abstinence-based standard of care.
- Trauma:Compassionate-use pathways in Israel and South Africa create demand pressure ahead of formal marketing authorization completion.
- Pain Management:Dissociative anesthetic applications remain exploratory, with ketamine derivatives pursued through Johnson & Johnson's regional psychiatric infrastructure.
Mental health anchors the volume base while trauma applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Middle East and Africa: South Africa deploys psychedelic compounds through supervised academic medical center protocols, while Israel pursues microdosing research and Egypt develops manufacturing partnerships for North African distribution.
South Africa
Clinical psychiatry departments at University of Cape Town and Stellenbosch University drive demand through investigator-initiated trials for treatment-resistant depression. SAHPRA's risk-based framework accelerates compound-specific authorizations, compressing trial startup timelines. Cape Town and Johannesburg academic clusters are expanding dedicated psychedelic therapy facilities to accommodate sponsor investment inflows.
Israel
Tel Aviv academic hospitals operate pre-authorization compassionate-use programs that create demand pressure ahead of formal marketing completion. The Ministry of Health maintains parallel access pathways that reshape registration sequencing expectations. Israeli universities concentrate microdosing research protocols, occupying a higher-margin position than standard therapeutic trials.
Egypt
Emerging protocols under the national pharmaceutical regulator signal potential first-mover advantage for sponsors establishing manufacturing partnerships. Import licensing friction through narcotics control boards constrains research-grade material availability. Cairo-based clinical research organizations are positioning to anchor North African distribution networks.
United Arab Emirates
Dubai's healthcare free zones attract pharmaceutical logistics investment, though psychedelic compound trials remain nascent pending regulatory clarity from MOHAP. The emirate's cold-chain infrastructure addresses stability requirements below 25 degrees Celsius for active pharmaceutical ingredients. Academic medical centers in Abu Dhabi are monitoring SAHPRA's framework as a template for future authorization pathways.
Middle East and Africa Psychedelic Drugs Market Competitive Landscape
Capability concentration sits with specialized psychedelic developers; scale advantage sits with diversified pharmaceutical conglomerates. The market exhibits a bifurcated structure where boutique innovators control formulation intellectual property while legacy players leverage psychiatric infrastructure for large-scale trials. Two archetypes dominate: sublingual delivery specialists and ketamine derivative sponsors. Competitive moves center on academic medical center partnerships and biosynthetic production capacity expansion.
Among diversified pharmaceutical conglomerates, Janssen Global Services and Johnson & Johnson exemplify scale-driven positioning through regional psychiatric infrastructure deployment. COMPASS Pathways occupies the specialized developer tier, anchoring proprietary psilocybin formulation partnerships with academic institutions. Cybin Corp. represents the delivery-technology archetype, with its corporate designation signaling sublingual specialization.
| Leading Market Players |
|---|
| Janssen Global Services, LLC |
| Hikma Pharmaceuticals PLC |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Jazz Pharmaceuticals Inc. |
| COMPASS Pathways |
| Johnson & Johnson |
| AstraZeneca |
| Cybin Corp. |
| Others |
Supply & Pricing Matrix
European contract manufacturers anchor active pharmaceutical ingredient sourcing for Middle East and Africa psychedelic trials, concentrating margin capture upstream while South African academic medical centers and Israeli hospitals compete for downstream therapy revenue pools. Biosynthetic production methods at University of Cape Town and Stellenbosch University are collapsing this dependency structure, redistributing value toward investigator-initiated trial sponsors.
Pricing Analysis
Long-term offtake agreements between academic medical centers and biosynthetic producers dominate contract structures, compressing spot-market premiums for research-grade psilocybin. Three-tier pricing structure across GMP-certified, research-grade, and compounding-pharmacy tiers separates premium intravenous administration from sublingual outpatient formats. Cost compression in oral formulations is intensifying as natural-extraction scalability improves, though cold-chain logistics sustain premium positioning for intravenous delivery. Rehabilitation centers exhibit highest price sensitivity, while Tel Aviv academic hospitals operating compassionate-use programs absorb premium pricing with minimal volume elasticity.
Supply Chain Analysis
Psilocybin feedstock draws from Netherlands-based extraction facilities, South African biosynthetic production at academic medical centers, and Israeli chemical synthesis operations for LSD derivatives. Active pharmaceutical ingredients, specialized cold-chain packaging, and certified psychotherapist training programs constitute critical input dependencies. Single-source vulnerability concentrates in GMP-certified API validation capacity, where extended timelines constrain multi-site trial expansion. Distribution runs through Johannesburg and Cape Town academic clusters for supervised administration, with Cairo-based clinical research organizations emerging as North African logistics anchors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as telehealth supervision protocols and sublingual delivery technologies create interoperability between outpatient rehabilitation settings and traditional clinic infrastructure. This ecosystem shift elevates formulation intellectual property holders over site-based service providers.
For Market Incumbents: Insulate proprietary psilocybin formulation partnerships through backward integration into biosynthetic production capacity at South African university hospitals. Expand GMP-certified manufacturing footprints ahead of Egyptian regulatory protocol finalization to preempt competitor access to North African distribution networks. The threat of investigator-initiated trial sponsorship displacement demands channel control reinforcement through exclusive academic medical center agreements.
For New Entrants and Emerging Players: Pursue sublingual delivery technology licensing opportunities with rehabilitation centers outside Johannesburg-Cape Town corridor, where psychotherapist training bottlenecks constrain incumbent expansion. Egypt's emerging manufacturing partnership protocols represent the most penetrable geography, offering first-mover positioning before formal regulatory pathway crystallization. A telehealth-integrated go-to-market angle bypasses infrastructure limitations that restrict intravenous competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward delivery-technology specialists with sublingual formulation patents and established academic medical center relationships across the analysis window. Acquisition targets should demonstrate captive supply agreements with biosynthetic producers or proprietary extraction methodologies. The signal to watch is SAHPRA authorization timeline compression for treatment-resistant depression indications, which would validate platform economics assumptions and accelerate regional investment flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Academic Medical Center Partnership | Secures investigator-initiated trial gatekeeper status and compound access control. |
| Biosynthetic Production Scale-Up | Collapsing API costs at University of Cape Town reduces European contract manufacturer dependency. |
| Compassionate-Use Program Expansion | Tel Aviv hospital pre-authorization access creates demand pressure ahead of formal marketing completion. |
| Sublingual Delivery Patent Portfolio | Cybin Corp. specialization bypasses first-pass metabolism constraints for outpatient market penetration. |
| Egyptian Manufacturing Joint Venture | Cairo clinical research organizations position to anchor North African distribution before regulatory clarity. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs leads at SAHPRA and Israel's Ministry of Health, and secondary validation through ClinicalTrials.gov entries and national narcotics control board import licensing records, anchors the qualitative findings. Drug development executives at Janssen Global Services and COMPASS Pathways, hospital procurement managers at University of Cape Town and Stellenbosch University, and formulary directors at Tel Aviv academic hospitals provided stakeholder perspectives. Bottom-up and top-down triangulation reconciled site-level trial capacity data with regional psychiatric infrastructure assessments.
Calibration against historical authorization timelines and biosynthetic production cost curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include compound type, delivery mode, end-user category, therapy area, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to investigator-initiated trial sponsorship inflows and compassionate-use program expansion rates. Forecast inputs incorporated SAHPRA risk-based framework adoption velocity and cold-chain infrastructure development outside major urban corridors.
Sensitivities concentrate around WHO substance scheduling convention revisions and national narcotics control board import licensing friction. Forecasts reflect assumptions regarding psychotherapist training pipeline expansion and GMP certification timeline stability. Cross-checking against SAHPRA quarterly authorization disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Pediatric Vaccines Market