
 Global Neuroprotective Agents Market | 2026-2036
Global Neuroprotective Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neuroprotective Agents Market Foresight
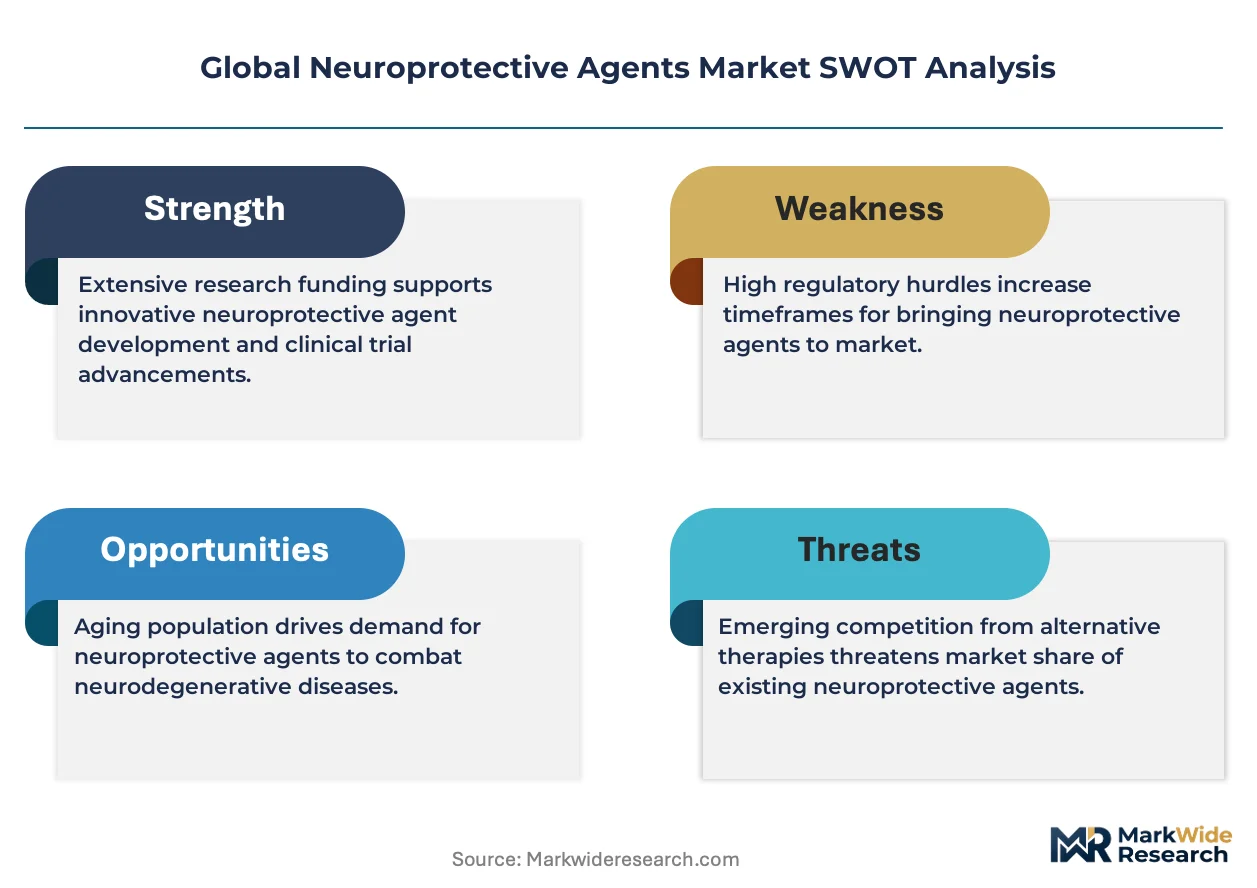
Specialty hospitals is bifurcating demand away from general neurology clinics as acute stroke protocols and post-traumatic brain injury management require concentrated infusion capabilities. Pfizer Inc anchors its position through manufacturing scale across intravenous neuroprotective formulations. Biogen Inc differentiates via R&D intensity in amyloid-targeting mechanisms for Alzheimer's applications. Novartis AG leverages its channel control through hospital pharmacy networks to secure preferential formulary placement.
Neuroprotective agents comprise pharmacological compounds designed to prevent neuronal death following ischemic, traumatic, or degenerative insults, typically administered via intravenous infusion or oral dosing within therapeutic windows measured in hours post-injury. Their primary commercial purpose centers on reducing disability burden in acute neurological events and slowing progression in chronic neurodegenerative conditions. NMDA antagonists occupy the leading position in acute stroke protocols due to established efficacy in excitotoxicity blockade, while anti-inflammatory agents represent the fastest-expanding category as microglial modulation gains mechanistic validation. Cholinesterase inhibitors constitute a mature margin pool concentrated in Alzheimer's maintenance therapy where generic competition has compressed pricing power.
FDA orphan drug incentives shape development priorities by granting seven-year market exclusivity for rare neurological indications, while EMA's centralized procedure governs European commercial access through unified scientific assessment. The EU AI Act introduces compliance requirements for algorithm-driven patient stratification tools used in neuroprotective clinical trials. Stakeholders must monitor evolving reimbursement thresholds for acute versus chronic administration as health technology assessment bodies recalibrate cost-effectiveness benchmarks.
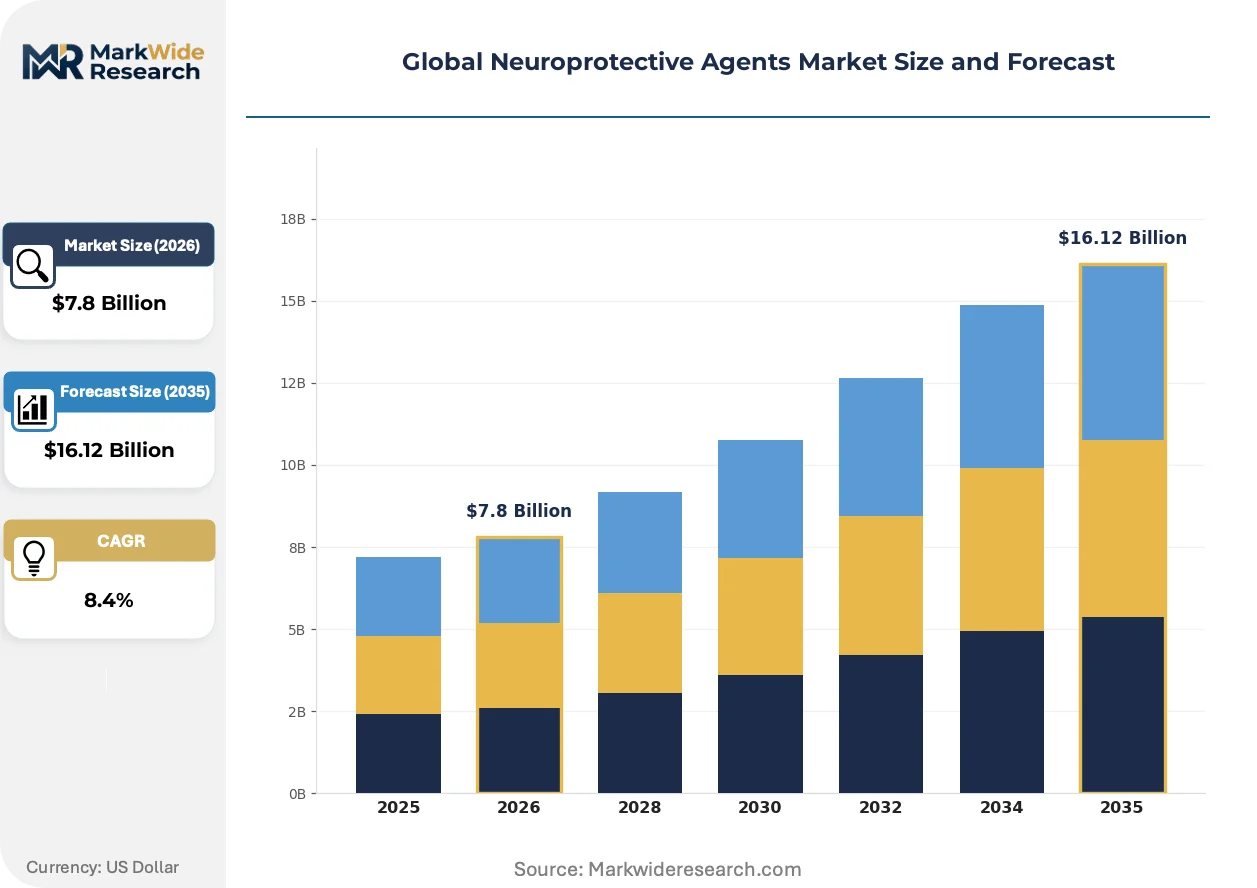
Market Dynamics
The neuroprotective agents market pivots on the tension between FDA's orphan drug exclusivity incentives and the narrowing therapeutic windows that demand faster diagnostic-to-treatment pathways in acute stroke care.
Growth Catalysts
- Orphan Drug Exclusivity:FDA's seven-year market exclusivity for rare neurological indications redirects R&D portfolios toward amyotrophic lateral sclerosis and Huntington's disease drug candidates.
- Specialty Hospital Infrastructure:Concentrated infusion capabilities in dedicated stroke centers enable administration of NMDA antagonists within the critical four-hour post-ischemia window.
- Microglial Modulation Research:Advances in neuroinflammation science validate anti-inflammatory agents as disease-modifying therapies for chronic neurodegenerative conditions.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for cholinesterase inhibitors concentrates in Chinese contract manufacturers, exposing formulators to geopolitical supply interruptions.
- Blood-Brain Barrier Limitations:Lipophilicity requirements restrict molecular design space, forcing developers toward invasive intrathecal delivery routes for large-molecule candidates.
- EMA Centralized Procedure Friction:Unified scientific assessment timelines extend commercial access delays by 12-18 months compared to national authorization pathways for urgent acute therapies.
Strategic Opportunities
- India's Stroke Burden:Underpenetrated acute stroke protocols in tier-two Indian cities create first-mover advantages for intravenous neuroprotective formulations.
- Biomarker-Driven Stratification:Convergence of liquid biopsy technology with neuroimaging enables patient selection algorithms that improve trial enrollment efficiency.
- EU AI Act Compliance Services:Algorithm-driven patient stratification tools require validation frameworks, opening advisory revenue streams for contract research organizations.
Industry Challenges
- Neuropharmacology Talent Scarcity:Blood-brain barrier pharmacokinetics expertise resides in a narrow pool of academic specialists, inflating compensation for translational researchers.
- Good Manufacturing Practice Retrofit Costs:Sterile injectable capacity expansion for neuroprotective infusions demands facility upgrades exceeding standard small-molecule oral dosing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neuroprotective Agents Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NMDA Antagonists, Calcium Channel Blockers, Antioxidants, Anti-inflammatory Agents, Cholinesterase Inhibitors Therapy Area: Alzheimer's Disease, Parkinson's Disorder, Stroke Recovery, Traumatic Brain Injury, Multiple Sclerosis End User: Neurology Clinics, Rehabilitation Centers, Research Facilities, Specialty Hospitals, Home Healthcare Providers Distribution Channel: Pharmacies, Hospital Pharmacies, Online Pharmacies, Drug Wholesalers, Direct Sales |
| Companies Covered | Merck KGaA, Novartis AG, Pfizer Inc, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Biogen Inc., Roche Holding AG, Johnson & Johnson, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neuroprotective Agents Market Shifts & Advancements
Neuroprotective development is fragmenting across mechanistic hypotheses as single-target amyloid strategies lose favor to multi-pathway interventions. Three forces are compressing traditional development timelines.
Exosome-mediated drug delivery is fragmenting established distribution assumptions for large-molecule neurotherapeutics. Biotech developers are adopting blood-brain barrier-penetrating vesicle platforms at accelerating pace. This technology is fragmenting the intravenous infusion monopoly by enabling subcutaneous administration routes for previously excluded biologics.
The EU AI Act imposes conformity assessment obligations on machine-learning patient selection algorithms used in neuroprotective trials. Developers must document training data provenance and algorithmic interpretability for centralized European Medicines Agency review. Phase II sponsors in Germany and France are restructuring clinical protocols to embed explainable AI documentation.
Hospital pharmacy committees are unbundling acute stroke bundle payments into discrete neuroprotective agent line items. United States stroke centers now negotiate drug-specific value-based contracts separate from procedural reimbursement. This shift is most visible in Medicare Advantage networks across Florida and Texas, where prior authorization requirements have compressed to 24-hour turnaround cycles.
Global Neuroprotective Agents Market Segmentation
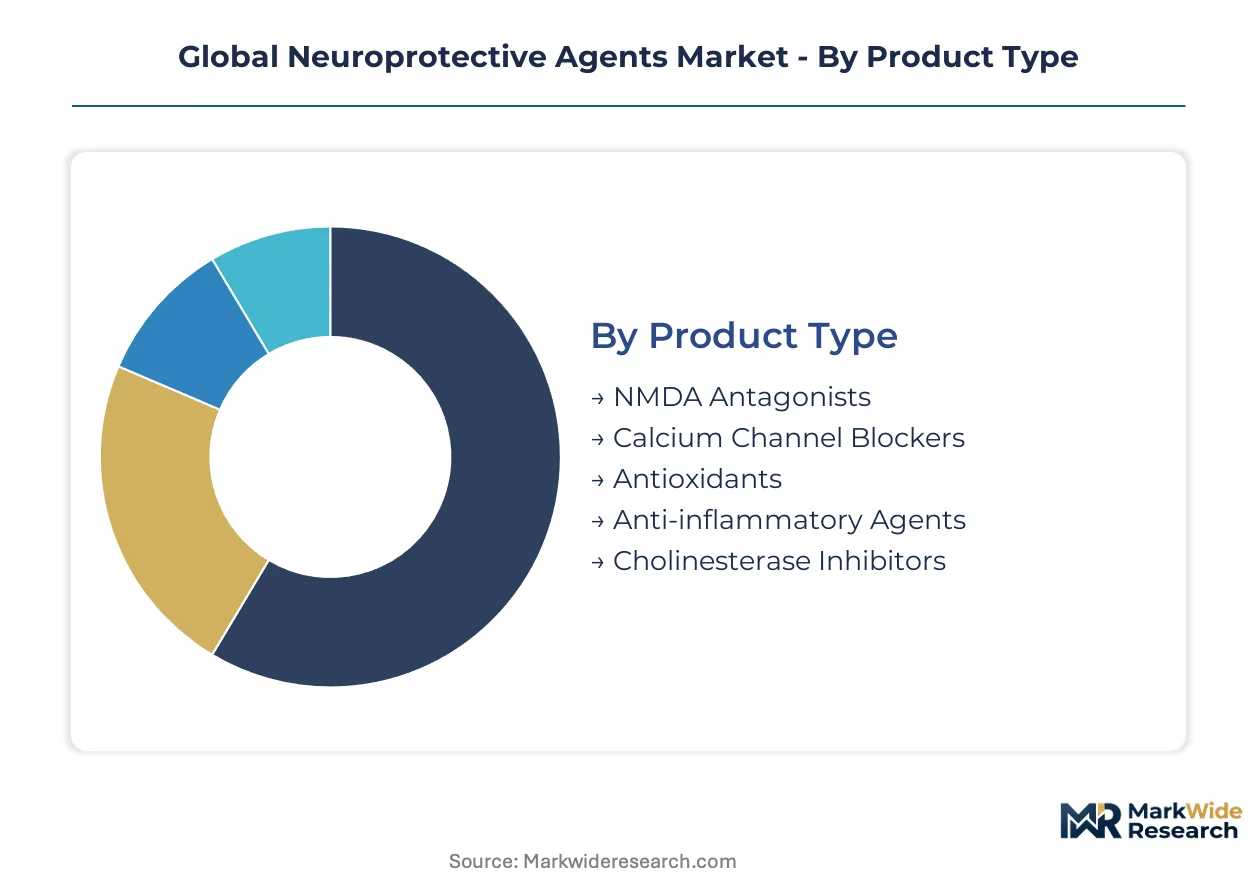
Neuroprotective agents traverse highly differentiated pathways from manufacturer to patient, with acute stroke therapies demanding hospital-based infusion infrastructure while chronic neurodegenerative maintenance therapies flow through retail and mail-order channels. Channel economics vary dramatically: intravenous NMDA antagonists command premium pricing through captive hospital pharmacy contracts, whereas oral cholinesterase inhibitors compete on formulary placement in Medicare Part D networks. Understanding these segment-specific channel dynamics enables manufacturers to optimize margin capture across the acute-chronic therapy divide.
Product Type:
Hospital pharmacy procurement committees segment neuroprotective portfolios between acute infusion therapies requiring cold-chain logistics and oral maintenance agents distributed through retail networks. NMDA antagonists and anti-inflammatory agents concentrate in stroke center formularies with 24-hour stocking requirements, while cholinesterase inhibitors and antioxidants flow through pharmacy benefit managers with 90-day dispensing cycles.
- NMDA Antagonists:These compounds block excitotoxic calcium influx in post-ischemic neurons, requiring intravenous administration within four hours of stroke onset. Demand concentrates in United States stroke centers certified by The Joint Commission, where door-to-needle time metrics drive formulary preference for agents with established pharmacokinetic profiles.
- Anti-inflammatory Agents:Microglial modulators targeting neuroinflammation represent disease-modifying candidates for chronic neurodegeneration. Germany's university hospital networks and Japan's geriatric medicine institutes are expanding clinical trial enrollment for these agents as mechanistic validation accumulates.
- Calcium Channel Blockers:Voltage-gated calcium antagonists prevent secondary neuronal injury through ischemic cascade interruption.
- Antioxidants:Free radical scavengers including edaravone formulations address oxidative stress in amyotrophic lateral sclerosis protocols.
- Cholinesterase Inhibitors:Acetylcholinesterase inhibitors constitute the oral maintenance standard for Alzheimer's symptomatic management.
By volume, cholinesterase inhibitors lead through broad geriatric prescribing. By growth pace, anti-inflammatory agents are expanding most quickly as microglial science matures.
Therapy Area:
Reimbursement architecture segments neuroprotective demand between acute event coverage with DRG-based hospital payments and chronic disease management through outpatient pharmacy benefits. Stroke recovery and traumatic brain injury therapies capture bundled procedural reimbursement, while Alzheimer's and Parkinson's agents compete for limited Medicare Part B infusion coverage versus Part D oral pharmacy allocations.
- Stroke Recovery:Acute ischemic stroke protocols represent the largest addressable acute event population, with neuroprotective administration contingent on computed tomography perfusion imaging and thrombolysis eligibility. The United States maintains the highest per-capita utilization of intravenous neuroprotective infusions, driven by comprehensive stroke center certification requirements and Medicare severity-adjusted DRG payments.
- Alzheimer's Disease:Disease-modifying neuroprotective development has shifted from single-target amyloid clearance toward multi-pathway interventions addressing tau propagation and synaptic preservation. Japan's regulatory pathway for conditional early approval accelerates access for symptomatic agents with biomarker endpoints.
- Parkinson's Disorder:Neuroprotective candidates target alpha-synuclein aggregation and mitochondrial dysfunction in dopaminergic neurons.
- Traumatic Brain Injury:Military and civilian concussion protocols drive demand for agents penetrating the blood-brain barrier after mechanical insult.
- Multiple Sclerosis:Remyelination-promoting neuroprotectives complement immunomodulatory disease-modifying therapies.
Stroke recovery commands the largest acute therapy expenditure. Alzheimer's disease shows the steepest expansion trajectory as biomarker-driven trial designs accelerate regulatory submissions.
End User:
Site-of-care economics fragment neuroprotective administration between high-acuity hospital settings with infusion nursing capabilities and lower-cost outpatient venues for chronic maintenance. Medicare site-neutral payment policies are compressing reimbursement differentials between hospital outpatient departments and freestanding clinics, redirecting stable chronic neurodegenerative patients toward rehabilitation centers and home infusion.
- Specialty Hospitals:Comprehensive stroke centers and level I trauma facilities concentrate acute neuroprotective administration with 24-hour pharmacy coverage and neurocritical care staffing. These institutions command preferential contracting through value-based stroke bundle arrangements with United States Medicare Advantage plans in Florida and Texas markets.
- Home Healthcare Providers:Subcutaneous neuroprotective formulations and implantable delivery systems are expanding chronic administration beyond institutional settings. Germany's disease management programs and the Netherlands' integrated care networks are piloting home-based neuroprotective protocols for stable Parkinson's patients.
- Neurology Clinics:Outpatient neurology practices manage oral neuroprotective titration and monitoring.
- Rehabilitation Centers:Post-acute facilities administer neuroprotective adjuncts during stroke recovery protocols.
- Research Facilities:Academic medical centers conduct phase II-III neuroprotective trials with specialized biomarker laboratories.
Specialty hospitals dominate acute therapy value capture. Home healthcare providers are gaining share fastest as subcutaneous delivery technologies mature.
Distribution Channel:
Procurement concentration shapes competitive access, with hospital pharmacy GPOs consolidating purchasing for acute neuroprotectives while retail and mail-order pharmacies fragment chronic oral therapy dispensing. Drug wholesalers maintain specialized cold-chain capabilities for temperature-sensitive biologic neuroprotectives, whereas direct manufacturer-to-hospital contracting bypasses distribution markups for high-volume stroke protocols.
- Hospital Pharmacies:Captive distribution within integrated delivery networks enables formulary control and compliance with Joint Commission medication management standards. United States health systems including Kaiser Permanente and Mayo Clinic operate centralized hospital pharmacy procurement with therapeutic class monopolies for acute neuroprotectives.
- Drug Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health distribute retail neuroprotective inventory with next-day replenishment to independent pharmacies. Wholesaler generic sourcing programs compress cholinesterase inhibitor pricing as patent expirations accumulate.
- Pharmacies:Community and specialty pharmacies dispense oral maintenance neuroprotectives with medication therapy management services.
- Online Pharmacies:Mail-order fulfillment captures 90-day supply dispensing for Medicare Part D chronic therapy optimization.
- Direct Sales:Manufacturer field representatives negotiate hospital system contracts for acute neuroprotective placement.
Hospital pharmacies lead by revenue per unit. Online pharmacies are climbing the fastest as Medicare Part D mail-order mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract manufacturers export active pharmaceutical ingredients for cholinesterase inhibitors to United States formulators, establishing a transatlantic trade corridor that shapes regional supply security calculations.
United States
Comprehensive stroke center certification by The Joint Commission drives intravenous neuroprotective utilization, with Medicare severity-adjusted DRG payments enabling premium pricing for acute infusion therapies. FDA orphan drug exclusivity redirects venture funding toward amyotrophic lateral sclerosis candidates. The Boston-Cambridge biotechnology cluster concentrates phase II-III trial activity for blood-brain barrier-penetrating formulations.
Germany
University hospital networks in Heidelberg and Berlin expand microglial modulator enrollment as mechanistic validation accumulates for chronic neurodegeneration. EMA centralized procedure timelines extend commercial access delays, prompting sponsors to prioritize parallel national authorization pathways. The Rhine-Main pharmaceutical manufacturing corridor anchors European API production for NMDA antagonist precursors.
Japan
Conditional early approval pathways accelerate symptomatic agent access where biomarker endpoints demonstrate disease modification. PMDA reviews prioritize Alzheimer's therapies addressing tau propagation alongside amyloid clearance. The Kansai region's geriatric medicine institutes pilot subcutaneous neuroprotective protocols for stable Parkinson's patients.
India
Tier-two cities including Pune and Ahmedabad present first-mover opportunities as acute stroke protocols penetrate beyond metropolitan stroke centers. CDSCO streamlined approval timelines for drugs with prior FDA or EMA clearance compress regulatory lag. Sun Pharmaceutical Industries Ltd. anchors domestic manufacturing capacity for oral maintenance neuroprotectives distributed across South Asian markets.
China
Aging demographics in the Yangtze River Delta drive clinical uptake of intravenous stroke therapies within hospital-based infusion networks. NMPA priority review vouchers for rare disease indications attract multinational sponsors to partner with domestic contract research organizations. The Beijing-Tianjin-Hebei corridor concentrates neuroimaging biomarker laboratory capacity supporting patient stratification algorithms.
Global Neuroprotective Agents Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established hospital pharmacy channel control, creating tiered competition between manufacturing-scale anchors and R&D-intensive specialists. Consolidation concentrates around intravenous formulation capabilities and sterile injectable capacity. Three archetypes dominate: multinational conglomerates with therapeutic class monopolies, biotechnology specialists pursuing disease-modifying mechanisms, and emerging market formulators competing on oral maintenance therapy cost structures. Competitive moves center on manufacturing facility upgrades for cold-chain biologics and strategic partnerships for blood-brain barrier delivery platforms.
Among diversified pharmaceutical conglomerates, Pfizer Inc and Novartis AG exemplify scale-driven archetypes with established hospital formulary positioning, while Biogen Inc occupies a specialist tier focused on amyloid-targeting R&D intensity. Roche Holding AG and Merck KGaA represent European-based anchors with channel control through centralized hospital pharmacy networks. Johnson & Johnson and GlaxoSmithKline plc sit within the acute-chronic therapy portfolio diversification segment. Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. exemplify emerging market formulators competing on oral neuroprotective manufacturing scale.
| Leading Market Players |
|---|
| Merck KGaA |
| Novartis AG |
| Pfizer Inc |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Biogen Inc. |
| Roche Holding AG |
| Johnson & Johnson |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between United States health systems and sterile injectable manufacturers lock in both API supply access and price visibility for intravenous neuroprotective formulations. These contracts insulate stroke centers from spot-market volatility in active pharmaceutical ingredient costs while embedding volume commitments that shape procurement committee formulary decisions.
Pricing Analysis
Next-generation blood-brain barrier-penetrating formulations command substantial premiums over established intravenous NMDA antagonists and mature oral cholinesterase inhibitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by therapeutic window urgency and biomarker stratification capability. Cost compression in oral maintenance tiers is intensifying because Indian and Chinese generic manufacturers are expanding cholinesterase inhibitor capacity. Hospital pharmacy committees exhibit lowest price sensitivity for acute stroke protocols where door-to-needle metrics override procurement cost concerns, while Medicare Part D plans demonstrate highest sensitivity for 90-day maintenance dispensing.
Supply Chain Analysis
Sterile injectable manufacturing capacity in the Rhine-Main corridor and the Boston-Cambridge biotechnology cluster constitutes a critical chokepoint for intravenous neuroprotective formulation supply. Active pharmaceutical ingredient production draws from Chinese contract manufacturers for small-molecule precursors and German specialty chemical producers for NMDA antagonist intermediates. Single-source vulnerability concentrates in blood-brain barrier pharmacokinetics expertise residing with narrow academic specialist pools. Distribution runs through hospital pharmacy group purchasing organizations for acute therapies and pharmacy benefit manager networks for chronic oral agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic and biomarker testing services are expanding faster than neuroprotective drug hardware, creating service-attach opportunities that extend per-patient revenue capture beyond the pharmaceutical ingredient itself.
For Market Incumbents: Fortify sterile injectable manufacturing capacity through facility upgrades exceeding standard small-molecule oral dosing lines, as FDA orphan drug exclusivity incentives attract emerging competitors to rare neurological indications. Deepen backward integration into active pharmaceutical ingredient production to offset geopolitical supply interruption exposure from Chinese contract manufacturer concentration. Channel control through hospital pharmacy networks remains the priority lever for formulary placement defense against R&D-intensive biotechnology specialists. For New Entrants and Emerging Players: Differentiate on subcutaneous delivery technology platforms that fragment the intravenous infusion monopoly and enable home healthcare administration routes previously excluded to biologics. Tier-two Indian cities including Pune and Ahmedabad present the most penetrable geography for first-mover intravenous neuroprotective protocols. EU AI Act compliance advisory services for algorithm-driven patient stratification tools offer a services-first go-to-market angle that precedes pharmaceutical product registration. For Investors and Strategic Acquirers: Blood-brain barrier delivery platform specialists with validated exosome-mediated vesicle technology represent the acquisition target archetype most likely to consolidate mechanistic validation into scalable manufacturing. Long-term viability frames around ten-year windows where multi-pathway interventions displace single-target amyloid strategies. The signal to watch is Japan PMDA conditional early approval pathway utilization rates for symptomatic agents with biomarker endpoints, which indicate regulatory appetite for accelerated access mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II-III progression for microglial modulators validates disease-modifying mechanisms in Germany's university hospital networks. |
| Regulatory Approval Pathway | FDA orphan drug designation accelerates development timelines for amyotrophic lateral sclerosis candidates with seven-year exclusivity. |
| Manufacturing Scale-Up | Sterile injectable capacity expansion demands facility upgrades exceeding standard small-molecule lines for cold-chain biologics. |
| Pipeline Diversification | Multi-pathway interventions addressing tau propagation and synaptic preservation reduce reliance on amyloid-targeting mechanisms. |
| Strategic Partnership | Contract research organization alliances for EU AI Act compliance embed explainable AI documentation in German and French protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases to validate market sizing and competitive positioning assessments. Primary interviews engaged drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across the United States, Germany, Japan, and India. Bottom-up patient-flow modeling triangulates against top-down pharmaceutical expenditure data to anchor volume and value estimates.
Segmentation dimensions modeled span product type, therapy area, end user, and distribution channel across the analysis window. Administration route stratification separates intravenous acute therapies from oral maintenance agents, while regional regulatory clusters capture FDA, EMA, PMDA, CDSCO, and NMPA pathway differentiation. CAGRs derive from therapeutic window expansion assumptions, biomarker-driven trial enrollment efficiency gains, and site-of-care shift trajectories toward home healthcare delivery.
Material uncertainties — reimbursement threshold recalibrations by health technology assessment bodies, blood-brain barrier delivery platform clinical validation failures, and API supply interruptions from geopolitical friction — sit outside the modeled envelope. Forecasts reflect assumptions around orphan drug exclusivity incentive continuity and microglial modulation mechanistic validation accumulation. Practitioners should keep alternative scenarios live as health technology assessment body cost-effectiveness benchmarks and EU AI Act enforcement precedents evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Amlodipine Besylate Market