
 Wireless Healthcare Asset Management Market | 2026-2036
Wireless Healthcare Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Healthcare Asset Management Market Outlook
The EU Medical Device Regulation (MDR) is expanding traceability mandates across acute care networks, compelling hospitals to deploy automated asset identification systems. CenTrak leverages its ultrasound-RFID hybrid architecture to dominate European installations requiring sub-room accuracy. Zebra Technologies Corporation sustains competitive pressure through its deep channel control in North American health system procurement. Impinj anchors the hardware layer with RAIN RFID chipsets that power third-party tag manufacturers.
Wireless healthcare asset management comprises real-time location systems, sensor networks, and cloud-native software platforms that track medical equipment, supplies, and personnel through radio-frequency identification, Bluetooth Low Energy, Wi-Fi triangulation, or ultra-wideband signaling with positional accuracy ranging from centimeters to room level. These systems primarily reduce capital expenditures by cutting equipment hoarding, shrinkage, and search-time losses while generating utilization analytics for capital planning. RFID tags and Bluetooth beacons represent the most mature hardware segments with established manufacturing scale, though software platforms and cloud solutions concentrate margin pools through recurring SaaS contracts and integration fees. Sensors for condition monitoring—temperature, humidity, shock—are gaining traction fastest in pharmaceutical supply chain extensions of hospital networks.
The FDA's Unique Device Identification (UDI) system and the EU MDR jointly shape product standards by mandating machine-readable identifiers on regulated medical devices, which asset management platforms must parse and reconcile with location data. HIPAA in the United States and GDPR in Europe constrain how patient-proximate location data is stored, transmitted, and anonymized, creating compliance overhead that favors vendors with healthcare-specific security certifications. Stakeholders must weigh interoperability investments against the risk of stranded infrastructure as health systems consolidate onto fewer enterprise platforms.
Market Dynamics
Hospital capital budgets are compressing procurement cycles for real-time location systems as CFOs demand measurable ROI within eighteen months, forcing vendors to restructure pricing around utilization guarantees rather than hardware markups.
Growth Catalysts
- EU Medical Device Regulation traceability mandates:Acute care networks must deploy automated asset identification to satisfy device-tracking requirements, creating pull-through demand for integrated RFID-software platforms.
- Bluetooth Low Energy tag economics:Manufacturing scale has driven per-unit costs below legacy active RFID, enabling health systems to tag lower-value equipment previously excluded from tracking programs.
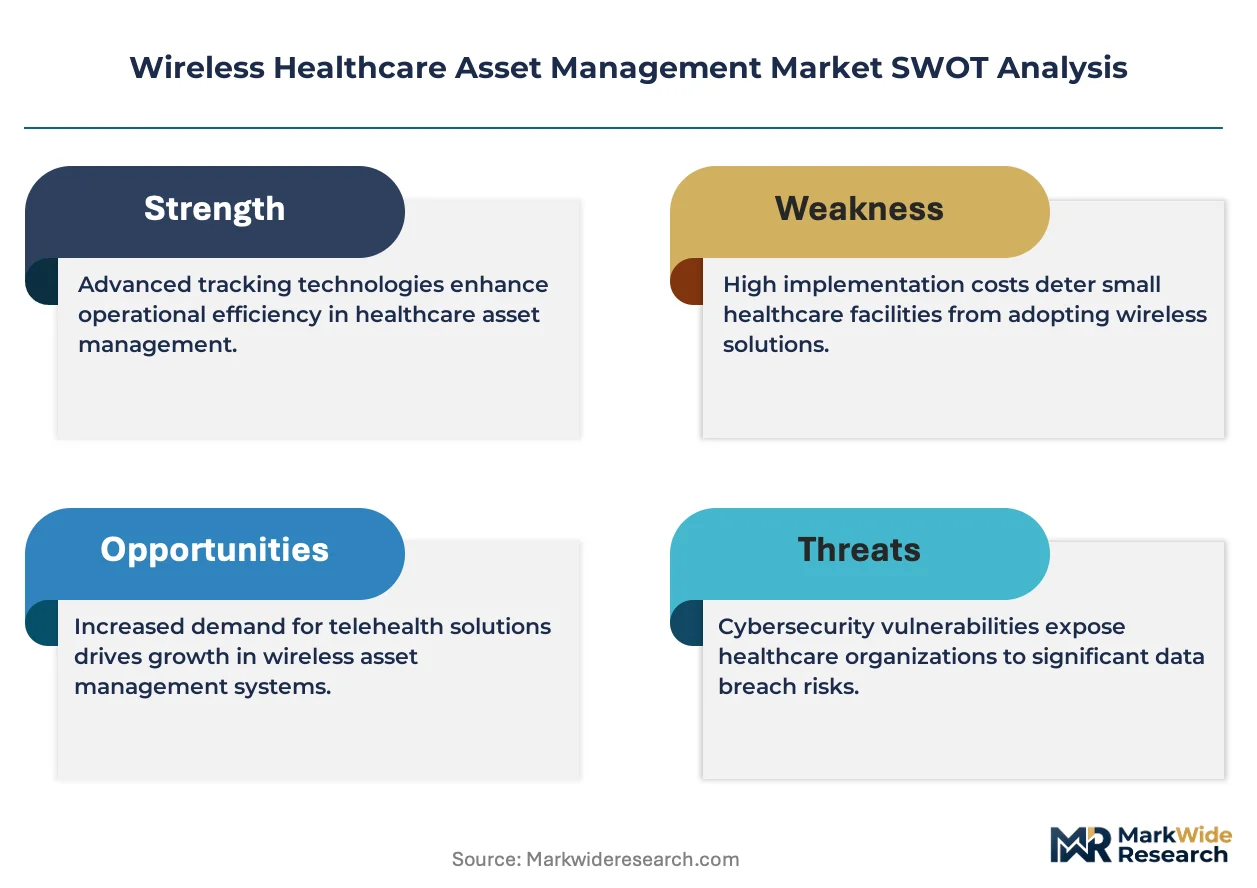
- Joint Commission audit pressure:US hospital systems face escalating surveyor scrutiny on equipment availability documentation, accelerating RTLS procurement to demonstrate compliance during unannounced inspections.
Market Restraints
- Legacy Wi-Fi infrastructure incompatibility:Many health systems operate 802.11n or older access points that cannot support location-grade timestamping without full hardware refreshes.
- Silicon supply concentration:RAIN RFID chipsets depend on a limited number of foundry sources in East Asia, creating vulnerability to geopolitical disruption or export control expansion.
- HIPAA-GDPR compliance overhead:Patient-proximate location data requires anonymization architectures that add implementation cost and legal review cycles, disadvantaging smaller vendors without healthcare-specific security certifications.
Strategic Opportunities
- Pharmaceutical cold-chain extension:Hospital networks are expanding asset management platforms into vaccine and biologics distribution, attaching temperature-humidity sensors to existing location infrastructure.
- India's hospital accreditation push:NABH standards are beginning to mirror Joint Commission requirements, opening greenfield deployment opportunities as private hospital chains modernize.
- Ultra-wideband-Bluetooth convergence:Hybrid architectures combining UWB centimeter accuracy with BLE cost structures are enabling new use cases in surgical instrument tracking and patient flow optimization.
Industry Challenges
- RF engineering talent scarcity:Health systems lack in-house expertise to optimize antenna placement and multipath interference mitigation in complex clinical environments.
- EMR integration complexity:Location data must flow into Epic, Cerner, and Meditech workflows through proprietary APIs, requiring vendor-specific customization that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Healthcare Asset Management Market |
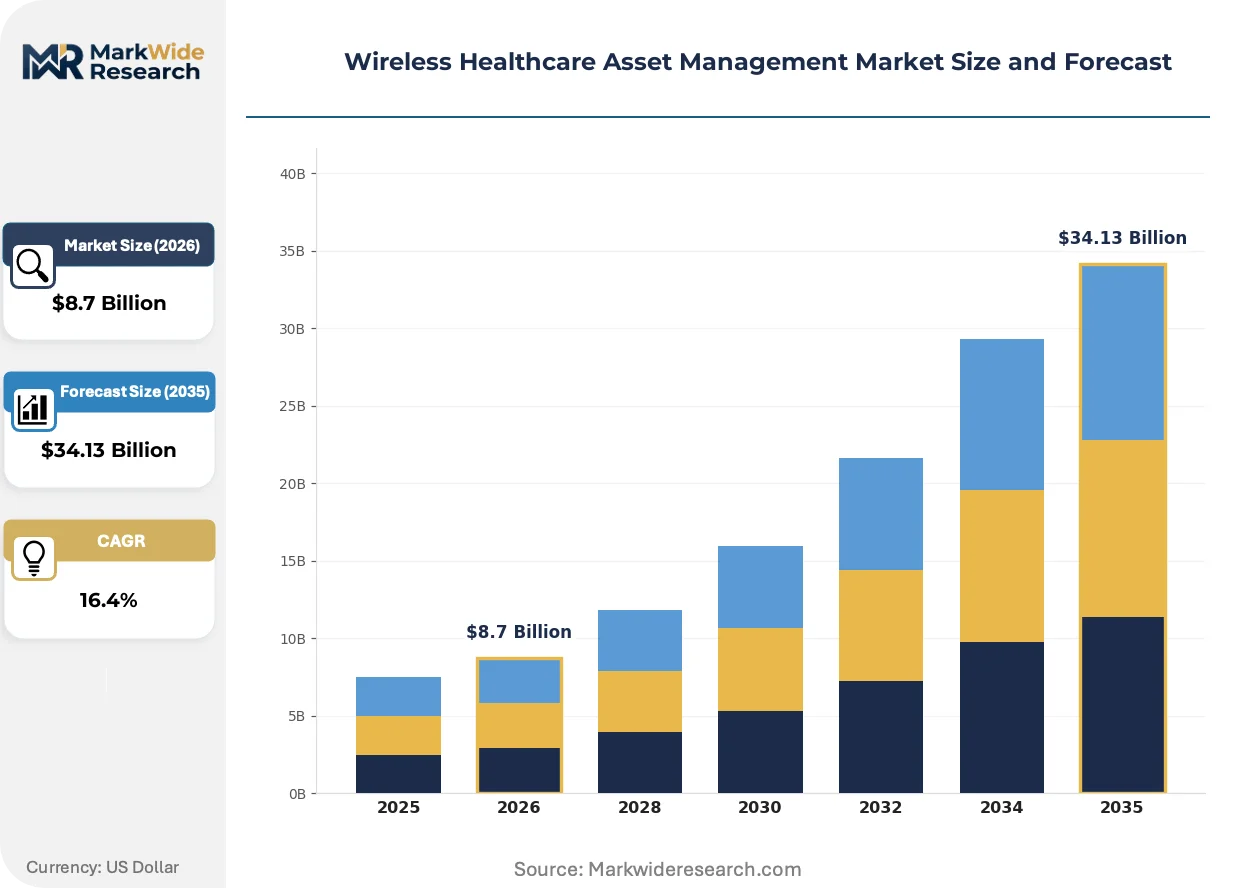
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, GPS, Wi-Fi, Bluetooth Product Type: Tags, Sensors, Software Platforms, Cloud Solutions Application: Asset Tracking, Inventory Management, Workflow Optimization, Patient Monitoring End User: Hospitals, Clinics, Laboratories, Rehabilitation Centers |
| Companies Covered | CenTrak, Zebra Technologies Corporation, Cisco Systems, Airista Flow, GE HealthCare Technologies, General Electric Company, Verizon, Impinj, Stanley Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Healthcare Asset Management Market Strategic Shifts
Software-defined architectures are displacing monolithic RTLS platforms, allowing health systems to mix hardware vendors and upgrade location algorithms without forklift infrastructure replacements.
Ultra-wideband chipsets are modularizing across the hardware layer, enabling tag manufacturers to source standardized UWB radios from multiple semiconductor suppliers rather than single-source dependencies. Tier-one health systems in Germany and the United States are piloting UWB for sub-meter surgical instrument tracking. This modularity is compressing hardware development cycles and eroding proprietary radio advantages held by incumbent vendors.
The EU AI Act's risk classification framework is reshaping how predictive analytics modules within asset management platforms are validated and deployed. Algorithms forecasting equipment failure or patient flow bottlenecks now face documentation requirements for training data provenance and human oversight protocols. European health systems are delaying procurement of AI-enhanced RTLS modules until vendor compliance roadmaps clarify, while North American buyers are accelerating purchases ahead of anticipated FDA guidance convergence.
Subscription-based service models are displacing perpetual license structures across the software tier, with health systems preferring per-bed or per-asset-month pricing that aligns costs with utilization. This shift pressures vendors to retain customers through continuous feature delivery rather than upfront lock-in. The transition is most advanced in Nordic countries and the Netherlands, where procurement frameworks already favor operational expenditure treatment for digital infrastructure.
Wireless Healthcare Asset Management Market Segmentation
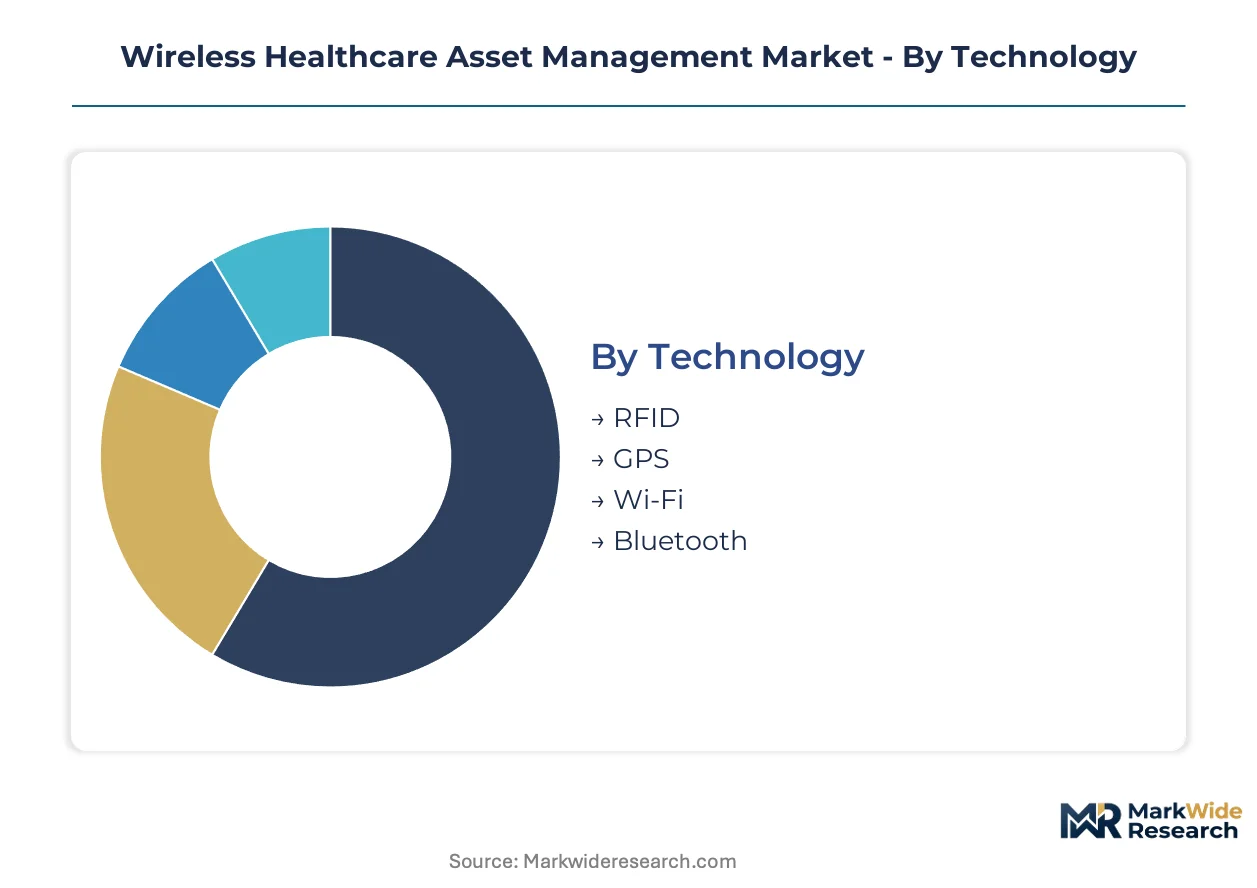
Technology choices in wireless healthcare asset management determine installation complexity, accuracy thresholds, and total cost of ownership across acute care networks. Product configurations and application scopes further differentiate vendor offerings and shape procurement negotiations between health systems and RTLS providers.
Technology:
Procurement teams select radio protocols based on required positional precision, existing infrastructure compatibility, and per-tag economics across their equipment fleets.
- RFID:Passive and active radio-frequency identification systems operate across unlicensed spectrum bands, with passive tags drawing power from reader interrogation signals. Hospital systems in Germany and the United States deploy RFID for high-volume equipment tracking where room-level accuracy satisfies clinical workflows, driven by EU MDR traceability mandates that require machine-readable device identifiers.
- Bluetooth:Bluetooth Low Energy beacons transmit advertising packets at configurable intervals, enabling battery-powered operation for five to seven years. Nordic health systems and Dutch hospital networks prioritize BLE for lower-value assets previously excluded from tracking programs, as manufacturing scale has compressed per-unit costs below legacy active RFID alternatives.
- Wi-Fi:Location-grade timestamping over existing wireless LAN infrastructure requires 802.11ac or newer access points with round-trip time measurement capabilities. Many health systems operate older hardware that cannot support positioning without full infrastructure refreshes, constraining adoption despite zero incremental radio deployment.
- GPS:Satellite-based positioning serves outdoor asset tracking and inter-facility logistics for mobile medical equipment and emergency response vehicles. GPS integration remains limited to specialized use cases where outdoor coverage and wide-area tracking override indoor precision requirements.
RFID leads volumes today; Bluetooth is gaining share fastest as tag economics enable comprehensive equipment coverage.
Product Type:
Hardware margins compress as manufacturing scales, while software and cloud tiers concentrate recurring revenue through subscription structures and integration fees.
- Tags:RFID inlays, BLE beacons, and UWB modules attach to medical devices, supplies, and personnel badges, with form factors ranging from credit-card size to sterilizable surgical instrument enclosures. German and American tier-one health systems pilot UWB-enabled tags for sub-meter surgical instrument tracking, though BLE dominates new deployments for general equipment.
- Software Platforms:Cloud-native and on-premise applications process location streams, generate utilization analytics, and integrate with electronic medical records through proprietary APIs. Health systems in the Netherlands and Nordic countries drive subscription model adoption, preferring per-bed or per-asset-month pricing that aligns costs with operational expenditure treatment.
- Sensors:Temperature, humidity, shock, and light exposure detectors extend location infrastructure into condition monitoring for pharmaceutical cold chains. Hospital networks attach these sensors to existing RTLS deployments for vaccine and biologics distribution, representing the most rapidly expanding hardware segment.
- Cloud Solutions:Multi-tenant SaaS architectures enable software-defined RTLS configurations that mix hardware vendors and upgrade location algorithms without infrastructure replacement. Cloud concentration creates margin pools through recurring contracts, though HIPAA and GDPR compliance overhead favors vendors with healthcare-specific security certifications.
Tags dominate installed base today; sensors are expanding most quickly through cold-chain extensions.
Application:
Use case prioritization reflects capital budget pressures and measurable ROI demands from hospital CFOs seeking eighteen-month payback periods.
- Asset Tracking:Real-time location systems reduce equipment hoarding, shrinkage, and search-time losses by maintaining continuous visibility of mobile medical devices. US hospital systems accelerate procurement to satisfy Joint Commission audit requirements for equipment availability documentation during unannounced inspections.
- Workflow Optimization:Patient flow analytics, staff coordination, and bed turnover acceleration generate operational efficiency gains beyond basic inventory management. German health systems pilot UWB-Bluetooth hybrid architectures for surgical instrument tracking and emergency department throughput improvement.
- Inventory Management:Automated par-level monitoring and supply chain integration reduce stockouts and carrying costs for consumables and implantable devices. RFID-based systems parse FDA Unique Device Identification codes to reconcile location data with regulatory traceability requirements.
- Patient Monitoring:Wandering prevention, fall risk alerts, and contact tracing applications leverage location data for safety and infection control protocols. GDPR constraints on patient-proximate location data storage and anonymization add implementation cost and legal review cycles.
Asset tracking commands the largest deployment base; workflow optimization is climbing the fastest as health systems prioritize operational efficiency over compliance-only investments.
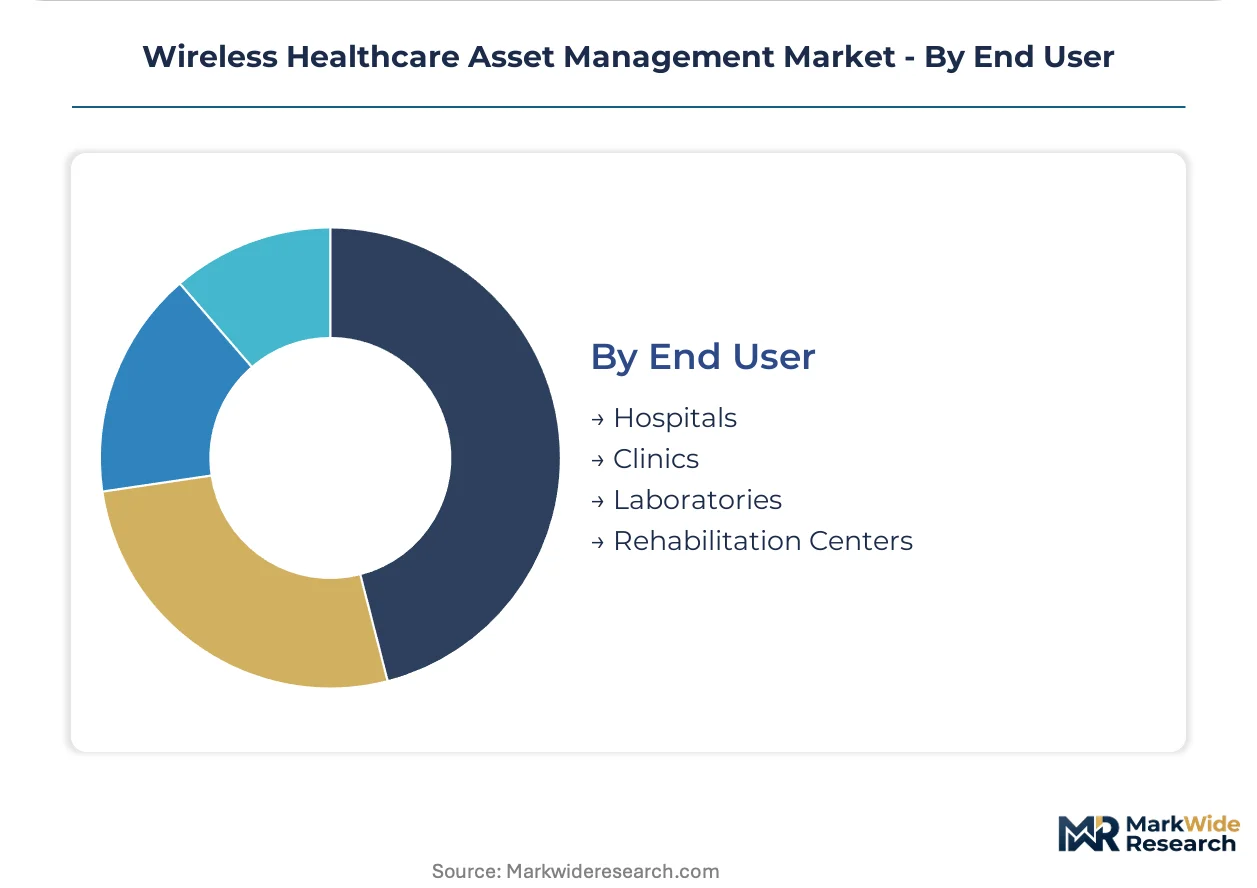
End User:
Facility scale and regulatory exposure determine system complexity, integration requirements, and vendor selection criteria across care settings.
- Hospitals:Acute care networks with hundreds of beds and diverse equipment fleets require sub-room accuracy, EMR integration, and enterprise-scale software platforms. EU MDR traceability mandates and Joint Commission audit pressure drive the largest procurement volumes for integrated RFID-software systems.
- Clinics:Ambulatory and specialty care facilities prioritize lower-cost BLE deployments with cloud-native software, accepting room-level or zone-based accuracy for reduced infrastructure investment. India's private hospital chains modernize under NABH accreditation standards that mirror Joint Commission requirements.
- Laboratories:Diagnostic and research facilities attach condition-monitoring sensors to samples, reagents, and equipment requiring temperature and humidity control. Pharmaceutical cold-chain extensions of hospital networks concentrate demand for sensor-enabled location platforms.
- Rehabilitation Centers:Long-term care and physical therapy facilities deploy patient monitoring applications for wandering prevention and staff safety alerts. Smaller scale and limited IT resources favor simplified cloud solutions over enterprise RTLS platforms.
Hospitals anchor procurement volumes today; clinics are expanding most quickly as BLE economics democratize asset tracking across smaller facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered hospital real-time location systems during the 2000s Joint Commission accreditation expansions. German health systems subsequently scaled ultrasound-RFID hybrid architectures to satisfy emerging traceability mandates. Today procurement concentrates across five national markets where regulatory pressure and capital availability intersect.
United States
Joint Commission unannounced inspections and FDA Unique Device Identification requirements drive acute care network procurement. Hospital CFOs demand eighteen-month ROI guarantees, compressing vendor pricing toward utilization-based models. The Boston-Cambridge corridor hosts concentrated RTLS software development clusters serving tier-one health systems.
Germany
EU Medical Device Regulation traceability mandates compel automated asset identification across university hospital networks. CenTrak dominates installations requiring sub-room accuracy through ultrasound-RFID hybrid deployments. The Munich-Stuttgart industrial corridor anchors precision sensor manufacturing for surgical instrument tracking applications.
Netherlands
Dutch hospital networks prioritize Bluetooth Low Energy economics for comprehensive equipment coverage previously excluded from tracking programs. Procurement frameworks favor operational expenditure treatment, accelerating subscription-based SaaS adoption. The Eindhoven-Utrecht corridor concentrates health technology integration expertise.
India
NABH accreditation standards mirror Joint Commission requirements, opening greenfield deployment opportunities as private hospital chains modernize. BLE tag manufacturing scale enables lower-value asset tracking across mid-tier facilities. The Bangalore-Hyderabad corridor hosts emerging health technology implementation clusters.
United Kingdom
NHS capital constraints favor phased BLE deployments with cloud-native software over infrastructure-heavy alternatives. GDPR compliance overhead disadvantages smaller vendors lacking healthcare-specific security certifications. The London-Oxford corridor concentrates health informatics integration capabilities for EMR-linked location platforms.
Wireless Healthcare Asset Management Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-platform differentiation, with recurring SaaS contracts concentrating margin pools while hardware tag manufacturing compresses toward cost-plus structures. The vendor base stratifies between integrated platform providers, specialized hardware manufacturers, and telecommunications infrastructure operators. Three archetypes dominate: ultrasound-RFID hybrid specialists, enterprise mobility hardware incumbents, and semiconductor chipset suppliers. Competitive dynamics center on EMR integration depth and healthcare-specific security certification acquisition rather than raw location accuracy specifications.
Within the integrated platform tier, CenTrak and Zebra Technologies Corporation occupy positions exemplifying divergent architectural approaches to sub-room accuracy requirements. Impinj anchors the hardware layer as a semiconductor supplier whose RAIN RFID chipsets power third-party tag manufacturers across multiple vendor ecosystems. These three entities represent distinct competitive vectors—hybrid radio specialization, enterprise channel control, and component-level supply—rather than direct substitution threats.
| Leading Market Players |
|---|
| CenTrak |
| Zebra Technologies Corporation |
| Cisco Systems |
| Airista Flow |
| GE HealthCare Technologies |
| General Electric Company |
| Verizon |
| Impinj |
| Stanley Healthcare |
| Others |
Value Chain & Pricing Dynamics
RAIN RFID chipset fabrication costs cascade through hardware tiers, compressing tag margins while software platforms capture recurring value through subscription structures anchored in healthcare-specific security certifications.
Pricing Analysis
Per-bed and per-asset-month subscription models dominate software procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by EMR integration depth and GDPR-HIPAA certification grade. Price differentiation stems from healthcare-specific security overhead and utilization guarantee commitments. Cost compression in hardware tags is intensifying because manufacturing scale has commoditized BLE beacon production. Mid-tier health systems exhibit highest price sensitivity, while university hospital networks prioritize accuracy specifications over per-unit economics.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries supplying RAIN RFID chipsets, creating exposure to export control expansion. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while precision sensor assembly anchors in Germany and the United States. Raw material dependencies span silicon wafers, lithium coin cells, and sterilizable polymer enclosures. Tariff exposure on radio modules threatens margin stability for hardware vendors. Distribution runs through health system GPO contracts and direct enterprise sales to hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with EU MDR traceability mandates and Joint Commission audit pressure creating procurement pull-through across acute care networks.
For Market Incumbents: Hedge against UWB-Bluetooth hybrid disruption by securing semiconductor supply agreements with multiple foundry sources. Defensive consolidation of EMR integration capabilities protects against software-defined architecture displacement. Channel control through GPO contracts remains the priority lever for margin defense. For New Entrants and Emerging Players: The mid-tier pricing gap between CenTrak's ultrasound-RFID premiums and commodity BLE tags creates white-space for hybrid accuracy solutions. India's NABH modernization drive offers the most penetrable geography for greenfield deployment. A cloud-native SaaS entry with per-asset-month pricing bypasses capital budget friction. For Investors and Strategic Acquirers: Roll-up economics work for regional software integrators because EMR customization requirements fragment vendor landscapes across health system footprints. Long-term viability favors platforms with HIPAA-GDPR dual certification and recurring revenue concentration. Watch FDA guidance convergence on AI-enhanced RTLS modules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner integration capabilities lock in multi-year enterprise contracts. |
| CE Marking Pathway | EU MDR compliance accelerates automated asset identification procurement cycles. |
| Software Companion Development | AI-enhanced predictive analytics modules command premium subscription tiers. |
| Strategic Partnership | Impinj chipset alliances enable rapid tag manufacturer ecosystem expansion. |
| Geographic Expansion | NABH-accredited Indian hospital chains require BLE infrastructure at scale. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and RTLS vendor sales executives alongside secondary validation through FDA UDI database filings, EU MDR implementation guidance, hospital procurement databases, and GPO contract repositories. Bottom-up equipment deployment counts triangulate against top-down health system capital expenditure surveys.
Granularity-level modeling disaggregates the projection horizon by radio protocol, product tier, application use case, and facility scale, with CAGRs derived from equipment replacement cycles and regulatory compliance deadlines. Technology diffusion curves incorporate EMR integration complexity scores and healthcare-specific security certification acquisition timelines as industry-specific forecast inputs.
Caveats apply where silicon supply disruption, export control expansion, or EMR vendor consolidation could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement intensity and health system capital availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
US Population Health Management Market
Health Data Management
Big Data Healthcare Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Hospital Management Software Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Medical Record Management System Market
Health Data Management
Healthcare Data De-Identification Assurance Market