
 Cell Culture Media Storage Containers Market | 2026-2036
Cell Culture Media Storage Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Culture Media Storage Containers Market Analytics
ISO 13485 certification is reorganizing competitive access in cell culture media storage containers, as contract manufacturers and end users now require documented quality management systems for single-use assemblies. Thermo Fisher Scientific leverages its integrated life sciences platform to control distribution across North American bioproduction hubs. Sartorius AG anchors its position through specialized bioreactor bag portfolios designed for perfusion cell culture workflows. Merck KGaA differentiates via upstream filtration and storage compatibility testing that reduces contamination risk in serum-free media handling.
Cell culture media storage containers are sterile vessels engineered from cyclic olefin polymer, borosilicate glass, or multilayer fluoropolymer films, designed to maintain pH stability, osmolality, and sterility across frozen and ambient temperature ranges for mammalian and microbial culture propagation. Plastic bottles occupy the largest volume share due to cost efficiency in routine academic and clinical research settings, while bioreactor bags represent the fastest-expanding category as perfusion and continuous manufacturing platforms displace stainless-steel tanks in commercial biologics production. Closure systems show margin concentration in validated screw-cap assemblies with integrated septa, which pharmaceutical companies specify for aseptic connection integrity.
The US FDA enforces container closure integrity standards under biologics license applications, while the EMA's Annex 1 revision on sterile manufacturing elevates particulate and endotoxin limits for single-use systems in European facilities. ISO 10993 biocompatibility testing and USP Class VI certification now function as baseline market access requirements rather than differentiators. Stakeholders must monitor how regulatory convergence between FDA process validation guidance and EMA good manufacturing practice updates reshapes supplier qualification timelines and capital allocation toward closed-system architectures.
Market Dynamics
Single-use bioprocessing is decomposing the installed base of stainless-steel infrastructure, forcing container suppliers to reengineer closure integrity and material compatibility for perfusion workflows at commercial scale.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile manufacturing guidelines mandate closed-system architectures for biologics production, accelerating validated storage container procurement across European facilities.
- Perfusion Cell Culture:Continuous manufacturing platforms require specialized bioreactor bags with integrated sampling ports, pulling demand from fed-batch stainless systems in mammalian cell therapy workflows.
- Boston-San Diego Clusters:Concentrated cell and gene therapy manufacturing in these US hubs drives procurement of high-capacity flexible containers with validated closure systems.
Market Restraints
- Fluoropolymer Film Supply:Multilayer film production concentrates among specialized chemical suppliers, creating input cost volatility for bioreactor bag manufacturers.
- ISO 13485 Certification Burden:Contract manufacturers now require documented quality management systems, extending supplier qualification timelines and freezing out uncertified entrants.
- Glass Bottle Substitution Ceiling:Borosilicate containers retain preference for small-volume serum applications, limiting plastic bottle penetration in legacy research settings.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's streamlined biologics approval pathways and PLI scheme incentives attract contract manufacturing investment, creating demand for single-use storage systems.
- Closed-System Integration:Convergence of aseptic connector technology with pre-sterilized container assemblies enables fully automated media transfer without cleanroom intervention.
- Direct Distribution Platforms:Biopharma procurement teams increasingly source validated containers through manufacturer-direct channels, compressing distributor margins and rewarding integrated suppliers.
Industry Challenges
- Extractables-Leachables Validation:Demonstrating container material compatibility with chemically defined media requires extended stability studies, stretching R&D timelines for new polymer formulations.
- Aseptic Processing Skill Gap:Qualified personnel for container closure integrity testing and sterile connection validation remain scarce in expanding manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Culture Media Storage Containers Market |
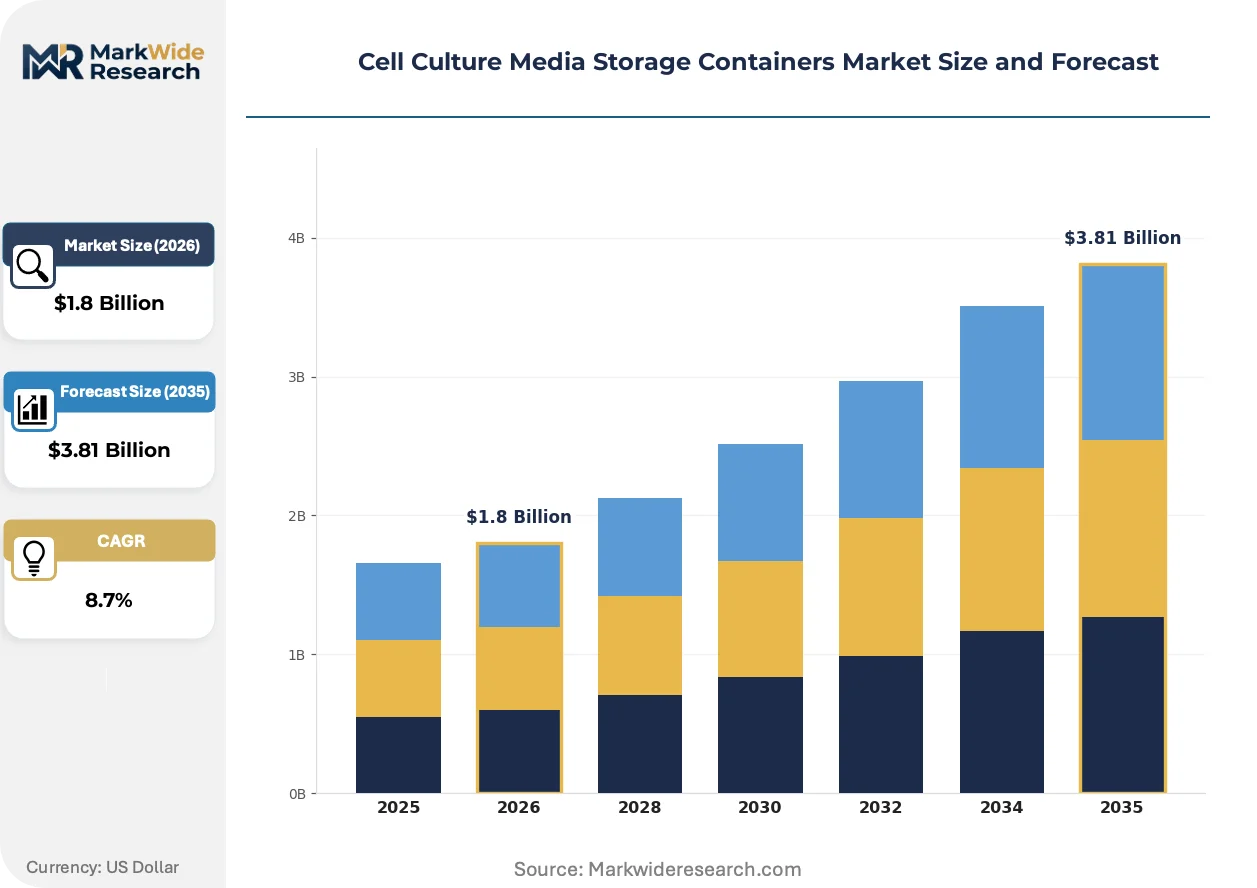
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bottles, Glass Vials, Aluminum Containers, Bioreactor Bags Closure System: Screw Caps, Snap Caps, Stopper Caps, Corks End User: Pharmaceutical Companies, Academic Institutions, Biotech Firms, Research Laboratories Capacity: 1 Liter, 5 Liters, 10 Liters, 20 Liters |
| Companies Covered | Thermo Fisher Scientific Inc., Corning Incorporated, Merck KGaA, Sartorius AG, Danaher Corporation, Greiner Bio-One International GmbH, Saint-Gobain Group, VWR International, LLC, Cytiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Culture Media Storage Containers Market Evolving Landscape
Container architecture is fragmenting into application-specific designs, with material science and regulatory convergence jointly determining which formats capture volume in biologics versus research settings.
Multilayer fluoropolymer film technology is decomposing the barrier between storage and bioreactor functionality. Commercial cell therapy manufacturers in the United States now specify single-use assemblies that transition directly from frozen media storage to perfusion culture without transfer steps. This convergence is compressing demand for standalone storage bottles while expanding the addressable market for integrated bag-reactor systems.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of conventional barrier films used in cell culture containers. The industrial consequence is accelerated development of cyclic olefin polymer alternatives with comparable gas permeation resistance. European biopharma facilities are responding by qualifying these next-generation materials ahead of anticipated substance restrictions.
Buyer consolidation among contract development and manufacturing organizations is compressing supplier qualification cycles. Large CDMOs now mandate pre-validated container assemblies with documented extractables profiles, displacing custom specification development with smaller research institutions. This pattern concentrates procurement leverage in the United States and Germany, where the largest biologics manufacturing service providers operate.
Cell Culture Media Storage Containers Market Segmentation
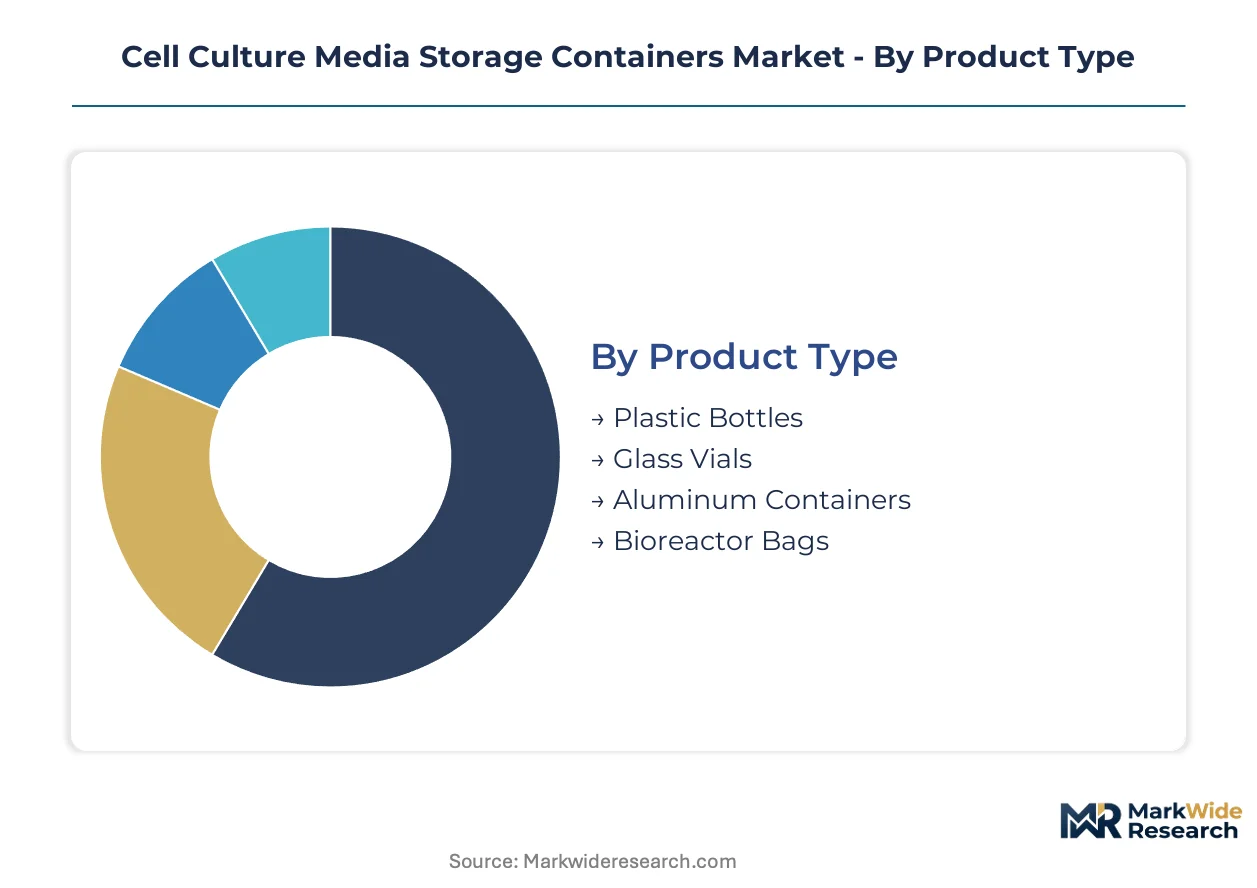
Segmentation in cell culture media storage containers reveals how substitution pressures between materials and formats reshape procurement patterns. Product architecture, closure integrity, and capacity scaling each create distinct competitive battlegrounds with diverging margin structures.
Product Type:
Substitution pressure runs strongest against borosilicate glass as cyclic olefin polymer and multilayer fluoropolymer films capture volume in commercial bioprocessing.
- Plastic Bottles:Engineered from cyclic olefin polymer or polyethylene terephthalate with gamma-irradiated sterility assurance. Academic and clinical research facilities in the United States specify these for cost-efficient routine propagation of mammalian cell lines.
- Bioreactor Bags:Multilayer fluoropolymer film assemblies with integrated ports for perfusion workflows. Cell and gene therapy manufacturers in Boston and San Diego clusters specify these for seamless transition from frozen storage to continuous culture.
- Glass Vials:Borosilicate construction with thermal shock resistance for serum-containing media. Legacy research settings retain preference for small-volume applications where chemical inertness outweighs cost considerations.
- Aluminum Containers:Lightweight metallic vessels for bulk powder media transport. Contract manufacturing organizations specify these for intermediate storage prior to sterile filtration.
Plastic bottles retain volume leadership; bioreactor bags hold the steepest expansion curve.
Closure System:
Cost tiering separates validated pharmaceutical-grade assemblies from commodity research closures.
- Screw Caps:Polypropylene or polyethylene construction with integrated septa for aseptic needle access. Pharmaceutical companies specify validated screw-cap assemblies under FDA container closure integrity requirements.
- Stopper Caps:Elastomeric bromobutyl or chlorobutyl formulations with aluminum overseals. Commercial biologics manufacturers specify these for vial-based media storage requiring pierceable access.
- Snap Caps:Single-use polyethylene closures for rapid access in non-sterile research workflows. Academic institutions specify these for routine subculture applications where aseptic connection integrity is not mandated.
- Corks:Natural or synthetic stopper materials for legacy fermentation media storage. Specialty yeast culture facilities retain limited specification for traditional brewing and beverage applications.
Screw caps command premium pricing in validated applications; snap caps dominate unit volume in research procurement.
End User:
Customer type determines specification stringency and qualification timeline intensity.
- Pharmaceutical Companies:Integrated biologics manufacturers with documented quality management system requirements. These buyers mandate ISO 13485-certified suppliers with complete extractables-leachables profiles.
- Biotech Firms:Venture-backed cell therapy developers with accelerated manufacturing timelines. These organizations specify pre-validated single-use assemblies to compress supplier qualification cycles.
- Academic Institutions:University research laboratories with decentralized procurement authority. These end users prioritize cost efficiency and catalog availability over documented validation packages.
- Research Laboratories:Government and nonprofit research facilities with standardized equipment protocols. These buyers specify through consolidated purchasing agreements with limited supplier flexibility.
Pharmaceutical companies drive margin expansion; biotech firms are gaining share fastest in procurement volume.
Capacity:
Volume scaling aligns with manufacturing format transition from bench-scale to commercial perfusion platforms.
- 20 Liters:Large-format flexible containers for commercial perfusion bioreactor feeding. CDMOs in United States manufacturing clusters specify these for continuous culture workflows.
- 1 Liter:Standard research-grade bottles for routine cell line maintenance. Academic laboratories specify these as the baseline unit for mammalian and microbial propagation.
- 5 Liters:Intermediate capacity for process development and pilot-scale optimization. Biotech firms specify these during technology transfer from research to manufacturing.
- 10 Liters:Mid-scale containers for small-batch clinical manufacturing. Contract manufacturers specify these for early-phase biologics production prior to commercial scale-up.
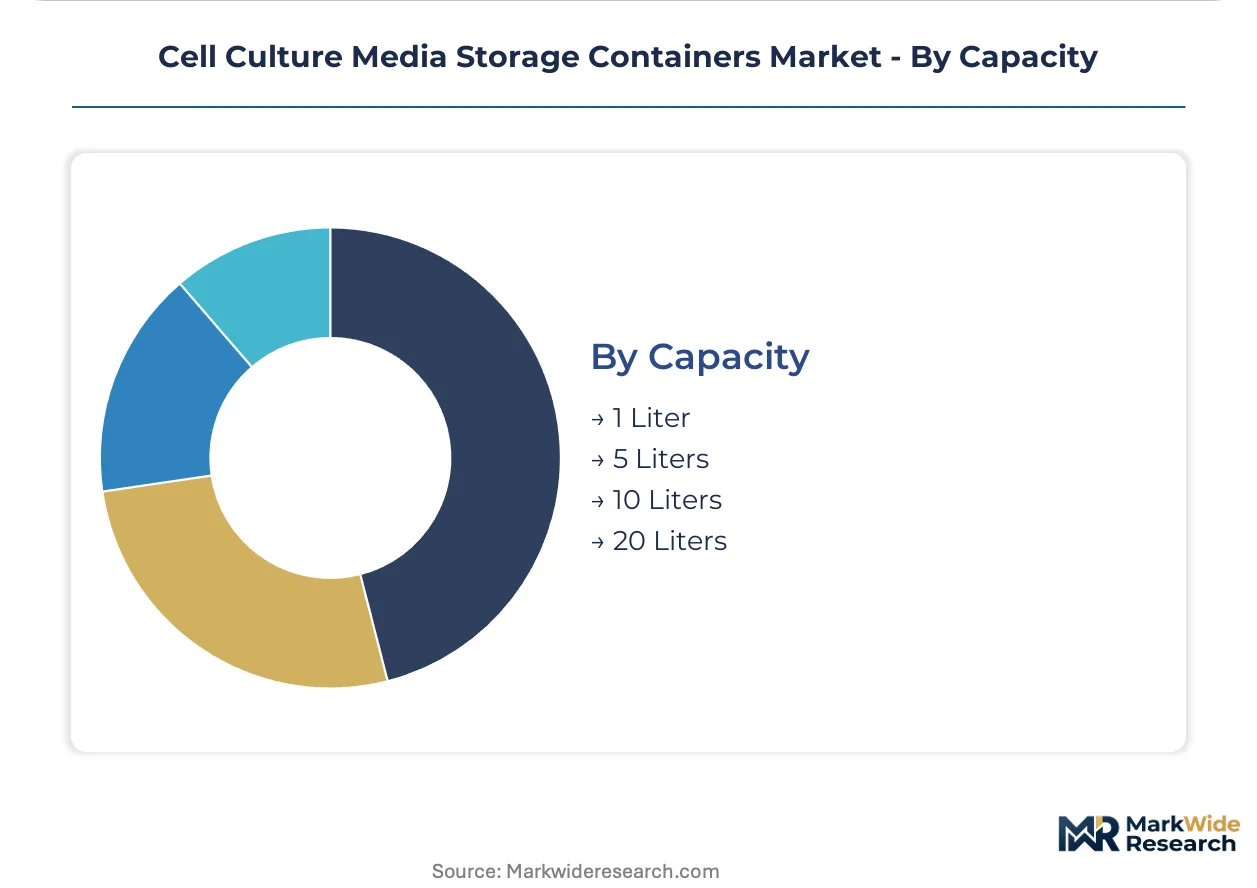
1 Liter formats dominate unit shipments; 20 Liter configurations show the steepest volume climb in commercial bioprocessing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's streamlined biologics approval pathways and PLI scheme incentives in India are attracting contract manufacturing investment, creating parallel demand centers alongside established North American and European production clusters.
United States
FDA container closure integrity standards under biologics license applications drive specification stringency for single-use storage systems. The IRA's domestic manufacturing incentives accelerate reshoring of biologics production capacity. Boston and San Diego manufacturing clusters procure high-capacity bioreactor bags with validated closure systems for cell and gene therapy workflows.
Germany
EMA Annex 1 revision on sterile manufacturing elevates particulate and endotoxin limits for single-use systems in European facilities. REACH restrictions on per- and polyfluoroalkyl substances force reformulation of conventional barrier films. Baden-Württemberg and Bavaria host concentrated bioprocessing equipment manufacturing and pharmaceutical packaging innovation centers.
India
CDSCO streamlined biologics approval pathways reduce regulatory timelines for novel therapy manufacturing. PLI scheme incentives for pharmaceutical manufacturing attract contract development and manufacturing organization investment. Maharashtra and Gujarat emerge as primary hubs for single-use system procurement serving domestic and export biologics production.
China
NMPA good manufacturing practice updates for biologics production reshape supplier qualification requirements for imported storage containers. National dual carbon goals accelerate displacement of stainless-steel infrastructure with single-use alternatives. Yangtze River Delta biopharma clusters specify pre-validated assemblies for monoclonal antibody and vaccine manufacturing.
Switzerland
Swissmedic maintains stringent biocompatibility documentation requirements for materials contacting cell culture media. Bilateral mutual recognition agreements with FDA and EMA position Swiss facilities as qualification benchmarks for global suppliers. Basel and Zurich pharmaceutical manufacturing centers specify ISO 13485-certified container systems with complete extractables profiles.
Cell Culture Media Storage Containers Market Competitive Landscape
Player mix skews toward integrated life sciences conglomerates with diversified bioprocessing portfolios. Tiered competitive structure separates full-platform suppliers from specialized container fabricators and regional distributors. Three archetypes dominate: integrated platform providers controlling distribution across North American hubs, specialized bioreactor bag designers for perfusion workflows, and filtration-compatibility testers reducing contamination risk. Capacity expansion and strategic partnerships constitute the primary competitive moves, with suppliers securing fluoropolymer film supply agreements and CDMO qualification contracts.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions spanning upstream storage through downstream processing. Among German-based specialists, Sartorius AG and Merck KGaA exemplify divergent specialization vectors—one anchored in bioreactor bag portfolios, the other in upstream filtration compatibility. Corning Incorporated represents the materials science archetype, leveraging glass and polymer expertise for container integrity applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Corning Incorporated |
| Merck KGaA |
| Sartorius AG |
| Danaher Corporation |
| Greiner Bio-One International GmbH |
| Saint-Gobain Group |
| VWR International, LLC |
| Cytiva |
| Others |
Value Network & Pricing Analysis
Capacity utilization at multilayer fluoropolymer film producers in Germany and Japan shapes both supply concentration and price floors for bioreactor bag manufacturers. Contract manufacturers in Boston and San Diego clusters absorb premium pricing for validated closure systems while academic buyers in the United States face compressed margins on standard plastic bottles.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-validated assemblies and commodity research-grade containers. The dominant pricing structure runs contract-based long-term offtake agreements with volume-scaled discounts for CDMOs, while spot procurement serves academic laboratories. Price differentiation rests on FDA-grade validation tier and geographic delivery cost to manufacturing clusters. Cost compression in standard plastic bottles is intensifying because REACH-compliant polymer reformulation raises input expenses. Academic institutions exhibit highest price sensitivity; integrated pharmaceutical companies show lowest sensitivity due to qualification timeline costs.
Supply Chain Analysis
Fluoropolymer resin production concentrates among specialized chemical suppliers in Germany, Japan, and the United States, creating single-source vulnerability for multilayer film manufacturers. Bioreactor bag fabricators draw from cyclic olefin polymer feedstocks, bromobutyl elastomer closures, and gamma-irradiation sterilization services. Tariff exposure on imported fluoropolymer films from Japan threatens margin stability for European container assemblers. Distribution runs through manufacturer-direct channels to large CDMOs, with distributor networks serving fragmented academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs deep as cell and gene therapy manufacturing disperses beyond Boston-San Diego clusters into emerging domestic hubs. Perfusion workflow specialization creates defensible niches for suppliers with documented extractables profiles.
For Market Incumbents: Consolidate fluoropolymer film supply agreements with German and Japanese resin producers to lock in input cost stability against REACH-driven reformulation cycles. Add ISO 13485-certified capacity in India to capture CDSCO-qualifying contract manufacturing demand before local suppliers mature. Vertical integration into gamma-irradiation sterilization services defends margin position against third-party capacity constraints.
For New Entrants and Emerging Players: Anchor in 5-liter intermediate capacity containers for biotech firms during technology transfer phases, where qualification burden stays lighter than commercial-scale specifications. Target Maharashtra and Gujarat manufacturing clusters in India with pre-validated assemblies priced below incumbent landed cost from North America. Pursue co-development partnerships with emerging CDMOs seeking captive supply security.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with multi-year qualification contracts at top-ten global CDMOs. Long-term viability favors platform-integrated players with backward control over polymer formulation rather than pure-play container fabricators. Watch for inflection when FDA publishes updated extractables-leachables guidance forcing requalification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Film Supply Agreement | Locks in resin access from German and Japanese chemical suppliers ahead of REACH restrictions. |
| ISO 13485 Certification Investment | Opens procurement pipelines at FDA-regulated pharmaceutical manufacturers and global CDMOs. |
| Perfusion Bag Portfolio Expansion | Captures volume from continuous manufacturing displacement of stainless-steel infrastructure. |
| India Manufacturing Footprint | Positions for CDSCO-qualifying demand under PLI scheme incentives for biologics production. |
| Closed-System Integration Partnership | Enables automated media transfer without cleanroom intervention at cell therapy facilities. |
Research Methodology
Desk research of FDA biologics license application filings, EMA Annex 1 revision documentation, and CDSCO approval pathway records preceded structured interviews with bioprocess engineers, regulatory affairs specialists, CDMO procurement directors, and sterilization validation consultants. Secondary validation drew from ISO certification databases, trade customs records for fluoropolymer resin shipments, and hospital procurement system contracts. Bottom-up demand modeling from end-user specification surveys was cross-checked against top-down supply-side capacity assessments at major film extrusion facilities.
Variance decomposition across product type, closure system grade, end-user category, and capacity tier anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution in validated versus research-grade tiers. Forecast inputs incorporated perfusion platform adoption curves at cell therapy manufacturers and REACH compliance timelines for polymer reformulation.
Decision-makers should treat outputs as directional under assumptions of sustained EMA Annex 1 enforcement and stable fluoropolymer resin supply from established chemical producers; material deviation would warrant model refresh. Specific risk factors include sudden CDSCO regulatory reversals, breakthrough cyclic olefin polymer formulations displacing multilayer films, or consolidation among top-ten CDMOs collapsing supplier qualification pipelines. Practitioners should keep alternative scenarios live as FDA extractables-leachables guidance and EU substance restriction schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Gloves Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Europe Ostomy Care and Accessories Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Soaker Pads Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
GCC Syringes and Needles Market