
 Belgium Pharmaceutical Market | 2026-2036
Belgium Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Pharmaceutical Market Analysis
The EU Green Deal is decoupling pharmaceutical manufacturing from carbon-intensive supply chains across Belgium's chemical-pharma corridor. Janssen Pharmaceutica leverages its Beerse campus to sustain integrated biologics production from active ingredient to finished dose. UCB anchors its Brussels operations in neurology and immunology specialization, while Pfizer competes through mRNA technology leadership at its Puurs manufacturing hub.
Belgium pharmaceutical comprises chemically synthesized or biologically derived medicinal products formulated for disease prevention, diagnosis, or treatment, with active pharmaceutical ingredients typically requiring purity thresholds exceeding 99.5% and stability validation across defined temperature bands. Prescription medications dominate value flows through hospital and pharmacy channels, while biologics capture expanding margin pools as complex manufacturing barriers limit competitive entry. Oncology applications lead therapeutic demand, with injectable delivery modes commanding premium positioning due to cold-chain infrastructure requirements and clinical administration protocols.
FAMHP, the EU Falsified Medicines Directive, and EMA centralized marketing authorization procedures collectively shape Belgium's pharmaceutical compliance architecture, with serialization mandates now mandatory across all prescription product distributions. The EU AI Act introduces emerging governance requirements for algorithmic drug discovery platforms that Belgian developers must integrate into R&D workflows. Stakeholders should monitor how evolving EU pharmaceutical strategy revisions reposition domestic manufacturing incentives against relocation pressures to lower-cost European jurisdictions.
Market Dynamics
Serialization mandates under the EU Falsified Medicines Directive are forcing wholesale reconfiguration of Belgium's distribution infrastructure, with FAMHP enforcement timelines compressing capital deployment cycles for hospital and retail pharmacy networks.
Growth Catalysts
- Oncology biologics procurement:Hospital purchasing consortia in the Brussels-Capital Region are consolidating demand for injectable immunotherapies. Cold-chain infrastructure investments at Antwerp logistics hubs enable temperature-validated distribution networks.
- EU Green Deal manufacturing incentives:Decarbonization subsidies are accelerating facility retrofits across Flanders' chemical-pharma corridor. Process electrification at biologics production sites reduces Scope 2 emissions intensity.
- mRNA platform technology:Lipid nanoparticle formulation capabilities developed during pandemic response are repurposing toward personalized cancer vaccines. Puurs manufacturing infrastructure anchors this technology transition.
Market Restraints
- API import concentration:Active pharmaceutical ingredient sourcing remains concentrated on Asian chemical manufacturers. Geopolitical friction exposes Belgian formulators to supply interruption risk.
- Biologics manufacturing cost structure:Single-use bioreactor consumables and cell culture media represent 35-45% of production costs. Input price volatility compresses margin predictability for complex molecules.
- EMA centralized authorization timelines:Marketing authorization procedures for novel biologics extend 12-18 months. Regulatory friction delays patient access to innovative therapies.
Strategic Opportunities
- Wallonia underpenetration:Pharmaceutical distribution density in Liège and Namur provinces lags Flanders by 40%. Specialty pharmacy networks present whitespace for neurology product access.
- AI Act compliance services:Algorithmic drug discovery platforms require governance integration. Belgian contract research organizations can capture regulatory consulting revenue.
- Hospital-at-home infusion:Subcutaneous formulation development enables outpatient administration. Home care channels reduce inpatient bed utilization pressure.
Industry Challenges
- Serialization technician scarcity:FAMHP-mandated track-and-trace systems require specialized IT-pharmacy hybrid skills. Training pipeline gaps delay compliance readiness.
- Legacy ERP integration:Hospital procurement systems lack native compatibility with European Medicines Verification Organization data standards. Middleware development consumes implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Pharmaceutical Market |
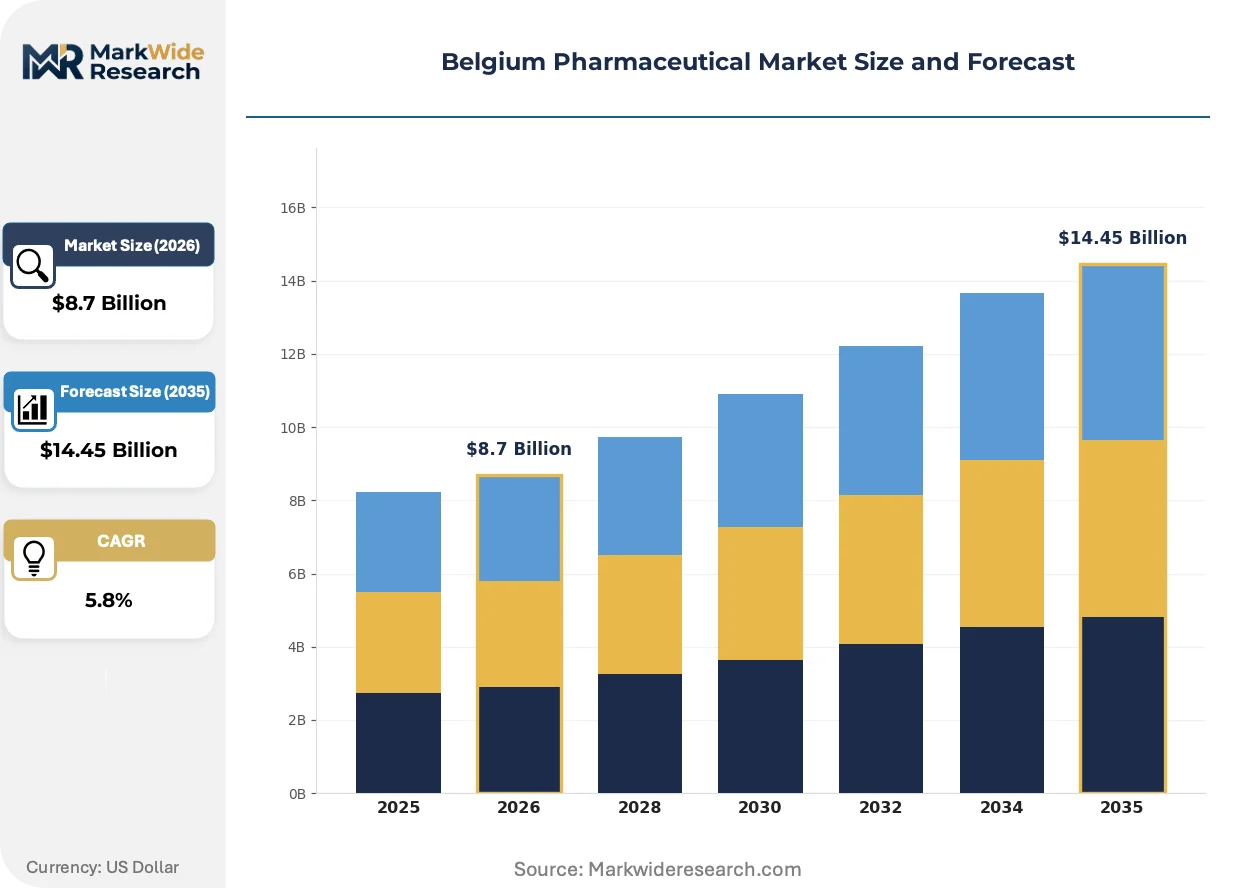
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Drugs, Biologics, Generics Application: Oncology, Cardiovascular, Neurology, Endocrinology Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Pharmacies, Clinics, Home Care |
| Companies Covered | Janssen Pharmaceutica, Glaxosmithkline Biologicals, Pfizer, UCB, Fagron, AstraZeneca, AbbVie, Bayer, Boehringer Ingelheim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Pharmaceutical Market Emerging Trajectories
Digital integration across discovery, manufacturing, and distribution is compressing development timelines while raising compliance complexity. Belgian operations are piloting technologies that unify previously siloed quality and supply chain functions.
Continuous bioprocessing is unifying upstream cell culture with downstream purification in single integrated trains. Janssen's Beerse campus is deploying perfusion bioreactor technology for monoclonal antibody production. This platform reduces facility footprint requirements while enabling real-time quality release testing.
The EU AI Act introduces algorithmic impact assessment requirements for machine-learning drug discovery platforms. Belgian developers must document training data provenance and model validation protocols. Early-stage biotechnology firms are restructuring R&D workflows to embed governance checkpoints before clinical candidate selection.
Hospital procurement consortia are consolidating oncology biologics purchasing through centralized tender mechanisms. Academic medical centers in Leuven and Brussels negotiate multi-year supply agreements directly with manufacturers. This concentration shifts price negotiation leverage toward institutional buyers and away from wholesale distributors.
Belgium Pharmaceutical Market Segmentation
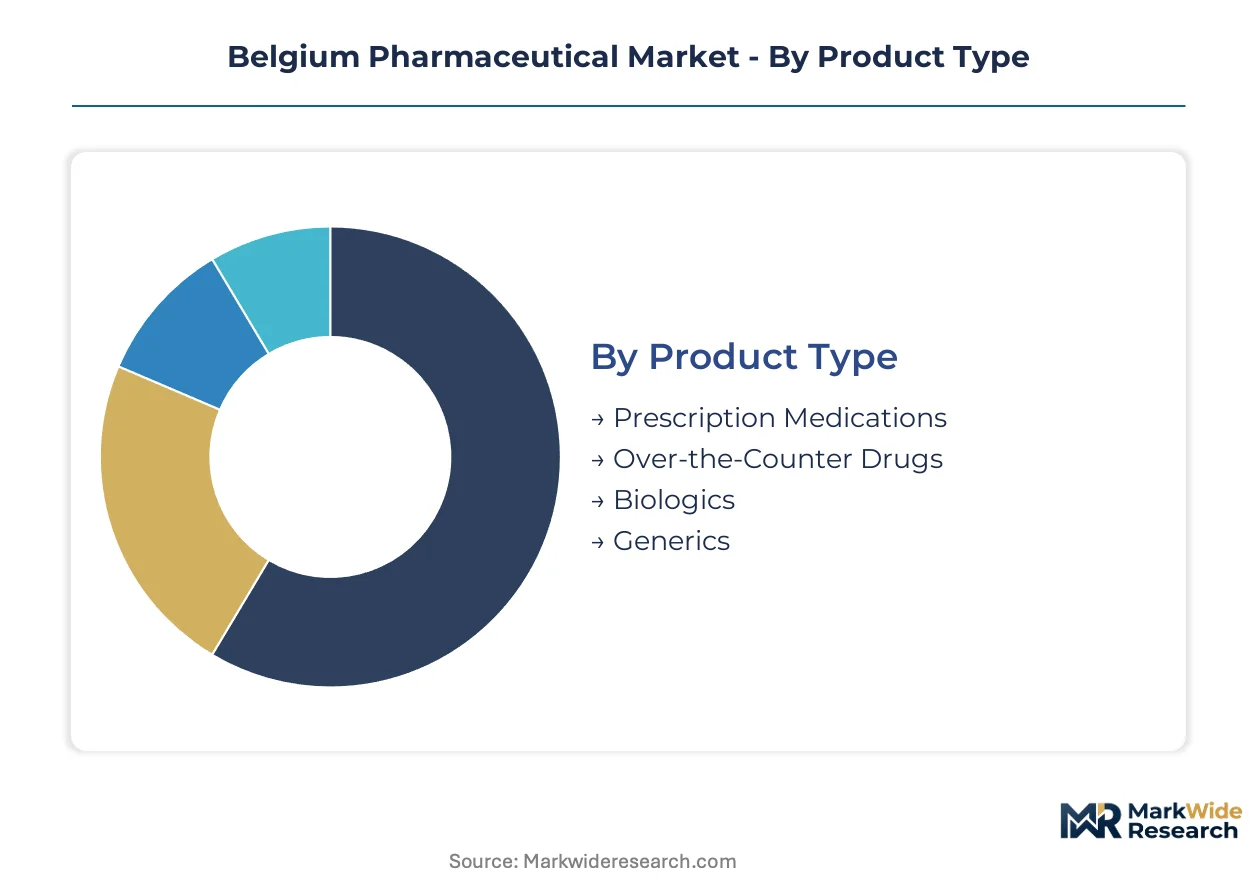
Belgium's pharmaceutical segmentation reveals divergent margin structures across product categories, with biologics commanding premium positioning through manufacturing complexity while generics compete on procurement efficiency. Hospital purchasing consortia and retail pharmacy networks drive distinct demand patterns across each segment dimension.
Product Type:
Biologics concentrate value capture through cold-chain infrastructure requirements and clinical administration protocols, while prescription medications dominate volume flows through institutional channels.
- Prescription Medications:Chemically synthesized medicinal products requiring FAMHP marketing authorization and EMA centralized procedures where applicable. Hospital procurement consortia in Brussels-Capital and Flanders regions consolidate demand for chronic disease therapies, with serialization mandates under the EU Falsified Medicines Directive adding compliance costs to distribution.
- Biologics:Large-molecule therapeutics produced through cell culture or recombinant DNA technology, typically requiring purity thresholds exceeding 99.5% and stability validation across defined temperature bands. Janssen's Beerse campus and Pfizer's Puurs hub anchor domestic production capacity for monoclonal antibodies and mRNA platforms, with oncology applications leading therapeutic demand concentration.
- Over-the-Counter Drugs:Self-medication products distributed through retail pharmacy networks without prescription requirements.
- Generics:Bioequivalent alternatives competing on price through tender mechanisms and reference pricing systems.
Today's leader: Biologics. Tomorrow's challenger: Prescription Medications.
Application:
Oncology and neurology applications concentrate R&D investment and manufacturing specialization, with UCB anchoring Brussels operations in immunology and central nervous system therapies.
- Oncology:Cancer therapeutics spanning cytotoxic agents, targeted small molecules, and immuno-oncology biologics. Academic medical centers in Leuven and Brussels negotiate multi-year supply agreements directly with manufacturers, shifting price leverage toward institutional buyers.
- Neurology:Therapeutics for epilepsy, Parkinson's disease, and multiple sclerosis, with injectable delivery modes commanding premium positioning. UCB's Brussels operations specialize in this segment, while Wallonia's underpenetrated Liège and Namur provinces present whitespace for specialty pharmacy network expansion.
- Cardiovascular:Antihypertensives, anticoagulants, and lipid-lowering agents distributed through chronic care pathways.
- Endocrinology:Diabetes and hormone replacement therapies with established biosimilar competition.
Oncology maintains the steepest expansion trajectory through immunotherapy pipeline maturation.
Delivery Mode:
Injectable formats concentrate margin pools through cold-chain infrastructure requirements, while oral formulations dominate prescription volume.
- Injectable:Parenteral administration requiring sterile manufacturing and temperature-validated distribution networks. Antwerp logistics hubs enable cold-chain infrastructure for biologics, with hospital-at-home infusion programs emerging as a channel innovation to reduce inpatient bed utilization.
- Oral:Tablet and capsule formulations dominating chronic disease management and generic substitution programs.
- Transdermal:Patch-based delivery for pain management and hormone therapies with controlled release profiles.
- Inhalation:Pulmonary delivery for respiratory conditions with device-dependent formulation complexity.
Hospital procurement patterns favor injectable biologics; retail pharmacy growth tilts toward oral chronic therapies.
End User:
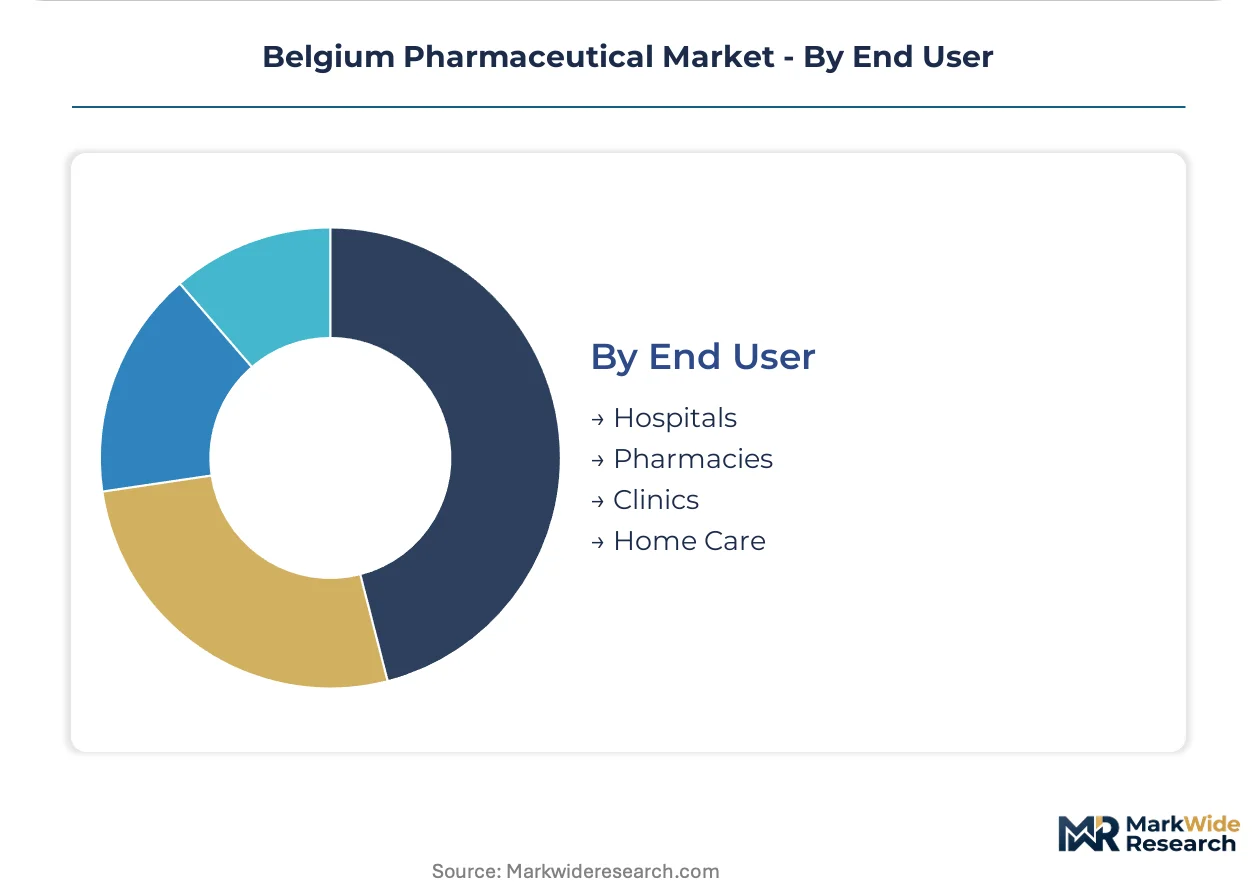
Hospital purchasing consortia consolidate oncology biologics demand, while home care channels emerge for subcutaneous formulation administration.
- Hospitals:Academic medical centers and general hospitals procuring through centralized tender mechanisms. FAMHP serialization mandates force wholesale reconfiguration of distribution infrastructure, with IT-pharmacy hybrid skills scarcity delaying compliance readiness for track-and-trace systems.
- Pharmacies:Community and hospital outpatient dispensaries handling prescription fulfillment and generic substitution.
- Clinics:Specialist outpatient facilities for infusion and injection administration.
- Home Care:Emerging channel for subcutaneous biologics and self-administered therapies.
Hospitals command current purchasing leverage; home care infrastructure builds for tomorrow's administration shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's pharmaceutical workforce concentrates in Flanders' chemical-pharma corridor and the Brussels-Capital Region, anchoring specialized manufacturing and R&D functions that differentiate sub-regional competitive positioning.
Flanders
Antwerp logistics hubs and the Port of Antwerp-Bruges anchor cold-chain distribution infrastructure for temperature-sensitive biologics. The EU Green Deal decarbonization subsidies accelerate facility retrofits across the chemical-pharma corridor. Janssen's Beerse campus sustains integrated biologics production from active ingredient to finished dose.
Brussels-Capital Region
Hospital purchasing consortia consolidate demand for injectable immunotherapies and neurology biologics. FAMHP serialization mandates under the EU Falsified Medicines Directive force wholesale reconfiguration of distribution infrastructure. UCB anchors operations in neurology and immunology specialization.
Wallonia
Pharmaceutical distribution density in Liège and Namur provinces lags Flanders by 40%, presenting whitespace for specialty pharmacy network expansion. Regional development incentives target biopharma manufacturing investments. Academic medical centers negotiate multi-year supply agreements directly with manufacturers.
Belgium Pharmaceutical Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across Belgium's pharmaceutical value chain. The market structure consolidates around integrated biologics manufacturers with captive production infrastructure and specialized contract research organizations serving algorithmic drug discovery platforms. Three archetypes dominate: vertically integrated multinational pharma with domestic manufacturing campuses, mid-cap specialists in neurology and immunology, and hospital procurement consortia consolidating purchasing leverage. Competitive moves center on facility electrification retrofits and strategic partnerships for lipid nanoparticle formulation capabilities.
Among integrated multinational producers, Janssen Pharmaceutica and Pfizer occupy positions anchored by domestic manufacturing campuses, while UCB exemplifies the mid-cap specialist archetype focused on therapeutic area concentration. These entities represent distinct strategic postures within Belgium's pharmaceutical competitive structure.
| Leading Market Players |
|---|
| Janssen Pharmaceutica |
| Glaxosmithkline Biologicals |
| Pfizer |
| UCB |
| Fagron |
| AstraZeneca |
| AbbVie |
| Bayer |
| Boehringer Ingelheim |
| Others |
Supply Flow & Price Mechanics
Hospital purchasing consortia in Brussels-Capital and Flanders are consolidating oncology biologics procurement through multi-year tender mechanisms, forcing manufacturers to absorb cold-chain infrastructure costs and compress service bundles into unit pricing. This demand concentration shifts negotiation leverage toward institutional buyers and squeezes margin pools for wholesale distributors caught between fixed logistics investments and compressed fee structures.
Pricing Analysis
Bundled service contracts dominate biologics procurement, with manufacturers packaging cold-chain logistics, clinical training, and patient support programs into per-dose pricing. Price differentiation hinges on EMA centralized authorization tier and volume scale commitments from academic medical centers. Pricing pressure stems from reference pricing systems for chronic disease therapies, squeezing originator margins. Generics compete on procurement efficiency, while biologics command premium positioning through manufacturing complexity and administration protocol requirements.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive returns and expired biologics require specialized disposal partnerships, adding cost layers to distribution economics. API sourcing concentrates on India and China, with Belgian formulators dependent on Asian chemical manufacturers for active ingredients. Cell culture media and single-use bioreactor consumables represent critical input dependencies. Tariff exposure on Chinese chemical imports threatens margin stability. Distribution runs through Antwerp logistics hubs and hospital procurement consortia, with FAMHP-mandated serialization forcing IT infrastructure upgrades across retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Belgium's pharmaceutical market rests on process electrification retrofits reducing Scope 2 emissions intensity and biologics premium-tier growth displacing commoditized small-molecule volumes.
For Market Incumbents: Extend cold-chain infrastructure control through captive logistics investments at Antwerp hubs, insulating against third-party fee inflation. Deepen backward integration into lipid nanoparticle formulation capabilities to capture mRNA platform value. Consolidate hospital procurement relationships through outcome-based contracting models that lock in multi-year oncology biologics supply agreements before tender mechanisms mature. For New Entrants and Emerging Players: Enter via Wallonia's underpenetrated specialty pharmacy networks in Liège and Namur provinces, where distribution density lags Flanders by 40%. Target neurology biologics with subcutaneous formulation development enabling hospital-at-home administration. Pursue AI Act compliance services for algorithmic drug discovery platforms as a regulatory consulting wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing therapeutic area concentration in immunology or central nervous system disorders, anchored by Brussels or Flanders manufacturing infrastructure. Long-term viability hinges on EU Green Deal subsidy capture and EMA centralized authorization track records. Monitor FAMHP serialization enforcement timelines and hospital procurement consortia formation rates as inflection indicators for distribution leverage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Deployment | Janssen's Beerse campus perfusion technology reduces facility footprint while enabling real-time quality release testing. |
| EU Green Deal Facility Retrofit | Decarbonization subsidies accelerate process electrification across Flanders' chemical-pharma corridor, lowering Scope 2 intensity. |
| Lipid Nanoparticle Formulation Scale-Up | Pfizer's Puurs manufacturing hub repurposes pandemic-era mRNA capabilities toward personalized cancer vaccines. |
| Hospital-at-Home Infusion Program | Subcutaneous biologics development reduces inpatient bed utilization pressure for Brussels-Capital academic medical centers. |
| AI Act Governance Integration | Belgian contract research organizations capture regulatory consulting revenue from algorithmic drug discovery platform developers. |
Methodological Framework
Multiple input streams — executive interviews with drug development and regulatory affairs leads, hospital procurement manager surveys, and payer access specialist consultations — were reconciled against EMA centralized marketing authorization databases, FAMHP enforcement bulletins, and ClinicalTrials.gov pipeline tracking. Secondary validation drew from EU pharmaceutical strategy documents, hospital procurement consortium tender records, and customs trade data on API imports. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from formulary directors and GPO contracts managers to construct analytical frameworks across the analysis window. Segmentation dimensions modeled include product type, therapeutic application, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from spline-interpolation of annual growth rates adjusted for EMA authorization timeline delays and EU Green Deal subsidy phase-in schedules.
Inputs from EMA submissions and hospital procurement databases were available through the study window; gaps in real-time biologics manufacturing cost data introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions on serialization compliance timelines and cold-chain infrastructure investment cycles. Practitioners should monitor FAMHP enforcement actions, hospital purchasing consortia consolidation rates, and API import tariff developments for early signals of pricing power redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market