
 Parathyroid Hormone Market | 2026-2036
Parathyroid Hormone Market Size, Share, and Industry Trends Forecast 2026-2036
Parathyroid Hormone Market Outlook
Hospital procurement of anabolic osteoporosis therapies is tilting toward integrated delivery networks with centralized pharmacy control. Amgen Inc. leverages its established biologics infrastructure to sustain formulary positioning across major health systems. Eli Lilly and Company anchors its presence through endocrinology specialist relationships, while Radius Health, Inc. competes on differentiated injection-frequency profiles for patient adherence.
Parathyroid hormone comprises a polypeptide chain of 84 amino acids secreted by the parathyroid glands, with recombinant teriparatide and abaloparatide representing the primary synthetic analogs manufactured through Escherichia coli-based fermentation. These agents stimulate osteoblast activity to increase bone mineral density and reduce fracture risk in patients with severe osteoporosis. Injectable delivery modes dominate current revenue due to established clinical efficacy data and payer familiarity, though transdermal formulations represent the fastest-growing development category as companies pursue patient convenience and reduced injection burden. Osteoporosis treatment applications command the largest margin pool, while hypoparathyroidism management segments attract premium pricing for orphan-indication status.
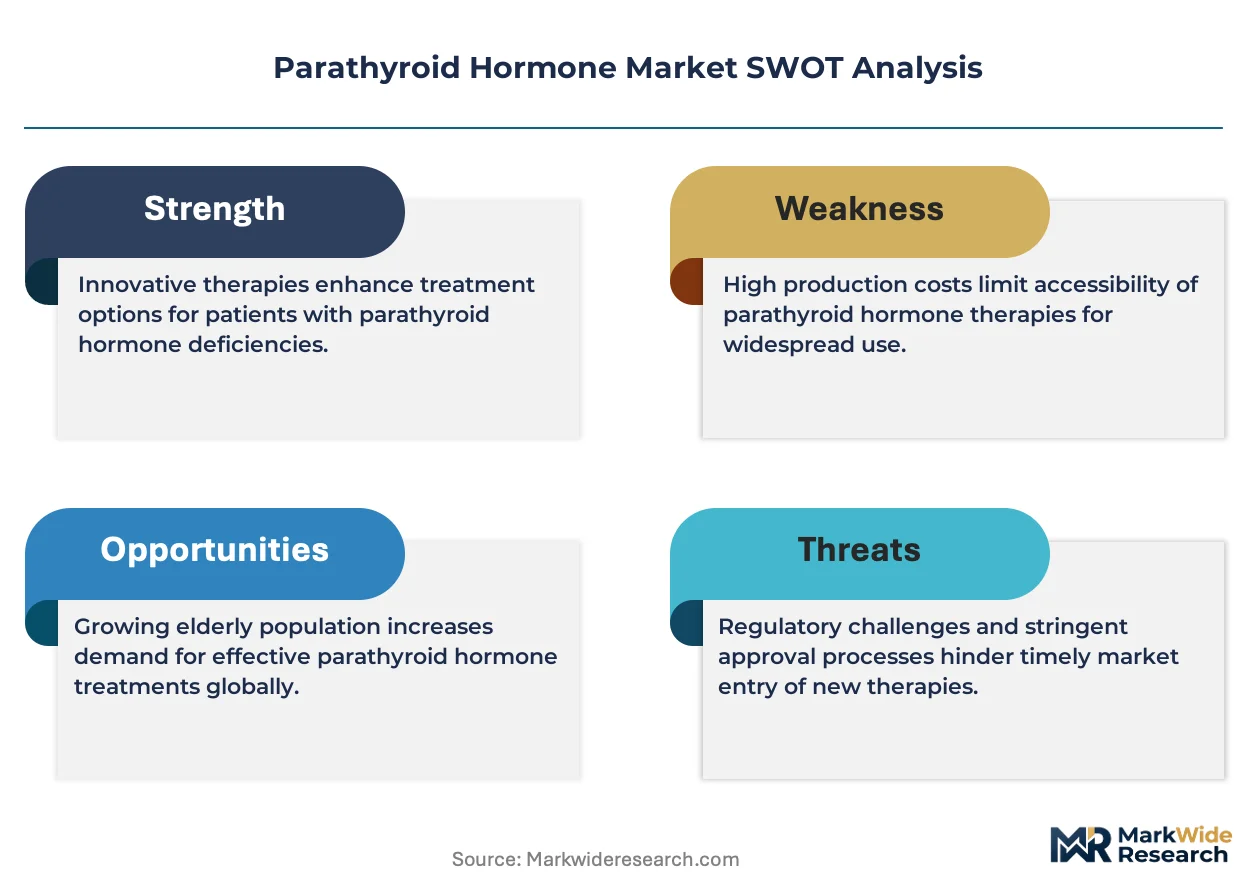
The FDA maintains stringent potency and immunogenicity standards for recombinant PTH products through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use enforces comparable biologics quality benchmarks across European markets. These frameworks elevate manufacturing compliance costs but simultaneously protect incumbent positions against biosimilar erosion. Stakeholders must monitor evolving pharmacovigilance requirements for long-term osteosarcoma risk surveillance as treatment durations extend in real-world practice.
Market Dynamics
Hospital networks are consolidating pharmacy procurement through integrated delivery networks, forcing manufacturers to negotiate centralized contracts rather than individual facility agreements. This structural concentration is compressing margin pools and elevating the importance of health system relationships over traditional physician detailing.
Growth Catalysts
- Expanded Medicare Part D Coverage:The Inflation Reduction Act's out-of-pocket cap provisions for Medicare beneficiaries reduce cost barriers for anabolic osteoporosis therapies in the United States.
- Recombinant Manufacturing Scale-Up:Advances in Escherichia coli fermentation yield improvements are lowering production costs for teriparatide analogs while maintaining bioequivalence standards.
- Japan's Super-Aged Society:METI's healthcare infrastructure investments for patients over 75 are expanding reimbursement pathways for fracture-prevention biologics in the world's oldest population.
Market Restraints
- Black Box Warning Limitations:The FDA's mandatory osteosarcoma risk labeling caps treatment duration at 24 months, constraining lifetime revenue per patient.
- Active Pharmaceutical Ingredient Concentration:Recombinant PTH production depends on a limited number of specialized biologics contract manufacturers in Switzerland and Singapore.
- Oral Bisphosphonate Substitution:Generic alendronate and risedronate remain first-line therapy for payers, creating pricing ceilings for anabolic agents.
Strategic Opportunities
- Germany's DMP Osteoporosis Program:Disease management program incentives reward physicians for bone density testing compliance, expanding addressable patient pools.
- Transdermal Patch Development:Microneedle array technology convergence with sustained-release formulations promises weekly rather than daily administration.
- Hypoparathyroidism Orphan Pricing:Natpara replacement therapy segments command premium reimbursement due to small population size and severity of untreated disease.
Industry Challenges
- Biologics Skill Shortage:Recombinant protein purification and potency assay development require specialized talent that remains scarce outside Boston and Basel clusters.
- Immunogenicity Surveillance Infrastructure:Extended pharmacovigilance for anti-drug antibody detection demands investment in specialized bioanalytical laboratories.
- Cold Chain Integration Complexity:Temperature-sensitive peptide stability requirements complicate distribution partnerships with non-specialized pharmacy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parathyroid Hormone Market |
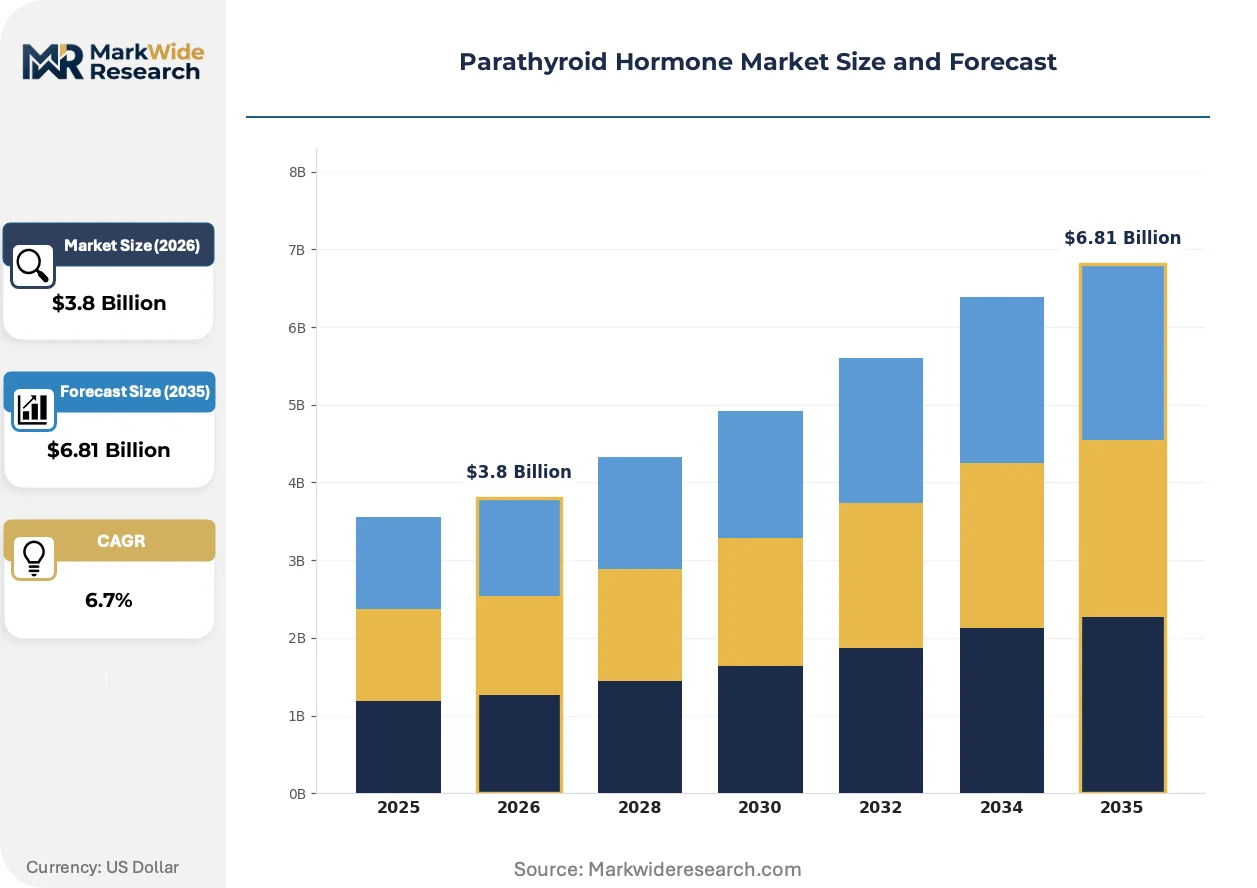
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Teriparatide, Abaloparatide, Recombinant PTH, Others End User: Hospitals, Clinics, Home Care, Research Laboratories Delivery Mode: Injectable, Oral, Transdermal, Nasal Application: Osteoporosis Treatment, Hypoparathyroidism Management, Bone Density Improvement, Others |
| Companies Covered | Amgen Inc., Eli Lilly and Company, Merck & Co., Inc., Novartis AG, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Ascendis Pharma, Radius Health, Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parathyroid Hormone Market Strategic Shifts
Parathyroid hormone delivery technology is fragmenting across administration routes as patient adherence data reshapes development priorities. Manufacturers are racing to reduce injection burden while preserving the anabolic bone-building efficacy that defines clinical value.
Transdermal microneedle systems are hybridizing peptide stabilization chemistry with patient-administered wearable devices. Endocrinology practices in academic medical centers are piloting these systems for treatment-intolerant patients. The technology is hybridizing convenience expectations with clinical outcomes, compressing differentiation space for conventional syringe-based products.
The EMA's revised biosimilar guidance for biotechnology-derived medicinal products is tightening immunogenicity comparability requirements. European manufacturers must now demonstrate equivalent anti-drug antibody profiles across multiple batches. Subcutaneous formulations face the steepest compliance costs as the guidance elevates analytical characterization burdens.
Integrated delivery networks are unbundling physician-administered injection services from drug acquisition. Hospital systems now separate specialty pharmacy dispensing from endocrinology clinic revenues. This restructuring is most visible in United States Medicare Advantage populations where risk-bearing entities capture drug margin directly.
Parathyroid Hormone Market Segmentation
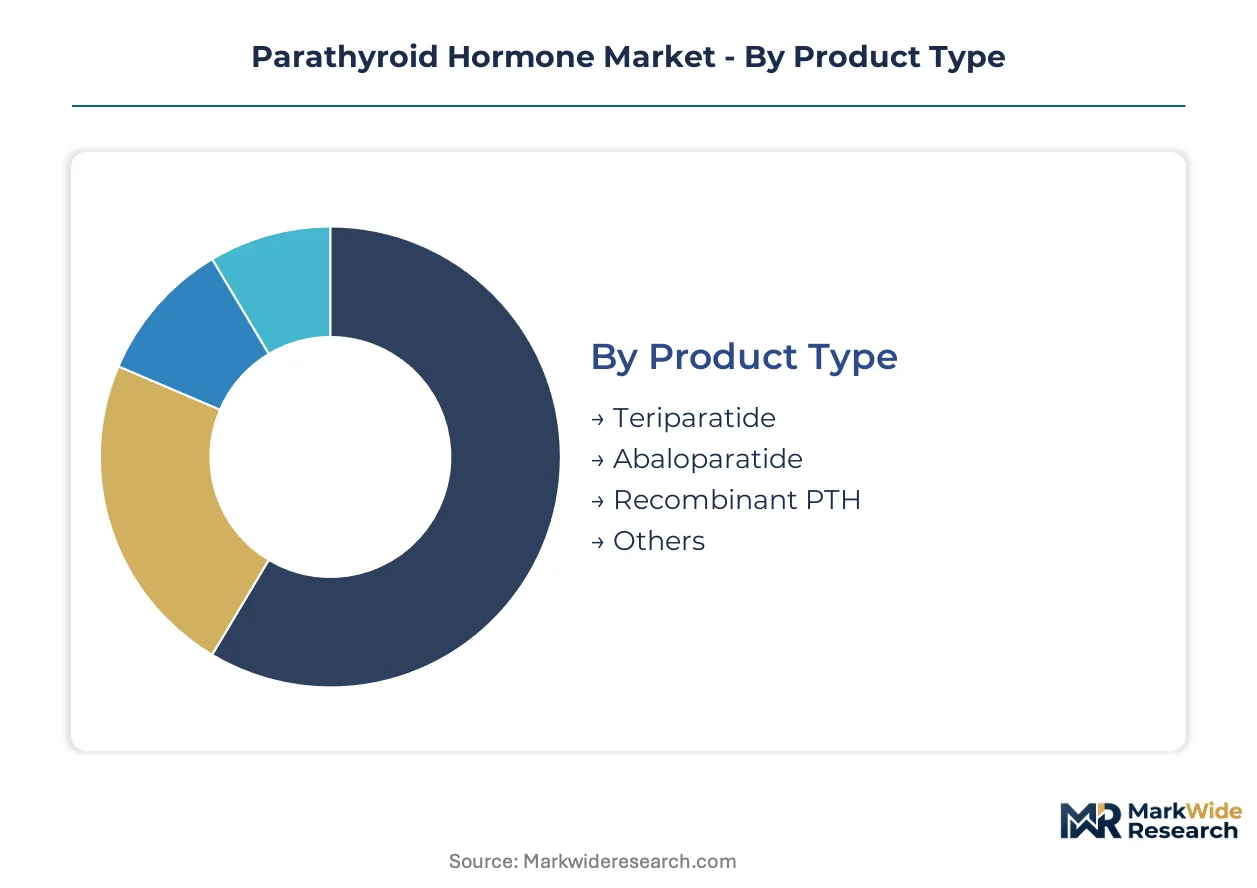
Parathyroid hormone market segmentation reveals how clinical utility, reimbursement pathways, and patient adherence requirements fragment commercial opportunity. Each dimension carries distinct margin profiles and competitive entry barriers that shape portfolio prioritization decisions.
Product Type:
Cost tier stratification separates established recombinant analogs from next-generation candidates, with manufacturing complexity and patent status driving price positioning.
- Teriparatide:The 34-amino acid N-terminal fragment of human PTH, manufactured through E. coli fermentation with established bioequivalence standards. Hospital networks in the United States concentrate procurement through centralized specialty pharmacy contracts, constrained by the FDA's 24-month treatment duration cap.
- Abaloparatide:A 34-amino acid analog with modified PTHrP sequence demonstrating enhanced bone formation selectivity. Endocrinology specialists in Germany's DMP Osteoporosis Program drive adoption for patients with severe vertebral fracture risk.
- Recombinant PTH:Full-length 84-amino acid synthetic hormone for hypoparathyroidism replacement therapy commanding orphan drug pricing premiums.
- Others:Investigational long-acting formulations and biosimilar candidates in early development stages.
Teriparatide commands the established base. The steepest expansion runs through abaloparatide.
End User:
Customer type determines channel economics, with institutional purchasers leveraging scale against fragmented outpatient settings.
- Hospitals:Integrated delivery networks consolidate procurement through centralized pharmacy and therapeutics committees, compressing margin pools while demanding real-world evidence packages.
- Clinics:Independent endocrinology practices in Japan's super-aged society drive patient identification through bone density screening protocols.
- Home Care:Self-administration models expanding with patient education investments and remote monitoring integration.
- Research Laboratories:Academic medical centers conduct pharmacovigilance studies for long-term osteosarcoma surveillance.
Hospitals anchor volume concentration. Home care claims the most rapid adoption trajectory.
Delivery Mode:
Maturity gradients separate decades-old injection platforms from emerging convenience-focused technologies.
- Injectable:Subcutaneous daily injections dominate current revenue due to established clinical efficacy data and payer familiarity with prior authorization pathways.
- Oral:Peptide formulation challenges including gastric degradation and bioavailability limitations constrain development progress.
- Transdermal:Microneedle array technology converging with sustained-release chemistry promises weekly administration and reduced injection burden for adherence-challenged patients.
- Nasal:Mucosal absorption formulations in early clinical testing for rapid systemic delivery.
Injectable modalities retain the revenue foundation. Transdermal systems are climbing the fastest.
Application:
Margin concentration varies sharply between high-volume osteoporosis treatment and premium-priced orphan indications.
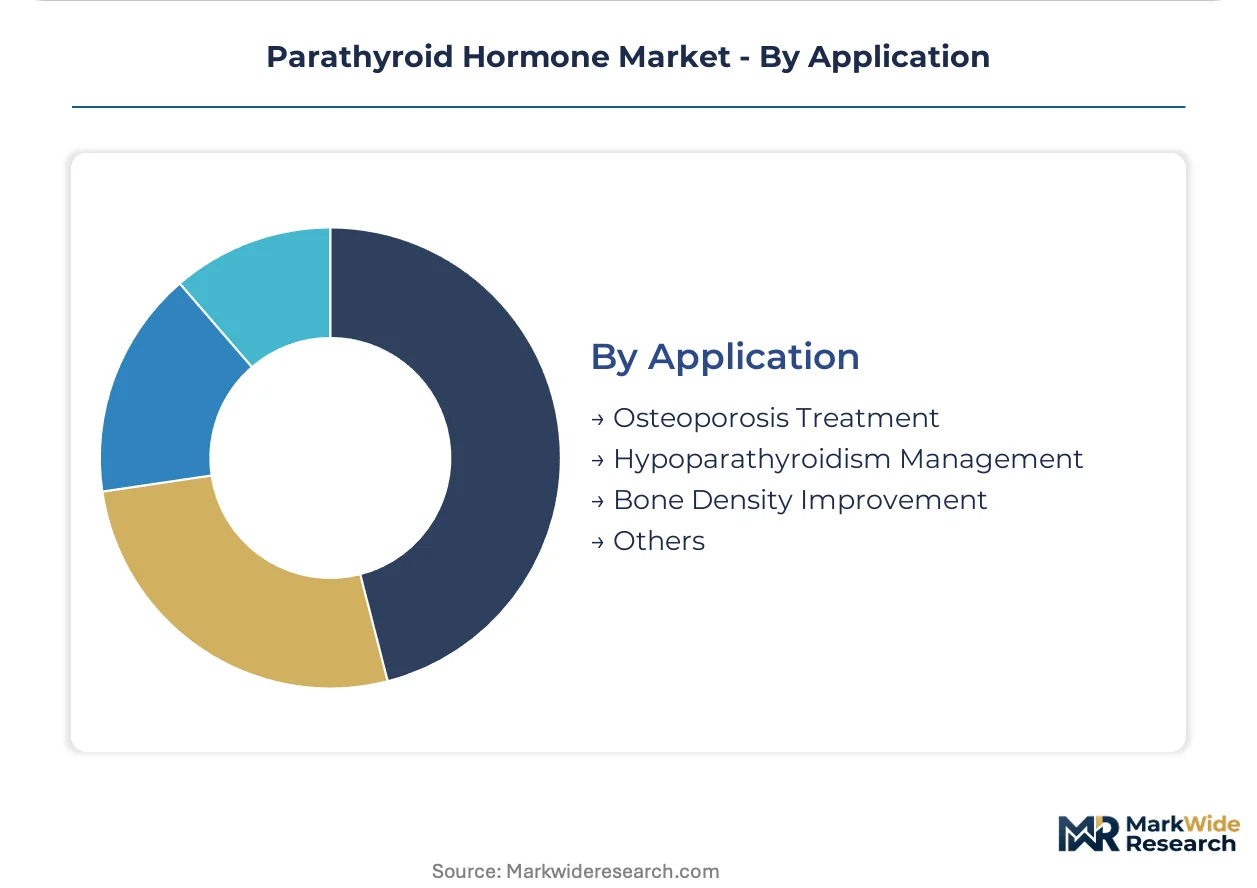
- Osteoporosis Treatment:Postmenopausal women with severe bone loss represent the largest addressable population, with Medicare Part D coverage expansion reducing out-of-pocket barriers in the United States.
- Hypoparathyroidism Management:Small population size and severity of untreated disease support premium reimbursement for replacement therapy requiring lifelong administration.
- Bone Density Improvement:Secondary prevention applications in glucocorticoid-induced osteoporosis expanding through rheumatology specialist adoption.
- Others:Investigational uses in fracture healing acceleration and skeletal dysplasias.
Osteoporosis treatment holds volume leadership. Hypoparathyroidism management delivers the highest per-patient economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Basel's tri-national logistics corridor underwrites Switzerland's role as the primary active pharmaceutical ingredient transit hub for recombinant peptide manufacturing. Cold-chain infrastructure connecting Basel to Singapore and Boston anchors distribution for temperature-sensitive biologics.
United States
Medicare Part D out-of-pocket caps from the Inflation Reduction Act reduce cost barriers for anabolic osteoporosis therapies. The FDA's Center for Drug Evaluation and Research maintains stringent potency standards for recombinant PTH products. The Greater Boston biotech cluster concentrates specialized talent for recombinant protein purification and potency assay development.
Germany
The Disease Management Program (DMP) Osteoporosis incentivizes physicians for bone density testing compliance, expanding addressable patient pools. The EMA's Committee for Medicinal Products for Human Use enforces biologics quality benchmarks that elevate manufacturing compliance costs. The Rhine-Main metropolitan region hosts centralized pharmacy procurement operations for integrated delivery networks.
Japan
METI's healthcare infrastructure investments for patients over 75 expand reimbursement pathways for fracture-prevention biologics. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees pharmacovigilance requirements for long-term osteosarcoma risk surveillance. The Kanto region surrounding Tokyo concentrates endocrinology specialist practices driving patient identification through screening protocols.
Switzerland
Specialized biologics contract manufacturers in Basel and Zurich supply recombinant PTH active pharmaceutical ingredients to global markets. Swissmedic enforces manufacturing standards that protect incumbent positions against biosimilar erosion. The Basel biopharma corridor integrates fermentation capacity with specialized cold-chain distribution to Singapore and the United States.
Singapore
Biologics manufacturing investments from global pharmaceutical companies establish secondary fermentation capacity for peptide hormones. The Health Sciences Authority aligns with FDA and EMA standards for biologics registration. The Tuas biomedical park concentrates contract manufacturing organizations serving Asia-Pacific markets with temperature-controlled peptide stability infrastructure.
Parathyroid Hormone Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in recombinant manufacturing and peptide synthesis. The market structure consolidates around established biologics infrastructure holders with centralized health system contracts. Three archetypes dominate: fermentation-scale incumbents with E. coli platform expertise, endocrinology-focused specialty pharmaceutical companies, and emerging transdermal delivery technology developers. Competitive moves concentrate on health system relationship deepening and microneedle array technology licensing.
Within the fermentation-scale tier, Amgen Inc. and Eli Lilly and Company anchor established positions through biologics infrastructure and specialist channel relationships. Radius Health, Inc. occupies a differentiated position on injection-frequency profiles. These three exemplify how manufacturing scale, physician access, and delivery innovation respectively define competitive vectors in anabolic bone therapy markets.
| Leading Market Players |
|---|
| Amgen Inc. |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Novartis AG |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Ascendis Pharma |
| Radius Health, Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Swiss and Singaporean contract manufacturers for recombinant PTH active pharmaceutical ingredients compresses pricing flexibility at the premium tier while forcing hospital networks toward centralized procurement contracts. This concentration dynamic simultaneously elevates orphan-disease pricing premiums for hypoparathyroidism therapies and squeezes margins on osteoporosis treatment volumes through formulary tiering.
Pricing Analysis
Volume-discount tiering separates hospital integrated delivery networks commanding centralized formulary placement from independent clinic purchasers facing higher per-unit acquisition costs. Price differentiation rests on manufacturing scale, cold-chain certification grade, and injection-frequency convenience profiles. Cost compression in the standard tier intensifies as generic oral bisphosphophonate substitution pressures payer reimbursement ceilings. Medicare Part D beneficiaries show lowest price sensitivity due to out-of-pocket caps, while cash-pay clinic segments face acute budget constraints.
Supply Chain Analysis
Upstream fermentation feedstock supply draws from specialized biologics contract manufacturers concentrated in Switzerland, Singapore, and the Greater Boston corridor. E. coli strain banks, peptide purification resins, and single-use bioreactor components constitute critical input dependencies. Single-source vulnerability at the active pharmaceutical ingredient stage exposes finished dose manufacturers to regulatory inspection delays. Distribution runs through temperature-controlled logistics partnerships linking Basel fermentation sites to hospital specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across delivery mode innovation as patient adherence requirements splinter the addressable market into injection-tolerant, injection-averse, and technology-accepting segments. This demand-side shift creates white-space niches for differentiated administration technologies.
For Market Incumbents: Pre-empt transdermic delivery licensing by securing exclusive microneedle array partnerships before regulatory guidance solidifies. Defend hospital formulary positioning through backward integration into E. coli fermentation capacity in Basel or Singapore. Counter biosimilar erosion by investing in real-world evidence generation for osteosarcoma surveillance databases that reinforce brand trust with institutional purchasers. For New Entrants and Emerging Players: Geographic underpenetration in Japan's super-aged society beyond the Kanto corridor offers the most penetrable expansion target for home care delivery models. Target Germany's DMP Osteoporosis Program incentive structures for physician-directed patient identification. Pursue licensing partnerships with established biologics contract manufacturers rather than greenfield fermentation investment to accelerate market entry. For Investors and Strategic Acquirers: FDA transdermal biologics guidance reshapes the acquisition landscape by elevating immunogenicity comparability requirements that favor platform-integrated developers over component specialists. Long-term viability favors targets with captive E. coli manufacturing and validated cold-chain partnerships. Watch for EMA revised biosimilar guidance enforcement as the signal indicating accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Patch Development | Microneedle array convergence with sustained-release chemistry enables weekly administration for adherence-challenged osteoporosis patients. |
| Manufacturing Scale-Up | E. coli fermentation yield improvements lower production costs while maintaining FDA bioequivalence standards for teriparatide analogs. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement through centralized pharmacy and therapeutics committees. |
| Regulatory Approval Pathway | FDA Center for Drug Evaluation and Research potency standards protect incumbent positions against biosimilar market entry. |
| Reimbursement Strategy | Medicare Part D out-of-pocket caps from the Inflation Reduction Act reduce cost barriers for anabolic osteoporosis therapies. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimation.
Forecast inputs considered treatment line progression, dosage form preferences, administration route adoption curves, and regional regulatory cluster variations across the projection horizon. CAGRs derived from segment-level growth rate blending with macroeconomic healthcare expenditure trajectories. Reimbursement pathway expansion and manufacturing capacity buildout schedules served as key industry-specific demand and supply-side inputs.
Practitioners should monitor FDA pharmacovigilance guidance evolution and EMA biosimilar comparability requirement enforcement for early signals necessitating forecast revision. Cross-checking against CMS Medicare Part D expenditure benchmarks and hospital 340B program utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Isotretinoin Drugs Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Global Anti-Suicide Drugs Market