
 Triamcinolone Ointment Chlorofluorocarbons Market | 2026-2036
Triamcinolone Ointment Chlorofluorocarbons Market Size, Share, and Industry Trends Forecast 2026-2036
Triamcinolone Ointment Chlorofluorocarbons Market Analysis
The EPA's AIM Act phasedown of hydrofluorocarbon propellants is shifting demand toward alternative aerosol formulations in topical corticosteroid delivery. Bristol Myers Squibb Company leverages its established dermatology portfolio to sustain market presence amid propellant transition pressures. Sun Pharmaceutical Industries Limited anchors its competitive stance through manufacturing scale across multiple dosage forms. Lupin Limited differentiates via specialized topical formulation capabilities that address evolving propellant compliance requirements.
Triamcinolone ointment chlorofluorocarbons denotes topical corticosteroid preparations incorporating triamcinolone acetonide in CFC-based aerosol propellant systems, historically formulated at concentrations ranging from 0.025% to 0.5% for anti-inflammatory and immunosuppressive dermatological application. The aerosol segment retains structural significance despite propellant phaseout mandates, while the cream formulation category occupies expanding shelf space in hospital and retail pharmacy channels. Dermatology applications dominate prescription volume, with allergy treatment representing a secondary but growing clinical indication where topical corticosteroid protocols apply.
The EPA oversees propellant transition timelines under Clean Air Act authority, while the FDA maintains jurisdiction over drug formulation safety and bioequivalence standards for reformulated products. These overlapping regulatory frameworks compel manufacturers to synchronize chemistry modifications with abbreviated new drug application pathways. Stakeholders must monitor propellant substitution timelines against clinical trial requirements for therapeutic equivalence certification.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon propellants under the AIM Act is forcing topical corticosteroid manufacturers toward alternative aerosol delivery systems while maintaining therapeutic equivalence standards.
Growth Catalysts
- Dermatology clinic expansion:Specialized dermatology practices in the United States are expanding prescription volumes for topical anti-inflammatory treatments, creating sustained demand pull for reformulated triamcinolone products.
- REACH compliance timelines:European chemical registration requirements are accelerating investment in propellant substitution R&D, positioning early reformulators for competitive advantage as F-Gas restrictions tighten.
- Compressed gas technology:Nitrous oxide and carbon dioxide propellant systems are achieving commercial scale, enabling manufacturers to bypass hydrofluorocarbon dependency while preserving metered-dose precision.
Market Restraints
- API supply concentration:Triamcinolone acetonide active pharmaceutical ingredient production clusters in Indian and Chinese manufacturing zones, exposing formulators to geopolitical and logistics disruption risks.
- Bioequivalence trial costs:FDA abbreviated new drug application pathways require expensive clinical validation for each reformulated propellant variant, compressing margins for mid-tier manufacturers.
- Patient switching friction:Established CFC-based product familiarity among prescribing dermatologists creates adoption resistance for alternative delivery systems despite equivalent clinical efficacy profiles.
Strategic Opportunities
- Pediatric allergy protocols:Expanding topical corticosteroid application in pediatric atopic dermatitis management offers volume growth in a prescription segment with higher compliance rates and longer treatment durations.
- Hospital formulary consolidation:Integrated delivery networks in the United States are centralizing procurement decisions, creating single-source contract opportunities for manufacturers with broad topical portfolio coverage.
- Green chemistry incentives:State-level environmental purchasing preferences in California and New York are creating procurement advantages for propellant-free or low-global-warming-potential formulations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in topical corticosteroid stability and propellant compatibility is concentrating among retiring professionals, constraining reformulation pipeline velocity.
- Legacy equipment retooling:Existing CFC-capable manufacturing lines require capital-intensive modification or replacement to handle alternative propellant chemistries and compressed gas systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triamcinolone Ointment Chlorofluorocarbons Market |
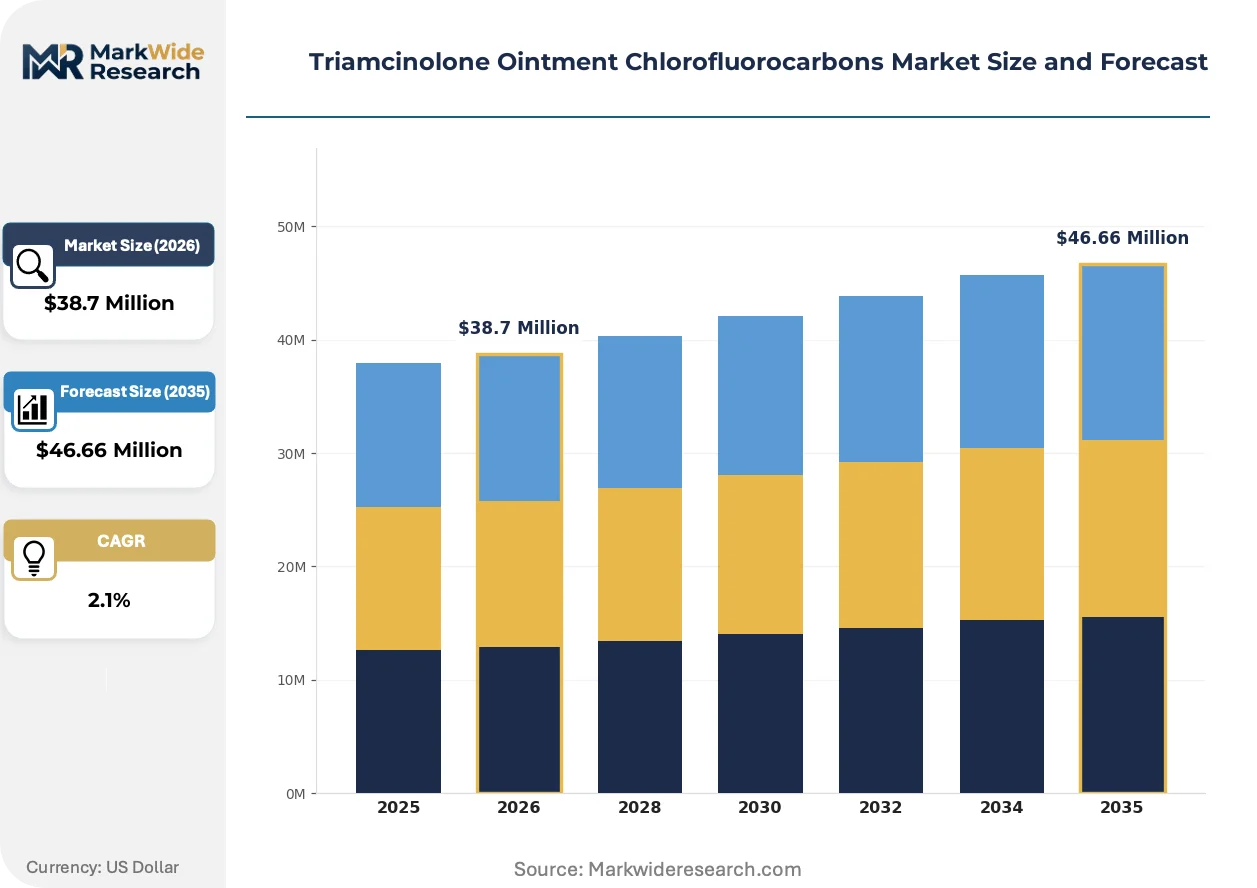
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $46.66 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Cream, Foam, Lotion Application: Dermatology, Allergy Treatment, Respiratory Disorders, Inflammation End User: Hospitals, Pharmacies, Clinics, Home Healthcare Packaging Type: Canister, Tube, Jar, Spray Bottle |
| Companies Covered | Bristol Myers Squibb Company, Sun Pharmaceutical Industries Limited, Lupin Limited, Novartis International AG, Glenmark Pharmaceuticals, Akorn Inc., Cosette Pharmaceuticals Inc., Mylan N.V., Taro Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triamcinolone Ointment Chlorofluorocarbons Market Emerging Trajectories
Propellant chemistry transition is compressing product development cycles while reshaping competitive positioning around regulatory compliance speed rather than traditional formulation differentiation.
Hydrofluoroalkane propellant systems are converging with precision valve engineering to replicate CFC-based spray characteristics in triamcinolone aerosol delivery. Dermatology clinics in the United States are piloting these reformulations at accelerated rates compared to retail pharmacy channels. This convergence is compressing the timeline for therapeutic equivalence certification as manufacturers race to secure abbreviated new drug application approvals before AIM Act phaseout deadlines.
The EPA's AIM Act implementation is mandating hydrofluorocarbon production quota reductions that cascade into pharmaceutical propellant supply constraints. Aerosol formulators are responding by diversifying propellant sourcing across multiple chemical classes and geographic suppliers. Hospital procurement departments are most affected, as they face formulary disruption risks from supply-constrained legacy products.
Consolidated buying by specialty pharmacy benefit managers is displacing traditional wholesale distribution for topical corticosteroid products. United States-based dermatology practices are increasingly channeling prescriptions through limited-distribution networks that require manufacturer direct contracts. This concentration is most visible in Medicare Part D and commercial insurance segments where formulary placement determines prescription volume allocation.
Triamcinolone Ointment Chlorofluorocarbons Market Segmentation
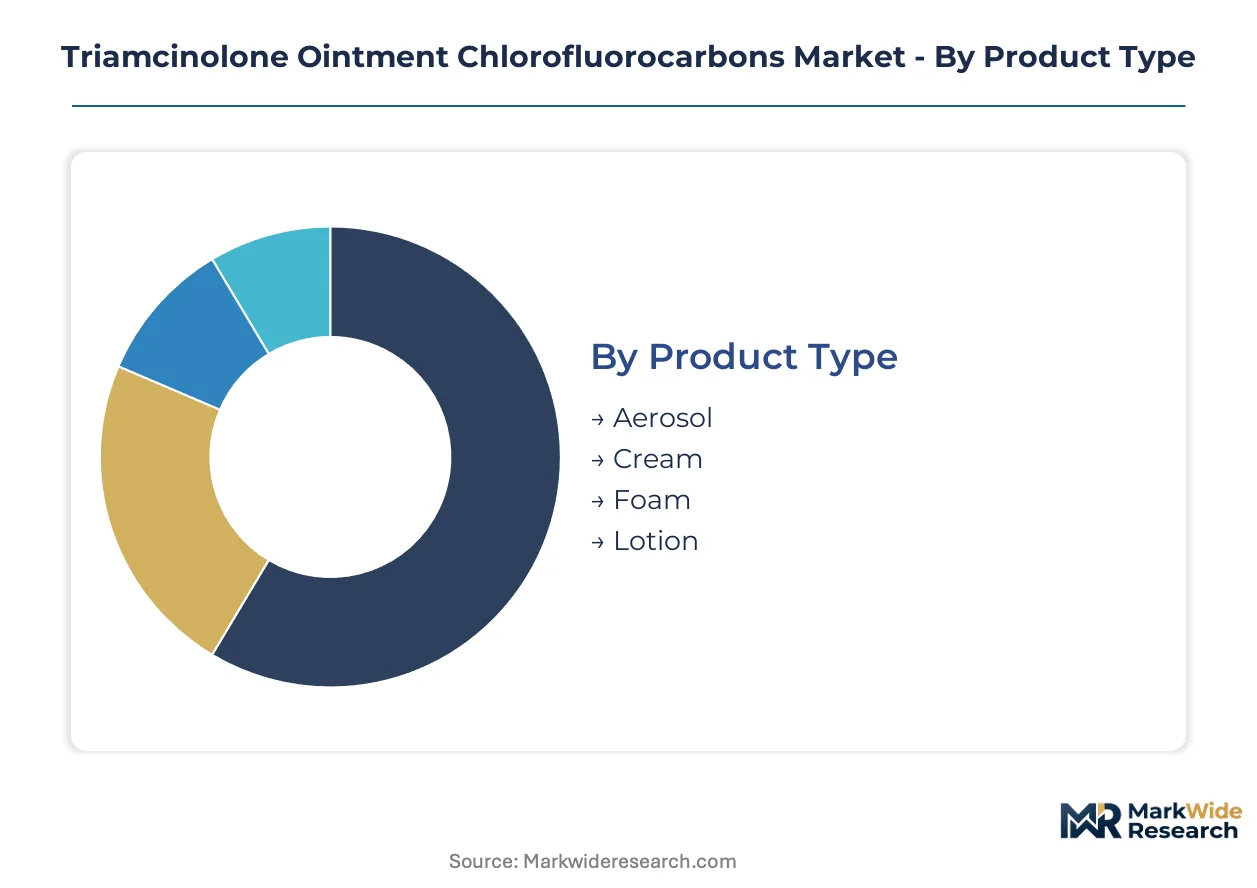
Segmentation in the Triamcinolone Ointment Chlorofluorocarbons Market reflects the tension between legacy propellant formulations and reformulation imperatives driven by environmental regulations. Understanding how demand distributes across product types, applications, and end users enables manufacturers to prioritize R&D investments and channel strategies amid propellant transition pressures.
Product Type:
Formulation technology dictates therapeutic delivery precision and propellant compatibility requirements across the product spectrum.
- Aerosol:Metered-dose spray systems utilizing hydrofluorocarbon or compressed gas propellants deliver triamcinolone acetonide in 0.025% to 0.5% concentrations. United States dermatology clinics are piloting hydrofluoroalkane reformulations at accelerated rates compared to retail channels, driven by EPA AIM Act compliance deadlines.
- Cream:Semisolid emulsion formulations in oil-in-water or water-in-oil bases provide occlusion-dependent penetration for inflammatory dermatoses. Hospital and retail pharmacy channels in the United States are expanding shelf space for cream variants as aerosol supply constraints intensify under propellant phasedown mandates.
- Foam:Quick-breaking mousse formulations offer cosmetically acceptable application for scalp and hair-bearing areas.
- Lotion:Flowable aqueous preparations facilitate large-surface-area application with minimal residue.
Mature deployment sits with Aerosol systems. Newer deployment is concentrated in Cream formulations.
Application:
Clinical indication determines dosing frequency, treatment duration, and prescriber specialty concentration.
- Dermatology:Topical corticosteroid protocols for eczema, psoriasis, and atopic dermatitis constitute the primary prescription volume driver. United States-based dermatology practices generate sustained demand pull as specialized clinics expand and formulary placement for reformulated products solidifies.
- Allergy Treatment:Adjunctive topical therapy for allergic contact dermatitis and urticarial manifestations represents a secondary but climbing indication. Pediatric atopic dermatitis management protocols are expanding corticosteroid application in this segment with higher compliance rates and longer treatment durations.
- Respiratory Disorders:Inhalation delivery of triamcinolone acetonide for asthma and allergic rhinitis operates under distinct regulatory and formulation requirements.
- Inflammation:Broad anti-inflammatory applications span mucosal and cutaneous inflammatory conditions with variable potency requirements.
Dermatology captures established prescription volume. Allergy Treatment is gaining share fastest among expanding indications.
End User:
Procurement concentration and reimbursement pathways segment demand across institutional and retail channels.
- Hospitals:Integrated delivery networks centralize formulary decisions and create single-source contract opportunities for manufacturers with broad topical portfolio coverage. United States hospital procurement departments face disruption risks from supply-constrained legacy propellant products.
- Clinics:Specialized dermatology practices channel prescriptions through limited-distribution networks requiring direct manufacturer contracts. Medicare Part D and commercial insurance formulary placement determines volume allocation in this concentrated channel.
- Pharmacies:Retail and specialty pharmacy benefit managers are displacing traditional wholesale distribution for topical corticosteroid products.
- Home Healthcare:Patient-directed administration for chronic dermatological conditions supports longer treatment adherence.
Hospitals anchor institutional procurement scale. Clinics are expanding most quickly as specialized dermatology practices proliferate.
Packaging Type:
Container engineering must reconcile propellant compatibility, dosing precision, and patient handling requirements.
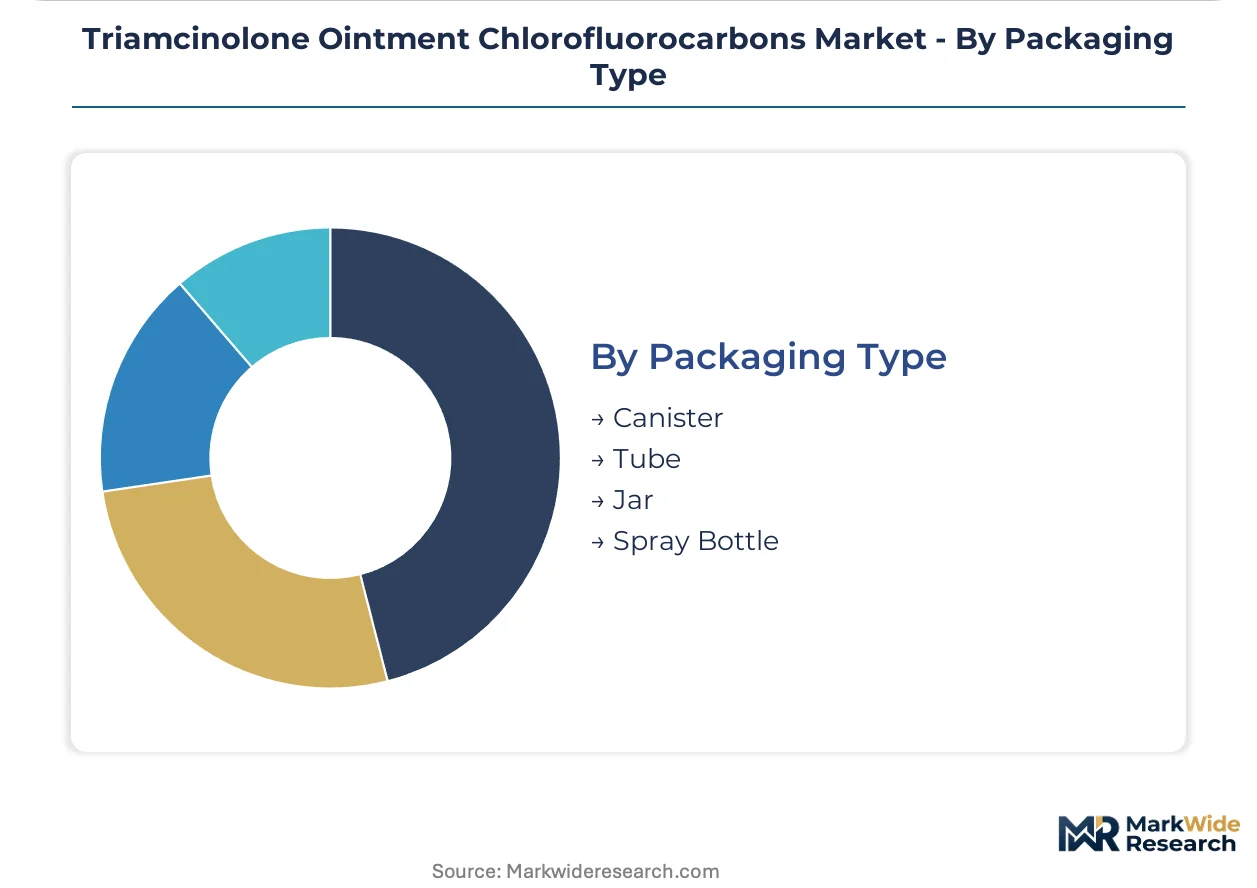
- Canister:Pressurized aluminum or steel containers with metered valves house aerosol formulations and require specialized lining for alternative propellant chemistries. Existing CFC-capable manufacturing lines demand capital-intensive modification to handle compressed gas systems.
- Tube:Collapsible aluminum or laminate tubes for cream and lotion formulations offer barrier protection and controlled dispensing. Tube filling operations face lower retooling burdens compared to aerosol line conversion.
- Jar:Wide-mouth containers accommodate semisolid formulations requiring finger application.
- Spray Bottle:Mechanical pump systems deliver non-pressurized liquid formulations without propellant dependency.
Canister formats dominate legacy aerosol volume. Spray Bottle configurations are climbing the fastest as propellant-free alternatives gain procurement preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey's pharmaceutical corridor along the I-95 corridor anchors North American formulation activity for topical corticosteroid aerosols. The concentration of dermatology research institutions and FDA review divisions in this metro creates proximity advantages for propellant transition trials.
United States
Dermatology clinics in Florida and Texas are expanding prescription volumes for reformulated triamcinolone products ahead of EPA AIM Act deadlines. The FDA maintains abbreviated new drug application pathways for hydrofluoroalkane substitutions requiring bioequivalence validation. New Jersey and North Carolina manufacturing clusters are retooling CFC-capable lines for compressed gas systems.
Germany
Specialized dermatology practices in Bavaria and North Rhine-Westphalia are piloting alternative propellant formulations under ECHA REACH compliance timelines. The EU F-Gas Regulation mandates hydrofluorocarbon quota reductions that cascade into pharmaceutical aerosol supply constraints. Frankfurt's chemical manufacturing corridor is diversifying propellant sourcing across nitrous oxide and carbon dioxide systems.
India
API manufacturing zones in Gujarat and Maharashtra supply concentrated triamcinolone acetonide production for global formulators. The Central Drugs Standard Control Organization regulates topical corticosteroid exports under harmonized international standards. Hyderabad's formulation development hubs are expanding specialized topical capabilities for propellant-free delivery systems.
Switzerland
Precision valve engineering specialists in Basel and Zurich are converging with hydrofluoroalkane propellant systems to replicate CFC spray characteristics. Swissmedic maintains jurisdiction over therapeutic equivalence certification for reformulated dermatological products. The Lake Geneva biopharma cluster is advancing metered-dose precision for alternative aerosol chemistries.
United Kingdom
Hospital procurement departments in London and the Midlands are centralizing formulary decisions for topical corticosteroid products amid supply disruption risks. The Medicines and Healthcare products Regulatory Agency oversees drug formulation safety standards for reformulated propellant variants. The Southeast England pharmaceutical corridor is consolidating manufacturing for cream and lotion alternatives.
Triamcinolone Ointment Chlorofluorocarbons Market Vendor Landscape
Premium-margin players sit above commodity-margin players across propellant transition speed and dermatology portfolio breadth. The vendor base clusters around three strategic archetypes: multinational pharmaceutical conglomerates with established aerosol infrastructure, mid-tier generic manufacturers with formulation flexibility, and specialized topical developers with propellant chemistry expertise. Consolidation pressure intensifies as FDA abbreviated new drug application costs compress margins for standalone operators. Dominant competitive moves include strategic partnerships with compressed gas technology licensors and backward integration into API supply.
Within the multinational tier, Bristol Myers Squibb Company and Novartis International AG occupy positions defined by dermatology portfolio scale and regulatory navigation capabilities. Sun Pharmaceutical Industries Limited and Lupin Limited represent the mid-tier generic archetype, with manufacturing scale across multiple dosage forms providing flexibility during propellant transition. These four entities exemplify competitive positioning around compliance speed rather than traditional formulation differentiation.
| Leading Market Players |
|---|
| Bristol Myers Squibb Company |
| Sun Pharmaceutical Industries Limited |
| Lupin Limited |
| Novartis International AG |
| Glenmark Pharmaceuticals |
| Akorn Inc. |
| Cosette Pharmaceuticals Inc. |
| Mylan N.V. |
| Taro Pharmaceutical Industries |
| Others |
Supply Flow & Price Mechanics
Captive API sourcing from Indian and Chinese manufacturing zones anchors cost structures for triamcinolone formulators while compressing margin flexibility for mid-tier manufacturers navigating EPA propellant transition timelines. This upstream integration pattern concentrates pricing power among vertically integrated players who control active pharmaceutical ingredient supply.
Pricing Analysis
Value-based pricing anchored to therapeutic equivalence certification separates reformulated hydrofluoroalkane products from legacy CFC-based alternatives. Price differentiation reflects FDA abbreviated new drug application costs and propellant chemistry compliance tiers. Pricing pressure stems from bioequivalence trial expenses compressing margins for standalone generic manufacturers. Hospital procurement departments exhibit highest price sensitivity due to formulary consolidation, while dermatology clinics prioritize delivery precision over unit cost.
Supply Chain Analysis
Freight cost volatility from Indian API manufacturing zones to United States formulation facilities is reshaping inventory strategies among topical corticosteroid producers. Triamcinolone acetonide supply concentrates in Gujarat and Maharashtra, with hydrofluoroalkane propellants sourcing from Chinese and European chemical corridors. Single-source vulnerability in metered-dose valve engineering creates chokepoint exposure. Distribution runs through specialty pharmacy benefit managers displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Triamcinolone Ointment Chlorofluorocarbons Market operates as a cost-of-compliance arena where EPA AIM Act propellant phasedown mandates erect regulatory moats favoring manufacturers with capital reserves for abbreviated new drug application pathways.
For Market Incumbents: Hedge against formulary displacement by accelerating hydrofluoroalkane reformulation pipelines ahead of AIM Act quota reductions. Secure backward integration into API supply through long-term contracts with Gujarat and Maharashtra manufacturers. Channel control through direct dermatology clinic contracts offers defensive positioning against specialty pharmacy benefit manager consolidation. For New Entrants and Emerging Players: The premium-economy price gap in propellant-free lotion and cream formulations creates white-space opportunity for mid-tier manufacturers. Target hospital procurement departments in integrated delivery networks seeking dual-source topical corticosteroid contracts. Pediatric allergy protocols offer penetrable entry with higher compliance rates and extended treatment durations. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational pharmaceutical conglomerates seeking dermatology portfolio scale. Long-term viability hinges on regulatory navigation speed rather than traditional formulation differentiation. Watch FDA abbreviated new drug application approval velocity as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Reformulation Pipeline | EPA AIM Act compliance deadlines force hydrofluoroalkane transition investments. |
| API Supply Contracting | Long-term agreements with Indian manufacturers reduce geopolitical disruption exposure. |
| Dermatology Clinic Direct Contracts | Limited-distribution networks bypass specialty pharmacy benefit manager intermediation. |
| Pediatric Formulation Development | Higher compliance rates in atopic dermatitis protocols extend revenue visibility. |
| Compressed Gas Technology Licensing | Nitrous oxide and carbon dioxide systems bypass hydrofluorocarbon quota constraints. |
Methodological Framework
Independent corroboration across regulatory affairs directors, dermatology clinic procurement managers, and pharmaceutical formulation scientists underwrites the qualitative findings. Primary interviews with FDA compliance officers, hospital formulary directors, and topical corticosteroid manufacturing executives combined with secondary validation from FDA filings, EPA AIM Act implementation documents, and ClinicalTrials.gov bioequivalence study records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulate demand estimates.
Comparable-period anchoring to historical propellant transition timelines in respiratory inhalers informed the forecast framework construction. Segmentation modeling across dosage form, end-user channel, and regional regulatory cluster generated volume and value outputs throughout the projection horizon. CAGRs were derived from prescription trend extrapolation and propellant substitution adoption curves. Industry-specific inputs included dermatology clinic expansion rates and AIM Act quota reduction schedules.
Inputs from EPA regulatory dockets and FDA approval databases were available through the study window; gaps in real-time propellant supply pricing introduce uncertainty bands around manufacturing cost assumptions. Forecasts reflect documented assumptions about bioequivalence trial success rates and formulary placement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Long-Acting Insulin Market