
 Water for Injection Market | 2026-2036
Water for Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Water for Injection Market Outlook
Pharmaceutical-grade water purification expertise is unwinding supply constraints across the WFI value chain. Baxter International Inc. leverages its integrated dialysis and infusion therapy platforms to sustain captive WFI demand. Fresenius SE & Co. KGaA anchors European supply through its hospital and pharmaceutical manufacturing networks. Sartorius AG specializes in single-use bioprocessing technologies that compete on sterility assurance for biotech-grade water applications.
Water for Injection denotes highly purified water meeting pharmacopeial endotoxin limits, produced through distillation or reverse osmosis and maintained at temperatures above 65°C to prevent microbial proliferation. Its primary purpose is diluting or dissolving substances for parenteral administration and cleaning equipment in sterile manufacturing environments. Pharmaceutical Grade WFI dominates volume due to injectable drug batch requirements, while Biotech Grade commands premium positioning from monoclonal antibody and cell therapy production. Ampoules and cartridges within Packaging Type are gaining share as pre-filled delivery formats displace bulk container compounding in hospital settings.
The FDA enforces current Good Manufacturing Practice standards for WFI production, storage, and distribution, while the EMA's Annex 1 revision mandates continuous quality monitoring in aseptic processing. ISO 22519 provides harmonized engineering standards for purified water and WFI generation systems that shape equipment procurement decisions. Contract Manufacturing Organizations must navigate divergent pharmacopeial requirements across FDA, EMA, and national regulators when qualifying multi-site WFI supply networks. Stakeholders should monitor how real-time release testing and continuous manufacturing adoption will redefine WFI quality verification protocols.
Market Dynamics
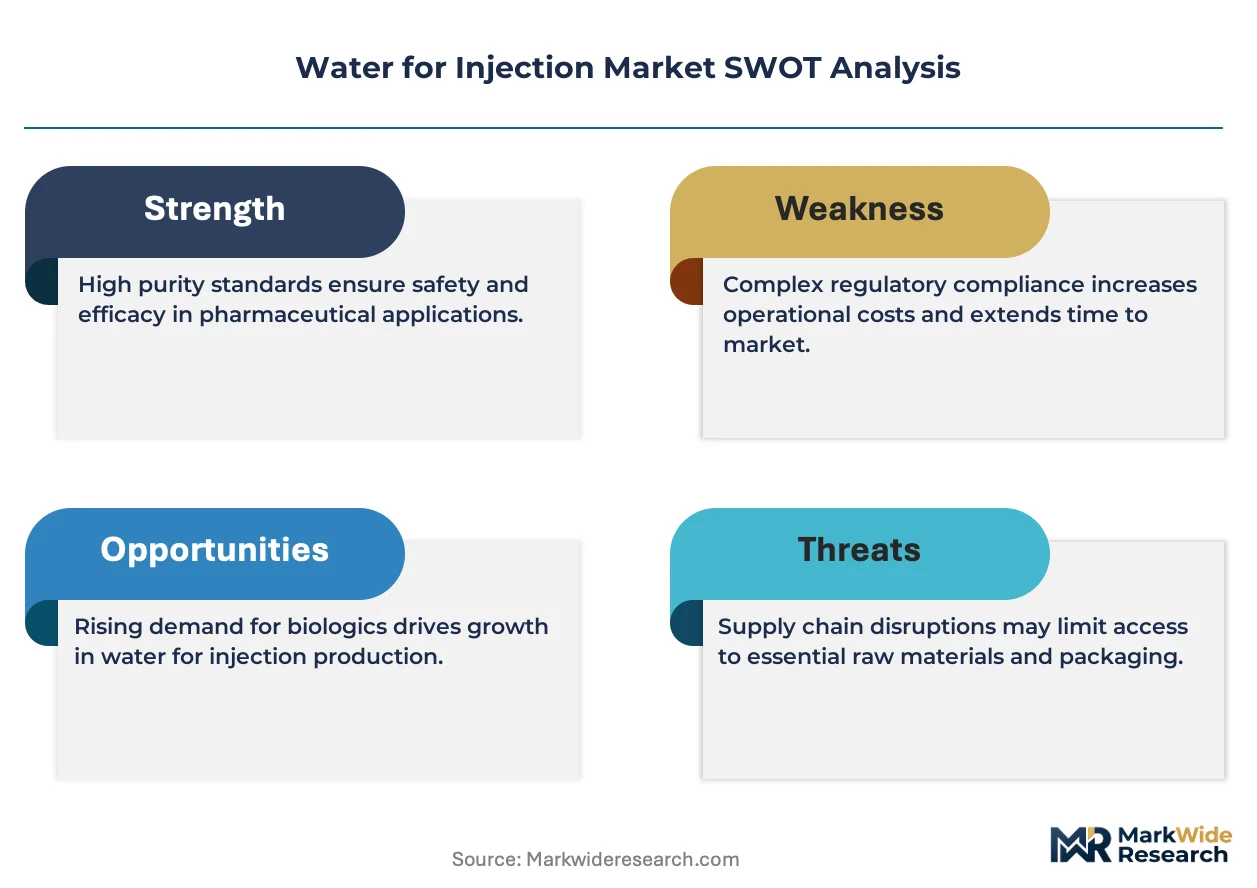
Biologics manufacturing expansion is compressing WFI production cycles as single-use bioprocessing displaces stainless steel infrastructure across sterile drug facilities.
Growth Catalysts
- EMA Annex 1 Revision:The updated aseptic processing mandate requires continuous environmental monitoring, forcing pharmaceutical manufacturers to upgrade WFI generation and distribution systems to maintain compliance.
- Cell Therapy Commercialization:Autologous and allogeneic cell therapy manufacturing requires biotech-grade WFI at volumes tenfold higher than conventional injectables, pulling capacity expansion from specialized suppliers.
- United States Parenteral Capacity Buildout:Domestic sterile fill-finish facility construction is accelerating WFI consumption as drug sponsors reshore production from European contract manufacturers.
Market Restraints
- Energy Input Volatility:Multi-effect distillation and vapor compression systems consume 15-25 kWh per cubic meter of WFI produced, exposing margins to electricity and natural gas price swings in deregulated markets.
- Equipment Supply Concentration:Generation system fabrication concentrates among German and Swiss engineering houses, creating 18-24 month lead times for large-scale distillation skids.
- Endotoxin Detection Limitations:Limulus amebocyte lysate testing remains the pharmacopeial standard despite recombinant Factor C alternatives offering faster results, slowing real-time release adoption.
Strategic Opportunities
- India CDMO Expansion:Contract manufacturing organizations in Hyderabad and Ahmedabad are qualifying WFI systems for export markets, creating demand for validation services and consumables.
- Continuous Manufacturing Integration:FDA's Emerging Technology Program is greenlighting direct WFI-to-dosage-form processing lines that eliminate intermediate holding tanks.
- Point-of-Use Generation:Reverse osmosis-based WFI production at hospital pharmacy compounding centers is displacing bulk tanker delivery in tertiary care networks.
Industry Challenges
- Qualification Timeline Compression:Three-phase process validation per FDA guidance requires 12-18 months from installation to commercial release, straining project schedules.
- Cross-Contamination Controls:Multi-product biologics facilities must implement dedicated WFI loops per production suite, multiplying capital requirements and utility infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water for Injection Market |
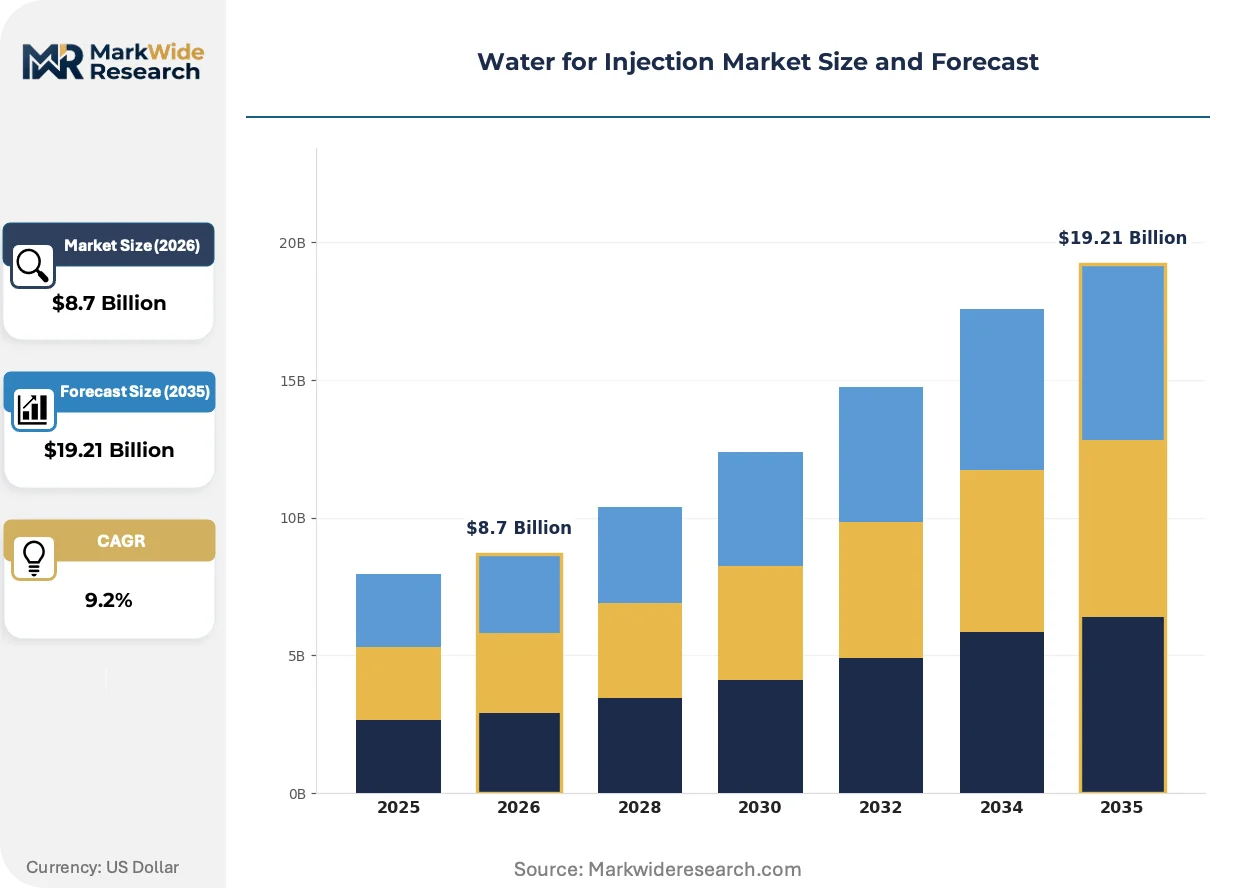
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Biotech Grade, Laboratory Grade, Compounding Grade Application: Pharmaceutical Manufacturing, Laboratory Testing, Hospital Use, Formulation Development Packaging Type: Bottles, Bulk Containers, Ampoules, Cartridges End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Contract Manufacturing Organizations |
| Companies Covered | Pfizer Inc., B. Braun SE, GlaxoSmithKline plc, Abbott Laboratories, Baxter International Inc., Fresenius SE & Co. KGaA, Merck KGaA, Sartorius AG, Evoqua Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water for Injection Market Strategic Shifts
Real-time quality verification and modular system architectures are displacing batch-release paradigms in pharmaceutical water management. Equipment suppliers and end-users are co-developing closed-loop control systems that reduce human intervention.
Single-use WFI distribution assemblies are miniaturizing sterile connection technologies for portable bioprocessing suites. Cell therapy manufacturers are adopting disposable flow paths to eliminate cleaning validation burdens. This architecture is compressing facility startup timelines from years to months for early-stage biotech sponsors.
EMA's Annex 1 revision on sterile medicinal products mandates barrier technology and automated environmental monitoring for all new aseptic facilities. Pharmaceutical manufacturers are retrofitting existing WFI generation rooms with isolator-based sampling systems. European fill-finish operators are absorbing the highest compliance costs as national inspectors align with the 2022 guidance.
Hospital pharmacy compounding is consolidating procurement through integrated delivery networks that self-supply WFI via on-site generation. Large health systems are displacing independent compounders and bulk tanker suppliers with reverse osmosis systems validated for immediate-use applications. This pattern is most visible in United States academic medical centers managing complex parenteral nutrition and oncology protocols.
Water for Injection Market Segmentation
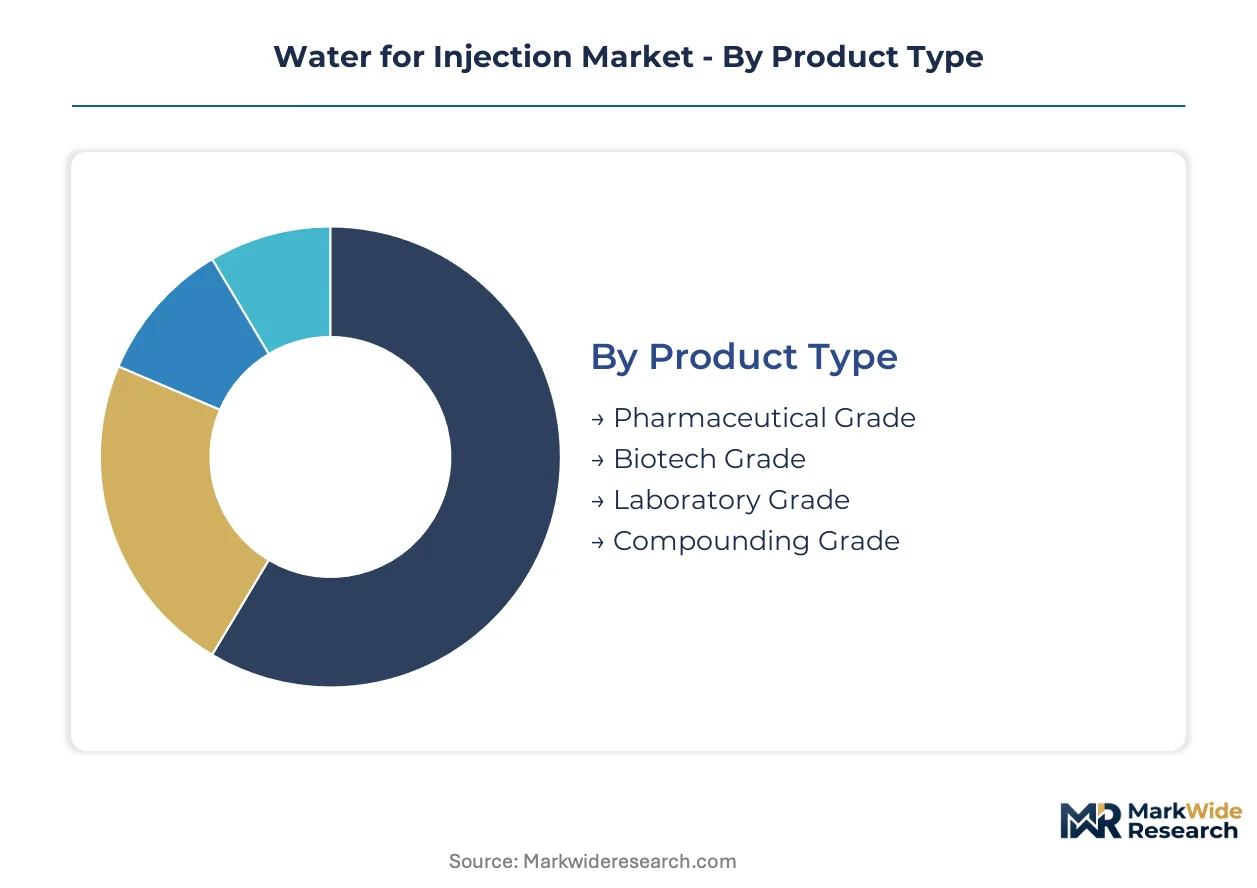
Water for Injection demand fragments across purity grades, packaging formats, and end-user workflows that each impose distinct endotoxin limits, temperature controls, and distribution economics. Understanding these segment boundaries clarifies where capital deployment yields margin capture versus commodity exposure.
Product Type:
Margin pools concentrate in grades serving regulated parenteral manufacturing, where validation documentation commands pricing premiums over laboratory or compounding specifications.
- Pharmaceutical Grade:Meets USP and EP endotoxin limits below 0.25 EU/mL through validated distillation or reverse osmosis with continuous hot storage above 65°C. Injectable drug batch processing in United States sterile fill-finish facilities absorbs the majority of volume as domestic parenteral capacity expands.
- Biotech Grade:Stringent specifications below 0.03 EU/mL support monoclonal antibody and cell therapy production where single-use bioprocessing intensifies consumption per dose. Autologous cell therapy manufacturing in Massachusetts and California biotech clusters pulls capacity from specialized suppliers.
- Laboratory Grade:Satisfies analytical and reagent preparation needs with relaxed endotoxin thresholds.
- Compounding Grade:Serves hospital pharmacy sterile preparation with intermediate purity requirements.
The dominant share belongs to Pharmaceutical Grade, while Biotech Grade is closing the gap fastest.
Application:
Volume concentration tracks sterile drug production cycles, though laboratory and hospital workflows are fragmenting procurement patterns.
- Pharmaceutical Manufacturing:Dilution and dissolution of active pharmaceutical ingredients for parenteral administration, plus equipment cleaning in aseptic suites. FDA's updated aseptic processing guidance tightens quality thresholds for WFI generation and distribution systems.
- Hospital Use:Parenteral nutrition compounding, oncology protocol preparation, and dialysis solution mixing. United States academic medical centers are displacing bulk tanker delivery with on-site reverse osmosis generation validated for immediate-use applications.
- Laboratory Testing:Media preparation, analytical standards, and equipment rinsing in quality control environments.
- Formulation Development:Early-stage drug product characterization and stability studies.
Pharmaceutical Manufacturing holds the largest volume position, with Hospital Use expanding most quickly as integrated delivery networks consolidate procurement.
Packaging Type:
Pre-filled delivery formats are restructuring container economics away from bulk compounding toward unit-dose presentation.
- Ampoules:Sealed glass containers for single-unit parenteral administration eliminate preservative requirements and reduce contamination risk. Pre-filled syringe manufacturing in Germany and Switzerland is pulling ampoule demand from specialized glass converters.
- Cartridges:Pen-injector compatible containers for chronic disease therapies including diabetes and multiple sclerosis. Novo Nordisk and Eli Lilly insulin production facilities in Denmark and Indiana are qualifying cartridge WFI supply chains.
- Bottles:Multi-dose containers for pharmacy compounding and laboratory applications.
- Bulk Containers:Stainless steel totes and tanker deliveries for large-scale manufacturing sites.
Bulk Containers retain the volume lead, though Ampoules and Cartridges together are gaining share fastest as pre-filled formats displace hospital compounding.
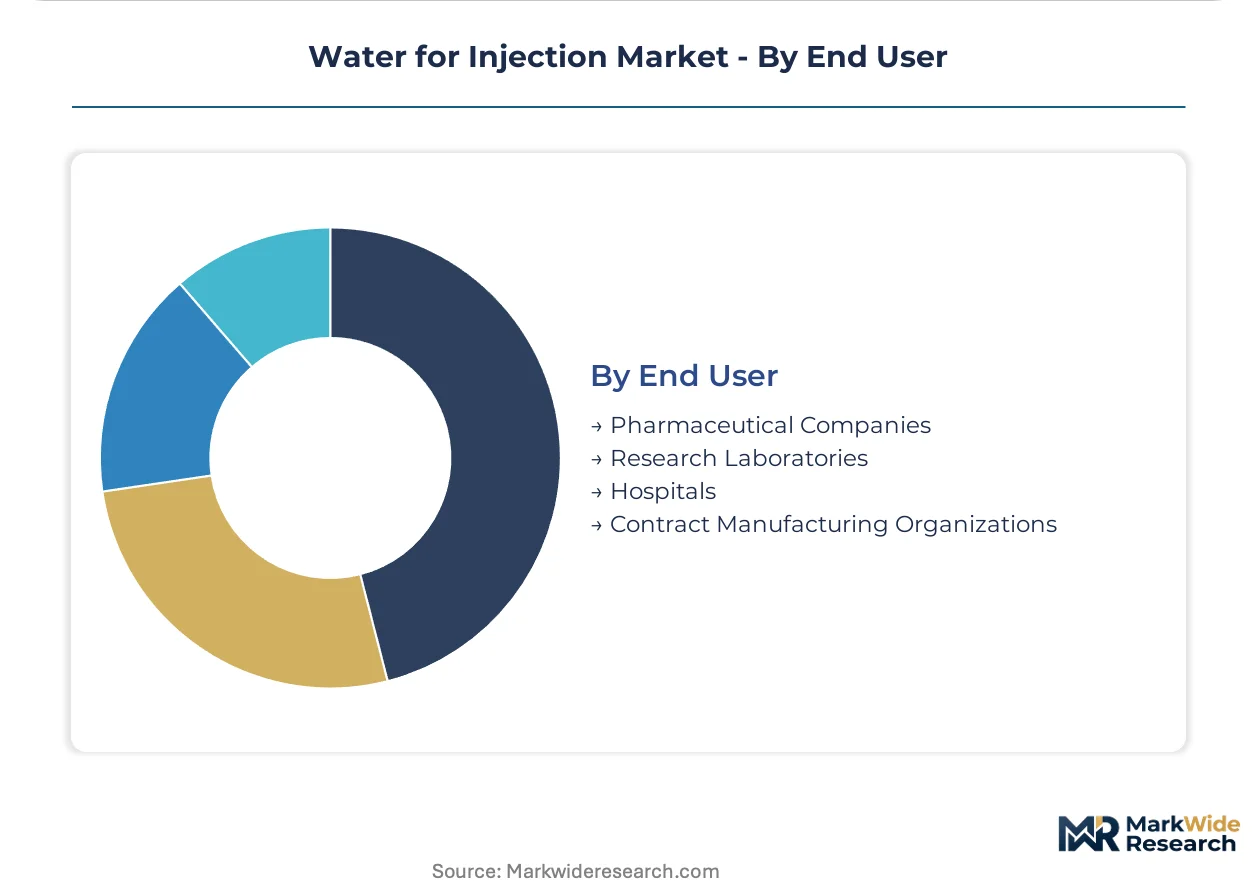
End User:
Procurement authority is concentrating in organizations with captive sterile processing infrastructure and multi-site quality systems.
- Pharmaceutical Companies:Integrated drug sponsors with in-house fill-finish capacity and validated WFI generation loops. Merck and Pfizer manufacturing networks in Ireland and Singapore maintain dedicated distillation systems for monoclonal antibody production.
- Contract Manufacturing Organizations:Multi-client sterile processing facilities navigating divergent FDA, EMA, and national pharmacopeial requirements. Lonza and Catalent sites in Switzerland and Belgium are qualifying WFI supply networks for export market access.
- Research Laboratories:Academic and government facilities with lower volume, higher variability demand patterns.
- Hospitals:Pharmacy compounding centers with emerging on-site generation capabilities.
Pharmaceutical Companies command the dominant procurement position, while Contract Manufacturing Organizations are expanding their share fastest as drug sponsors outsource sterile manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical manufacturers consume WFI primarily for large-scale sterile fill-finish operations, while European and Asian facilities emphasize distributed generation for multi-site compliance networks. This consumption-mix differential shapes equipment procurement patterns and validation service demand across geographies.
United States
Parenteral drug reshoring and cell therapy commercialization are accelerating WFI demand in Massachusetts and North Carolina biotech clusters. FDA's updated aseptic processing guidance tightens quality thresholds for generation and distribution systems. Boston-Cambridge autologous cell therapy facilities pull biotech-grade capacity from specialized suppliers.
Germany
Engineering-intensive distillation system fabrication and monoclonal antibody production anchor WFI consumption in Baden-Württemberg and Bavaria. EMA's Annex 1 revision mandates continuous environmental monitoring for sterile medicinal products. Stuttgart-area equipment fabricators face 18-24 month order backlogs for large-scale generation skids.
Switzerland
High-value biologics manufacturing and precision pharmaceutical packaging concentrate WFI demand around Basel and Zug. Swissmedic alignment with EMA standards enforces harmonized quality verification protocols. Lonza's Visp biologics campus maintains dedicated generation loops per production suite.
India
Contract manufacturing expansion for export markets is qualifying WFI systems in Hyderabad and Ahmedabad pharmaceutical zones. CDSCO's phased alignment with ICH Q7 and Q11 guidelines elevates validation requirements for multi-site supply networks. Telangana's Genome Valley biotech cluster attracts dedicated biotech-grade WFI capacity.
Japan
Aging demographics and chronic disease therapy production sustain hospital and pharmaceutical WFI consumption in the Kanto and Kansai regions. PMDA's GMP ministerial ordinances enforce endotoxin limits matching USP and EP standards. Osaka-based fill-finish operators retrofit existing facilities with isolator-based sampling systems.
Water for Injection Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the WFI market structure. Integrated healthcare conglomerates with captive pharmaceutical manufacturing absorb the largest volume share through internal generation capacity. Specialist equipment fabricators and water technology providers compete on validation documentation and modular system architectures. Competitive moves concentrate on strategic partnerships with biotech sponsors and geographic expansion into emerging CDMO markets.
Among integrated healthcare leaders, Baxter International Inc. and Fresenius SE & Co. KGaA exemplify the captive-demand archetype through their dialysis and infusion therapy platforms. Sartorius AG occupies a position within the specialist tier, representing single-use bioprocessing expertise that competes on sterility assurance. These three anchors illustrate how vertical integration into patient-care delivery contrasts with pure-play technology positioning in WFI value capture.
| Leading Market Players |
|---|
| Pfizer Inc. |
| B. Braun SE |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Baxter International Inc. |
| Fresenius SE & Co. KGaA |
| Merck KGaA |
| Sartorius AG |
| Evoqua Water Technologies |
| Others |
Value Chain & Pricing Dynamics
Reverse osmosis generation displacing multi-effect distillation in hospital pharmacy settings simultaneously redistributes supply geography toward United States academic medical centers and compresses pricing economics for bulk tanker delivery networks. This substitution dynamic intensifies margin pressure on centralized WFI producers while rewarding modular system fabricators with validation expertise.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical manufacturing procurement, with biotech-grade WFI commanding premiums over pharmaceutical-grade based on endotoxin specifications and validation documentation depth. Price differentiation rests on certification tier and geographic delivery cost, with United States parenteral facilities absorbing higher logistics expenses than European counterparts. Cost compression in compounding-grade supply is intensifying because hospital systems are internalizing generation capacity. Research laboratories exhibit highest price sensitivity due to fragmented volume and budget constraints, while cell therapy manufacturers prioritize sterility assurance over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor precision distillation system fabrication, with Baden-Württemberg engineering houses producing generation skids for global pharmaceutical networks. Raw material dependencies center on pharmaceutical-grade stainless steel, specialized membrane assemblies, and Limulus amebocyte lysate testing reagents. Single-source vulnerability concentrates in vapor compression equipment sourced from Stuttgart-area fabricators facing extended order backlogs. Distribution runs through validated cold-chain logistics providers serving sterile fill-finish facilities, with bulk tanker networks consolidating around regional hub-and-spoke configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water for Injection demand sits in early-cycle expansion as cell therapy commercialization and continuous manufacturing adoption accelerate biotech-grade consumption beyond traditional pharmaceutical applications.
For Market Incumbents: Consolidate validation service capabilities and captive generation capacity to defend against modular system suppliers eroding equipment margins. Deepen backward integration into membrane and filtration media production to secure input cost control. Expand United States service infrastructure to capture reshoring-driven qualification demand from Massachusetts and North Carolina biotech clusters. For New Entrants and Emerging Players: Anchor in Indian CDMO validation services where Hyderabad and Ahmedabad facilities are qualifying export-compliant WFI systems. Target hospital pharmacy point-of-use generation as the most penetrable segment, with academic medical centers displacing bulk delivery fastest. Pursue strategic partnerships with integrated delivery networks seeking immediate-use generation expertise. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors specialist equipment fabricators with regulatory documentation depth. Long-term viability over the next decade hinges on continuous manufacturing integration and real-time release testing adoption. Acquisition targets should demonstrate EMA Annex 1 compliance capabilities and modular system architectures. The signal to watch is FDA Emerging Technology Program approvals for direct WFI-to-dosage-form processing lines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA aseptic processing guidance compliance unlocks United States parenteral manufacturing access. |
| Manufacturing Scale-Up | Biotech-grade WFI capacity expansion serves Massachusetts autologous cell therapy commercialization. |
| Backward Integration | In-house membrane production reduces dependency on German filtration media suppliers. |
| Strategic Partnership | Hospital system alliances enable point-of-use generation deployment in tertiary care networks. |
| Geographic Expansion | Indian CDMO validation services capture export market qualification demand from Genome Valley. |
Study Parameters
A standing panel of sterile manufacturing executives, regulatory affairs specialists, hospital pharmacy directors, and water system validation engineers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with equipment fabricators and end-user procurement teams, cross-referenced against FDA 483 observations, EMA inspection findings, and USP pharmacopeial revision notices. Secondary validation drew from pharmaceutical water generation system SEC filings, ISO 22519 implementation case studies, and CDSCO regulatory guidance documents. Bottom-up segment sizing triangulated against top-down industry capacity estimates.
Consistency checks validated volume and value outputs against external benchmarks including pharmaceutical manufacturing capacity databases and sterile fill-finish facility construction tracking. The analytical framework modeled demand across purity grades, packaging formats, end-user workflows, and regional regulatory clusters throughout the projection horizon. CAGRs were derived from facility investment cycles, biologics pipeline advancement rates, and pharmacopeial standard adoption timelines. Forecast inputs incorporated single-use bioprocessing penetration rates and continuous manufacturing technology readiness levels.
Decision-makers should treat outputs as directional under assumptions of stable regulatory alignment between FDA, EMA, and ICH guidelines; material deviation in aseptic processing standards or energy cost trajectories would warrant model refresh. Specific risk factors include endotoxin detection technology transitions, electricity price volatility in deregulated markets, and equipment supply chain elongation. Recalibration cycles align with material shifts in biologics manufacturing capacity deployment and pharmacopeial revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Sweden Pharmaceutical Market