
 Norway Pharmaceutical Market | 2026-2036
Norway Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Pharmaceutical Market Analytics
Norway's domestic biologics manufacturing capacity is narrowing as regional production scales across Nordic neighbors. Roche anchors its Nordic oncology supply chain through specialized cold-chain distribution from Oslo. Novartis leverages its cell therapy infrastructure to sustain access for Norwegian hematology centers. AbbVie differentiates through immunology portfolio depth in a market where biologic penetration runs high.
Pharmaceuticals comprise chemically synthesized or biologically derived substances formulated for disease prevention, diagnosis, or treatment, with active pharmaceutical ingredients typically requiring purity thresholds above 99.5% and stability validation across Nordic temperature ranges. Their primary commercial purpose centers on therapeutic intervention within publicly financed healthcare systems. Prescription drugs command the dominant value share under Norway's centralized drug procurement system, while biologics capture accelerating volume as biosimilar competition intensifies in hospital tenders. Generics face margin compression despite volume growth, as pharmacy reimbursement caps limit price differentiation across the wholesale channel.
NoMA, the Norwegian Medicines Agency, enforces pharmacovigilance and market authorization standards aligned with EMA centralised procedures, while the Norwegian Directorate of Health regulates hospital formulary inclusion through national priority guidelines. These frameworks shape demand by conditioning reimbursement on health technology assessments that favor cost-effectiveness thresholds stricter than many European peers. Stakeholders must monitor how Norway's upcoming hospital procurement consolidation affects tender participation rules for specialty drug suppliers.
Market Dynamics
Norway's hospital procurement consolidation is compressing supplier margins while accelerating biosimilar penetration through centralized tender mechanisms. The national reimbursement framework's recalibration for cell and gene therapies is redistributing value capture toward specialty distributors.
Growth Catalysts
- EMA-aligned fast-track pathways:NoMA's streamlined market authorization procedures for breakthrough therapies accelerate patient access timelines. Hospital formularies incorporate these products within six months of central approval.
- Oslo university hospital cluster:This concentration of tertiary care capacity generates demand pull for innovative oncology and immunology treatments. Clinical trial infrastructure attracts multinational sponsors seeking Nordic patient populations.
- Biologic manufacturing investments:Nordic neighbors' production scale-up creates regional supply security for Norwegian importers. Cold-chain logistics networks strengthen distribution reliability for temperature-sensitive therapies.
Market Restraints
- Reimbursement ceiling rigidity:Norway's cost-effectiveness thresholds under national priority guidelines exclude premium-priced therapies that clear German or French assessments. Health technology assessment timelines extend market access delays.
- Wholesale channel concentration:Three distributors control pharmacy supply, limiting price negotiation leverage for generic manufacturers. Margins compress as reimbursement caps tighten.
- Specialty pharmacy capacity constraints:Centralized compounding for northern counties creates geographic access inequities. Rural hospitals face extended lead times for personalized medicines.
Strategic Opportunities
- Northern county service gaps:Troms and Finnmark present underpenetrated demand for specialty infusion services. Mobile health units could extend clinical trial access to dispersed populations.
- Real-world evidence generation:Norway's longitudinal health registries enable post-market outcome studies that satisfy payer evidence requirements. This infrastructure attracts sponsors seeking differentiated reimbursement arguments.
- Digital therapeutics integration:Prescription digital health products face streamlined regulation under national e-health initiatives. Hospital procurement frameworks are adapting to include software-based interventions.
Industry Challenges
- Gene therapy logistics complexity:Patient-specific manufacturing timelines strain hospital pharmacy workflows. Coordination between Oslo's centralized facility and regional treatment centers requires new operational protocols.
- Pharmacovigilance reporting scale:Biologic adverse event surveillance demands expanded specialist staffing at NoMA. Signal detection capacity has not kept pace with novel modality submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Pharmaceutical Market |
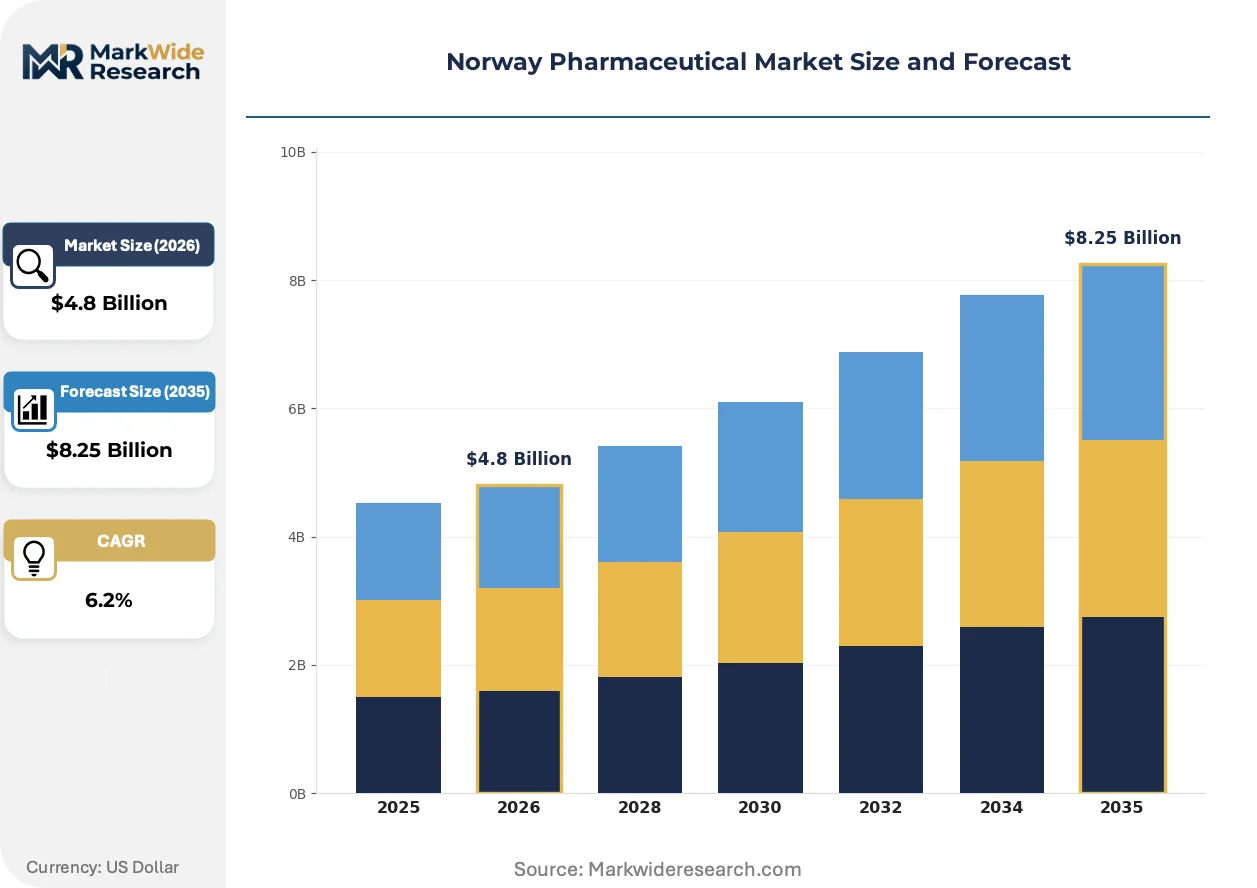
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Biologics, Generics Therapy Area: Cardiology, Neurology, Oncology, Infectious Diseases End User: Hospitals, Pharmacies, Clinics, Homecare Distribution Channel: Wholesalers, Direct Sales, Retail Pharmacies, Online Pharmacies |
| Companies Covered | GlaxoSmithKline, Eli Lilly, AbbVie, Boehringer Ingelheim, Novartis, Roche, Merck & Co, Hikma Pharma, AstraZeneca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Pharmaceutical Market Evolving Landscape
Digital infrastructure is rewiring how therapies reach patients across Norway's dispersed geography. Three convergent developments are compressing traditional distribution timelines and redefining site-of-care economics.
Continuous manufacturing is migrating from batch production paradigms toward integrated flow chemistry systems for small-molecule APIs. Contract manufacturers serving Nordic markets are adopting modular production units to reduce campaign changeover losses. This migration from batch to continuous is enabling just-in-time inventory models that align with Norway's centralized procurement cycles.
NoMA's implementation of EMA's centralized procedure alignment is compressing regulatory review timelines for innovative therapies. The agency's pharmacovigilance system now integrates directly with European databases, reducing duplicate reporting burdens. Hospital formulary committees are responding by accelerating inclusion decisions for centrally authorized products.
Hospital-at-home administration models are displacing traditional infusion center visits for stable biologic therapies. Home nursing networks in Bergen and Trondheim are expanding capacity to support subcutaneous administration training. This channel shift is most visible in immunology, where patient convenience preferences override site-of-care loyalty.
Norway Pharmaceutical Market Segmentation
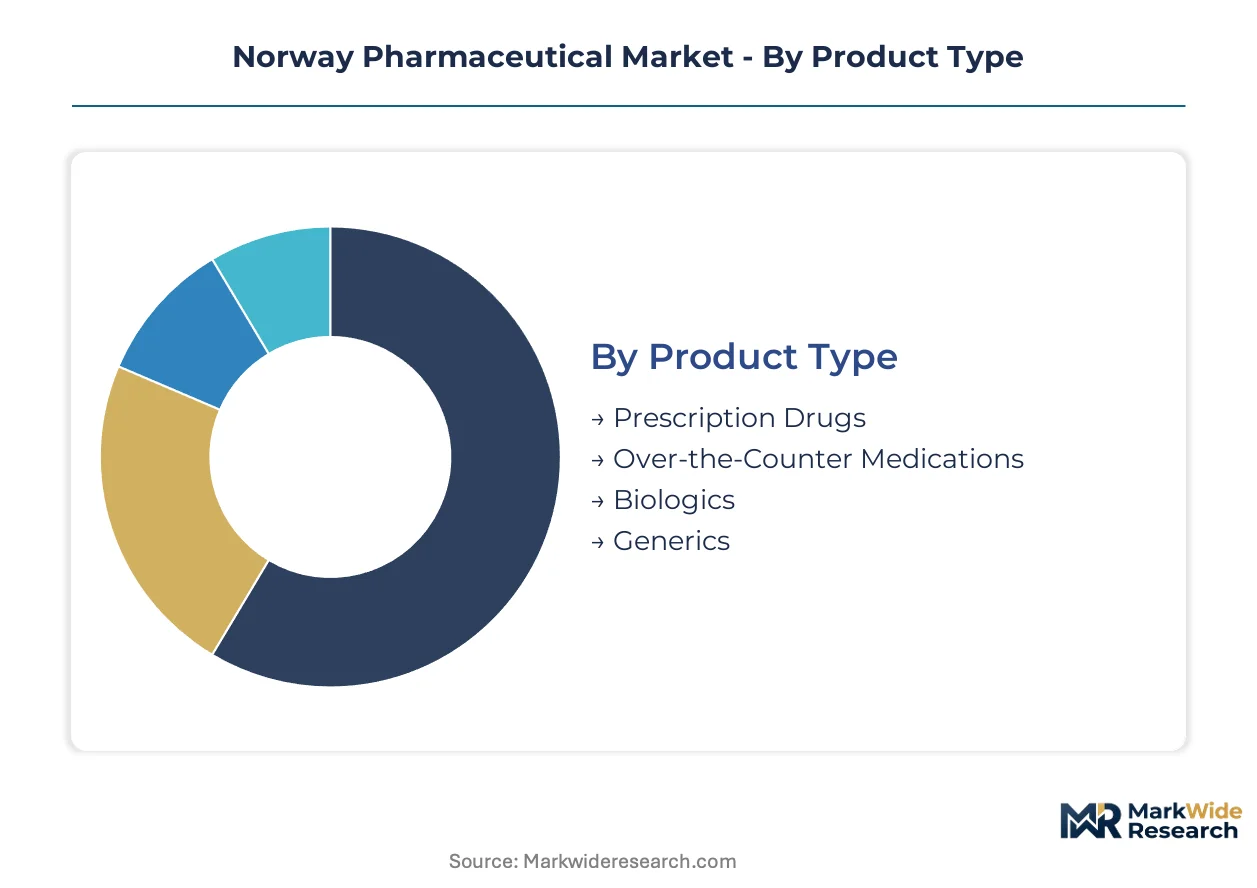
Norway's centralized procurement system fragments demand across product maturity tiers, with hospital tenders favoring established molecules while specialty channels absorb novel biologics. Segment boundaries blur as biosimilar substitution reshapes product classification and site-of-care shifts redistribute end-user volumes.
Product Type:
Mature small-molecule categories coexist with emerging biologic modalities across Norway's formulary tiers, creating divergent margin structures under national reimbursement ceilings.
- Prescription Drugs:Chemically synthesized active pharmaceutical ingredients requiring 99.5% purity thresholds dominate hospital formularies. Oslo's university hospital cluster concentrates demand for cardiovascular and central nervous system therapies under national priority guidelines.
- Biologics:Recombinant proteins and monoclonal antibodies manufactured through cell culture systems command premium positioning. Troms and Finnmark counties face access delays due to cold-chain distribution constraints and centralized compounding bottlenecks.
- Over-the-Counter Medications:Self-care formulations bypass prescription requirements through pharmacy retail networks.
- Generics:Bioequivalent small molecules face margin compression under wholesale channel concentration and reimbursement caps.
Prescription drugs handle the majority of throughput; biologics are expanding most quickly on share.
Therapy Area:
Cost-effectiveness thresholds vary sharply across clinical domains, with oncology and rare diseases receiving preferential assessment latitude under NoMA's health technology framework.
- Oncology:Cytotoxic agents, targeted small molecules, and immuno-oncology biologics constitute the most scrutinized category. Bergen and Trondheim hospital networks participate in pan-Nordic tumor boards that standardize treatment protocols.
- Neurology:Disease-modifying therapies for multiple sclerosis and Parkinson's disease require specialized infusion infrastructure. Rural access gaps persist for patient populations dispersed across northern counties.
- Cardiology:Antihypertensives and anticoagulants anchor primary care prescribing patterns.
- Infectious Diseases:Antimicrobial stewardship programs constrain broad-spectrum utilization.
Oncology commands the largest absolute spend; neurology shows the steepest expansion trajectory as novel mechanisms clear regulatory review.
End User:
Site-of-care economics are restructuring as hospital-at-home programs displace traditional infusion centers for stable chronic therapies.
- Hospitals:Tertiary centers in Oslo, Bergen, Trondheim, and Stavanger coordinate specialized pharmacy compounding and clinical trial access. National procurement consolidation compresses supplier margins through centralized tender mechanisms.
- Homecare:Subcutaneous administration training and home nursing networks expand capacity for immunology and hematology patients. Mobile health units extend reach to dispersed northern populations.
- Pharmacies:Community dispensers handle outpatient prescription fulfillment under reimbursement caps.
- Clinics:Specialist outpatient facilities bridge hospital and primary care interfaces.
Hospitals retain the dominant volume position; homecare is climbing the fastest as administration protocols simplify.
Distribution Channel:
Channel concentration creates structural leverage, with three wholesalers controlling pharmacy supply and limiting price negotiation scope for generic manufacturers.
- Wholesalers:Temperature-controlled logistics networks serve hospital and pharmacy accounts across Norway's elongated geography. Cold-chain reliability investments target biologic integrity maintenance from Oslo distribution hubs to northern county destinations.
- Online Pharmacies:Digital prescription fulfillment platforms gain traction for chronic disease maintenance therapies. National e-health initiatives streamline authentication and reimbursement processing.
- Direct Sales:Manufacturer-to-hospital contracting applies for cell and gene therapies requiring patient-specific logistics coordination.
- Retail Pharmacies:Physical dispensers maintain presence for acute need and elderly patient segments.
Wholesalers channel the preponderance of volume; online pharmacies are gaining share fastest among younger demographics and stable chronic conditions.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical consumption patterns diverge sharply across Nordic borders, with Norway's hospital-centric procurement contrasting Sweden's pharmacy-dispensed model and Denmark's primary care emphasis.
Sweden
Stockholm's Karolinska Institutet drives demand for immuno-oncology and cell therapy clinical trials, while the Dental and Pharmaceutical Benefits Agency (TLV) enforces cost-effectiveness ceilings stricter than Norwegian thresholds. The Uppsala-Stockholm corridor concentrates biologics manufacturing investment from regional contract development organizations.
Denmark
Copenhagen's Medicon Valley anchors insulin and enzyme production for global export, with Novo Nordisk's manufacturing footprint shaping regional supply chain logistics. The Danish Medicines Agency operates accelerated assessment pathways for breakthrough therapies that Norwegian NoMA frequently references in procedural alignment.
Finland
Helsinki's university hospital network coordinates rare disease treatment protocols that Norwegian northern counties emulate for dispersed population access. Fimea, the Finnish Medicines Agency, maintains pharmacovigilance databases integrated with NoMA's Nordic adverse event surveillance system.
Iceland
Reykjavik's single national hospital manages centralized procurement for the entire island population, creating demand concentration patterns that mirror Norway's own consolidation trajectory. The Icelandic Medicines Agency relies on EMA centralized procedures for novel therapy authorization, reducing parallel national review burdens.
Norway Pharmaceutical Market Competitive Landscape
Capability concentration sits with specialty biologic developers; scale advantage sits with diversified pharmaceutical conglomerates. The Norwegian market structures around three tiers: global innovators with Nordic oncology infrastructure, immunology-focused biologic suppliers, and generic manufacturers competing on hospital tender participation. Consolidation pressures intensify as national procurement centralization favors suppliers with integrated cold-chain distribution and real-world evidence generation capacity.
Among the innovator tier, Roche anchors Nordic oncology supply chain operations through Oslo-based specialized distribution, while Novartis occupies a position exemplifying cell therapy infrastructure investment for hematology center access. AbbVie represents the immunology portfolio depth archetype in a market where biologic penetration runs particularly high. These three entities illustrate divergent strategic positioning within Norway's reimbursement-constrained environment.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Eli Lilly |
| AbbVie |
| Boehringer Ingelheim |
| Novartis |
| Roche |
| Merck & Co |
| Hikma Pharma |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
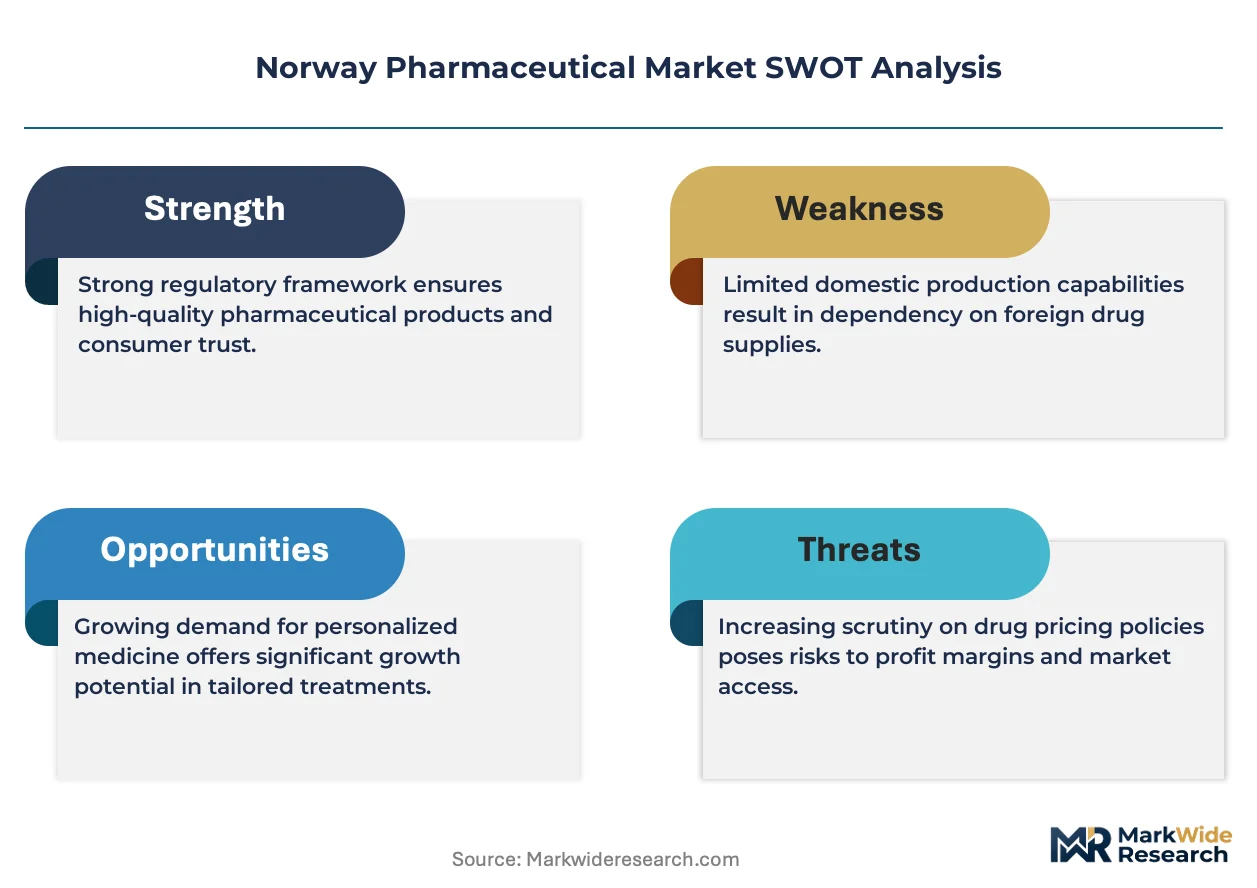
Cold-chain undercapacity across Nordic distribution hubs is forcing specialty biologic suppliers to prioritize long-term hospital contracts over spot market participation, compressing margins for generic manufacturers while securing premium positioning for temperature-validated products.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement, with three-year tender locks replacing annual cycles as Oslo's university hospital cluster consolidates purchasing power. Price differentiation rests on cold-chain certification tier and real-world evidence generation capacity, with biosimilar manufacturers facing the steepest compression as reimbursement caps tighten. Cost compression in the generic tier is intensifying because wholesale channel concentration limits negotiation leverage. Hospital procurement managers demonstrate highest price sensitivity; cell therapy sponsors maintain lowest sensitivity due to patient-specific manufacturing constraints.
Supply Chain Analysis
Tariff exposure between Denmark and Norway dominates logistics risk planning as insulin and enzyme shipments traverse the Copenhagen-Oslo corridor under unified Nordic customs protocols. API manufacturing concentrates in India, China, and Switzerland, with Norwegian formulators drawing from these hubs for small-molecule synthesis. Active pharmaceutical ingredients, sterile fill-finish capacity, and specialized cold-chain packaging constitute critical input dependencies. Single-source vulnerability in gene therapy vector production threatens patient-specific treatment timelines. Distribution runs through Oslo-based wholesaler networks with satellite depots in Bergen and Trondheim.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's pharmaceutical market sits in early-cycle expansion as cell and gene therapy infrastructure attracts multinational sponsors seeking Nordic patient populations for breakthrough therapy development.
For Market Incumbents: Harden formulary defense through backward integration into real-world evidence generation capabilities that satisfy NoMA's health technology assessment requirements. Secure exclusive distribution partnerships with Oslo's centralized compounding facility to block biosimilar substitution for temperature-sensitive biologics. Threat: Hospital procurement consolidation favors suppliers with integrated cold-chain infrastructure. Lever: Captive supply of Nordic patient registry data for post-market outcome studies. For New Entrants and Emerging Players: Build out mobile health unit networks targeting Troms and Finnmark counties where specialty infusion services remain underpenetrated. Penetrable segment: Northern county homecare administration for stable immunology patients. Go-to-market angle: Partner with Bergen and Trondheim hospital-at-home programs to bypass traditional infusion center competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cell therapy logistics infrastructure as patient-specific manufacturing timelines strain hospital pharmacy workflows. Long-term viability favors acquirers targeting specialty distributors with cold-chain validation and centralized compounding relationships. Acquisition archetype: Regional logistics platforms with NoMA pharmacovigilance integration. Signal to watch: Hospital procurement tender participation rules tightening for non-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Generation | Norway's longitudinal health registries enable post-market studies that satisfy NoMA's cost-effectiveness requirements. |
| Cold-Chain Infrastructure Investment | Oslo-based distribution hubs with satellite depots in Bergen and Trondheim secure biologic integrity across northern counties. |
| Hospital Procurement Consolidation | Centralized tender mechanisms favor suppliers with integrated logistics and evidence-generation capabilities. |
| Homecare Administration Expansion | Bergen and Trondheim nursing networks extend reach for subcutaneous immunology therapies. |
| Regulatory Alignment with EMA | NoMA's streamlined authorization procedures accelerate patient access timelines for breakthrough therapies. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions underlying this analysis. Primary interviews with formulary directors and centralized pharmacy compounding operators combined with secondary validation against EMA submissions, ClinicalTrials.gov records, Norwegian hospital procurement databases, and NoMA pharmacovigilance reports. Bottom-up patient population modeling and top-down healthcare expenditure triangulation anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation modeling across therapy area, product type, end user, and distribution channel dimensions. Administration route and regional regulatory cluster variables refined patient access projections. CAGRs derived from historic utilization trend extrapolation adjusted for formulary inclusion timelines and reimbursement threshold shifts. Forecast inputs incorporated biosimilar substitution rates and hospital-at-home program expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cell therapy sponsors or Nordic neighbor manufacturers would shift outcomes beyond modeled ranges. Gene therapy logistics complexity and pharmacovigilance reporting scale constraints constitute specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Mail Order Pharmacy Market