
 Urticaria Drugs Market | 2026-2036
Urticaria Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Urticaria Drugs Market Analytics
Biologics targeting the IgE and IL-5 pathways is fragmenting the traditional antihistamine-dominated treatment paradigm for chronic urticaria. Novartis AG leverages its Xolair franchise to anchor the monoclonal antibody segment with established reimbursement pathways. Genentech, Inc. competes through differentiated dosing regimens and specialist channel depth. Sanofi sustains R&D intensity in next-generation biologics for antihistamine-refractory populations.
Urticaria drugs comprise pharmaceutical agents designed to modulate histamine-mediated vascular permeability and immune dysregulation, with monoclonal antibodies engineered to bind soluble IgE or specific interleukins at nanomolar affinity. These therapeutics serve to terminate wheal formation, angioedema progression, and pruritus in acute and chronic presentations across outpatient and inpatient settings. The monoclonal antibody segment commands the deepest margin pools due to manufacturing complexity and specialist-only administration, while the antihistamine segment remains structurally mature with generic commoditization compressing pricing power. Injectable administration routes concentrate value in hospital and clinic settings where cold-chain logistics and infusion nursing justify premium reimbursement.
The FDA maintains stringent requirements for biologics license applications in chronic urticaria, while the EMA's MDR framework governs companion diagnostic and autoinjector device standards across European markets. These dual regulatory architectures shape clinical trial design, manufacturing scale-up timelines, and market access negotiations for new molecular entities. Stakeholders must monitor evolving biosimilar interchangeability determinations and their cascading effects on formulary positioning and patient switching protocols.
Market Dynamics
The chronic urticaria treatment landscape is restructuring around biologic penetration into antihistamine-refractory patient populations, with reimbursement infrastructure and specialist network density determining commercial success more than molecular differentiation alone.
Growth Catalysts
- EMA MDR framework harmonization:Streamlined device-drug combination approvals across European markets reduce regulatory duplication for autoinjector-enabled biologics.
- Specialist allergist network expansion:United States-based prior authorization infrastructure now supports same-day biologic initiation in major metropolitan clusters.
- IgE pathway validation:Decades of clinical data on soluble IgE neutralization accelerates payer comfort with mechanism-based prior authorization criteria.
Market Restraints
- Cold-chain distribution concentration:Injectable monoclonal antibodies require temperature-controlled logistics that concentrate supply risk with three dominant specialty distributors.
- Biologics manufacturing input scarcity:Stainless steel bioreactor capacity and single-use bag supply constraints limit rapid scale-up for new molecular entities.
- Antihistamine generic commoditization:Second-generation H1 antagonists at pennies per dose create severe price anchoring for payers evaluating biologic value propositions.
Strategic Opportunities
- Japan's aging dermatology patient base:METI's regenerative medicine acceleration framework supports localized clinical development for refractory chronic urticaria populations.
- Subcutaneous formulation convergence:Prefilled syringe and pen device technologies reduce infusion center dependency and expand community-based administration.
- India's CDSCO fast-track pathway:Accelerated approval mechanisms for drugs addressing unmet needs in chronic inflammatory conditions enable earlier market entry.
Industry Challenges
- Biosimilar interchangeability determination delays:FDA's evolving guidance on switching studies creates clinical program uncertainty and extends development timelines.
- Specialist infusion nursing workforce gaps:Biologic administration requires trained personnel that concentrate in academic medical centers, limiting community penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urticaria Drugs Market |
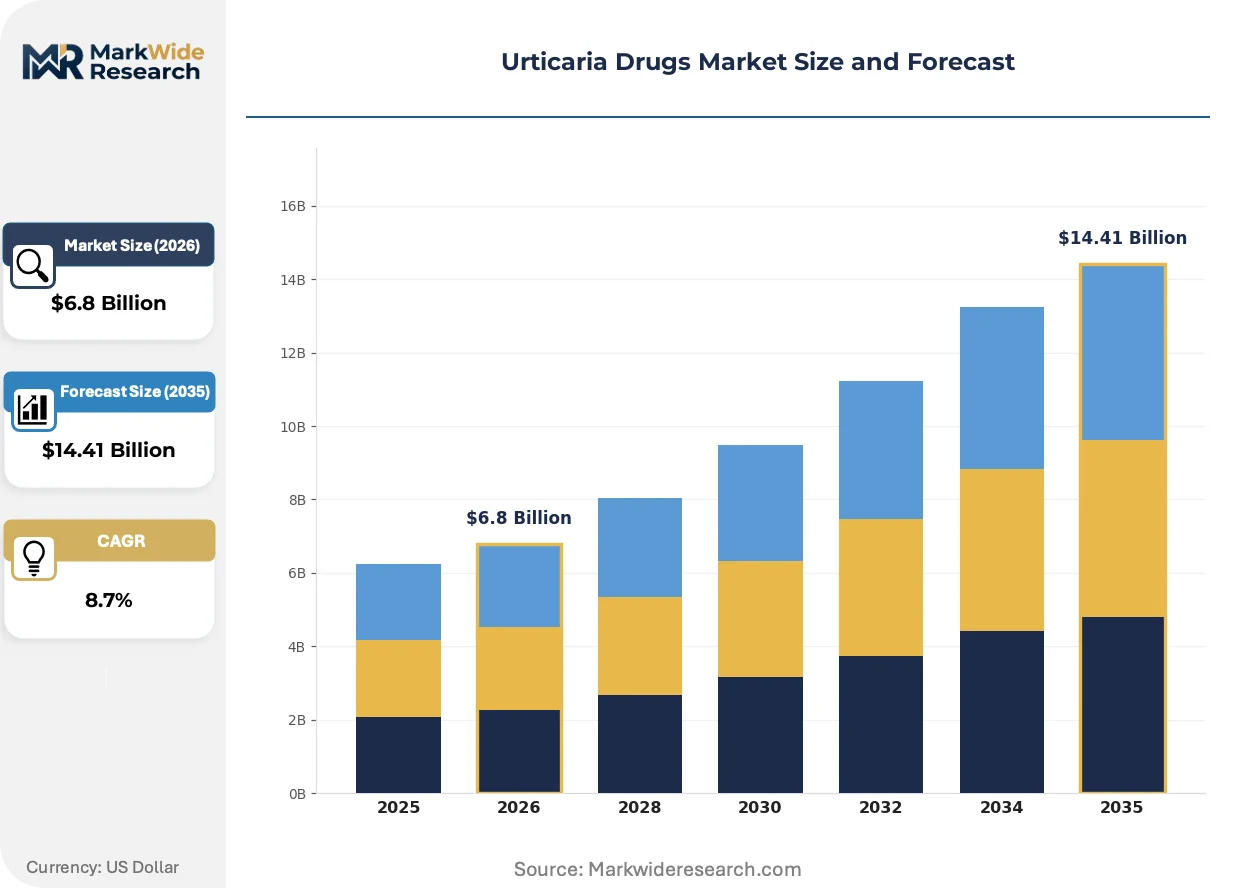
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Antihistamines, Corticosteroids, Immunosuppressants, Monoclonal Antibodies Administration Route: Oral, Injectable, Topical, Sublingual End User: Hospitals, Clinics, Homecare, Pharmacies Application: Chronic Urticaria, Acute Urticaria, Allergic Reactions, Dermatological Disorders |
| Companies Covered | Novartis AG, Pfizer Inc., Sanofi, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd, Genentech, Inc., Amneal Pharmaceuticals, Inc., Sun Pharmaceutical Industries Ltd, Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urticaria Drugs Market Evolving Landscape
Biologic administration is migrating from hospital-based infusion centers toward community and home settings, while regulatory frameworks adapt to combination product complexity and payer evidence requirements intensify.
Subcutaneous autoinjector platforms are collapsing the traditional infrastructure requirement for chronic urticaria biologics. Allergist practices in Germany and the United States now administer Xolair without infusion suite overhead. This shift compresses per-dose reimbursement to facility fees while expanding addressable prescriber bases beyond academic centers.
FDA's evolving biosimilar interchangeability guidance is forcing developers to structure head-to-head switching studies earlier in clinical programs. The industrial consequence is extended Phase III timelines and larger safety databases for molecules targeting the IgE pathway. European developers are responding by prioritizing EMA marketing authorization with US filing deferral to preserve program economics.
Prior authorization automation is altering how specialty pharmacies capture chronic urticaria prescriptions. Electronic prior authorization platforms at CVS Caremark and Express Scripts now process biologic approvals in under 48 hours, displacing traditional hub-and-spoke patient support programs. This acceleration is most visible in United States commercial plans where step-therapy algorithms have standardized around antihistamine failure documentation.
Urticaria Drugs Market Segmentation
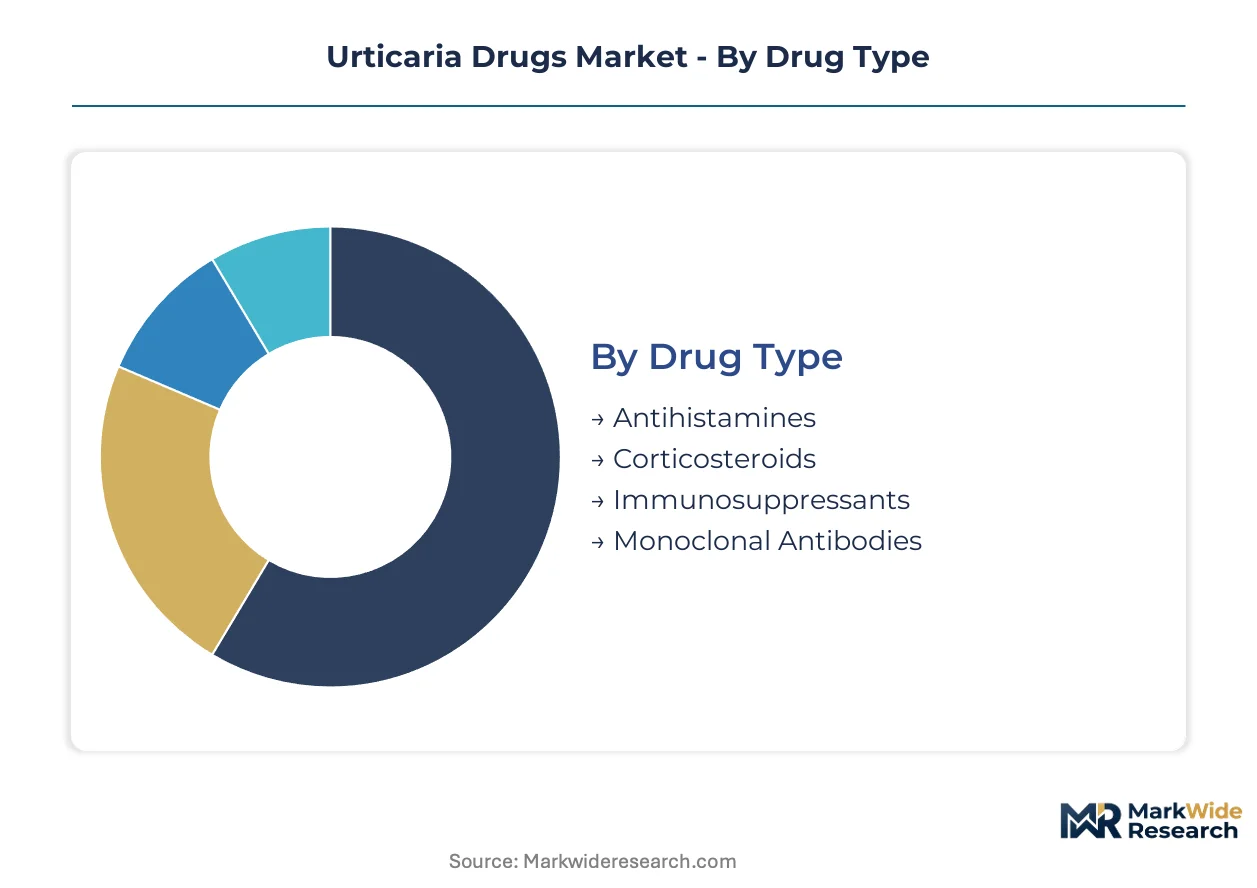
The Urticaria Drugs Market fragments across four structural dimensions that determine pricing power, distribution economics, and clinical adoption velocity. Each segmentation axis captures distinct competitive dynamics between mature genericized categories and emerging biologic platforms.
Drug Type:
Maturity gradients separate commoditized first-line therapies from high-complexity biologics commanding specialist-only access.
- Antihistamines:Second-generation H1 receptor antagonists dominate first-line prescribing through established safety profiles and pennies-per-dose economics. Demand concentrates in primary care networks across Germany and the United States where step-therapy protocols mandate failure documentation before biologic escalation.
- Monoclonal Antibodies:Engineered proteins binding soluble IgE or interleukin receptors at nanomolar affinity serve antihistamine-refractory chronic urticaria populations. Specialist allergist practices in metropolitan United States clusters now initiate same-day therapy through streamlined prior authorization infrastructure.
- Corticosteroids:Short-course systemic and topical formulations address acute flare management with rapid onset kinetics.
- Immunosuppressants:Off-label calcineurin inhibitors and methotrexate occupy a narrowing niche between antihistamine failure and biologic qualification.
Antihistamines retain volume leadership; monoclonal antibodies hold the steepest expansion curve.
Administration Route:
Cost tier stratification runs from mass-market oral tablets to cold-chain-dependent injectable biologics requiring nursing oversight.
- Oral:Tablet and liquid formulations enable patient-directed chronic management with minimal healthcare infrastructure dependency.
- Injectable:Subcutaneous autoinjector platforms are collapsing infusion center requirements for IgE-targeting biologics. German allergist practices now administer therapy without hospital suite overhead, compressing per-dose facility fees while expanding prescriber bases.
- Topical:Localized corticosteroid and antihistamine preparations serve limited skin-surface involvement with minimal systemic exposure.
- Sublingual:Rapid-dissolve formulations address acute pruritus episodes through buccal mucosa absorption bypassing first-pass metabolism.
Oral administration retains volume leadership; injectable routes are gaining share fastest through subcutaneous device convergence.
End User:
Customer type segmentation maps to reimbursement complexity and prescriber credential requirements.
- Hospitals:Academic medical centers concentrate infusion-suite biologic administration for complex cases requiring multidisciplinary oversight.
- Clinics:Specialist allergist practices in the United States and Germany are migrating toward community-based subcutaneous administration without hospital infrastructure.
- Homecare:Self-administered autoinjector therapies expand addressable populations beyond metropolitan specialist density constraints.
- Pharmacies:Retail and specialty pharmacy channels capture oral antihistamine volume and biologic dispensing through cold-chain distribution partnerships.
Pharmacies retain volume leadership; homecare holds the steepest expansion curve through patient-administration device enablement.
Application:
Application segmentation distinguishes between episodic acute management and chronic disease modification requiring sustained therapy.
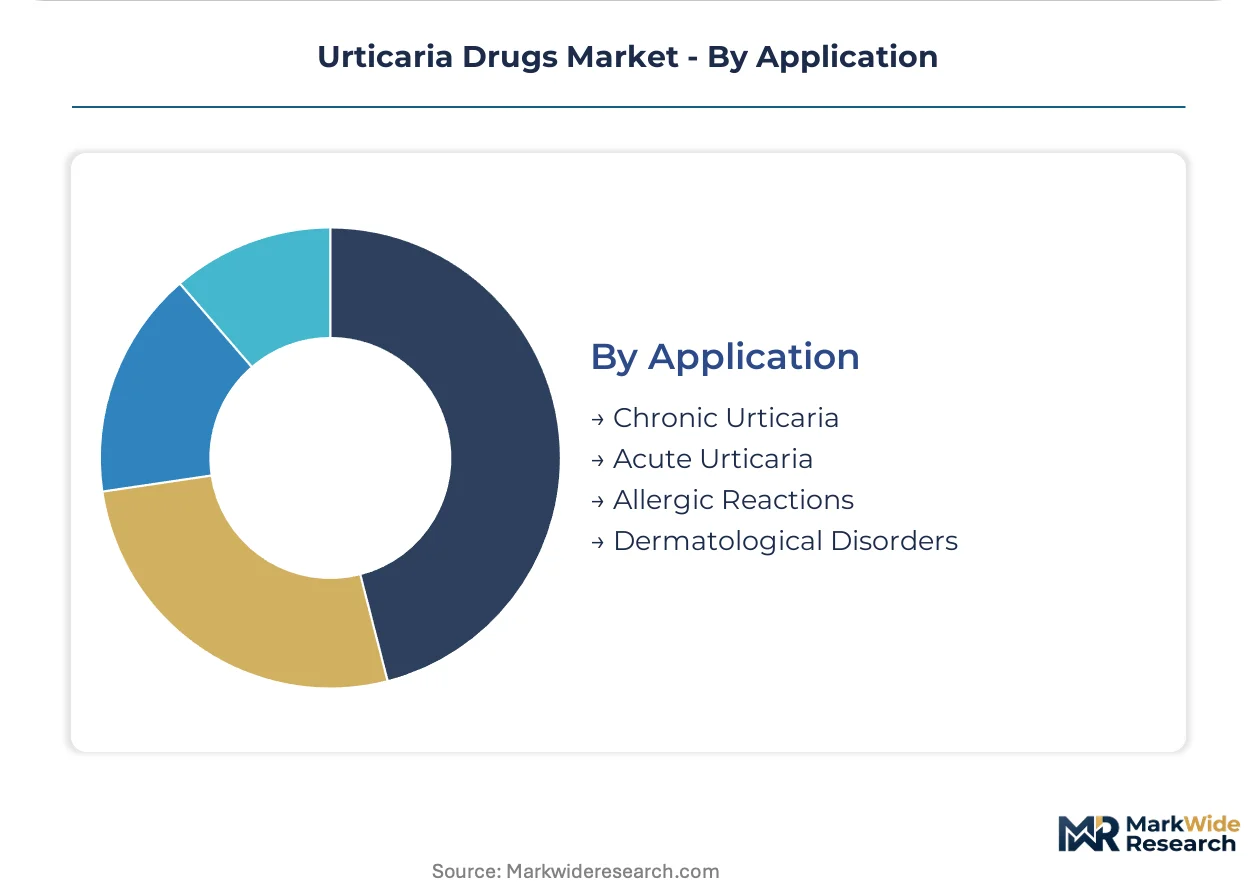
- Chronic Urticaria:Persistent wheal and angioedema presentations exceeding six weeks duration drive biologic penetration. The FDA's evolving biosimilar interchangeability guidance shapes clinical program structure for developers targeting this population.
- Acute Urticaria:Self-limited hypersensitivity reactions resolve with short-course antihistamine therapy, limiting revenue per episode.
- Allergic Reactions:Cross-indication demand from food, drug, and insect venom hypersensitivity expands addressable patient pools for IgE-targeting platforms.
- Dermatological Disorders:Adjunctive use in atopic dermatitis and other pruritic conditions creates off-label utilization beyond urticaria-specific indications.
Chronic urticaria retains volume leadership; allergic reactions hold the steepest expansion curve through indication expansion for established biologic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biologics manufacturers export monoclonal antibodies to United States specialist networks, establishing the primary transatlantic trade corridor for chronic urticaria therapeutics.
United States
Specialist allergist networks in Boston and New York Metro drive biologic penetration through same-day prior authorization infrastructure. FDA's evolving biosimilar interchangeability guidance shapes clinical trial design for developers targeting refractory populations. The Philadelphia corridor concentrates cold-chain distribution capacity with three dominant specialty pharmacy distributors managing temperature-controlled logistics for injectable therapies.
Germany
Community-based allergist practices in Bavaria and North Rhine-Westphalia administer subcutaneous biologics without hospital suite overhead, compressing per-dose facility fees. EMA's MDR framework governs autoinjector device standards and streamlines combination product approvals across European markets. The Munich-Stuttgart industrial cluster hosts manufacturing facilities for prefilled syringe and pen device technologies enabling patient-administered therapy.
Japan
Aging dermatology patient bases in Kanto and Kansai regions intensify demand for next-generation biologics in antihistamine-refractory chronic urticaria. METI's regenerative medicine acceleration framework supports localized clinical development through streamlined regulatory pathways. The Tokyo-Osaka corridor concentrates specialist prescriber density and reimbursement infrastructure for premium biologic uptake.
India
Domestic pharmaceutical manufacturing in Maharashtra and Gujarat supplies generic antihistamines to price-sensitive acute urticaria markets across South Asia and Africa. CDSCO's fast-track approval pathway for drugs addressing unmet needs in chronic inflammatory conditions accelerates market entry for new molecular entities. The Hyderabad-Bengaluru corridor concentrates contract research and manufacturing capacity for biologics process development.
Switzerland
Specialist healthcare infrastructure in Zurich and Geneva sustains premium pricing for biologic therapies in chronic urticaria with established IgE pathway validation. Swissmedic maintains stringent biologics licensing requirements that align with EMA standards while preserving national regulatory autonomy. The Basel-Zurich corridor concentrates pharmaceutical headquarters and early-stage clinical research facilities for monoclonal antibody development.
Urticaria Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around biologic platforms and commoditized antihistamine generics. Large-cap pharmaceutical conglomerates anchor the monoclonal antibody segment through established reimbursement pathways and specialist network relationships. Three strategic archetypes dominate: vertically integrated biologics manufacturers with captive manufacturing capacity, generic antihistamine specialists competing on pennies-per-dose economics, and emerging biotech developers targeting IL-5 and novel cytokine pathways. Competitive moves concentrate on subcutaneous formulation convergence reducing infusion center dependency, and strategic partnerships with specialty pharmacy distributors securing cold-chain logistics access.
Within the vertically integrated biologics tier, Novartis AG and Genentech, Inc. exemplify channel-controlling archetypes with established specialist network penetration and reimbursement infrastructure. Sanofi occupies a position among the next-generation biologics developers sustaining R&D intensity for antihistamine-refractory populations. These three anchors represent distinct competitive vectors: legacy IgE pathway dominance, differentiated dosing regimen specialization, and pipeline-forward cytokine targeting respectively.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Sanofi |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd |
| Genentech, Inc. |
| Amneal Pharmaceuticals, Inc. |
| Sun Pharmaceutical Industries Ltd |
| Johnson & Johnson Services Inc. |
| Others |
Value Network & Pricing Analysis
Stainless steel bioreactor capacity concentration in Germany and Switzerland anchors margin pools in the monoclonal antibody tier, where cold-chain logistics costs cascade into specialist-only reimbursement premiums. Antihistamine commoditization in India and China compresses pricing power at the volume base, creating divergent margin architectures across the therapeutic stack.
Pricing Analysis
Next-generation subcutaneous autoinjector biologics command substantial premiums over prior-generation infusion-center formulations, while first-line antihistamines trade at commodity spot levels. Three-tier pricing structure across premium biologics, standard specialist-administered therapies, and economy oral generics reflects certification grade and administration complexity. Cost compression in the antihistamine tier intensifies as Indian manufacturers expand export capacity. Primary care networks exhibit acute price sensitivity; academic medical centers show relative inelasticity for mechanism-based prior authorization.
Supply Chain Analysis
Upstream cell culture media and single-use bioprocessing bags draw from manufacturing clusters in Germany, Switzerland, and the United States. Stainless steel bioreactor components, affinity chromatography resins, and pharmaceutical-grade excipients feed from specialized chemical suppliers. Single-source vulnerability concentrates in three dominant specialty distributors managing temperature-controlled logistics. Distribution runs through hospital-based infusion suites migrating toward community allergist practices and direct-to-patient specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Urticaria Drugs Market is recovering from antihistamine genericization troughs, with biologic penetration into refractory populations providing cyclical uplift through mechanism-based prior authorization expansion.
For Market Incumbents: Build regulatory data moats through head-to-head switching studies addressing FDA biosimilar interchangeability guidance. Deepen backward integration into single-use bioprocessing bag supply to mitigate manufacturing input scarcity. Consolidate specialist channel control against emerging IL-5 pathway developers threatening IgE franchise dominance. For New Entrants and Emerging Players: Build out subcutaneous formulation capabilities targeting community-based allergist practices outside academic medical center clusters. Japan's aging dermatology patient base offers the most penetrable geography through METI's regenerative medicine acceleration framework. Pursue CDSCO fast-track pathway entry for antihistamine-refractory chronic urticaria indications. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated biologics manufacturers with captive stainless steel bioreactor capacity and established EMA MDR framework compliance. Long-term viability hinges on pipeline depth beyond IgE pathway validation. Monitor FDA interchangeability determinations as the critical inflection signal for biosimilar switching protocol adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Autoinjector Development | Reduces infusion center dependency and expands community prescriber bases beyond academic clusters. |
| EMA MDR Compliance Investment | Streamlines combination product approvals across European markets for device-enabled biologics. |
| Specialist Network Partnership | Secures prior authorization infrastructure for same-day biologic initiation in metropolitan United States. |
| Cold-Chain Distribution Expansion | Mitigates concentration risk with dominant specialty pharmacy distributors managing injectable logistics. |
| IL-5 Pathway Clinical Advancement | Differentiates pipeline beyond established IgE mechanisms for antihistamine-refractory populations. |
Research Methodology
The analysis maps antihistamine, monoclonal antibody, corticosteroid, and immunosuppressant segments, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview insights triangulate against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue reconciliation anchor quantitative outputs.
Assumptions held fixed include current FDA biosimilar interchangeability guidance and EMA MDR framework standards; variables include subcutaneous formulation adoption velocity and specialist network expansion rates. The projection horizon spans drug type, administration route, end user, and application dimensions with regional regulatory cluster overlays. CAGRs derive from patient population epidemiology, biologic penetration curves, and antihistamine generic substitution patterns across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive moves by IL-5 pathway developers or biosimilar entrants would shift outcomes beyond modeled ranges. Cross-checking against CMS Medicare Part B spending data and commercial plan formulary placement trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Global Topical Analgesic Market