
 Automated Cannabis Testing Market | 2026-2036
Automated Cannabis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Cannabis Testing Market Outlook
Aftermarket service revenue from calibration contracts and consumable replenishment is rewriting margin economics for instrument vendors. Agilent Technologies leverages its CrossLab service portfolio to capture recurring revenue from compliance-driven laboratories. Shimadzu Corporation anchors its position through localized application support centers in states with mature cannabis programs. Thermo Fisher Scientific competes by extending its chromatography software ecosystem into seed-to-sale traceability integrations.
Automated cannabis testing encompasses robotic sample preparation coupled with chromatographic and spectroscopic detection systems operating at throughputs exceeding 500 samples daily, designed to quantify cannabinoid potency, terpene profiles, and residual contaminants in flower, extract, and infused product matrices. Liquid chromatography with UV or mass spectrometric detection dominates routine potency analysis due to its compatibility with non-volatile, thermally labile cannabinoids at the parts-per-million thresholds required by most state regulations. High-throughput screening workflows are gaining share fastest among laboratories processing batch release for multi-state operators, while data management solutions represent an emerging margin pool as laboratories face audit scrutiny from state departments of agriculture and public health.
The FDA's enforcement discretion framework for cannabis-derived drug development, combined with state-level departments of agriculture implementing ISO 17025 accreditation requirements, is elevating instrument validation documentation to a competitive gate. EPA methods 8270 and 8081 for residual solvent and pesticide screening are becoming de facto standards even in the absence of federal cannabis scheduling reform. Stakeholders must monitor how state laboratory accreditation reciprocity agreements reshape equipment procurement cycles and service contract structures.
Market Dynamics
State-mandated batch testing volumes are compressing laboratory turnaround times below 48 hours, forcing capital deployment into robotic sample handling systems that eliminate manual preparation bottlenecks. This throughput imperative is restructuring vendor-customer relationships around uptime guarantees rather than equipment ownership.
Growth Catalysts
- ISO 17025 accreditation mandates:State departments of agriculture in California and Colorado now require accredited methods for potency and contaminant screening, driving replacement of legacy manual workflows with validated automated platforms.
- Multi-state operator expansion:Cannabis companies operating across jurisdictional boundaries require harmonized testing protocols, concentrating procurement with vendors offering standardized liquid chromatography-mass spectrometry configurations.
- Residual solvent screening protocols:EPA Method 8270 adoption for volatile organic compound detection in concentrates is elevating gas chromatography headspace automation from optional to mandatory equipment categories.
Market Restraints
- Helium supply volatility:Gas chromatography systems depend on helium carrier gas sourced primarily from Qatar and Russia, with price spikes disrupting operating cost models for pesticide screening laboratories.
- Capital intensity barriers:Fully automated high-throughput installations exceed $800,000 per line, excluding smaller independent laboratories from compliance-grade testing capabilities.
- Inter-state regulatory fragmentation:Absence of federal scheduling reform prevents method reciprocity between California and New York laboratories, duplicating validation expenditures.
Strategic Opportunities
- Seed-to-sale software integration:LIMS platforms connecting analytical results to state traceability systems represent unpenetrated white space beyond instrument hardware margins.
- Emerging medical markets:Germany's BfArM cannabis agency is establishing GMP testing requirements for pharmaceutical-grade extracts, opening premium instrument configurations.
- Terpenoid profiling services:Automated solid-phase microextraction coupled with GC-MS is digitizing quality differentiation for craft cultivators seeking strain-specific certification.
Industry Challenges
- Analytical chemist scarcity:Laboratories struggle to recruit personnel qualified in mass spectrometry method development for complex cannabis matrices.
- Legacy LIMS incompatibility:Older data management systems lack API architectures required for real-time state reporting, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Cannabis Testing Market |
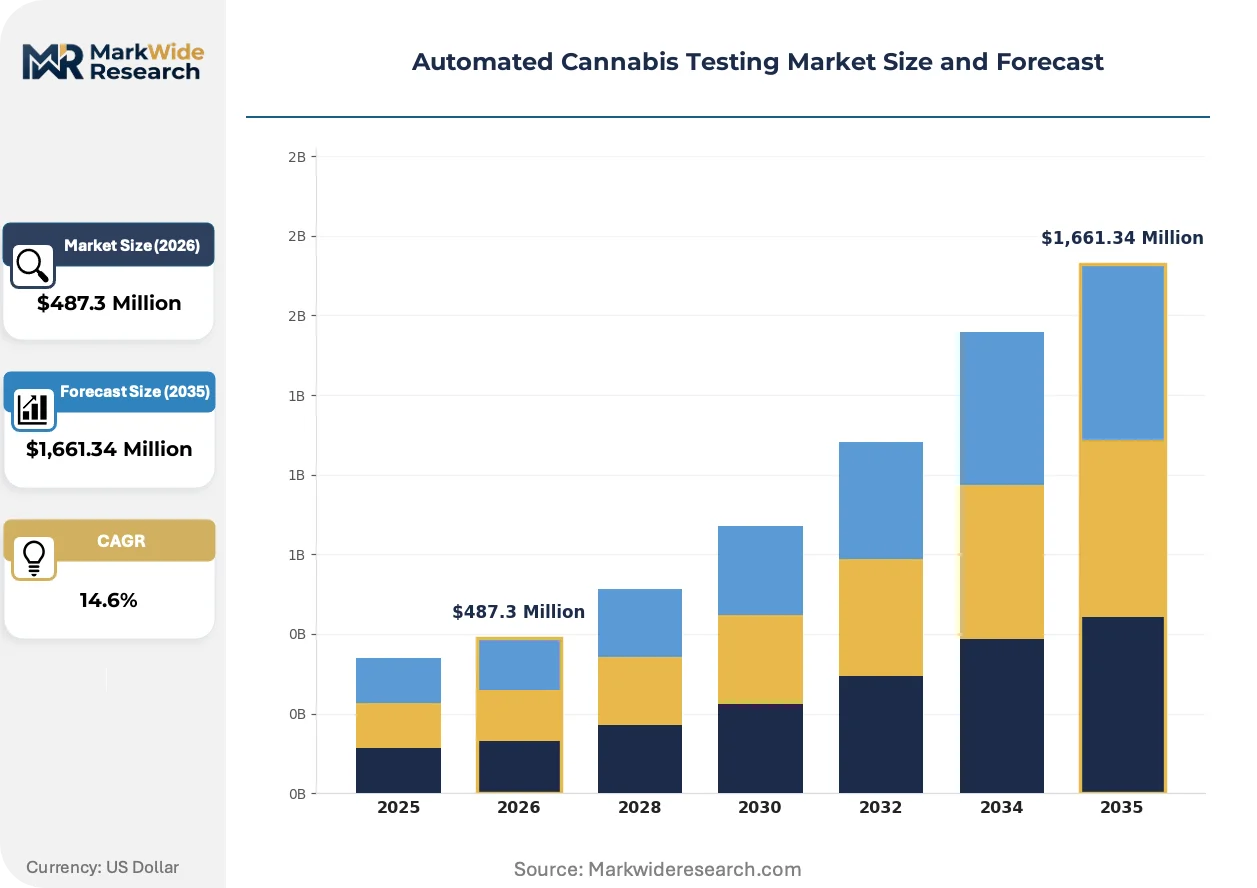
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Chromatography, Liquid Chromatography, Mass Spectrometry, Near-Infrared Spectroscopy End User: Laboratories, Research Institutions, Manufacturers, Regulatory Agencies Technology: High-Throughput Screening, Analytical Techniques, Data Management Solutions, Automation Software Application: Quality Control, Compliance Testing, Research & Development, Product Development |
| Companies Covered | PerkinElmer Inc., Shimadzu Corporation, Agilent Technologies, Inc., Merck KGaA, Waters Corporation, Thermo Fisher Scientific, AB SCIEX LLC, Medicinal Genomics Corp., Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Cannabis Testing Market Strategic Shifts
Robotic automation is compressing the gap between sample receipt and certificate-of-analysis issuance, while regulatory digitization is embedding compliance documentation directly into instrument firmware rather than external audit trails.
Automated solid-phase extraction workstations are digitizing sample preparation for pesticide panels, eliminating technician variability in solvent volume and elution timing. High-throughput laboratories in Colorado and California are deploying these systems at 1,000-sample daily throughputs. The technology is digitizing compliance economics by reducing headcount per instrument from three shifts to unattended overnight operation.
EPA Method 8081 organochlorine screening is becoming a de facto federal standard through state adoption cascades, even absent congressional rescheduling. This regulatory convergence is forcing instrument vendors to pre-configure pesticide libraries and calibration curves. California laboratories are responding by consolidating procurement with vendors offering EPA-validated method packages rather than custom development.
Service contract unbundling is separating preventive maintenance from software updates and regulatory method revisions. Multi-state operators are negotiating direct calibration gas supply agreements to bypass vendor markups. This procurement evolution is most visible in Michigan, where large vertically integrated cultivators are bringing metrology functions in-house while outsourcing only break-fix hardware support.
Automated Cannabis Testing Market Segmentation
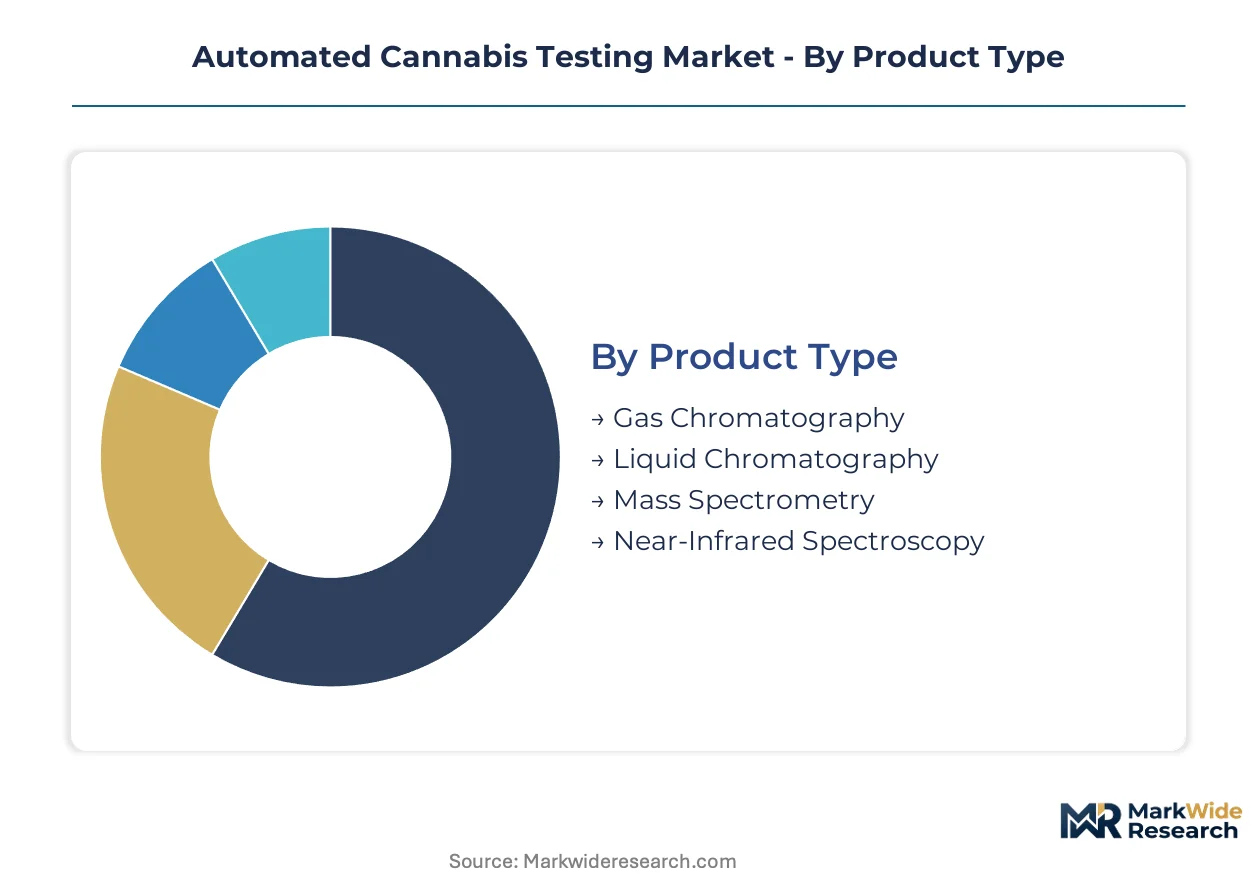
Segmentation in automated cannabis testing reveals how capital allocation, regulatory pressure, and sample throughput requirements reshape procurement patterns across instrument categories and customer types.
Product Type:
Use-case spectrum spans potency quantification, contaminant detection, and terpene profiling, with each application demanding distinct separation physics and detection limits.
- Liquid Chromatography:UV and mass spectrometric detection configurations dominate routine cannabinoid potency analysis due to compatibility with non-volatile, thermally labile compounds. California and Colorado laboratories concentrate procurement here, driven by state mandates for parts-per-million threshold compliance in batch release testing.
- Mass Spectrometry:Triple-quadrupole and time-of-flight platforms deliver definitive identification of pesticides, mycotoxins, and residual solvents at trace levels. Multi-state operators in Michigan and Massachusetts are standardizing on these configurations to harmonize protocols across jurisdictional boundaries.
- Gas Chromatography:Headspace and thermal desorption systems target volatile terpenes and residual solvents per EPA Method 8270.
- Near-Infrared Spectroscopy:Portable and at-line configurations enable rapid incoming material screening before laboratory submission.
Established volume favors Liquid Chromatography; emerging adoption favors Mass Spectrometry.
End User:
Customer archetypes range from high-volume commercial laboratories to specialized research facilities, each with divergent capital cycles and service contract expectations.
- Laboratories:ISO 17025-accredited commercial testing facilities process 500-plus samples daily using robotic sample handling and chromatographic detection suites. California's state-mandated batch testing requirements compress turnaround times below 48 hours, forcing capital deployment into automated workflows.
- Research Institutions:Academic and government laboratories pursue method development for novel matrices including beverages, topicals, and transdermal patches. Colorado State University's hemp research programs are expanding analytical infrastructure for fiber and grain applications beyond cannabinoid testing.
- Manufacturers:Vertically integrated cannabis companies bring testing in-house to control batch release timelines and protect proprietary formulations.
- Regulatory Agencies:State departments of agriculture and public health laboratories conduct proficiency testing and enforcement sampling.
Procurement concentration sits with Laboratories; capability expansion is climbing the fastest among Manufacturers.
Technology:
Technology layers separate hardware automation from informatics infrastructure, with margin pools shifting toward data integration and compliance documentation.
- High-Throughput Screening:Robotic sample preparation workstations eliminate manual pipetting and extraction bottlenecks, enabling unattended overnight operation. Colorado laboratories deploying these systems report headcount reductions from three shifts per instrument to single-operator oversight.
- Data Management Solutions:LIMS platforms with API architectures connect analytical results to state seed-to-sale traceability systems. Michigan multi-state operators are negotiating direct middleware development to bypass legacy system incompatibility.
- Analytical Techniques:Chromatographic and spectroscopic method packages with pre-loaded regulatory compliance libraries.
- Automation Software:Firmware-embedded compliance documentation and audit trail generation replacing external paper-based systems.
Hardware automation commands current spending; data management solutions are expanding most quickly as audit scrutiny intensifies.
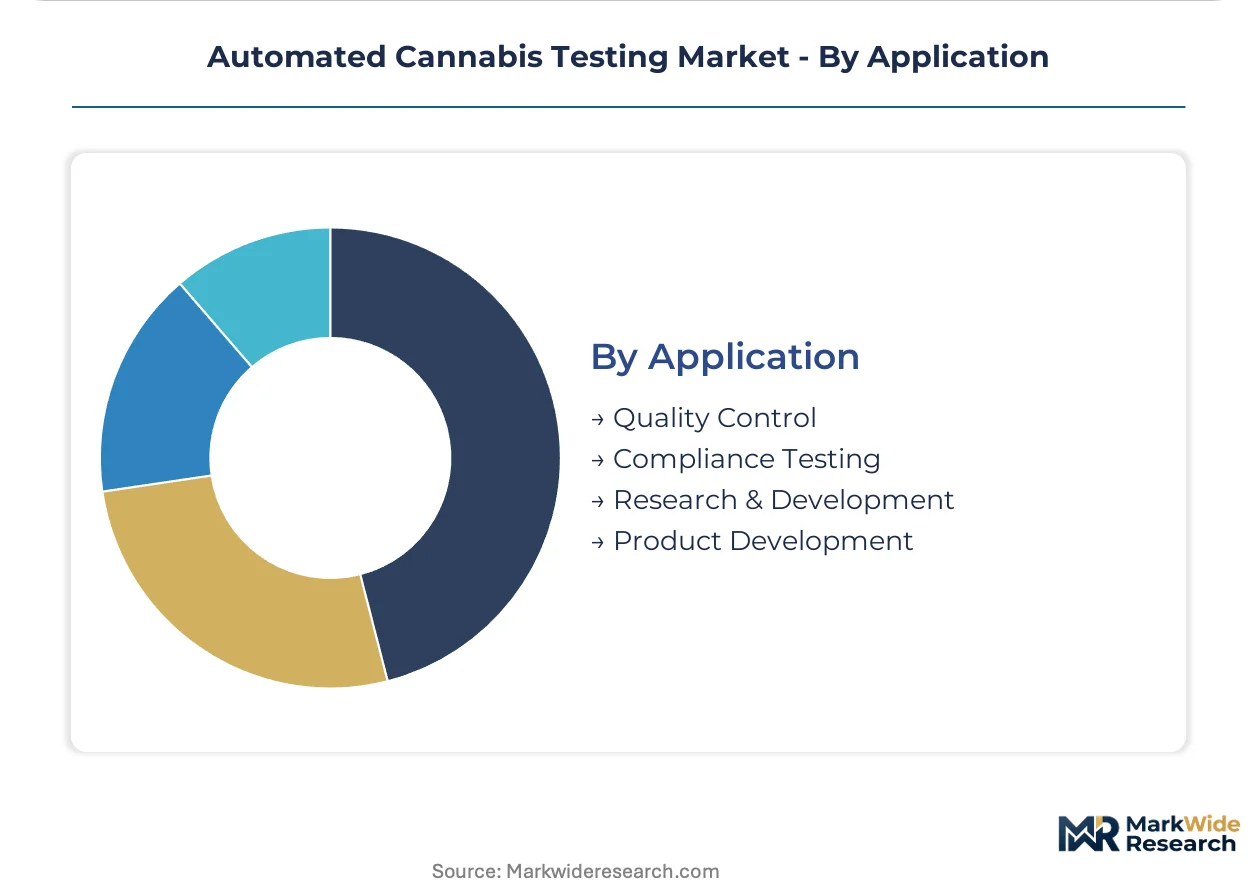
Application:
Application focus determines instrument configuration, with compliance-driven testing demanding validated methods and R&D permitting exploratory approaches.
- Compliance Testing:State-mandated potency, contaminant, and moisture content verification for product release to retail. California's Bureau of Cannabis Control requirements for mycotoxin, heavy metal, and pesticide panels drive standardized method adoption.
- Quality Control:In-process testing during extraction, infusion, and packaging operations to catch deviations before batch completion. Colorado manufacturers integrate at-line near-infrared systems for real-time potency monitoring of ethanol extraction streams.
- Research & Development:Method development for novel delivery formats and stability studies under ICH guidelines.
- Product Development:Formulation optimization for bioavailability, shelf life, and sensory attributes in infused products.
Compliance Testing absorbs the majority of installed base; Product Development is gaining share fastest as pharmaceutical-grade extract demand expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated cannabis testing deployment varies sharply by jurisdiction maturity, with recreational-legal states driving high-throughput installations while medical-only markets prioritize pharmaceutical-grade configurations. Canada and Germany pursue GMP-aligned instrumentation, contrasting with the compliance-volume focus of mature US state programs.
United States
California and Colorado host the largest installed bases of chromatography systems, processing state-mandated batch testing volumes exceeding 500 samples daily. The FDA's enforcement discretion framework for cannabis-derived pharmaceuticals pushes manufacturers toward validated analytical methods. Denver and Los Angeles laboratories concentrate procurement with vendors offering ISO 17025-accredited method packages.
Canada
Health Canada's cannabis regulations require licensed producers to maintain in-house testing capabilities or contract ISO 17025-accredited laboratories. Ontario and British Columbia lead instrument deployment, with Toronto-area facilities investing in mass spectrometry configurations for pesticide and mycotoxin screening. The federal framework enables method reciprocity across provincial boundaries, reducing validation duplication.
Germany
The BfArM cannabis agency establishes GMP testing requirements for pharmaceutical-grade extracts, opening premium instrument configurations for potency and contaminant analysis. Bavaria and North Rhine-Westphalia concentrate cultivation and processing infrastructure, driving demand for validated chromatography-mass spectrometry workflows. German laboratories prioritize ICH guideline alignment over throughput speed.
Switzerland
Swissmedic oversees a regulated medical cannabis program with quality standards approaching pharmaceutical-grade requirements. Basel and Zurich host analytical service providers serving both domestic cultivators and cross-border EU clients. The country's precision instrumentation heritage shapes procurement toward high-sensitivity detection platforms.
Australia
The TGA's medicinal cannabis framework mandates batch release testing by licensed laboratories, with New South Wales and Victoria leading infrastructure investment. Sydney and Melbourne facilities deploy automated sample preparation to meet growing import and domestic production volumes. State-level manufacturing licenses require demonstrated analytical capability as a condition of approval.
Automated Cannabis Testing Market Competitive Environment
Capability concentration sits with chromatography specialists possessing deep method development expertise; scale advantage sits with diversified life science conglomerates offering bundled service contracts. The vendor base stratifies across three tiers: integrated analytical platform providers, focused cannabis application specialists, and regional automation integrators. Dominant competitive moves include service contract unbundling to capture recurring calibration revenue and pre-configured regulatory method packages to accelerate laboratory accreditation timelines.
Among diversified analytical instrumentation providers, Agilent Technologies, Shimadzu Corporation, and Thermo Fisher Scientific occupy positions defined by their chromatography software ecosystems and service infrastructure density in recreational-legal jurisdictions. These companies exemplify the integrated platform archetype, anchoring their market presence through localized application support centers and seed-to-sale traceability integrations rather than hardware differentiation alone.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| Shimadzu Corporation |
| Agilent Technologies, Inc. |
| Merck KGaA |
| Waters Corporation |
| Thermo Fisher Scientific |
| AB SCIEX LLC |
| Medicinal Genomics Corp. |
| Hamilton Company |
| Others |
Value Chain & Pricing Dynamics
Helium sourcing from Qatar and Russia concentrates upstream cost exposure for gas chromatography-dependent laboratories, redirecting margin pools toward service contract unbundling and captive calibration gas procurement downstream. California multi-state operators now negotiate direct helium supply agreements to bypass vendor markups, compressing instrument OEM pricing power into firmware-embedded compliance documentation and LIMS integration bundles.
Pricing Analysis
Long-term service contracts dominate instrument procurement, with laboratories locking in five-year calibration and preventive maintenance agreements to hedge against helium price volatility and chemist scarcity. Price differentiation separates ISO 17025-accredited configurations from non-validated platforms, while volume scale discounts concentrate among multi-state operators processing 1,000-plus samples daily. Cost compression in mid-tier installations is intensifying because smaller independent laboratories face capital intensity barriers exceeding $800,000 per automated line. Commercial testing facilities exhibit highest price sensitivity, whereas pharmaceutical-grade extract manufacturers prioritize GMP-aligned validation over upfront cost.
Supply Chain Analysis
Export-control regimes limiting mass spectrometry component flows from the United States and Germany constrain triple-quadrupole platform availability for non-NATO laboratories. Manufacturing concentrates in Germany, Japan, and the United States for high-precision chromatography systems, while robotic sample handling components draw from Switzerland and South Korea. Single-source vulnerability sits with helium carrier gas, sourced primarily from Qatar and Russia. Distribution runs through authorized distributor networks with localized application support centers in California, Colorado, and Ontario.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with regulatory digitization, as state-mandated seed-to-sale traceability creates niches for LIMS specialists outside dominant chromatography OEM ecosystems.
For Market Incumbents: Entrench position through firmware-embedded compliance documentation that locks laboratories into recurring software update revenue streams. Defend against emerging robotics integrators by consolidating procurement with multi-state operators through standardized LC-MS configurations. Priority lever: localized application support centers in Michigan and Massachusetts to capture accreditation-driven replacement cycles. For New Entrants and Emerging Players: Germany's BfArM GMP requirements represent underpenetrated white space for pharmaceutical-grade extract testing configurations. Target terpenoid profiling services for craft cultivators seeking strain-specific certification through automated solid-phase microextraction. Go-to-market angle: API-first LIMS platforms connecting analytical results to state traceability systems without legacy middleware development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cannabis testing laboratory rollups facing ISO 17025 renewal deadlines and helium cost structure pressure. Long-term viability favors instrument vendors with recurring service revenue exceeding 40% of total mix. Acquisition target archetype: robotics integrators with EPA-validated method packages. Signal to watch: state laboratory accreditation reciprocity agreements compressing validation duplication expenditures.| Strategic Initiative | Industry Significance |
|---|---|
| Seed-to-Sale Software Integration | LIMS platforms embedding directly into state traceability systems capture audit-driven procurement from California and Colorado laboratories. |
| EPA-Validated Method Package Development | Pre-configured pesticide libraries accelerate ISO 17025 accreditation timelines for multi-state operators in Michigan. |
| Helium Supply Agreement Diversification | Direct procurement contracts with Qatari and Russian suppliers bypass vendor markups for high-throughput pesticide screening laboratories. |
| Localized Application Support Center Expansion | On-site method development expertise anchors vendor-customer relationships around uptime guarantees in Massachusetts. |
| Terpenoid Profiling Service Launch | Automated SPME-GC-MS configurations digitize quality differentiation for Colorado craft cultivators seeking strain certification. |
Study Parameters
Operator-level perspectives from laboratory directors, state regulatory compliance officers, chromatography application specialists, and multi-state operator procurement heads anchored the qualitative base. Secondary validation drew from FDA enforcement discretion guidance documents, EPA Method 8270 and 8081 protocols, state department of agriculture accreditation requirements, and ISO 17025 audit reports. Bottom-up instrument shipment data triangulated against top-down laboratory capacity estimates across California, Colorado, Michigan, and Ontario.
Scenario-bracketing framed projections across the analysis window, modeling demand trajectories under varying federal scheduling reform assumptions. Segmentation dimensions included product type (liquid chromatography, mass spectrometry, gas chromatography), end user (commercial laboratories, manufacturers, research institutions), and technology layer (hardware automation, data management solutions). CAGRs derived from regression analysis of historical instrument procurement cycles against state legalization event timelines. Industry-specific inputs incorporated helium price volatility indices and analytical chemist labor market tightness metrics.
Practitioners should monitor EPA method adoption cascades and state accreditation reciprocity negotiations for early signals of procurement cycle compression. Forecasts reflect assumptions of continued regulatory fragmentation absent federal rescheduling. Material shifts in FDA cannabis-derived pharmaceutical approval pathways or helium export restrictions from Qatar would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market