
 Omega 3 Prescription Drugs Market | 2026-2036
Omega 3 Prescription Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Omega 3 Prescription Drugs Market Intelligence
Advanced lipid nanoparticle encapsulation is rewriting how omega-3 active pharmaceutical ingredients achieve bioavailability and stability in prescription formulations. Amarin Corporation plc leverages its specialized icosapent ethyl platform to anchor the high-purity EPA segment with patented manufacturing processes. GSK plc sustains competitive relevance through its cardiovascular portfolio breadth and established hospital formularies across North America and Europe.
Omega 3 prescription drugs are purified ethyl ester or free fatty acid formulations of eicosapentaenoic acid and docosahexaenoic acid, typically dosed at 2-4 grams daily and manufactured through molecular distillation and winterization to achieve pharmaceutical-grade purity exceeding 96% EPA content for triglyceride-lowering indications. The therapy area dimension shows cardiovascular applications dominating current volume, while mental health applications represent the fastest-growing prescriptive category as psychiatrists integrate omega-3 augmentation into mood disorder protocols. Combined formulations of EPA and DHA occupy mature, lower-margin positions compared to single-entity EPA drugs, where pricing power concentrates among manufacturers with New Drug Application exclusivity.
The FDA maintains stringent chemistry, manufacturing, and controls requirements for omega-3 prescription drugs through its Office of Pharmaceutical Quality, while the EMA's Committee for Medicinal Products for Human Use evaluates cardiovascular outcomes data for market authorization across European member states. Health Canada and the TGA apply comparable purity and stability standards that shape import requirements for multinational suppliers. Stakeholders must monitor how evolving pharmacoeconomic assessments from national payers redefine access criteria for premium-priced single-entity formulations versus generic alternatives.
Market Dynamics
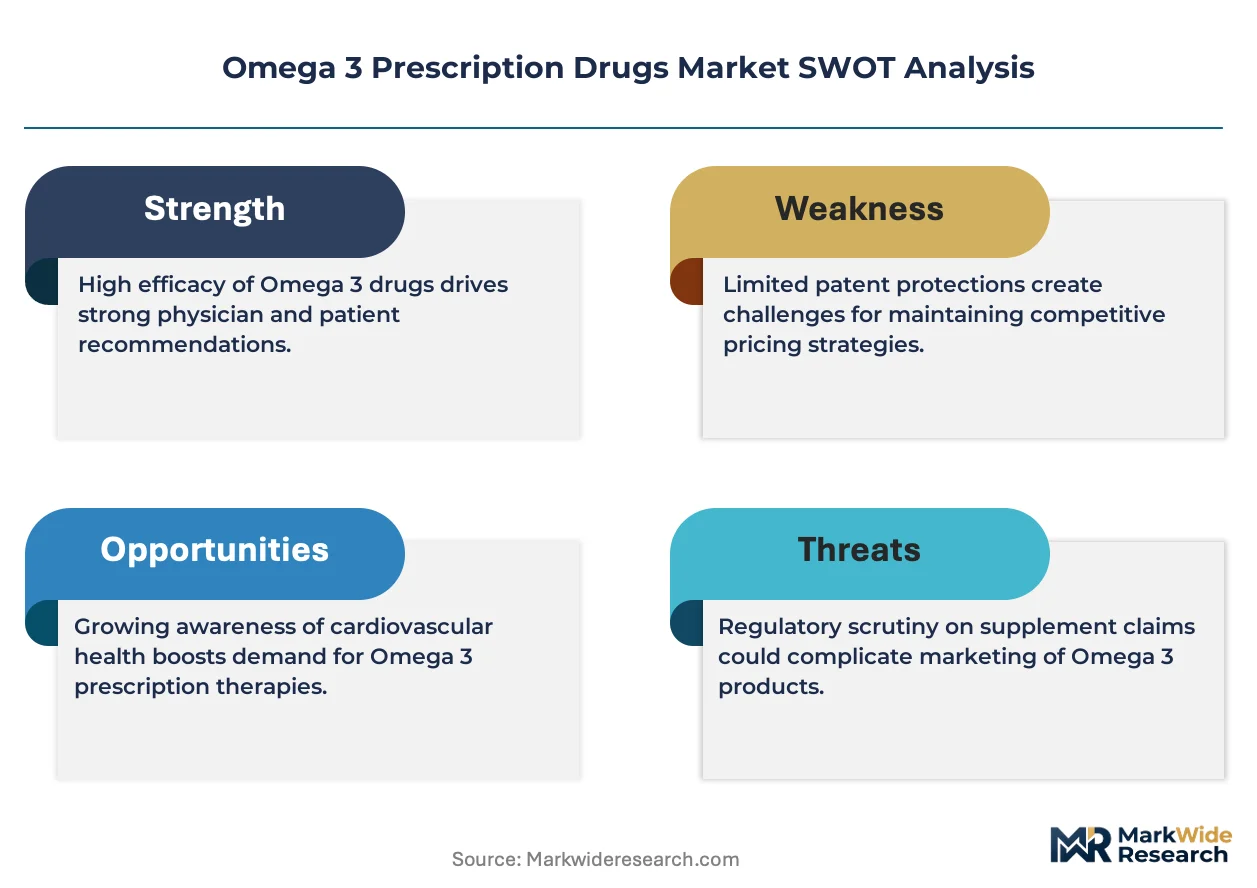
The FDA's tightened cardiovascular efficacy thresholds are compressing commercialization timelines for new omega-3 entrants while concentrating revenue among manufacturers with validated outcomes data and established hospital formularies.
Growth Catalysts
- Hypertriglyceridemia protocols:Cardiology clinics in the United States are integrating prescription EPA therapies into standard-of-care pathways for high-risk patients, expanding addressable patient pools beyond statin-intolerant populations.
- Medicare reimbursement alignment:CMS coverage policies favor clinically validated single-entity formulations over dietary supplements, directing institutional purchasing toward pharmaceutical-grade omega-3 products with New Drug Application status.
- Mental health augmentation:Psychiatric practices are adopting omega-3 co-therapy for mood disorder management, creating prescriptive demand outside traditional cardiovascular indications.
Market Restraints
- Marine source concentration:Wild-caught anchovy and krill fisheries in the Southeast Pacific create geographic supply vulnerability to El Niño disruptions and quota restrictions.
- Ethyl ester manufacturing complexity:Molecular distillation and winterization processes require specialized equipment with limited vendor base, constraining capacity expansion for new market entrants.
- Dietary supplement substitution:Over-the-counter fish oil products at lower price points capture price-sensitive patients outside reimbursed care pathways, fragmenting volume across non-pharmaceutical channels.
Strategic Opportunities
- India outpatient expansion:CDSCO streamlined approval pathways for cardiovascular fixed-dose combinations create regulatory runway for omega-3 inclusion in domestic hypertension protocols.
- Lipid nanoparticle encapsulation:Convergence of nanotechnology with omega-3 formulation science enables bioavailability improvements that support patent extension strategies for mature active pharmaceutical ingredients.
- Telehealth prescription channels:Direct-to-patient platforms are bypassing traditional hospital pharmacy gatekeepers, enabling manufacturer-capture of patient adherence data and refill automation.
Industry Challenges
- Pharmaceutical quality chemistry expertise:FDA Office of Pharmaceutical Quality requirements for forced degradation studies and impurity profiling exceed capabilities at mid-scale contract manufacturing organizations.
- EMA centralized procedure navigation:Committee for Medicinal Products for Human Use cardiovascular outcomes data requirements demand 12-18 month regulatory preparation cycles that strain development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega 3 Prescription Drugs Market |
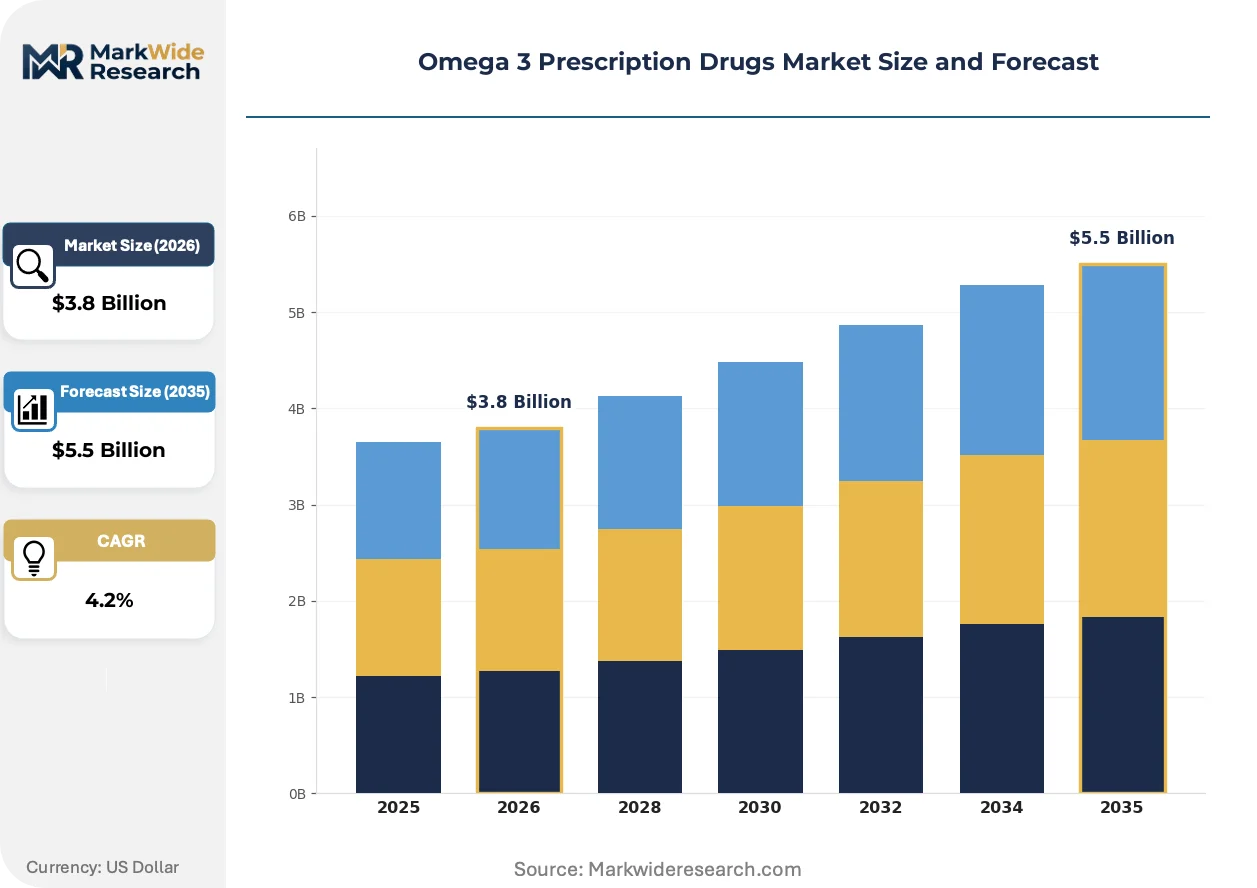
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPA, DHA, Combined Formulations, Nutraceuticals Delivery Mode: Capsules, Softgels, Liquid, Injectable Therapy Area: Cardiovascular, Mental Health, Inflammatory Disorders, Lipid Management End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Amarin Corporation plc, AstraZeneca plc, GSK plc, Dr. Reddy’s Laboratories Ltd., Hikma Pharmaceuticals PLC, Camber Pharmaceuticals, Inc., Teva Pharmaceutical Industries Ltd., Pfizer Inc., Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega 3 Prescription Drugs Market Strategic Shifts & Innovations
Formulation science and regulatory science are converging to redefine competitive differentiation, with bioavailability engineering and outcomes-based authorization becoming primary value levers.
Lipid nanoparticle encapsulation technology is digitizing supply chain traceability through embedded batch-level authentication markers. Cardiology clinics and hospital pharmacies are adopting these smart formulations at accelerating rates to combat counterfeit infiltration. The technology is digitizing compliance documentation workflows while compressing dispensing verification times at institutional points of care.
EMA's evolving pharmacoeconomic assessment frameworks are tightening evidence requirements for cardiovascular market authorization across European member states. Manufacturers must now submit health technology appraisal data alongside traditional safety and efficacy packages. Single-entity EPA drugs with outcomes trial backing command preferential formulary placement in Germany and France versus combined EPA-DHA alternatives.
Hospital procurement consortia are consolidating omega-3 purchasing through centralized therapeutic class negotiations, displacing individual clinic autonomy. Group purchasing organizations in the United States are extracting volume-based rebates that compress net realized prices for manufacturers. This concentration is most visible in integrated delivery networks across Texas and Florida, where three-tier pricing stratification separates premium, standard, and economy formulation tiers.
Omega 3 Prescription Drugs Market Segmentation
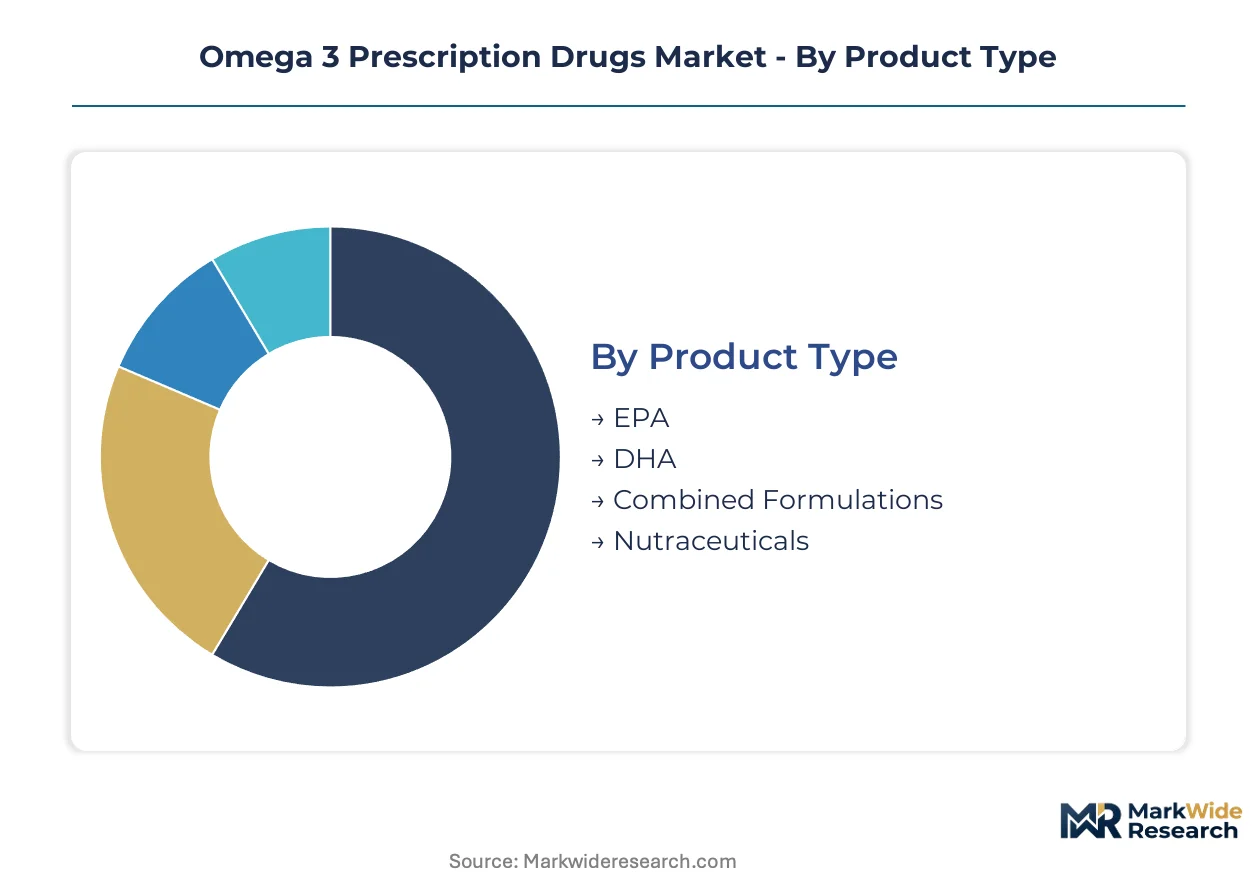
Prescription omega-3 formulations fragment across molecular composition, delivery technology, clinical indication, and care setting. Each dimension carries distinct regulatory pathways, reimbursement profiles, and manufacturing requirements that reshape competitive positioning.
Product Type:
Purification chemistry and fatty acid specificity drive formulation economics and clinical positioning across cardiovascular and neurological applications.
- EPA:Eicosapentaenoic acid formulations achieve pharmaceutical-grade purity exceeding 96% through molecular distillation and winterization processes. Demand concentrates in United States cardiology clinics where Medicare reimbursement policies favor single-entity New Drug Application exclusivity over dietary supplement alternatives.
- DHA:Docosahexaenoic acid products occupy narrower prescriptive niches focused on neurological development and retinal health applications. European psychiatric practices in Germany and France are integrating DHA augmentation into perinatal mood disorder protocols, creating prescriptive volume outside traditional lipid management.
- Combined Formulations:EPA-DHA blends serve cost-sensitive segments with established generic availability.
- Nutraceuticals:Food-grade omega-3 concentrates bypass pharmaceutical quality requirements for wellness positioning.
The dominant share belongs to EPA, while DHA is closing the gap fastest.
Delivery Mode:
Formulation engineering and patient adherence requirements shape route selection across acute and chronic care pathways.
- Capsules:Hard-shell gelatin capsules dominate outpatient dispensing with standardized dosing and stability profiles. Hospital pharmacies in Texas and Florida integrated delivery networks favor capsule formats for automated dispensing compatibility and inventory consolidation.
- Softgels:Gelatin-based soft capsules improve palatability and reduce gastric reflux incidence in long-term therapy. Psychiatric practices prescribing omega-3 augmentation for mood disorders prefer softgel formats to enhance patient compliance with 2-4 gram daily regimens.
- Liquid:Pediatric and dysphagia populations require volumetric dosing flexibility unavailable in solid forms.
- Injectable:Parenteral formulations serve critical care settings with immediate bioavailability requirements.
Capsule formats command institutional procurement volume, though softgels are expanding most quickly in psychiatric co-therapy.
Therapy Area:
Clinical evidence thresholds and regulatory authorization scope determine prescriptive access and pricing power by indication.
- Cardiovascular:Hypertriglyceridemia management anchors prescription volume with FDA-validated outcomes data supporting hospital formulary placement. United States cardiology clinics are integrating EPA therapies into standard-of-care pathways for statin-intolerant high-risk patients.
- Mental Health:Omega-3 augmentation for mood disorders represents the steepest expansion trajectory as psychiatrists incorporate fatty acid co-therapy into depression and bipolar protocols.
- Inflammatory Disorders:Rheumatology applications for omega-3 immunomodulation remain underdeveloped relative to cardiovascular precedents.
- Lipid Management:General dyslipidemia protocols compete with statin-first guidelines in primary care settings.
Cardiovascular indications retain institutional purchasing dominance, though mental health applications are gaining share fastest.
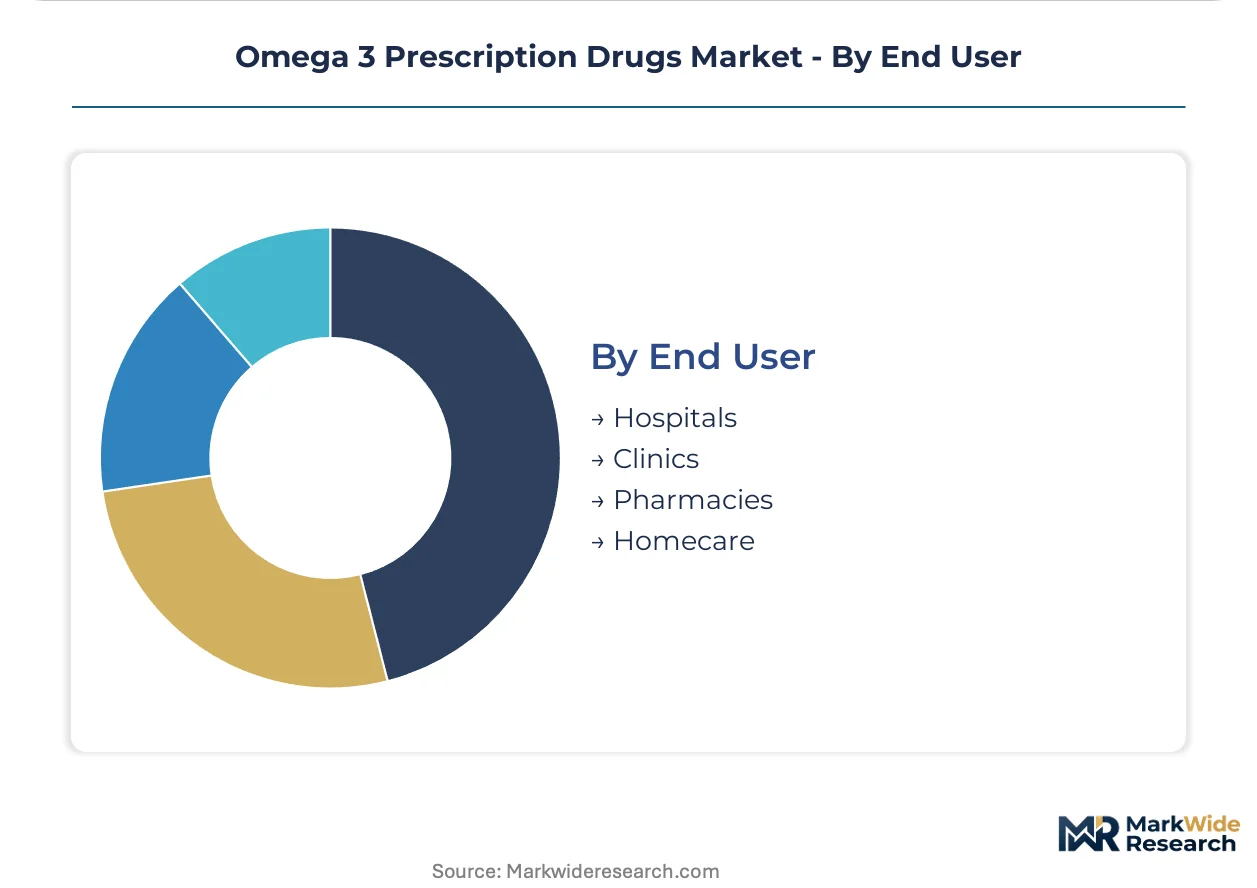
End User:
Procurement concentration and reimbursement mechanics fragment demand across care settings with distinct formulary control structures.
- Hospitals:Integrated delivery networks consolidate omega-3 purchasing through group purchasing organization negotiations. Three-tier pricing stratification separates premium single-entity EPA from standard combined formulations and economy dietary supplement alternatives.
- Clinics:Outpatient cardiology and psychiatric practices drive prescription volume through direct patient relationships.
- Pharmacies:Retail dispensing captures refill adherence and insurance adjudication complexity.
- Homecare:Direct-to-patient platforms bypass traditional pharmacy gatekeepers with telehealth prescription channels.
Hospitals anchor volume through procurement consolidation, while homecare channels are climbing the fastest on telehealth platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia and cardiology clinic networks concentrate omega-3 prescription demand across distinct national healthcare systems. Reimbursement mechanics and regulatory authorization scope fragment competitive access by geography.
United States
Medicare Part D coverage policies favor single-entity EPA formulations with New Drug Application exclusivity over dietary supplement alternatives. FDA's Office of Pharmaceutical Quality enforces stringent chemistry, manufacturing, and controls requirements that shape import standards for multinational suppliers. Texas and Florida integrated delivery networks deploy three-tier pricing stratification across premium, standard, and economy formulation tiers.
Germany
Hospital pharmacies in Bavaria and North Rhine-Westphalia anchor institutional purchasing volume through group purchasing organization negotiations. EMA's Committee for Medicinal Products for Human Use requires health technology appraisal data alongside traditional safety packages for cardiovascular authorization. The Frankfurt-Rhine-Main pharmaceutical cluster concentrates formulation science expertise for lipid nanoparticle encapsulation development.
Japan
PMDA's pharmaceutical evaluation standards prioritize bioequivalence data for omega-3 ethyl ester generics entering the reimbursed market. METI's industrial policy supports domestic molecular distillation capacity for high-purity EPA production. The Kanto region around Tokyo houses specialized contract manufacturing organizations serving cardiovascular drug developers.
India
CDSCO streamlined approval pathways for cardiovascular fixed-dose combinations create regulatory runway for omega-3 inclusion in domestic hypertension protocols. Maharashtra's Mumbai-Pune pharmaceutical corridor hosts active pharmaceutical ingredient manufacturers expanding into prescription omega-3 production. Cardiology clinics in Delhi-NCR and Bengaluru integrate EPA therapies into standard-of-care pathways for statin-intolerant patients.
United Kingdom
NICE pharmacoeconomic assessments determine National Health Service formulary placement for premium-priced single-entity formulations versus generic alternatives. The MHRA applies EMA-aligned purity standards through its post-Brexit regulatory framework. London's hospital procurement consortia consolidate omega-3 purchasing through centralized therapeutic class negotiations.
Omega 3 Prescription Drugs Market Key Industry Players
Channel-controlling players compete with product-specialist players across hospital formulary placement and direct-to-patient prescription channels. The vendor base separates into manufacturers with New Drug Application exclusivity and generic entrants with established chemistry expertise. Three archetypes dominate: single-entity EPA specialists, combined formulation commoditizers, and nanotechnology-enabled formulation innovators. Competitive moves concentrate on lipid nanoparticle patent extension strategies and telehealth platform partnerships for patient adherence capture.
Within the single-entity EPA tier, Amarin Corporation plc anchors high-purity prescription positioning through specialized manufacturing platforms. GSK plc occupies a position reflecting cardiovascular portfolio breadth across North American and European hospital formularies. Among generic-scale suppliers, Teva Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. exemplify chemistry-manufacturing-controls capabilities serving cost-sensitive institutional segments.
| Leading Market Players |
|---|
| Amarin Corporation plc |
| AstraZeneca plc |
| GSK plc |
| Dr. Reddy's Laboratories Ltd. |
| Hikma Pharmaceuticals PLC |
| Camber Pharmaceuticals, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Viatris Inc. |
| Others |
Cost & Logistics Intelligence
The Southeast Pacific anchovy fishery clusters off Peru and Chile concentrate raw material supply for pharmaceutical-grade EPA production, concentrating pricing power among molecular distillation operators with captive access to winterized ethyl ester feedstock. This geographic tethering of omega-3 active pharmaceutical ingredient sourcing to marine biomass availability creates asymmetric cost structures that downstream formulation manufacturers must absorb or hedge through long-term offtake contracts.
Pricing Analysis
Cost-plus contracts with anchovy meal price indexation dominate raw material procurement between Peruvian fishery cooperatives and ethyl ester manufacturers. Price differentiation rests on EPA purity grades and FDA New Drug Application status, with single-entity formulations commanding premium positioning over combined EPA-DHA alternatives. Pricing pressure intensifies as group purchasing organizations extract volume-based rebates from hospital procurement consortia. Retail pharmacy channels exhibit highest price sensitivity, while integrated delivery networks in Texas and Florida tolerate premium tiers for formulary-protected single-entity drugs.
Supply Chain Analysis
Tariff exposure between Peru and the United States dominates supply chain risk planning for omega-3 ethyl ester importers. Manufacturing concentration in Peru, Chile, and India shapes global availability of pharmaceutical-grade feedstock, with molecular distillation capacity expansion constrained by specialized equipment vendor scarcity. Raw material dependencies on wild-caught anchovy biomass, krill oil alternatives, and synthetic omega-3 precursors create input volatility. Distribution runs through hospital pharmacy consortia and group purchasing organization channels that consolidate institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA-validated cardiovascular outcomes data creates durable competitive moats for incumbent manufacturers while constraining new entrant commercialization timelines. The capability gap in pharmaceutical quality chemistry expertise separates contract manufacturing organizations with forced degradation study capabilities from mid-scale competitors.
For Market Incumbents: Build regulatory data moats by commissioning cardiovascular outcomes trials that exceed FDA Office of Pharmaceutical Quality efficacy thresholds for hypertriglyceridemia indications. Anchor hospital formulary placement through integrated delivery network contracts in Texas and Florida that preempt generic substitution. Defend against dietary supplement encroachment by emphasizing Medicare reimbursement advantages of New Drug Application status in cardiology clinic protocols.
For New Entrants and Emerging Players: Build out lipid nanoparticle encapsulation capabilities to differentiate mature EPA active pharmaceutical ingredients through bioavailability claims that support patent extension strategies. Target psychiatric co-therapy segments where omega-3 augmentation for mood disorders lacks established formulary incumbents. Pursue CDSCO streamlined approval pathways in India for cardiovascular fixed-dose combinations that incorporate omega-3 into domestic hypertension protocols.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors nanotechnology-enabled formulation innovators with patent extension runway over commoditized combined EPA-DHA generic manufacturers. Long-term viability hinges on telehealth platform partnerships that capture patient adherence data and automate refill workflows. Watch for EMA pharmacoeconomic assessment framework tightening as inflection indicator for European market authorization difficulty.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcomes data satisfies FDA Office of Pharmaceutical Quality efficacy thresholds for hypertriglyceridemia indications. |
| Regulatory Approval Pathway | CDSCO streamlined pathways enable omega-3 inclusion in Indian cardiovascular fixed-dose combination protocols. |
| Manufacturing Scale-Up | Molecular distillation capacity expansion addresses pharmaceutical-grade ethyl ester supply constraints for statin-intolerant patient populations. |
| Licensing Agreement | Telehealth platform partnerships bypass hospital pharmacy gatekeepers for direct patient adherence capture. |
| Pipeline Diversification | Mental health augmentation indications expand prescriptive demand beyond traditional cardiovascular therapy areas. |
Research Approach
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings for this omega-3 prescription drugs analysis. Conversations with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed competitive positioning assessments. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing were reconciled through iterative triangulation.
Calibration against historical volume data and known regulatory approval timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular composition, delivery technology, therapy area, and care setting, with regional regulatory cluster effects incorporated. CAGRs were derived from epidemiological trend extrapolation and reimbursement policy trajectory analysis. Forecast inputs incorporated Medicare Part D coverage policy evolution and EMA pharmacoeconomic assessment framework development.
The forecast holds incumbent behavior within observed patterns; aggressive moves by nanotechnology-enabled formulation innovators or telehealth platform operators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Oral Anticoagulant Market