
 Middle East and Africa Biguanide Market | 2026-2036
Middle East and Africa Biguanide Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Biguanide Market Foresight
Private hospital networks are unwinding the long-standing grip of government tenders on biguanide procurement across the Middle East and Africa. Sanofi leverages its established insulin and oral antidiabetic portfolio to maintain formulary presence in Gulf Cooperation Council markets. Boehringer Ingelheim anchors its position through integrated diabetes care platforms that pair biguanides with SGLT-2 inhibitors. Novo Nordisk competes by extending its endocrinology expertise into combination therapies that include metformin-based regimens.
Biguanides constitute a class of oral hypoglycemic agents characterized by a guanide-derived molecular structure, with metformin hydrochloride serving as the dominant compound due to its suppression of hepatic gluconeogenesis and improvement of peripheral insulin sensitivity. These agents function primarily to lower blood glucose in Type 2 diabetes patients without stimulating insulin secretion, thereby minimizing hypoglycemic risk. Metformin dominates product type revenue due to decades of clinical validation and WHO Essential Medicines List inclusion, while diabetes management anchors application demand as the fastest-growing segment driven by expanding patient pools. Hospital end users capture the largest volume share, though pharmacy distribution channels are gaining traction as retail networks modernize across urban centers.
South Africa's SAHPRA and Saudi Arabia's SFDA enforce bioequivalence standards that shape which generic metformin formulations gain market access, while Egypt's EDA centralized procurement system directly controls public-sector pricing and supplier selection. The WHO prequalification program and local Good Manufacturing Practice requirements further filter which manufacturers can serve institutional buyers. Stakeholders must monitor regulatory harmonization efforts between Gulf states and sub-Saharan frameworks, as divergent approval timelines create asymmetric competitive windows for first movers.
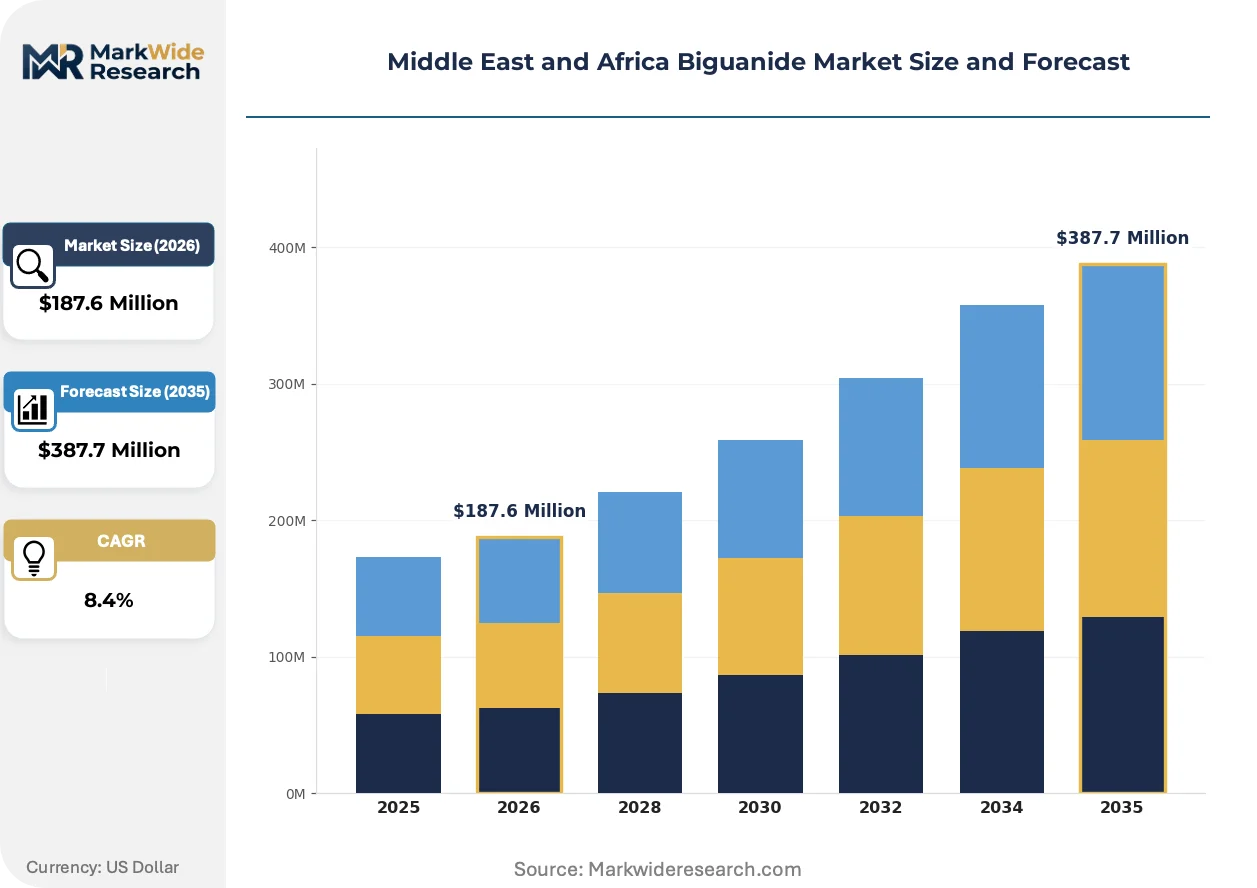
Market Dynamics
Hospital procurement across the Middle East and Africa is unwinding from centralized government tenders toward private institutional buyers, with Saudi Arabia's SFDA bioequivalence enforcement and Egypt's EDA tender system creating divergent competitive access windows.
Growth Catalysts
- Metformin hydrochloride formulation:Decades of clinical validation and WHO Essential Medicines List inclusion sustain physician prescribing confidence across institutional formularies.
- South Africa's biopharmaceutical manufacturing incentives:Local production subsidies attract multinational API sourcing commitments and expand regional supply capacity.
- Type 2 diabetes patient pools:Urbanization-driven metabolic disease prevalence concentrates demand in Egypt, South Africa, and Saudi Arabia's hospital networks.
Market Restraints
- Active pharmaceutical ingredient import dependency:Regional manufacturers rely on Chinese and Indian API suppliers, exposing margins to currency volatility and shipping disruptions.
- SFDA and SAHPRA bioequivalence testing costs:Generic entrants face six-figure certification expenses that filter out smaller domestic producers.
- SGLT-2 inhibitor combination therapies:Boehringer Ingelheim and Novo Nordisk's integrated diabetes platforms threaten standalone biguanide prescribing.
Strategic Opportunities
- Retail pharmacy modernization:Urban pharmacy chains in Dubai, Johannesburg, and Cairo are building direct-to-patient dispensing capabilities.
- Egypt's centralized pharmaceutical tender system:Volume commitments through EDA procurement offer predictable offtake for qualified suppliers.
- Fixed-dose combination development:Pairing metformin with newer antidiabetics aligns with Gulf Cooperation Council hospital formulary preferences.
Industry Challenges
- Pharmacovigilance reporting infrastructure:National regulators lack harmonized adverse event databases, complicating post-market surveillance obligations.
- Cold chain distribution gaps:Extended-release metformin formulations degrade in ambient temperature exposure across last-mile rural networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Biguanide Market |
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $387.7 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Oxybutynin, Buformin, Others Application: Diabetes Management, Polycystic Ovary Syndrome, Weight Loss, Cardiovascular Health End User: Hospitals, Clinics, Pharmacies, Research Institutions Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Sanofi, Boehringer Ingelheim, Novo Nordisk, Bristol-Myers Squibb, Merck & Co., GlaxoSmithKline, Pfizer, Teva Pharmaceuticals, Takeda, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Biguanide Market Shifts & Advancements
Formulation science and procurement digitization are compressing traditional supply hierarchies across Middle Eastern and African diabetes care markets.
Extended-release metformin matrix technologies are decomposing immediate-release prescribing dominance in Gulf Cooperation Council hospital formularies. Saudi Arabian and Emirati endocrinology departments are prioritizing once-daily dosing regimens to improve adherence metrics. This shift is decomposing volume share for conventional tablet suppliers while rewarding polymer-coating specialists with tender access.
SFDA's 2023 bioequivalence guidance revision tightened dissolution profile requirements for generic metformin submissions. Domestic Saudi manufacturers now invest in in vitro-in vivo correlation studies that previously exceeded their technical capabilities. Egyptian and Jordanian exporters face extended approval timelines as they adapt testing protocols to the new standard.
Private hospital networks in Dubai and Cape Town are consolidating pharmaceutical purchasing through group procurement organizations. These entities negotiate directly with manufacturers, bypassing traditional distributor markups that previously captured 15-20 percent of product value. Government hospital systems in Cairo and Riyadh retain centralized tender structures, creating a bifurcated procurement landscape.
Middle East and Africa Biguanide Market Segmentation
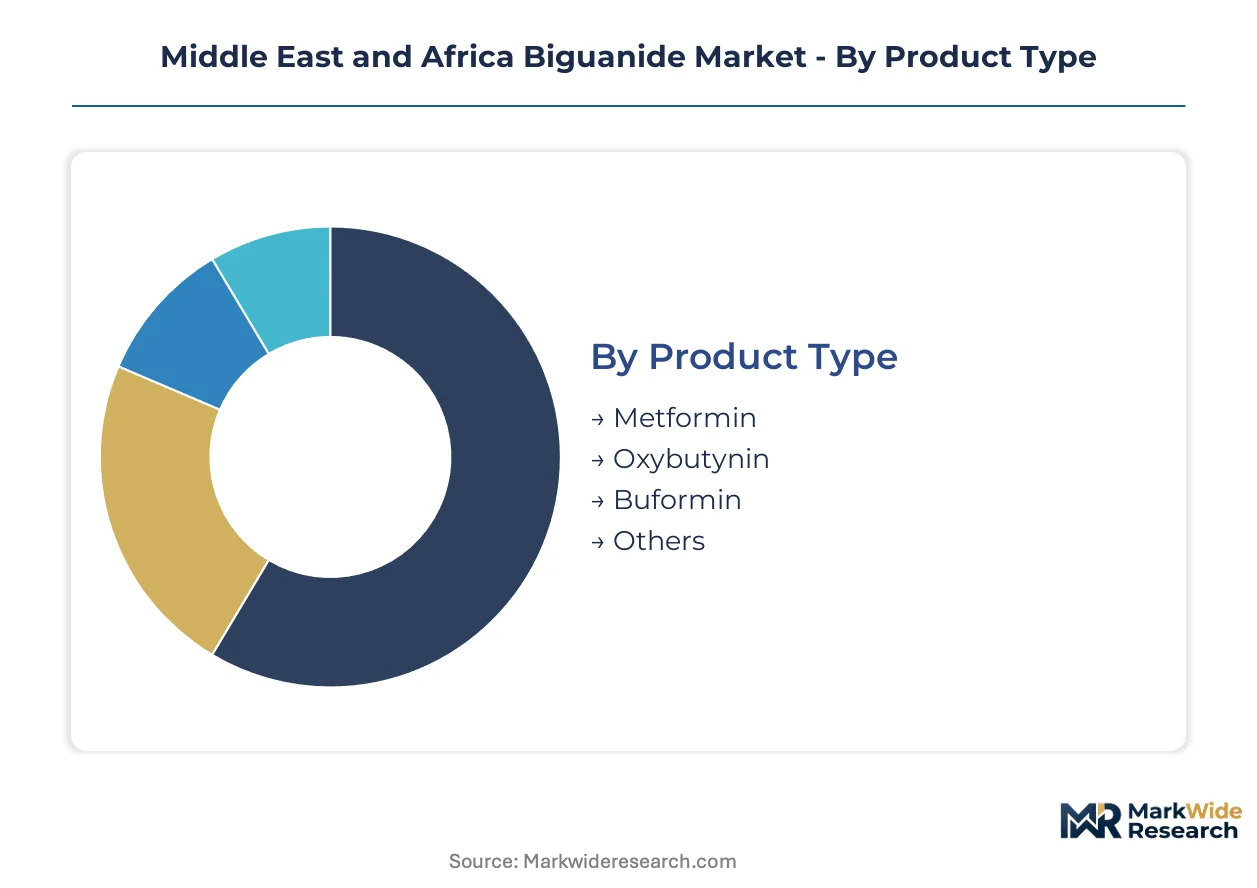
Biguanide procurement patterns across the Middle East and Africa diverge sharply by institutional setting and patient access route. Regulatory frameworks in Egypt, Saudi Arabia, and South Africa create asymmetric entry barriers that reshape competitive positioning within each segment tier.
Product Type:
SFDA bioequivalence enforcement and SAHPRA dissolution standards filter which molecular formulations reach institutional formularies across the region.
- Metformin:The hydrochloride salt dominates prescribing due to WHO Essential Medicines List inclusion and decades of hepatic gluconeogenesis suppression validation. Egyptian hospital tenders and Saudi private networks concentrate procurement of immediate-release and extended-release matrices, with polymer-coating specialists gaining tender access as once-daily regimens displace conventional tablets.
- Oxybutynin:This anticholinergic agent with guanide-derived structure addresses diabetic bladder dysfunction in aging Type 2 populations. South African urology clinics and Gulf Cooperation Council endocrinology departments represent concentrated demand pockets where combination prescribing with standard hypoglycemics is accelerating.
- Buformin:Withdrawn from most developed markets due to lactic acidosis risk, this agent retains niche availability in select North African procurement systems where cost constraints override safety protocols.
- Others:Phenformin and experimental guanide analogs occupy research institution purchasing in Cairo and Johannesburg academic medical centers.
Established volume favors metformin; emerging adoption favors oxybutynin as diabetic complication management expands.
Application:
Patient pool concentration in Egypt, South Africa, and Saudi Arabia determines where each therapeutic indication commands procurement priority.
- Diabetes Management:Type 2 diabetes anchors institutional purchasing across public hospital networks and private facilities. Urbanization-driven metabolic disease prevalence in Cairo, Johannesburg, and Riyadh sustains inpatient and outpatient metformin dispensing at scale.
- Polycystic Ovary Syndrome:Insulin resistance protocols in Gulf Cooperation Council gynecology departments and South African reproductive health clinics drive off-label biguanide utilization for ovarian function modulation.
- Weight Loss:Metformin's appetite-suppressing properties attract bariatric surgery pre-operative protocols in Dubai and Cape Town private hospital networks, though reimbursement remains fragmented.
- Cardiovascular Health:Emerging evidence of endothelial benefit supports formulary inclusion in Saudi tertiary care centers with integrated diabetes-cardiology units.
Diabetes management captures institutional volume dominance; polycystic ovary syndrome prescribing climbs fastest as reproductive endocrinology expands across urban hospital networks.
End User:
Procurement centralization versus decentralization splits the customer landscape between government-controlled and privately negotiated purchasing.
- Hospitals:Public-sector tenders through Egypt's EDA and Saudi government health systems compete with Dubai and Cape Town group purchasing organizations consolidating private network buying. Hospital pharmacies enforce the strictest bioequivalence documentation requirements.
- Clinics:Outpatient diabetes centers in Johannesburg townships and Cairo urban corridors rely on distributor networks with ambient temperature storage limitations affecting extended-release formulation integrity.
- Pharmacies:Retail modernization in Dubai, Cairo, and Johannesburg builds direct-to-patient dispensing capabilities, bypassing traditional hospital-centric distribution.
- Research Institutions:Cairo University teaching hospitals and South African academic medical centers procure for investigator-initiated trials and pharmacokinetic studies.
Hospital procurement retains volume concentration; pharmacy channels gain share fastest as retail networks modernize.
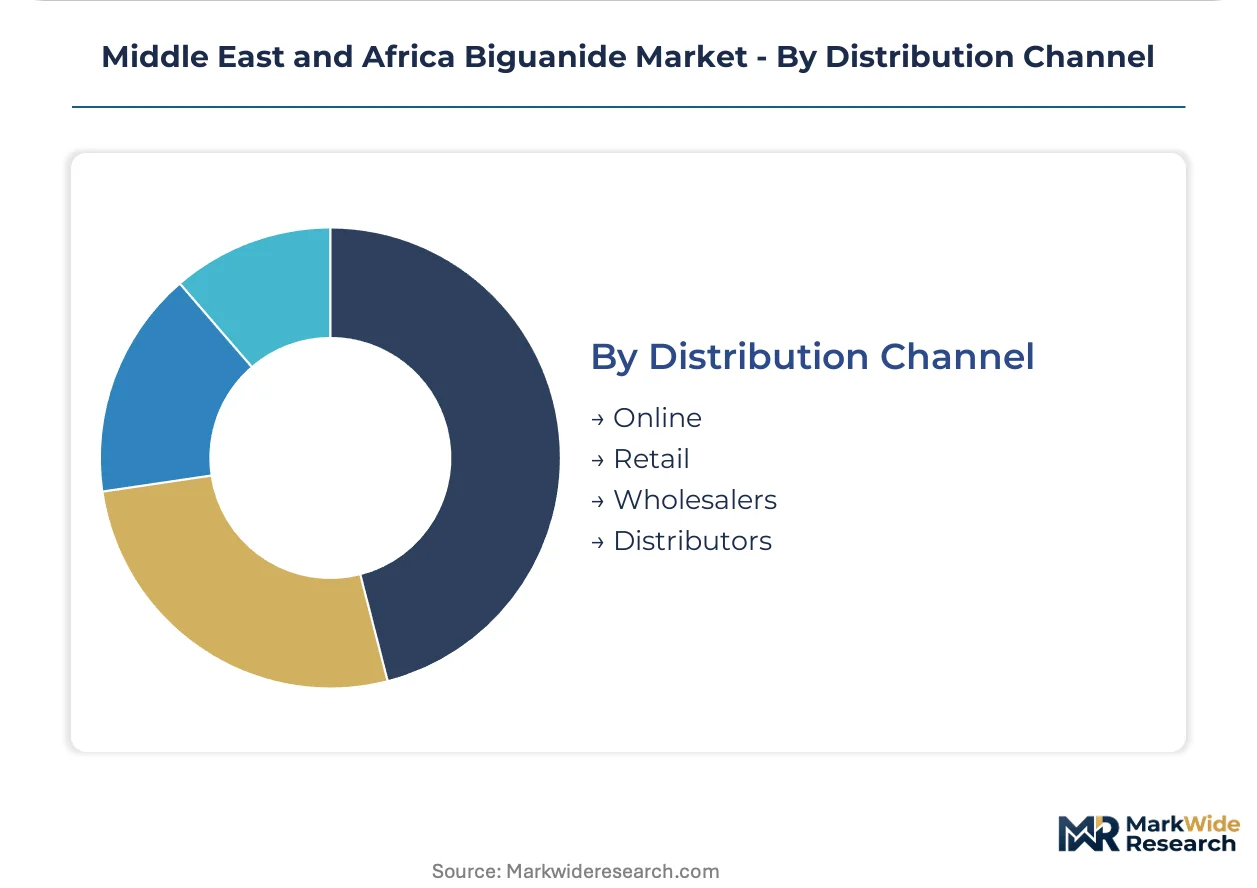
Distribution Channel:
Cold chain capabilities and regulatory documentation intensity determine which logistics pathways serve each customer tier.
- Online:Telemedicine-linked dispensing platforms in UAE and South Africa bypass physical pharmacy visits for stable Type 2 patients on established metformin regimens.
- Retail:Urban pharmacy chains in Dubai, Johannesburg, and Cairo consolidate purchasing power and build direct manufacturer relationships.
- Wholesalers:Regional distributors with ambient and cold storage infrastructure serve institutional buyers across North Africa and the Gulf.
- Distributors:Specialized pharmaceutical logistics providers navigate SAHPRA and SFDA import licensing for multinational suppliers.
Wholesaler networks dominate institutional volume; online channels expand most quickly as telehealth adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturers supply metformin hydrochloride to Egyptian and South African formulators, creating a triangular trade corridor that exposes regional procurement to rupee-dollar volatility and Red Sea shipping disruptions.
Egypt
Cairo's government hospital networks drive metformin procurement through the Egyptian Drug Authority's centralized tender system. The EDA's volume-based supplier selection prioritizes lowest-unit-cost bids, compressing margins for multinational entrants. Giza's pharmaceutical manufacturing zone hosts domestic tablet producers that repackage imported Indian APIs for public-sector distribution.
Saudi Arabia
Riyadh's Ministry of Health hospital clusters anchor Gulf Cooperation Council demand for extended-release metformin formulations. The Saudi Food and Drug Authority's 2023 bioequivalence guidance revision tightened dissolution profile requirements, extending approval timelines for Egyptian and Jordanian exporters. Jeddah's private hospital group purchasing organizations now negotiate directly with polymer-coating specialists for once-daily regimens.
South Africa
Johannesburg's township diabetes clinics and Cape Town's private hospital networks split national metformin consumption between public and institutional channels. The South African Health Products Regulatory Authority enforces dissolution standards that filter generic entrants, while Pretoria's biopharmaceutical manufacturing incentives attract multinational API sourcing commitments. Durban's cold chain logistics hubs struggle with ambient temperature degradation of extended-release matrices in last-mile rural distribution.
United Arab Emirates
Dubai's retail pharmacy modernization and Abu Dhabi's hospital procurement digitization create divergent access pathways for biguanide therapies. The Ministry of Health and Prevention's formulary guidelines favor fixed-dose combinations in tertiary care, while Dubai Healthcare City's telemedicine platforms enable direct-to-patient metformin dispensing for stable Type 2 patients.
Nigeria
Lagos's urban hospital networks and Kano's northern distributor corridors concentrate Nigerian metformin demand amid fragmented regulatory oversight. The National Agency for Food and Drug Administration and Control's import licensing creates bottlenecks at Apapa port, while Ikeja's pharmaceutical wholesalers maintain ambient storage facilities that compromise extended-release formulation integrity.
Middle East and Africa Biguanide Market Competitive Landscape
Player mix skews toward multinational pharmaceutical conglomerates with established insulin portfolios extending into oral hypoglycemic adjacencies. Market structure concentrates around three strategic tiers: research-intensive innovators with endocrinology platforms, generic manufacturers with bioequivalence certification capabilities, and regional distributors with cold chain infrastructure. Dominant competitive moves include fixed-dose combination development pairing metformin with newer antidiabetics, and backward integration into active pharmaceutical ingredient sourcing to offset import dependency.
Among research-intensive innovators, Sanofi, Boehringer Ingelheim, and Novo Nordisk exemplify the endocrinology platform archetype. Sanofi leverages its established insulin portfolio to maintain Gulf Cooperation Council formulary presence. Boehringer Ingelheim anchors positioning through integrated diabetes care platforms. Novo Nordisk extends endocrinology expertise into combination therapies. These three represent the premium-tier competitive vector where clinical validation and physician relationships determine access.
| Leading Market Players |
|---|
| Sanofi |
| Boehringer Ingelheim |
| Novo Nordisk |
| Bristol-Myers Squibb |
| Merck & Co. |
| GlaxoSmithKline |
| Pfizer |
| Teva Pharmaceuticals |
| Takeda |
| Others |
Supply & Pricing Matrix
Ninety-day inventory buffers at Egyptian Drug Authority warehouses concentrate procurement leverage among lowest-unit-cost bidders, compressing margins for multinational entrants while rewarding domestic formulators with Indian API sourcing relationships. This lead-time architecture shapes pricing power across the Middle East and Africa biguanide market, where tender systems and private hospital networks operate on divergent cost structures.
Pricing Analysis
Extended-release versus immediate-release metformin formulations command a technology-generation pricing gap that stratifies procurement across Gulf Cooperation Council hospital formularies. Three-tier pricing structure across originator, bioequivalent generic, and unbranded commodity levels anchors the dominant model, with SFDA dissolution certification and SAHPRA bioequivalence documentation serving as primary price differentiation drivers. Pricing pressure stems from Egypt's EDA volume-based tender system that prioritizes lowest-unit-cost bids, compressing margins across all tiers. Public-sector hospital networks exhibit highest price sensitivity, while Dubai's private group purchasing organizations demonstrate lowest sensitivity due to adherence-focused formulary preferences.
Supply Chain Analysis
Red Sea shipping lane congestion and container availability constraints at Jeddah and Durban ports elevate inbound logistics costs for Indian API shipments destined for Egyptian and South African formulators. Supply concentrates in India for active pharmaceutical ingredients, China for chemical intermediates, and domestic manufacturing zones in Egypt and South Africa for finished dosage forms. Raw material dependencies center on metformin hydrochloride API, polymer coating excipients for extended-release matrices, and blister packaging materials. Single-source vulnerability to Indian API suppliers creates structural supply chain risk. Distribution runs through regional wholesalers with ambient and cold storage infrastructure serving institutional buyers, while retail pharmacy chains in Dubai and Johannesburg build direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
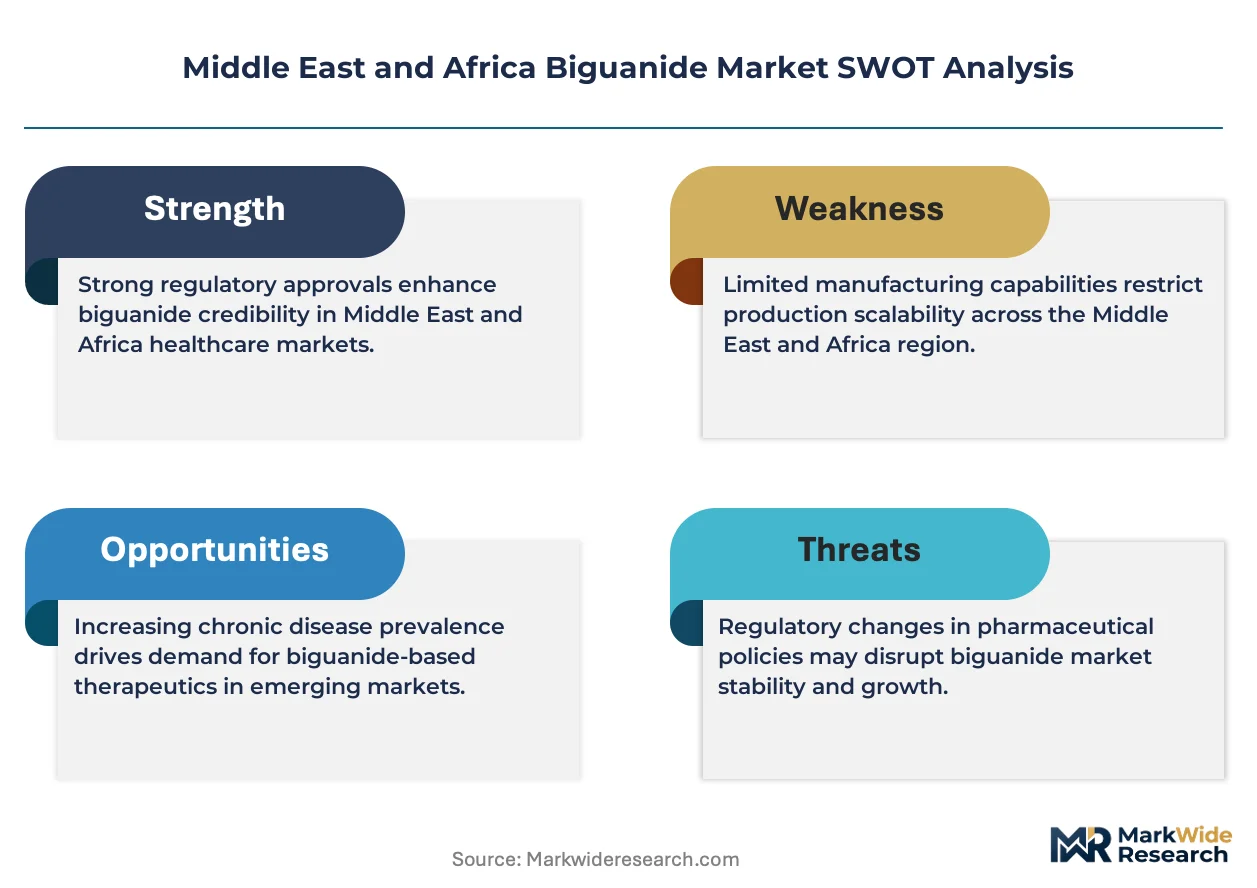
Procurement fragmentation between centralized government tenders and private hospital networks creates multiple entry niches across the Middle East and Africa biguanide market. Urbanization-driven Type 2 diabetes prevalence in Cairo, Johannesburg, and Riyadh sustains demand dispersion that rewards specialized positioning.
For Market Incumbents: Fortify formulary presence through backward integration into API sourcing and polymer-coating capabilities for extended-release formulations. Boehringer Ingelheim and Novo Nordisk's integrated diabetes platforms threaten standalone biguanide prescribing; defensive moves require fixed-dose combination development pairing metformin with SGLT-2 inhibitors and direct engagement with Dubai and Cape Town group purchasing organizations to bypass distributor markups. For New Entrants and Emerging Players: SFDA bioequivalence fast-track pathways for domestic Saudi manufacturers present the most penetrable regulatory entry point, as 2023 guidance revisions filter out Egyptian and Jordanian exporters lacking in vitro-in vivo correlation capabilities. Target South Africa's biopharmaceutical manufacturing incentives for API sourcing commitments and local production subsidies. Go-to-market success hinges on polymer-coating specialization for once-daily regimens preferred in Gulf Cooperation Council adherence protocols. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease infrastructure play because urbanization and metabolic disease prevalence sustain institutional demand regardless of therapeutic innovation cycles. Acquisition targets should center on generic manufacturers with SAHPRA and SFDA bioequivalence certification capabilities and established cold chain distribution infrastructure. The signal to watch is harmonization progress between Gulf states and sub-Saharan regulatory frameworks, which would compress asymmetric competitive windows and consolidate procurement leverage.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | Pairing metformin with SGLT-2 inhibitors aligns with MOHAP formulary preferences in UAE tertiary care. |
| Backward Integration into API Sourcing | Captive supply of metformin hydrochloride offsets rupee-dollar volatility and Red Sea shipping disruptions. |
| Polymer-Coating Specialization | Extended-release matrix capabilities unlock tender access as Saudi hospitals prioritize once-daily regimens. |
| Group Purchasing Organization Partnerships | Direct negotiation with Dubai and Cape Town private networks bypasses 15-20 percent distributor markups. |
| Bioequivalence Certification Investment | SFDA and SAHPRA dissolution documentation filters generic entrants and creates sustainable competitive moats. |
Research Methodology
Cross-validation between hospital procurement databases and regulatory filing records anchors the qualitative findings in this analysis. Primary interviews with formulary directors at Saudi Ministry of Health hospital clusters, Egyptian Drug Authority tender officials, and South African pharmacy procurement managers combined with secondary validation through SFDA guidance documents, SAHPRA bioequivalence standards, and WHO prequalification records. Bottom-up patient pool modeling and top-down pharmaceutical expenditure triangulation ensure coverage consistency across the analysis window.
Sensitivity analysis on API import cost assumptions and currency volatility bands frames the forecast uncertainty. The analytical framework segments by product type, application, end user, and distribution channel across the projection horizon, with dosage form and regional regulatory cluster as additional modeled dimensions. CAGRs derive from patient pool expansion rates, tender volume commitments, and retail pharmacy modernization trajectories. Key forecast inputs include urbanization-driven diabetes prevalence curves and bioequivalence certification timelines.
The analysis sits within stated boundaries; outcomes outside sustained government health initiative funding and stable API trade flows would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization progress, cold chain infrastructure investment, and chronic disease management prioritization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Global Divalproex Sodium Market