
 Tumor Necrosis Factor Alpha Inhibitors Market | 2026-2036
Tumor Necrosis Factor Alpha Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Necrosis Factor Alpha Inhibitors Market Analytics
Project finance structures for biologics manufacturing facilities are rewriting capital requirements for new entrants in the TNF alpha inhibitor space. AbbVie Inc. leverages its Humira infrastructure to sustain manufacturing scale across multiple therapy areas. Amgen Inc. anchors its position through vertical integration into protein production and purification operations. Johnson & Johnson Services Inc. competes via Janssen Biotech's specialized immunology channel control in hospital systems.
Tumor necrosis factor alpha inhibitors are recombinant proteins or monoclonal antibodies that bind soluble TNF-alpha or its cell-surface receptors, blocking pro-inflammatory cytokine signaling in autoimmune pathologies; these therapies require cold-chain distribution and parenteral administration due to protein degradation in gastric environments. Adalimumab and infliximab occupy the mature core of the product type landscape, while etanercept faces accelerating biosimilar displacement. The subcutaneous delivery mode leads in patient convenience metrics, though intravenous administration retains preference in hospital-based induction protocols for inflammatory bowel disease.
The FDA governs biologics licensing through the Public Health Service Act and 351(k) biosimilar pathways, while the EMA's Committee for Medicinal Products for Human Use coordinates centralized marketing authorization across EU member states. These frameworks determine reference product exclusivity periods, interchangeability standards, and post-market pharmacovigilance obligations that directly shape competitive entry timing. Stakeholders must monitor evolving interchangeability designation criteria and state-level pharmacy substitution laws that will determine biosimilar uptake velocity.
Market Dynamics
Biosimilar entry timelines are compressing reference product exclusivity windows and forcing originators to reconfigure manufacturing scale and channel economics before patent cliffs arrive.
Growth Catalysts
- EMA centralized marketing authorization:The EMA's Committee for Medicinal Products for Human Use accelerates cross-border commercialization for biosimilar sponsors, reducing regulatory duplication costs across EU member states.
- Subcutaneous formulation preference:Rheumatology clinics and patient advocacy groups favor self-administered delivery modes that reduce infusion center dependency and improve adherence metrics in chronic autoimmune management.
- Specialty pharmacy network density:United States distribution infrastructure concentrates in limited-distribution channels that capture patient data and manage prior authorization workflows for payers.
Market Restraints
- Cold-chain infrastructure requirements:Protein stability demands maintain refrigerated distribution from manufacturing through patient administration, elevating logistics costs and limiting rural access.
- Interchangeability designation uncertainty:The FDA's evolving standards for automatic pharmacy substitution create payer hesitation and slow biosimilar uptake velocity in commercial insurance formularies.
- Reference product litigation delays:Patent thickets surrounding cell culture methods and purification processes extend market exclusivity through settlement negotiations rather than scientific merit.
Strategic Opportunities
- Japan's aging autoimmune population:METI and PMDA streamlined review pathways for biosimilars create favorable entry conditions in a market with concentrated hospital procurement and limited generic competition.
- Inflammatory bowel disease induction protocols:Intravenous administration retains hospital capture for severe Crohn's and ulcerative colitis cases, creating service-based revenue streams beyond drug margin alone.
- ISO 13485 quality management convergence:Medical device and biologics manufacturers adopting unified quality standards reduce audit burden and accelerate multi-product facility certifications.
Industry Challenges
- Cell line development expertise scarcity:Mammalian expression system optimization requires rare combinations of molecular biology and bioprocess engineering skills that concentrate in Boston and Basel talent pools.
- Comparative immunogenicity study design:EMA and FDA divergent expectations for switching studies and extrapolation indications force redundant clinical investment for multi-territory filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Necrosis Factor Alpha Inhibitors Market |
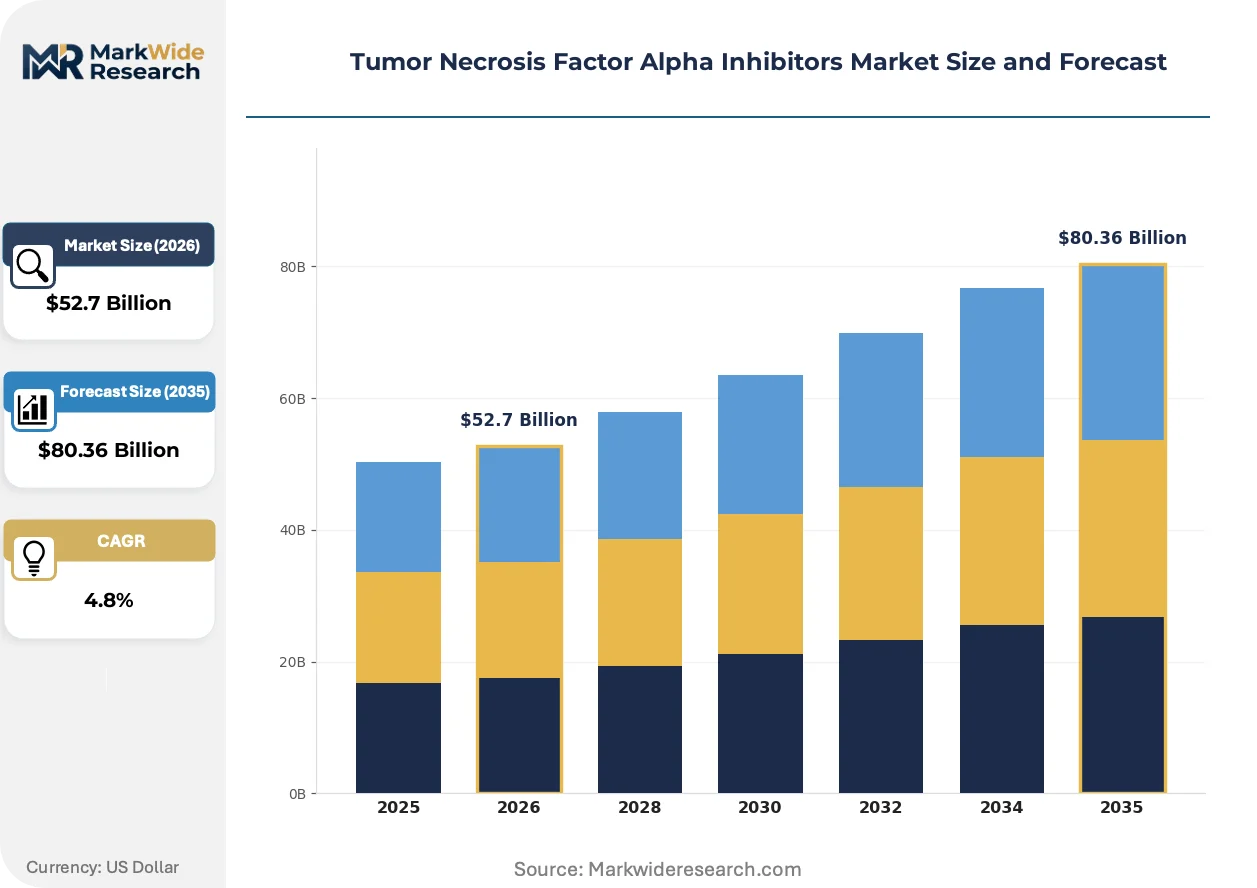
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adalimumab, Infliximab, Etanercept, Golimumab Therapy Area: Rheumatoid Arthritis, Psoriasis, Ankylosing Spondylitis, Inflammatory Bowel Disease Delivery Mode: Subcutaneous, Intravenous, Oral, Intramuscular End User: Hospitals, Specialty Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | AbbVie Inc., Amgen Inc., Johnson & Johnson Services Inc., Pfizer Inc., UCB S.A., Novartis International AG, Merck & Co. Inc., Janssen Biotech, Boehringer Ingelheim Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Necrosis Factor Alpha Inhibitors Market Evolving Landscape
Manufacturing technology and regulatory science are converging to redefine competitive moats in protein therapeutics, with differentiation shifting from molecular design to supply chain reliability and real-world evidence generation.
Continuous bioprocessing is migrating from stainless-steel batch fermentation to single-use perfusion systems that reduce facility footprint and enable modular capacity expansion. CDMOs in Switzerland and Singapore are adopting these platforms to serve mid-size biotech sponsors lacking captive manufacturing. The structural consequence compresses capital requirements for new entrants and fragments production geography away from legacy bulk biologics hubs.
The FDA's 351(k) biosimilar pathway and EMA's biosimilar guidance revision are tightening analytical similarity thresholds while expanding indication extrapolation criteria. Sponsors must now demonstrate physicochemical equivalence through advanced mass spectrometry and surface plasmon resonance before clinical testing. European biosimilar developers benefit from centralized scientific advice that harmonizes development programs across member state regulators.
Hospital formulary committees are consolidating vendor relationships and demanding integrated outcomes contracts that tie reimbursement to sustained clinical response. United States integrated delivery networks now require biosimilar sponsors to provide real-world evidence platforms and patient support services as table stakes for access. This behavioral shift concentrates procurement authority in pharmacy benefit managers and specialty distributors with data integration capabilities.
Tumor Necrosis Factor Alpha Inhibitors Market Segmentation
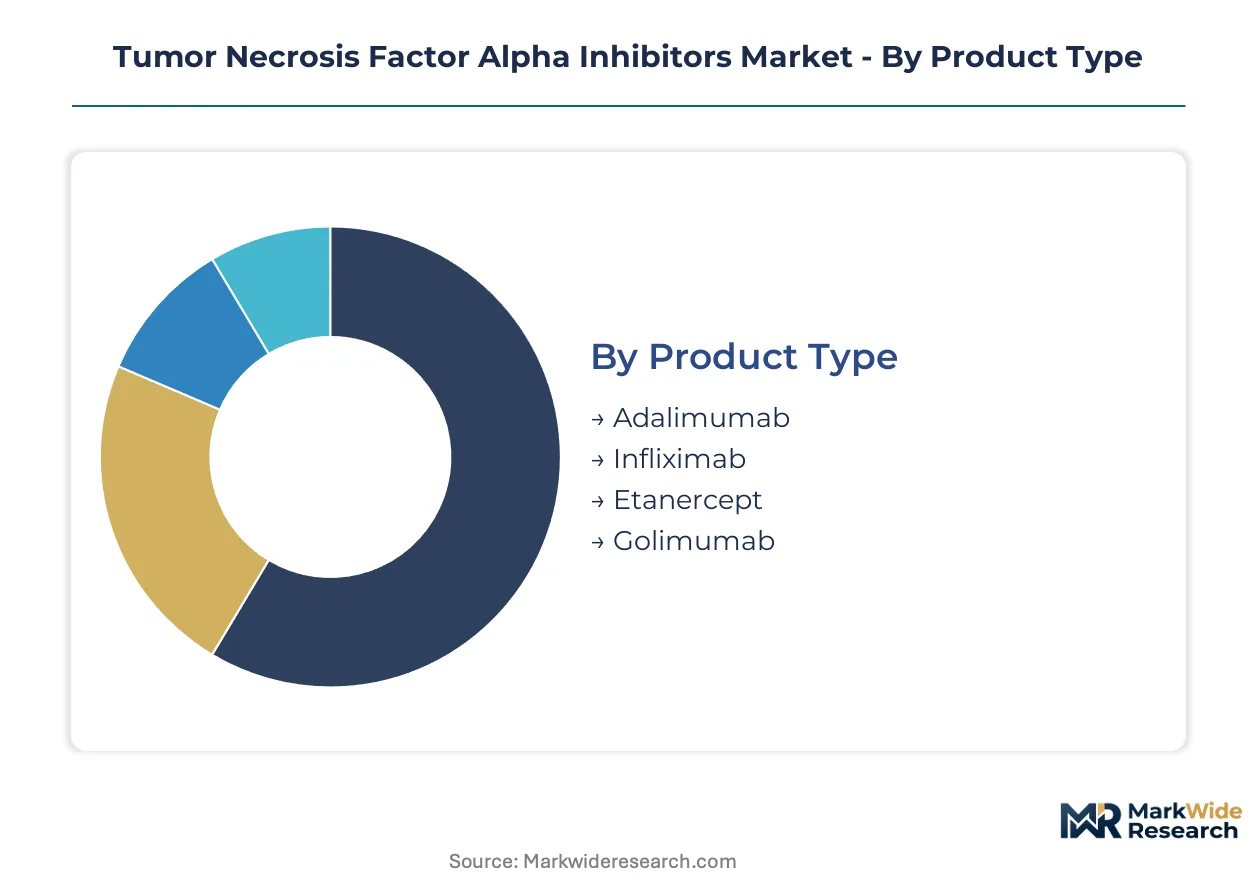
Tumor necrosis factor alpha inhibitors fragment across molecular origin, clinical indication, and care setting. Each dimension carries distinct reimbursement pathways, cold-chain requirements, and competitive entry barriers that shape portfolio prioritization.
Product Type:
Cost tier stratification separates originator biologics from biosimilar entrants, with manufacturing scale and litigation exposure determining margin structure.
- Adalimumab:Fully human monoclonal antibody targeting TNF-alpha with subcutaneous and intravenous formulations. United States specialty pharmacy networks capture the majority of volume as biosimilar substitution laws vary by state. Patent litigation settlements have compressed exclusivity windows ahead of FDA interchangeability designations.
- Infliximab:Chimeric monoclonal antibody requiring intravenous infusion in hospital or infusion center settings. Japanese hospital procurement concentrates demand for severe inflammatory bowel disease induction protocols where payer reimbursement favors institutional administration.
- Etanercept:TNF receptor fusion protein with established subcutaneous delivery. European biosimilar competition accelerates price erosion as EMA centralized authorizations enable rapid multi-country launches.
- Golimumab:Human monoclonal antibody with monthly subcutaneous dosing. Rheumatology clinics favor the reduced injection frequency for patient adherence in chronic maintenance therapy.
Adalimumab commands the established base. The steepest expansion runs through infliximab biosimilars capturing hospital formulary switches.
Therapy Area:
Application severity determines dosing intensity, monitoring requirements, and the relative preference for self-administration versus supervised infusion.
- Rheumatoid Arthritis:Chronic autoimmune joint destruction requiring lifelong TNF inhibition. United States rheumatology practices drive volume through prior authorization workflows managed by specialty pharmacies.
- Psoriasis:Dermatologic indication with visible symptom burden driving patient preference for rapid onset therapies. European markets show higher biosimilar penetration due to centralized tendering for biologics.
- Ankylosing Spondylitis:Axial spondyloarthritis affecting younger male demographics with high functional disability scores. Physical therapy integration in German rehabilitation centers shapes combination therapy protocols.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis requiring induction dosing in hospital settings. Japanese gastroenterology societies maintain conservative biosimilar switching guidelines that slow uptake velocity.
Rheumatoid arthritis anchors prescription volume. Inflammatory bowel disease claims the fastest share gain as hospital-based protocols expand biologic eligibility criteria.
Delivery Mode:
Patient autonomy and care setting economics create divergent preference structures across chronic maintenance versus acute induction scenarios.
- Subcutaneous:Self-injection devices enabling home administration with cold-chain stability requirements. United States patient copay assistance programs concentrate demand in this modality for commercial insurance populations.
- Intravenous:Hospital or infusion center administration with higher per-dose reimbursement and professional service revenue capture. European day-clinic networks optimize throughput for inflammatory bowel disease induction.
- Oral:Small molecule TNF pathway modulators in development for gastric-stable delivery. Clinical trial programs face bioavailability challenges that limit near-term commercial relevance.
- Intramuscular:Alternative parenteral route with limited current adoption in approved TNF inhibitors. Pharmacokinetic profiles show slower absorption kinetics that may suit specific patient populations.
Subcutaneous formulations dominate patient-preferred prescribing. Intravenous administration retains institutional capture where severity mandates supervised monitoring.
End User:
Customer type concentration reflects reimbursement complexity, cold-chain infrastructure, and the balance between clinical oversight and patient convenience.
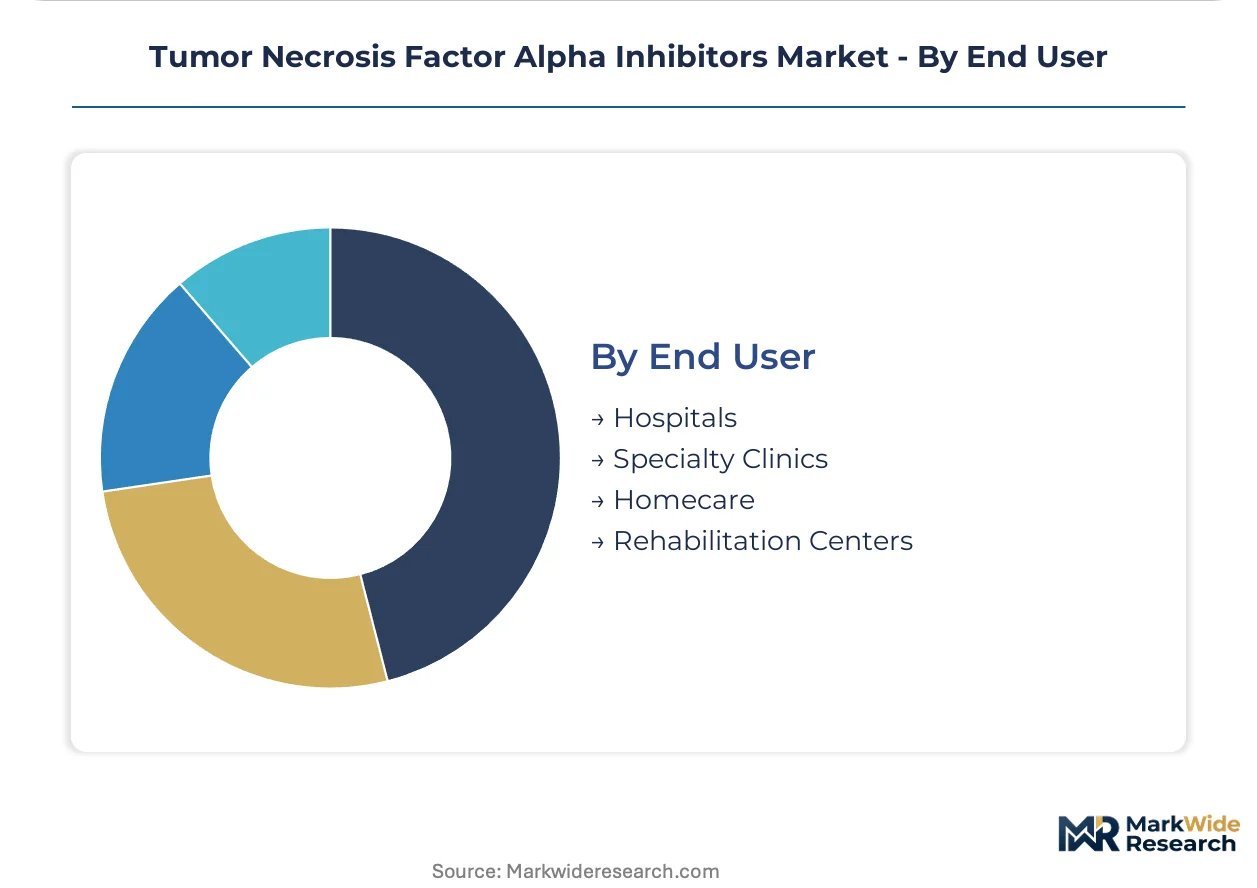
- Hospitals:Institutional purchasers managing inpatient induction protocols and infusion center operations. Japanese diagnosis procedure combination reimbursement creates fixed payment incentives for efficient biologic utilization.
- Specialty Clinics:Rheumatology and gastroenterology practices with in-office infusion capabilities and biologic coordinator staffing. United States integrated delivery networks consolidate vendor relationships through pharmacy benefit manager intermediaries.
- Homecare:Self-administration supported by nursing visits and telehealth monitoring. German homecare nursing associations negotiate device training and adverse event reporting responsibilities.
- Rehabilitation Centers:Post-acute settings managing functional recovery in ankylosing spondylitis and psoriatic arthritis. European occupational therapy integration shapes combination biologic-physical therapy protocols.
Hospitals anchor the reimbursement infrastructure. Specialty clinics are climbing fastest as limited-distribution networks concentrate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy divergence across major pharmaceutical markets is redrawing competitive entry sequencing for TNF alpha inhibitor sponsors. FDA interchangeability standards and EMA centralized authorization create divergent development investment profiles. Japanese procurement centralization through diagnosis procedure combination payments accelerates hospital formulary consolidation.
United States
Specialty pharmacy networks capture patient data and manage prior authorization workflows for commercial payers. FDA 351(k) biosimilar pathways and evolving interchangeability designation criteria shape substitution velocity across state-level pharmacy laws. The Greater Boston biotech cluster concentrates cell line development expertise and mammalian expression system optimization talent.
Germany
Centralized tendering for biologics through sickness funds accelerates biosimilar price erosion in rheumatology and dermatology indications. EMA Committee for Medicinal Products for Human Use coordinates marketing authorization that German regulators implement through national reimbursement negotiations. The Rhine-Main region anchors European distribution infrastructure for cold-chain biologics logistics.
Japan
An aging autoimmune population and concentrated hospital procurement create favorable entry conditions for biosimilar sponsors. METI and PMDA streamlined review pathways reduce regulatory duplication for multi-product facility certifications. The Kanto region dominates biologics manufacturing scale with specialized immunology channel control in university hospital systems.
Switzerland
CDMO adoption of single-use perfusion systems enables modular capacity expansion for mid-size biotech sponsors lacking captive manufacturing. Swissmedic coordinates with EMA centralized procedures while maintaining distinct national pricing negotiations. The Basel biotech cluster concentrates rare combinations of molecular biology and bioprocess engineering skills.
United Kingdom
NHS England biosimilar switching guidelines and national procurement frameworks compress reference product exclusivity windows ahead of patent cliffs. MHRA post-Brexit regulatory autonomy diverges from EMA centralized authorization on extrapolation indication criteria. The Cambridge-London corridor anchors real-world evidence generation capabilities for integrated outcomes contracts.
Tumor Necrosis Factor Alpha Inhibitors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent access models. The market structure consolidates around originator biologics manufacturers with established cold-chain infrastructure and biosimilar sponsors leveraging CDMO partnerships for manufacturing scale. Two strategic archetypes dominate: vertically integrated pharmaceutical conglomerates with multi-therapy area portfolios, and focused biotech sponsors pursuing indication-specific development programs. Competitive moves concentrate on M&A for cell line development capabilities and strategic partnerships for real-world evidence platform access.
Among vertically integrated pharmaceutical conglomerates, AbbVie Inc., Amgen Inc., and Johnson & Johnson Services Inc. exemplify distinct competitive positioning. AbbVie Inc. represents the infrastructure-leveraging archetype, sustaining manufacturing scale across multiple therapy areas through established biologics platforms. Amgen Inc. anchors the upstream-control archetype, with protein production and purification operations concentrated in captive facilities. Johnson & Johnson Services Inc. occupies the channel-dominance position through specialized immunology control in hospital systems, reflecting the Janssen Biotech subsidiary structure.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amgen Inc. |
| Johnson & Johnson Services Inc. |
| Pfizer Inc. |
| UCB S.A. |
| Novartis International AG |
| Merck & Co. Inc. |
| Janssen Biotech |
| Boehringer Ingelheim Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
The Basel biotech cluster's mammalian expression system capacity governs originator biologics pricing power, while Singapore CDMO expansion compresses biosimilar entry costs and fragments downstream margin capture across regional hospital procurement networks.
Pricing Analysis
Certification level (FDA interchangeability versus EMA biosimilar authorization) creates the primary spread between originator and follow-on biologics, with three-tier pricing structure across premium originator, authorized biosimilar, and unbranded interchangeable tiers. Price differentiation hinges on cold-chain reliability guarantees and real-world evidence packages demanded by United States integrated delivery networks. Cost compression in the biosimilar tier is intensifying because EMA centralized authorizations enable rapid multi-country launches. Hospital formulary committees show highest price sensitivity, while specialty pharmacy networks with data integration capabilities command premium capture.
Supply Chain Analysis
Lonza and Samsung Biologics hold dominant contract manufacturing capacity for mammalian cell culture production, with Catalent and Boehringer Ingelheim capturing fill-finish operations. Geographic supply concentration centers on Switzerland, Singapore, and South Korea for active pharmaceutical ingredient production, with fill-finish capacity distributed across Germany and the United States. Raw material dependencies rest on recombinant protein media, single-use bioreactor bags, and pharmaceutical-grade cold-chain packaging. Single-source vulnerability in protein A resin purification creates bottleneck exposure. Distribution runs through specialty pharmacy networks in the United States and hospital central procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TNF alpha inhibitor market operates as a defensive-moat story anchored in regulatory entrenchment, where FDA interchangeability designation and EMA centralized authorization create multi-year barriers to automatic pharmacy substitution.
For Market Incumbents: Entrench manufacturing scale through captive bioreactor capacity in the Kanto region and Rhine-Main corridor, securing dual-source protein A resin supply before biosimilar sponsors achieve EMA extrapolation approvals. Deepen channel control via real-world evidence platforms that United States integrated delivery networks now require as table stakes for formulary access. For New Entrants and Emerging Players: Japanese secondary cities and German rehabilitation centers offer concentrated hospital procurement with limited biosimilar penetration, where conservative gastroenterology society guidelines slow switching velocity. Target inflammatory bowel disease induction protocols requiring intravenous administration, leveraging CDMO partnerships in Singapore to bypass cell line development expertise scarcity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMO platforms with single-use perfusion capabilities over originator biologics facing patent cliff compression. Long-term viability rests on facilities achieving ISO 13485 quality management convergence across medical device and biologics standards. Watch FDA interchangeability designation criteria evolution as the inflection signal determining biosimilar substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use perfusion system adoption reduces facility footprint and enables modular capacity expansion for mid-size sponsors. |
| Regulatory Approval Pathway | FDA 351(k) biosimilar submissions with interchangeability designation compress exclusivity windows for reference products. |
| Hospital System Partnership | Integrated delivery network contracts tie reimbursement to sustained clinical response and patient support services. |
| Pipeline Diversification | Indication extrapolation across rheumatoid arthritis, psoriasis, and inflammatory bowel disease maximizes development ROI. |
| Strategic Partnership | CDMO alliances in Switzerland and Singapore bypass cell line development expertise scarcity concentrated in Boston and Basel. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews with payer access specialists and biologics coordinators supplemented secondary validation through FDA 351(k) filings, EMA centralized procedure submissions, ClinicalTrials.gov protocols, and hospital procurement databases. Bottom-up patient population modeling triangulated against top-down manufacturer revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning molecular origin, clinical indication, delivery mode, and care setting. CAGRs were derived from epidemiology-adjusted patient flow models and pricing trajectory assumptions. Forecast inputs incorporated EMA biosimilar guidance revision timing and Japanese diagnosis procedure combination reimbursement rate adjustments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated pharmaceutical conglomerates or CDMO consolidation would shift outcomes beyond modeled ranges. Regulatory divergence between FDA interchangeability standards and EMA extrapolation criteria, alongside patent litigation settlement timing, constitute primary revision risks. Quarterly review of biosimilar interchangeability designations and hospital formulary switch announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Isotretinoin Drugs Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Global Paracetamol Market