
 Global Live Cell Encapsulation Market | 2026-2036
Global Live Cell Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Live Cell Encapsulation Market Foresight
Platform licensing revenue is fragmenting across contract development and in-house bioprocessing teams. ViaCyte, Inc. leverages its stem cell-derived encapsulation platform to anchor partnerships with large diabetes programs. Sernova Corp. differentiates through its Cell Pouch system, competing on localized vascularization rather than systemic immunosuppression. Merck KGaA sustains its position by controlling supply of alginate and other encapsulation-grade biomaterials.
Live cell encapsulation encloses viable therapeutic cells within semipermeable biopolymer membranes, typically alginate-poly-L-lysinate composites ranging from 200 to 800 micrometers in diameter, to shield transplanted tissue from host immune responses while permitting nutrient and metabolite exchange. The technique serves primarily to enable allogeneic cell therapies without chronic immunosuppression. Hydrogel beads and microcapsules command the dominant share of product-type revenue, reflecting their established use in islet transplantation protocols. Electrostatic droplet generation leads technology adoption due to its precision in producing uniform bead sizes, while extrusion methods occupy cost-sensitive research applications where throughput requirements are modest.
The FDA regulates encapsulated cell products as combination devices under 21 CFR Part 3, requiring sponsors to demonstrate membrane integrity and cell viability over specified shelf lives. The EMA's Committee for Advanced Therapies coordinates scientific advice for cross-border trials involving encapsulated allogeneic cells, shaping European development timelines. ISO 10993 biocompatibility testing and MDR Class III device classification in Europe impose substantial preclinical documentation burdens on developers. Stakeholders must monitor evolving reimbursement decisions for encapsulated cell therapies by CMS and Germany's G-BA, as these will determine whether clinical efficacy translates into sustainable commercial adoption.
Market Dynamics
Platform licensing revenue is fragmenting across contract development and in-house bioprocessing teams, forcing developers to choose between partnership dependency and captive manufacturing scale. This structural tension between collaboration and control defines competitive positioning across the value chain.
Growth Catalysts
- FDA's regenerative medicine advanced therapy designation:This regulatory pathway compresses clinical trial timelines for encapsulated islet cell programs, accelerating commercial readiness for diabetes therapies in the United States.
- Alginate-poly-L-lysinate composite membranes:Advances in biopolymer chemistry are extending cell viability windows, enabling longer shelf lives and reducing per-dose manufacturing costs for transplant centers.
- Specialized manufacturing infrastructure in Germany and Japan:These clusters provide contract encapsulation services at clinical scale, lowering barriers for biopharmaceutical companies lacking in-house microfluidic capabilities.
Market Restraints
- MDR Class III device classification in Europe:The European Medical Device Regulation imposes extensive preclinical documentation requirements, extending time-to-market for developers targeting the EU.
- Supply concentration in pharmaceutical-grade alginate:Merck KGaA and limited alternative suppliers control encapsulation-grade biomaterial availability, creating input dependency risks for formulation developers.
- Electrostatic droplet generation throughput ceilings:Current microfluidic bead production methods face scaling constraints above certain batch volumes, limiting cost reductions for high-volume indications.
Strategic Opportunities
- Underpenetrated chronic pain and neurodegenerative applications:Encapsulated chromaffin cells and neural progenitors represent expansion vectors beyond the crowded diabetes segment, with early clinical programs in Parkinson's disease.
- Japan's PMDA regenerative medicine product pathway:This accelerated review framework offers faster approval timelines for allogeneic cell therapies, attracting developers seeking earlier revenue generation.
- Convergence of 3D bioprinting with microencapsulation:Hybrid manufacturing approaches are enabling spatially organized multicellular constructs, opening organoid-scale therapeutic possibilities.
Industry Challenges
- ISO 10993 biocompatibility testing timelines:Extended preclinical validation periods for novel membrane compositions delay IND submissions and compress development runway.
- Cross-functional talent scarcity:The intersection of immunology, biomaterials science, and GMP manufacturing requires hybrid expertise that academic programs rarely produce.
- Reimbursement pathway uncertainty:CMS and Germany's G-BA have not established consistent coding for encapsulated cell therapies, forcing developers to pursue case-by-case coverage determinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Live Cell Encapsulation Market |
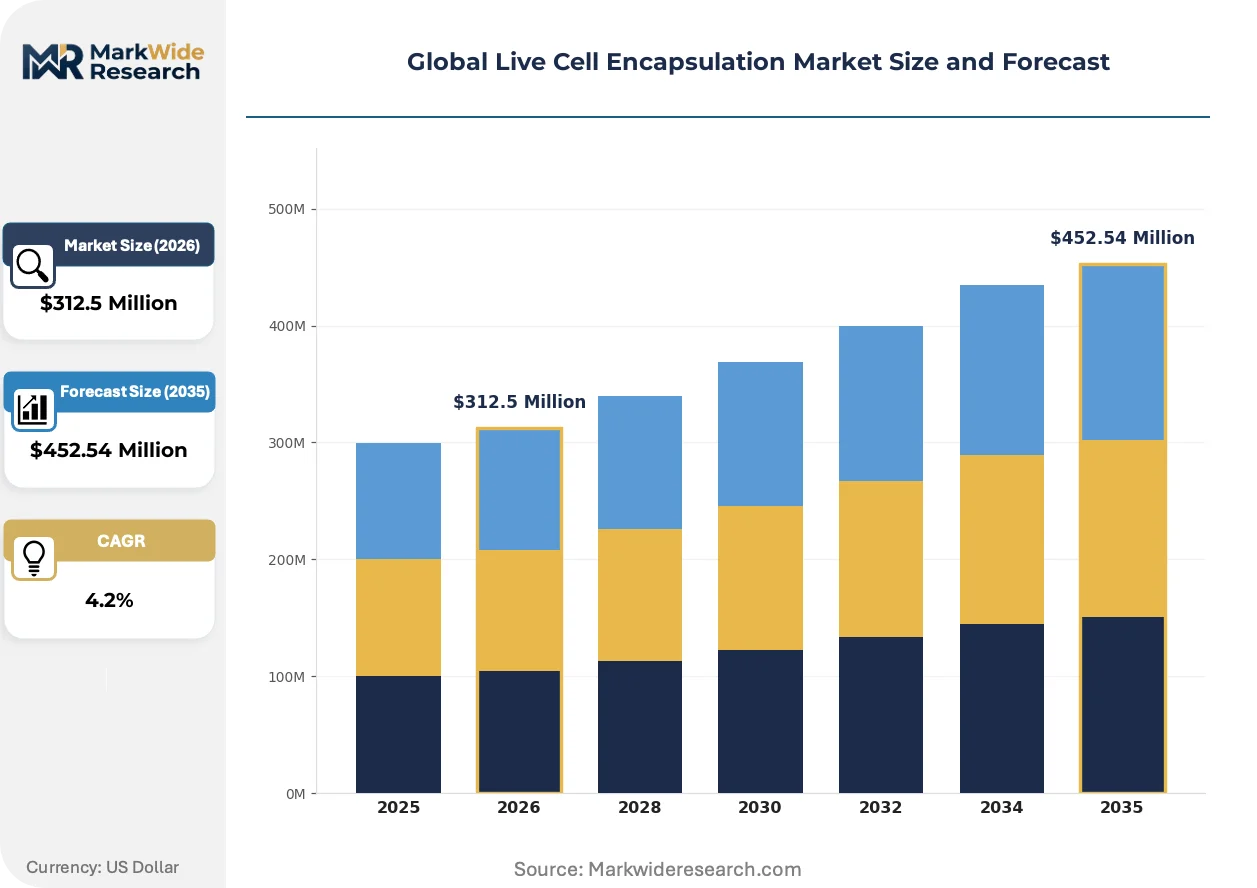
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcapsules, Microcarriers, Hollow Fibers, Hydrogel Beads, Nanocapsules Application: Diabetes Treatment, Oncology, Regenerative Medicine, Cardiovascular Disorders, Neurological Diseases End User: Biopharmaceutical Companies, Research Laboratories, Tissue Engineering Firms, Academic Institutions, Contract Research Organizations Technology: Electrostatic Droplet Generation, Extrusion, Emulsion, Coacervation, Spray Drying |
| Companies Covered | ViaCyte, Inc., Sernova Corp., Austrianova, Lineage Cell Therapeutics, Inc., Sigilon Therapeutics, Inc., Merck KGaA, Diatranz Otsuka Ltd., BÜCHI Labortechnik AG, PharmaCyte Biotech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Live Cell Encapsulation Market Shifts & Advancements
Electrostatic droplet generation is reshaping manufacturing economics while regulatory frameworks in the United States, Europe, and Japan are converging toward accelerated pathways for combination cell-device products. These forces are compressing development timelines and redistributing value capture across the supply chain.
Microfluidic bead production systems are collapsing the cost structure for uniform alginate microcapsules. Biopharmaceutical companies with in-house electrostatic droplet capabilities are reducing per-batch variability and cutting contract manufacturing dependencies. This technology compression is enabling smaller developers to retain process control through Phase II trials.
The FDA's 21 CFR Part 3 combination device framework is creating harmonization pressure across jurisdictions. Sponsors must demonstrate membrane integrity and cell viability over specified shelf lives, forcing alignment between CMC strategies and clinical endpoints. European developers are responding by front-loading ISO 10993 biocompatibility data to support parallel EMA and FDA submissions.
Buyer concentration among large diabetes programs is consolidating procurement leverage. Academic medical centers and integrated delivery networks are demanding outcome guarantees and extended viability warranties, displacing traditional fee-for-service supply arrangements. This shift is most visible in the United States, where CMS reimbursement uncertainty amplifies purchasing risk aversion.
Global Live Cell Encapsulation Market Segmentation
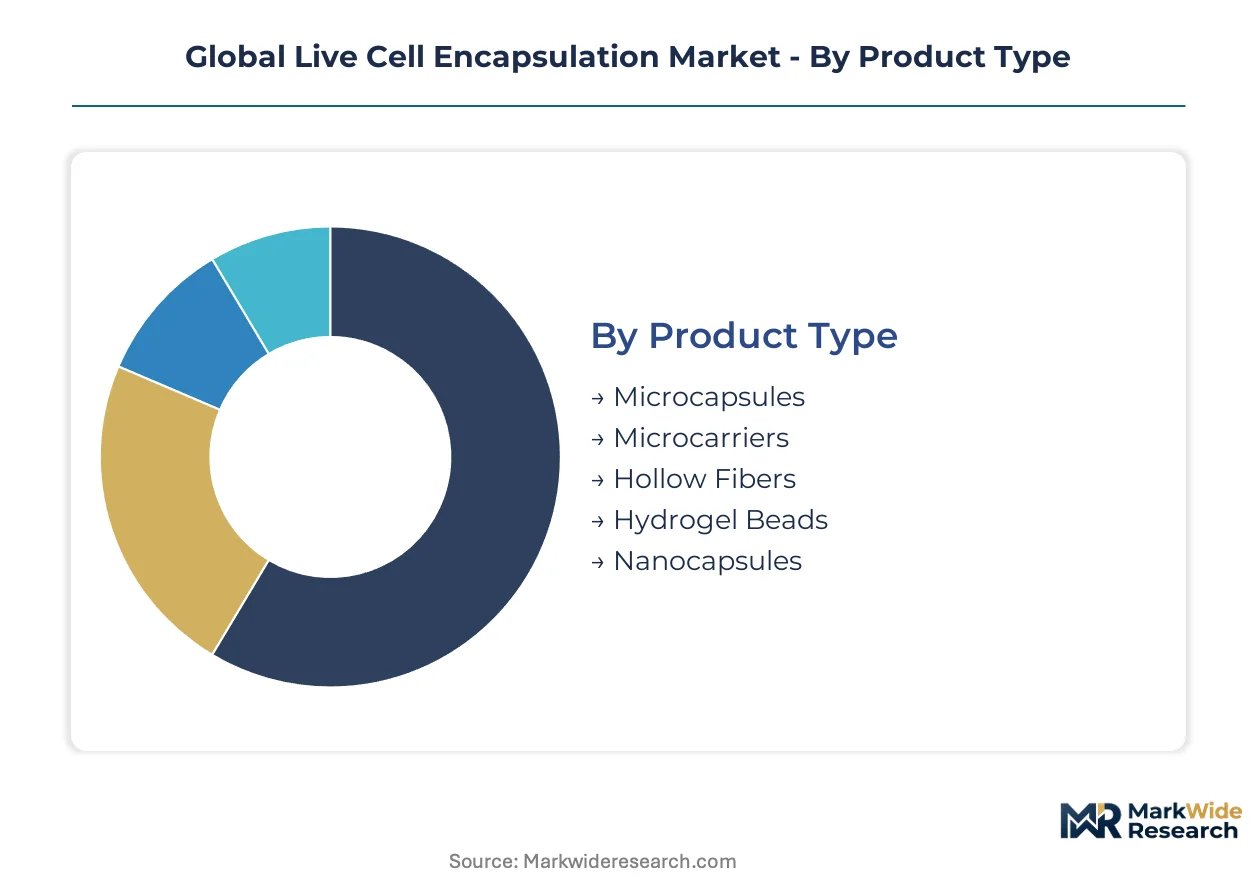
Segmentation in live cell encapsulation reveals how manufacturing scale, clinical application maturity, and technology readiness create divergent investment timelines. Each dimension carries distinct regulatory burdens and partnership requirements that shape competitive positioning.
Product Type:
Cycle times vary dramatically — hydrogel bead production completes in hours while hollow fiber manufacturing spans weeks of membrane conditioning and sterility validation.
- Hydrogel Beads:Alginate-poly-L-lysinate composites ranging 200-800 micrometers dominate islet transplantation protocols. United States transplant centers drive procurement volume as FDA regenerative medicine designations accelerate clinical program scale-up.
- Microcapsules:Semi-permeable biopolymer membranes enclose viable therapeutic cells for allogeneic therapies without chronic immunosuppression. Germany's contract encapsulation infrastructure supports commercial manufacturing for European diabetes programs facing MDR Class III documentation requirements.
- Microcarriers:Surface-attached cell culture substrates enable adherent cell expansion in bioreactor environments.
- Hollow Fibers:Tubular membrane configurations suit high-volume metabolite exchange applications.
- Nanocapsules:Sub-micron encapsulation systems target intracellular delivery and gene therapy vectors.
Hydrogel beads dominate installed base. Nanocapsules are where expansion concentrates.
Application:
Margin profiles diverge sharply — diabetes treatment commands premium pricing through established reimbursement pathways while neurological applications require de novo economic validation.
- Diabetes Treatment:Encapsulated islet cell therapies represent the most clinically advanced application with ViaCyte and Sernova anchoring late-stage programs. United States biopharmaceutical procurement concentrates here due to CMS coverage precedents for cell-based interventions.
- Regenerative Medicine:Broad therapeutic category spanning tissue repair and organoid development. Japan's PMDA accelerated pathway attracts developers seeking earlier revenue generation for allogeneic cell products.
- Oncology:Encapsulated immune cell and tumor vaccine applications remain predominantly preclinical.
- Cardiovascular Disorders:Cardiac cell encapsulation for myocardial repair faces substantial vascularization challenges.
- Neurological Diseases:Encapsulated chromaffin cells and neural progenitors for Parkinson's disease represent early clinical expansion beyond diabetes.
Diabetes treatment dominates installed base. Regenerative medicine is where expansion concentrates.
End User:
Customer sophistication tiers separate specification-heavy biopharmaceutical procurement from price-sensitive academic purchasing.
- Biopharmaceutical Companies:Integrated developers and platform licensors demand GMP-compliant encapsulation with extended viability warranties. United States and German manufacturing clusters supply clinical-scale production for these customers.
- Contract Research Organizations:CROs aggregate demand from mid-cap developers lacking in-house microfluidic capabilities. Japan's specialized infrastructure supports Asia-Pacific clinical trial material production.
- Research Laboratories:Preclinical investigation and protocol development centers.
- Tissue Engineering Firms:Organoid and scaffold-integrated encapsulation specialists.
- Academic Institutions:Investigator-initiated studies with limited commercial manufacturing requirements.
Biopharmaceutical companies dominate installed base. Contract research organizations are where expansion concentrates.
Technology:
Capital intensity separates precision microfluidic systems from equipment-light emulsion methods.
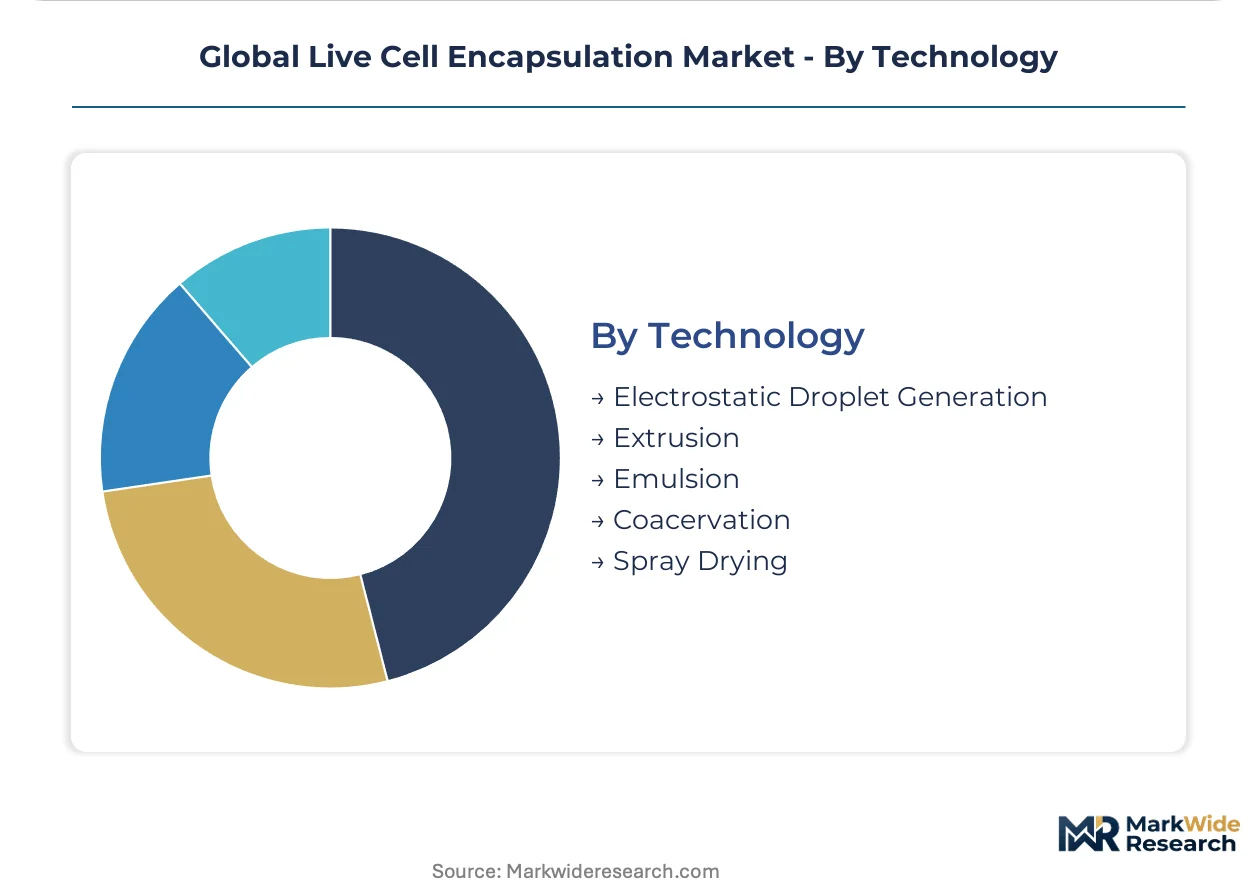
- Electrostatic Droplet Generation:Precision microfluidic production of uniform bead sizes enables reduced per-batch variability and lower contract manufacturing dependencies. United States developers with captive capabilities retain process control through Phase II trials.
- Extrusion:Cost-sensitive research applications with modest throughput requirements occupy this method. European academic centers utilize extrusion for preclinical protocol development under ISO 10993 biocompatibility frameworks.
- Emulsion:Oil-phase dispersion techniques for hydrophobic encapsulation matrices.
- Coacervation:Phase separation methods for complex multi-layer membrane formation.
- Spray Drying:High-throughput dehydration processes for shelf-stable encapsulated products.
Electrostatic droplet generation dominates installed base. Spray drying is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates clinical adoption through CMS reimbursement precedents for cell-based diabetes interventions, while Germany and Japan concentrate manufacturing infrastructure for contract encapsulation services. Demand patterns diverge sharply: US transplant centers prioritize GMP-compliant islet cell products, whereas Japanese developers exploit accelerated regulatory pathways for earlier revenue generation.
United States
FDA regenerative medicine advanced therapy designations compress clinical trial timelines for encapsulated islet programs. The agency's 21 CFR Part 3 combination device framework demands demonstrated membrane integrity over specified shelf lives. Boston and San Diego bioclusters anchor platform licensing activity between stem cell-derived encapsulation developers and large diabetes programs.
Germany
Specialized contract encapsulation infrastructure serves European biopharmaceutical companies lacking in-house microfluidic capabilities. EMA Committee for Advanced Therapies coordinates scientific advice for cross-border trials involving encapsulated allogeneic cells. The Baden-Württemberg and Bavaria regions concentrate MDR Class III device manufacturing for diabetes treatment applications.
Japan
PMDA regenerative medicine product pathway offers faster approval timelines for allogeneic cell therapies than FDA or EMA routes. METI industrial policy supports clinical-scale production facilities for Asia-Pacific trial material supply. Tokyo and Osaka metropolitan areas host specialized infrastructure attracting developers seeking earlier commercialization.
Switzerland
Swissmedic maintains alignment with EMA advanced therapy frameworks while offering streamlined scientific advice procedures. ISO 10993 biocompatibility testing capabilities concentrate around Basel and Zurich life science clusters. Local encapsulation-grade biomaterial suppliers serve as alternative inputs to German-dominated alginate supply chains.
Global Live Cell Encapsulation Market Competitive Landscape
Capability concentration sits with platform technology developers; scale advantage sits with biomaterial suppliers controlling encapsulation-grade inputs. The market structures around three tiers: stem cell-derived platform licensors, device-integrated system specialists, and pharmaceutical-grade material suppliers. Consolidation pressure runs through partnership dependency versus captive manufacturing scale. Dominant competitive moves include strategic licensing of microfluidic production capabilities and backward integration into alginate supply chains.
Among North American platform developers, ViaCyte, Inc. and Sernova Corp. exemplify divergent technical approaches to encapsulated cell therapies. Merck KGaA occupies a position as the dominant supplier of pharmaceutical-grade alginate and complementary encapsulation biomaterials. These three anchors represent the structural tension between therapeutic application ownership and critical input control that defines competitive positioning across the value chain.
| Leading Market Players |
|---|
| ViaCyte, Inc. |
| Sernova Corp. |
| Austrianova |
| Lineage Cell Therapeutics, Inc. |
| Sigilon Therapeutics, Inc. |
| Merck KGaA |
| Diatranz Otsuka Ltd. |
| BÜCHI Labortechnik AG |
| PharmaCyte Biotech Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in United States GMP encapsulation facilities is compressing lead times for clinical-grade alginate microcapsules and amplifying pricing leverage for contract manufacturers serving late-stage diabetes programs. This utilization squeeze forces biopharmaceutical developers to commit to multi-year offtake structures or absorb spot-market premiums for priority batch scheduling.
Pricing Analysis
Long-term offtake agreements dominate procurement for clinical-scale encapsulation, with project-based spot purchasing reserved for preclinical protocol development and academic investigator-initiated studies. Price differentiation hinges on GMP certification tier and ISO 10993 documentation depth, with FDA master file-backed suppliers commanding substantial premiums over research-grade alternatives. Pricing pressure stems from buyer consolidation among integrated diabetes programs demanding outcome-linked warranties. Academic institutions exhibit highest price sensitivity, while large biopharmaceutical companies prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for encapsulation-grade biomaterials, though alginate sourcing concentrates in Germany, Norway, and Japan. Raw material dependencies center on pharmaceutical-grade sodium alginate, poly-L-lysine of defined molecular weight, and sterile-filtered calcium chloride solutions. Single-source vulnerability characterizes high-viscosity alginate grades suitable for islet encapsulation. Distribution runs through specialized cold-chain logistics providers serving regional manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. FDA combination device precedents and EMA advanced therapy familiarity create switching costs that new entrants struggle to replicate.
For Market Incumbents: Harden supply security through backward integration into alginate purification capabilities or exclusive cultivation partnerships with seaweed harvesting cooperatives in Norway. Expand GMP capacity in Baden-Württemberg to capture European diabetes program demand facing MDR Class III documentation requirements. Prioritize membrane integrity testing automation to reduce per-batch release timelines. For New Entrants and Emerging Players: Establish a beachhead in neurological disease applications where reimbursement pathways remain unsettled and incumbent presence is sparse. Target Japan's PMDA regenerative medicine pathway for earlier revenue generation with allogeneic neural progenitor programs. Lead with hybrid 3D bioprinting-encapsulation capabilities that differentiate from established electrostatic droplet platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical-scale microfluidic manufacturing as FDA master file investments and ISO 13485 certification requirements escalate fixed cost bases. Platform licensors with demonstrated cell viability warranties beyond 24 months represent the most defensible acquisition profile. Monitor CMS coverage determinations for encapsulated islet therapies as the critical signal for commercial scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Master File Submission | Accelerates partner IND timelines by pre-qualifying alginate membrane biocompatibility data. |
| ISO 13485 Certification Investment | Unlocks European MDR Class III device manufacturing contracts for diabetes programs. |
| Cell Viability Warranty Extension | Differentiates procurement bids from integrated delivery networks demanding outcome guarantees. |
| Backward Integration into Alginate Supply | Reduces input dependency on Merck KGaA and Norwegian pharmaceutical-grade suppliers. |
| 3D Bioprinting Platform Partnership | Enables spatially organized multicellular constructs for organoid-scale therapeutic applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cell therapy development executives, GMP manufacturing directors, regulatory affairs specialists, and hospital transplant center procurement leads. Secondary validation drew from FDA 510(k) and BLA filings, EMA Committee for Advanced Therapies scientific advice minutes, ClinicalTrials.gov protocol registries, and ISO 10993 biocompatibility study databases. Bottom-up segment sizing triangulated against top-down market boundary checks.
Calibration against historical capacity utilization at United States and German contract encapsulation facilities anchored the analytical framework. Segmentation dimensions modeled include product type, clinical application maturity, end-user sophistication tier, and regional regulatory pathway cluster. CAGRs were derived from slope analysis across the projection horizon, incorporating PMDA approval timeline differentials and CMS reimbursement scenario weightings.
Stress conditions across alginate supply disruption, MDR documentation timeline extension, and electrostatic droplet generation throughput ceilings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clinical trial success rates and regulatory pathway harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
India Biopsy Devices Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Surgical Devices Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Operating Room Integration Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Global Electrotherapy Devices Market