
 Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market | 2026-2036
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Foresight
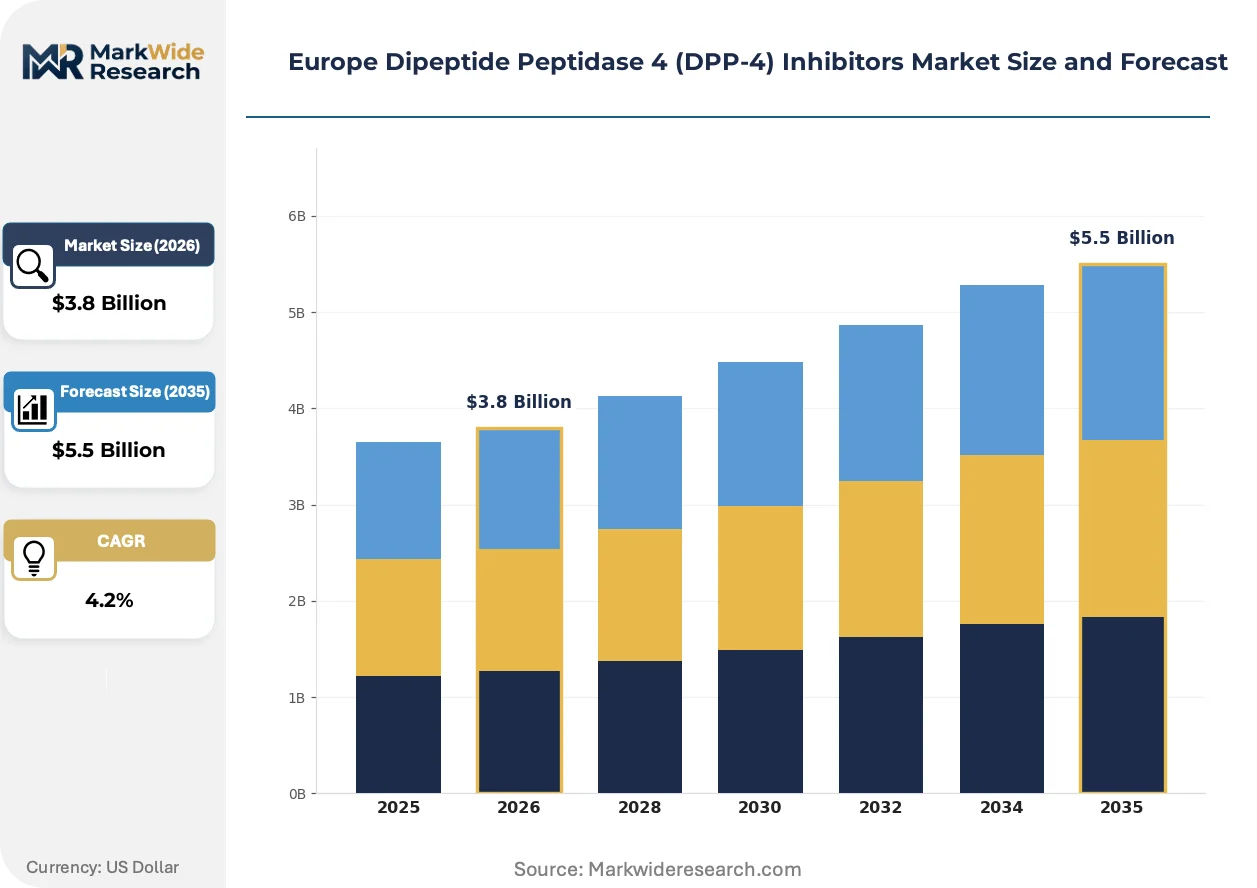
Hospital procurement of DPP-4 inhibitors is shifting toward fixed-dose combination therapies that pair gliptins with SGLT-2 inhibitors or metformin. Merck & Co. leverages its manufacturing scale to dominate sitagliptin supply across Northern European markets. Boehringer Ingelheim anchors its position through co-development partnerships that extend reach into cardiology-linked diabetes protocols. Eli Lilly and Company differentiates via R&D intensity focused on next-generation oral formulations.
Dipeptide Peptidase 4 (DPP-4) inhibitors are oral antihyperglycemic agents that block the DPP-4 enzyme to prolong incretin hormone activity, stimulating glucose-dependent insulin secretion with a low hypoglycemia risk profile. These agents primarily serve Type 2 diabetes management, with emerging applications in metabolic syndrome and cardiovascular risk reduction. Among product types, linagliptin commands attention for its non-renal elimination pathway that suits elderly populations with declining kidney function. Oral administration routes retain the dominant share, though sublingual delivery formats attract development interest for patient populations with swallowing difficulties. Therapy area segmentation reveals diabetes as the mature revenue base while cardiology represents the fastest-growing margin pool as cardiovascular outcome trials reshape prescribing guidelines.
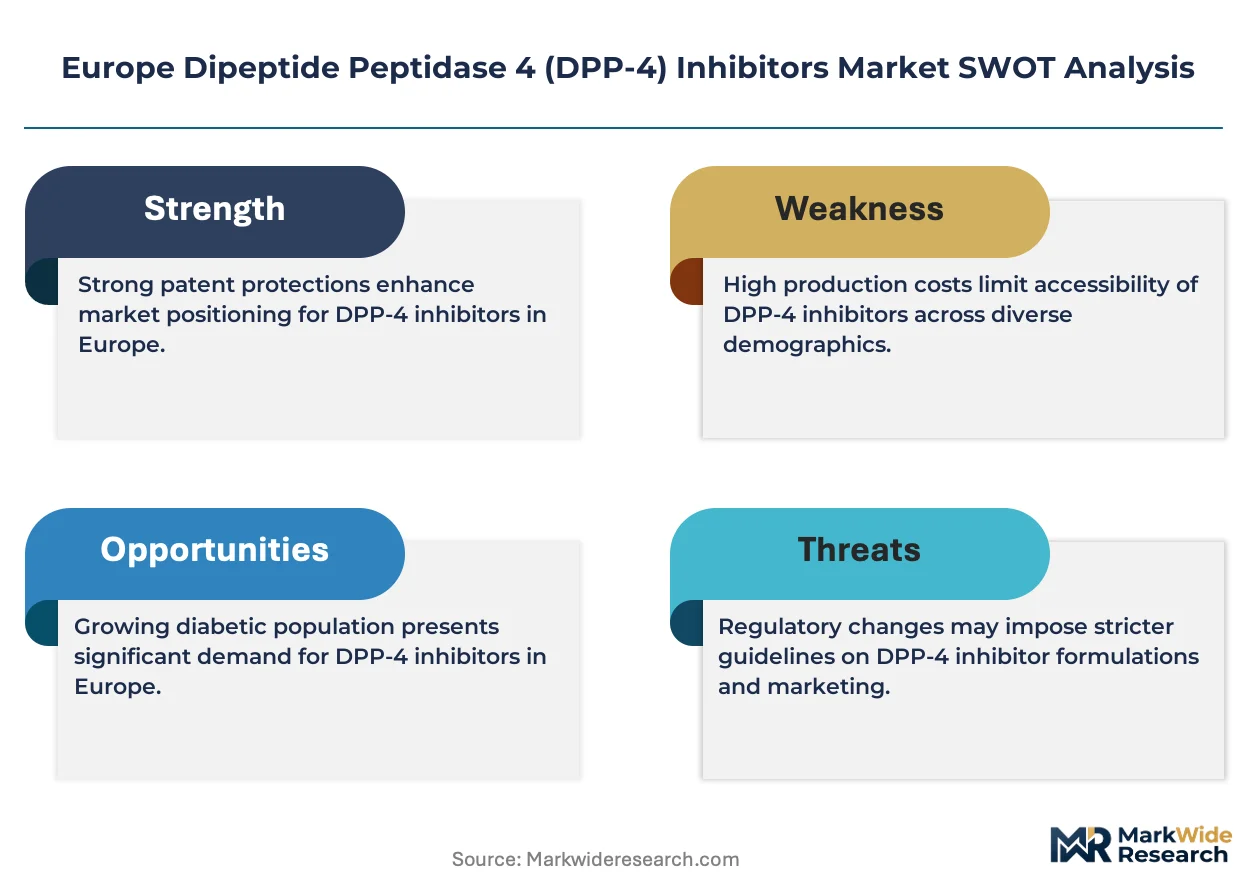
EMA marketing authorization requirements and the EU Medical Device Regulation govern combination product approvals, creating layered compliance costs that favor established pharmaceutical manufacturers with dedicated regulatory affairs infrastructure. The F-Gas Regulation indirectly affects cold-chain logistics for temperature-sensitive biologic components used in certain formulation processes. France's ANSM and Germany's BfArM enforce national pharmacovigilance reporting that shapes post-market surveillance obligations across the region. Stakeholders must monitor EMA guideline revisions on cardiovascular outcome data requirements, as these will determine which DPP-4 inhibitor formulations retain preferred reimbursement status in major European markets.
Market Dynamics
Hospital procurement protocols across Western Europe are consolidating purchasing power around fixed-dose combination therapies, compressing margins for standalone DPP-4 inhibitor formulations while elevating manufacturers with integrated cardiovascular outcome data portfolios.
Growth Catalysts
- EMA cardiovascular outcome guidelines:Marketing authorization pathways now reward formulations with proven heart failure risk reduction, steering hospital formulary decisions toward data-rich gliptin combinations.
- Germany's Diabetologen networks:Specialist diabetes centers in Bavaria and North Rhine-Westphalia drive protocol standardization that accelerates adoption of renal-friendly linagliptin regimens.
- Metabolic syndrome expansion:Prescribing boundaries are stretching beyond glycemic control into pre-diabetic populations with elevated cardiovascular biomarkers.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for sitagliptin intermediates clusters in select Asian contract manufacturers, exposing European formulators to single-source fragility.
- F-Gas Regulation compliance costs:Cold-chain storage requirements for temperature-sensitive biologic excipients face escalating refrigerant phase-out timelines that inflate logistics expenditure.
- SGLT-2 inhibitor substitution:Empagliflozin and dapagliflozin formulations with demonstrated cardiovascular mortality benefits capture hospital formulary slots previously reserved for gliptin monotherapy.
Strategic Opportunities
- France's regional health agencies:ARS Auvergne-Rhône-Alpes and ARS Hauts-de-France pilot integrated diabetes-cardiology care pathways that create procurement windows for combination therapies.
- Sublingual delivery formats:Orally disintegrating tablet technologies address dysphagia prevalence in elderly diabetic populations, opening differentiation in nursing home and long-term care channels.
- EU Medical Device Regulation convergence:Combination product frameworks that blend drug and delivery device elements offer first-mover advantages for manufacturers with dedicated quality management systems.
Industry Challenges
- Pharmacovigilance workforce scarcity:Germany's BfArM and France's ANSM impose escalating post-market surveillance reporting obligations that outstrip available qualified drug safety personnel.
- Legacy manufacturing line retrofitting:Existing oral solid dose facilities require substantial capital deployment to accommodate combination tablet complexity and real-time release testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sitagliptin, Saxagliptin, Linagliptin, Alogliptin Administration Route: Oral, Injectable, Sublingual, Transdermal End User: Clinics, Hospitals, Homecare, Research Laboratories Therapy Area: Diabetes, Metabolic Disorders, Weight Management, Cardiology |
| Companies Covered | AstraZeneca, Merck & Co., Inc., Novartis, Eli Lilly and Company, Boehringer Ingelheim, Takeda, Sanofi, Bristol-Myers Squibb, Pfizer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Shifts & Advancements
Formulation science and regulatory data requirements are converging to reshape competitive positioning in European diabetes care, with delivery mechanism innovation and cardiovascular evidence generation commanding disproportionate investment priority.
Extended-release matrix technologies incorporating hydroxypropyl methylcellulose and polymethacrylate copolymers are decentralizing manufacturing flexibility by enabling regional production hubs to achieve bioequivalence without centralized high-shear granulation infrastructure. Mid-sized European contract manufacturers in Spain and Italy are adopting these platform technologies to capture hospital tender business previously monopolized by integrated multinationals. This diffusion is compressing the minimum efficient scale for competitive DPP-4 inhibitor supply.
REACH authorization requirements for novel excipients and the EU Medical Device Regulation's Annex I general safety and performance obligations are tightening documentation burdens for combination product developers. Formulators must now generate clinical evidence bridging pharmacokinetic performance across device variants, extending development timelines by eighteen to thirty-six months. Cardiology-linked diabetes protocols in the United Kingdom's NHS Integrated Care Systems are responding by consolidating procurement around established manufacturers with existing regulatory dossiers.
Hospital pharmacy committees are unbundling historical physician-preference purchasing in favor of centralized therapeutic class reviews that benchmark total cost of cardiovascular outcomes. Germany's university hospitals in Berlin and Munich are piloting value-based procurement frameworks that weight HbA1c stability, hypoglycemia incidence, and heart failure hospitalization rates in tender scoring algorithms. This behavioral shift elevates manufacturers with robust real-world evidence generation capabilities and compresses commercial access for late entrants lacking longitudinal patient registries.
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Segmentation
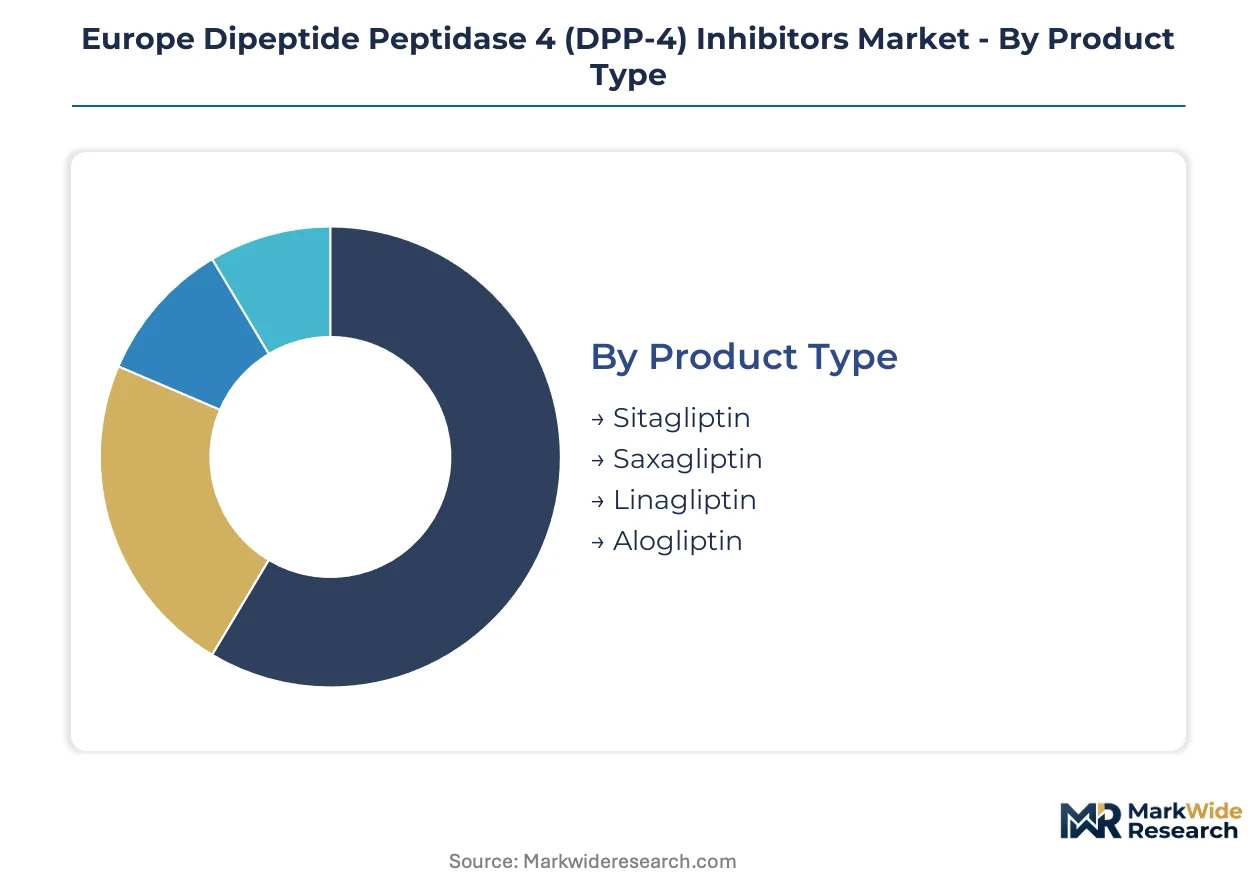
DPP-4 inhibitor procurement across Europe fragments along clinical setting, molecular profile, and delivery mechanism. Hospital formulary committees weight cardiovascular outcome data against renal clearance pathways when segmenting purchasing decisions.
Product Type:
Customization intensity varies sharply across this category, with molecular pharmacokinetics driving prescriber preference in elderly populations with comorbid renal impairment.
- Linagliptin:Non-renal elimination via hepatic metabolism and biliary excretion eliminates dose adjustment requirements in chronic kidney disease. Germany's Diabetologen networks in Bavaria prioritize this agent for patients over 75 with declining glomerular filtration rates.
- Sitagliptin:Dipeptide structure with primary renal clearance demands creatinine monitoring and dose titration protocols. France's ARS regional health agencies in Auvergne-Rhône-Alpes steer procurement toward this established molecule where cost-containment pressures dominate formulary decisions.
- Saxagliptin:Active metabolite formation extends pharmacodynamic duration in hepatic impairment scenarios.
- Alogliptin:Minimal CYP450 interaction profile suits polypharmacy regimens common in nursing home populations.
Leading the category by volume: Sitagliptin. Expanding most quickly: Linagliptin.
Administration Route:
Volume concentration clusters around oral formats, though margin expansion concentrates in alternative delivery mechanisms addressing swallowing dysfunction.
- Oral:Immediate-release and extended-release tablet matrices dominate hospital procurement across Western Europe. Merck & Co. and Boehringer Ingelheim compete through bioequivalent formulations meeting EMA marketing authorization standards for interchangeability.
- Sublingual:Orally disintegrating tablet technologies bypass gastrointestinal absorption variability. United Kingdom NHS Integrated Care Systems in Greater Manchester pilot these formats for dysphagic patients in long-term care facilities where aspiration risk constrains conventional tablet use.
- Injectable:Subcutaneous depot formulations under development for adherence-challenged populations.
- Transdermal:Patch-based delivery remains preclinical for DPP-4 enzyme modulation.
Oral administration commands procurement volume. Sublingual formats gain share fastest in geriatric channels.
End User:
Customer sophistication tiers separate centralized hospital purchasing from decentralized homecare reimbursement pathways.
- Hospitals:University medical centers in Berlin and Munich implement value-based procurement frameworks weighting cardiovascular outcome data. Germany's BfArM pharmacovigilance reporting requirements shape post-market surveillance obligations for inpatient DPP-4 inhibitor use.
- Homecare:Outpatient prescription fulfillment through community pharmacies dominates volume in France and the United Kingdom. ANSM national reimbursement lists determine patient copayment levels for linagliptin versus sitagliptin selection.
- Clinics:Specialist diabetes centers concentrate protocol-standardized prescribing.
- Research Laboratories:Academic medical centers generate real-world evidence for cardiovascular outcome trials.
Hospitals anchor procurement value. Homecare channels deliver volume scale.
Therapy Area:
Maturity gradients separate established diabetes applications from emerging metabolic syndrome indications where evidence generation commands R&D investment.
- Diabetes:Glycemic control with low hypoglycemia risk profile defines the core therapeutic application. EMA cardiovascular outcome guidelines now require heart failure risk reduction data for preferred reimbursement status in Type 2 diabetes populations.
- Cardiology:Heart failure hospitalization reduction emerges as the fastest-expanding margin pool. United Kingdom NHS cardiology-diabetes integrated care pathways in London and Birmingham prioritize DPP-4 inhibitors with proven cardiovascular safety signals.
- Metabolic Disorders:Pre-diabetic populations with elevated cardiovascular biomarkers represent prescriptive boundary expansion.
- Weight Management:Adjunctive use in obesity-linked glucose dysregulation remains off-label in most European markets.
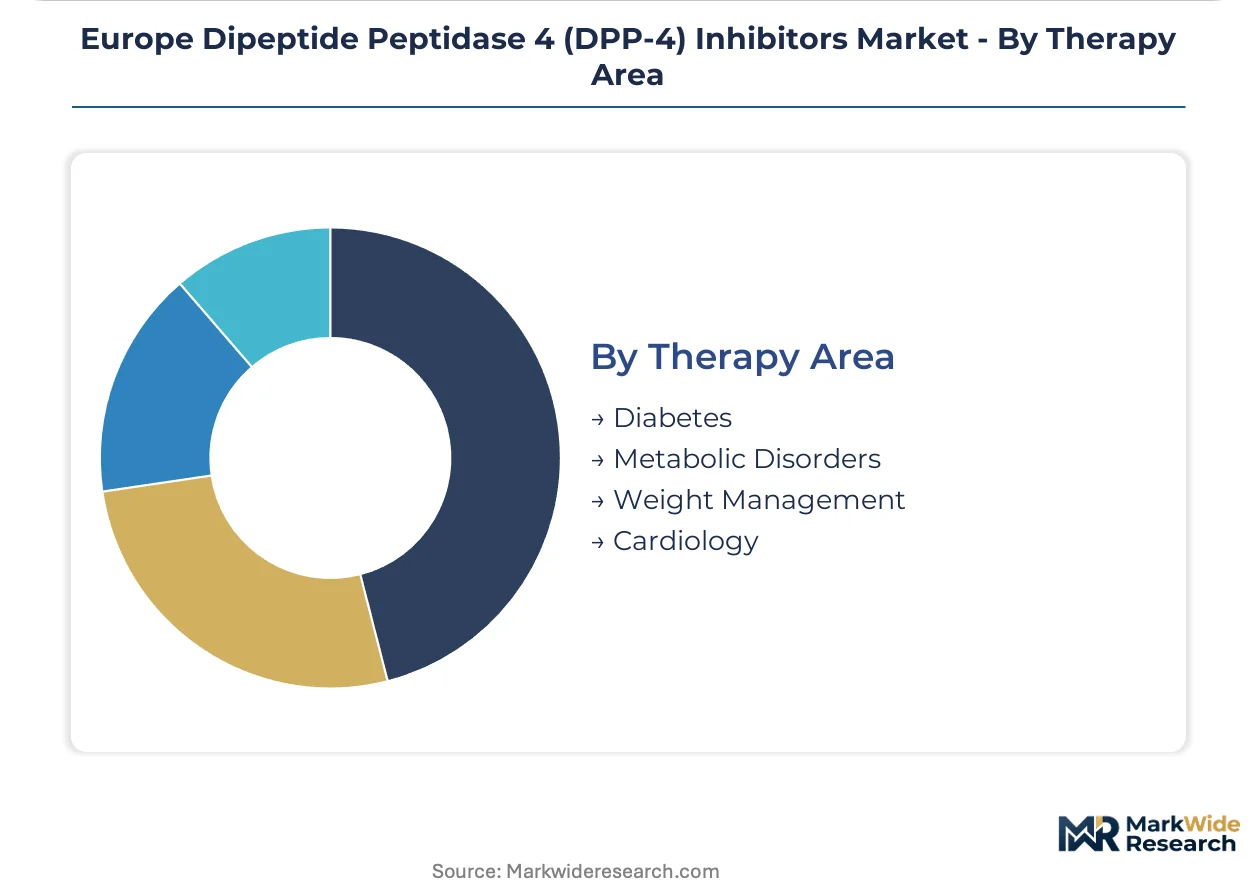
Diabetes generates current revenue concentration. Cardiology applications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Diabetologen specialist networks and France's regional health agencies concentrate procurement authority, while the United Kingdom's NHS Integrated Care Systems and hospital pharmacy committees in Italy and Spain shape national adoption patterns for DPP-4 inhibitor therapies.
Germany
Bavaria's university hospitals in Munich and Berlin's Charité medical center pilot value-based procurement frameworks weighting cardiovascular outcome data. The BfArM enforces pharmacovigilance reporting obligations that shape post-market surveillance for inpatient DPP-4 inhibitor use. North Rhine-Westphalia's Diabetologen networks drive protocol standardization accelerating renal-friendly linagliptin regimens for elderly populations.
France
ARS Auvergne-Rhône-Alpes and ARS Hauts-de-France pilot integrated diabetes-cardiology care pathways creating procurement windows for combination therapies. The ANSM national reimbursement lists determine patient copayment levels steering formulary decisions toward cost-contained sitagliptin where budget pressures dominate. Île-de-France's hospital pharmacy committees in Paris academic centers unbundle physician-preference purchasing for centralized therapeutic class reviews.
United Kingdom
NHS Integrated Care Systems in Greater Manchester pilot sublingual delivery formats for dysphagic patients in long-term care facilities where aspiration risk constrains conventional tablet use. NICE technology appraisals weight heart failure hospitalization rates in formulary scoring algorithms. London and Birmingham cardiology-diabetes integrated care pathways prioritize DPP-4 inhibitors with proven cardiovascular safety signals.
Italy
Mid-sized contract manufacturers in Lombardy and Emilia-Romagna adopt extended-release matrix technologies to capture hospital tender business. The AIFA national reimbursement framework governs regional formulary placement for oral antidiabetic agents. Milan's university hospitals concentrate real-world evidence generation capabilities for cardiovascular outcome trials.
Spain
Catalonia's hospital pharmacy committees consolidate purchasing power around fixed-dose combination therapies compressing margins for standalone formulations. The AEMPS marketing authorization requirements align with EMA cardiovascular outcome guidelines. Barcelona's clinical research organizations generate bridging pharmacokinetic data for combination product developers.
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical multinationals commanding hospital formulary access while mid-sized European formulators capture tender business through platform technologies. The vendor base organizes around three archetypes: large-cap innovators with cardiovascular outcome trial infrastructure, regional specialists with flexible manufacturing scale, and contract development organizations with real-world evidence generation capabilities. M&A activity concentrates on combination therapy portfolios, while capacity expansion targets extended-release formulation lines.
Within the large-cap innovator tier, Merck & Co., Inc. and Boehringer Ingelheim occupy positions defined by manufacturing scale and co-development partnerships respectively. Eli Lilly and Company sits within the R&D-intensive segment focused on next-generation oral formulations. These three anchors exemplify divergent competitive vectors: supply chain dominance, cardiology-linked protocol integration, and formulation science differentiation.
| Leading Market Players |
|---|
| AstraZeneca |
| Merck & Co., Inc. |
| Novartis |
| Eli Lilly and Company |
| Boehringer Ingelheim |
| Takeda |
| Sanofi |
| Bristol-Myers Squibb |
| Pfizer |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient spot indices for sitagliptin intermediates cascade through European formulator margins, compressing pricing tiers as hospital procurement committees consolidate purchasing power around bioequivalent generics and fixed-dose combinations.
Pricing Analysis
Short lead-time premiums for temperature-sensitive biologic excipients under F-Gas Regulation constraints separate emergency procurement from contract-based offtake arrangements. Three-tier pricing structure across premium cardiovascular outcome data portfolios, standard bioequivalent formulations, and economy spot inventory reflects differentiation by EMA marketing authorization tier and real-world evidence depth. Cost compression in the economy tier intensifies because Germany's Diabetologen networks and France's ARS regional agencies steer volume toward lowest-cost bioequivalent options. Community pharmacy channels in the United Kingdom exhibit highest price sensitivity, while university medical centers in Berlin and Munich prioritize outcome data over unit cost.
Supply Chain Analysis
Qualified drug safety personnel scarcity in Spain's Catalonia and Italy's Lombardy constrains regional contract manufacturers from scaling extended-release matrix production. Active pharmaceutical ingredient manufacturing for DPP-4 inhibitor intermediates draws from India and China, with formulation finishing concentrated in Germany, France, and mid-sized European hubs. Single-source vulnerability in sitagliptin intermediate supply exposes European formulators to geopolitical disruption and customs processing delays. Distribution runs through hospital pharmacy committees in Western Europe, with direct-to-pharmacy channels dominating outpatient volume in France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation around fixed-dose combination therapies forces standalone DPP-4 inhibitor manufacturers toward exit or acquisition, with EMA cardiovascular outcome data requirements accelerating this consolidation dynamic.
For Market Incumbents: Extend cardiovascular outcome trial infrastructure to capture Germany's value-based procurement pilots and France's integrated care pathway tenders. Deepen backward integration into extended-release matrix technologies to reduce dependence on Asian contract manufacturers for critical excipients. Lock in formulary positioning through real-world evidence generation partnerships with NHS Integrated Care Systems before SGLT-2 substitution displaces gliptin monotherapy slots. For New Entrants and Emerging Players: Sublingual delivery format innovation offers entry into United Kingdom long-term care channels where dysphagia prevalence creates procurement windows outside hospital pharmacy committee control. Target Spain's mid-sized contract manufacturing segment for platform technology licensing rather than direct formulation competition. Pursue white-label partnerships with established cardiovascular outcome data holders to bypass eighteen-to-thirty-six-month EMA combination product development timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with flexible manufacturing scale in Italy and Spain over large-cap innovators facing SGLT-2 substitution pressure. Long-term viability hinges on cardiology-linked diabetes protocol integration rather than glycemic control commoditization. Watch EMA guideline revisions on heart failure risk reduction data requirements as the inflection signal determining which formulation portfolios retain preferred reimbursement status.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | EMA marketing authorization now rewards heart failure risk reduction data with preferred formulary status in Germany and France. |
| Extended-Release Manufacturing Scale-Up | Regional production hubs in Spain and Italy capture tender business through hydroxypropyl methylcellulose matrix platform adoption. |
| Combination Product Regulatory Pathway | EU Medical Device Regulation convergence creates eighteen-to-thirty-six-month first-mover windows for integrated device-drug developers. |
| Real-World Evidence Generation Partnership | NHS Integrated Care Systems in Greater Manchester pilot value-based procurement weighting HbA1c stability and hospitalization rates. |
| Sublingual Delivery Format Development | Orally disintegrating tablet technologies address dysphagia prevalence in United Kingdom nursing home channels. |
Research Methodology
Multi-period observation of EMA marketing authorization timelines, hospital formulary placement rates, and regional procurement tender outcomes anchored the trend analysis, supplemented by interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and payer access specialists. Secondary validation drew from EMA submission databases, ClinicalTrials.gov cardiovascular outcome trial records, ANSM and BfArM pharmacovigilance reports, and NHS Integrated Care System procurement disclosures. Bottom-up patient population modeling and top-down pharmaceutical expenditure tracking were triangulated against manufacturer capacity announcements.
Input-output matrices mapped formulation complexity, regulatory dossier requirements, and regional pricing elasticity across the projection horizon. Segmentation dimensions included molecular profile, administration route, end-user channel, and therapy area maturity. CAGRs were derived from trend extrapolation of hospital procurement volumes and reimbursement pathway evolution. Forecast inputs incorporated Diabetologen network protocol standardization rates and F-Gas Regulation compliance cost trajectories for cold-chain logistics.
Several conditions sit outside the modeled scope, including abrupt EMA guideline reversals, major API supply disruptions, and SGLT-2 inhibitor cardiovascular outcome data publication timing. Forecasts reflect documented assumptions about reimbursement stability and regulatory pathway continuity. Material deviation in EMA heart failure data requirements or German hospital procurement consolidation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market