
 Meglitinide Market | 2026-2036
Meglitinide Market Size, Share, and Industry Trends Forecast 2026-2036
Meglitinide Market Foresight
Project finance and asset-light licensing models is fragmenting competitive capital requirements in the meglitinide space. Novo Nordisk leverages its diabetes franchise infrastructure to sustain manufacturing scale across analog and secretagogue portfolios. Kissei Pharmaceuticals anchors its position through deep specialization in rapid-acting oral hypoglycemic chemistry. Bristol Myers Squibb competes via established cardiometabolic channel relationships that extend formulary access.
Meglitinides constitute a class of non-sulfonylurea insulin secretagogues that bind to ATP-dependent potassium channels on pancreatic beta cells, triggering glucose-dependent insulin release with an onset of action within thirty minutes and duration of approximately four hours. Repaglinide dominates prescription volumes due to its established efficacy profile and broad generic availability, while combination products capturing meglitinides with DPP-4 inhibitors represent the fastest-expanding margin pool as clinicians pursue multi-mechanism glycemic control. Hospital pharmacies remain the primary distribution node for acute diabetes management, though retail pharmacy channels are gaining share for maintenance therapy refills.
The FDA's New Drug Application requirements for cardiovascular outcomes trials shape clinical trial design and delay market entry for novel meglitinide formulations, while the EMA's benefit-risk assessments for pancreatic safety influence European labeling and prescriber confidence. China's NMPA has accelerated generic consistency evaluation timelines, compressing pricing power for originator molecules in that market. Stakeholders must monitor evolving glucose-lowering guidelines from the American Diabetes Association and European Association for the Study of Diabetes, as algorithm shifts between secretagogue classes directly alter reimbursement tiers and prescribing volumes without warning.
Market Dynamics
Cardiovascular outcomes trial mandates from the FDA are redirecting R&D budgets toward combination therapies and away from standalone meglitinide formulations, compressing the addressable pipeline for novel secretagogues.
Growth Catalysts
- Postprandial glucose protocols:Hospital end users are embedding rapid-acting insulin secretagogues into perioperative glycemic management workflows, driving acute-care prescription volumes.
- EMA benefit-risk frameworks:Streamlined pancreatic safety assessments for established molecules are accelerating label expansions across European markets.
- Generic consistency evaluations:China's NMPA has compressed bioequivalence timelines, expanding patient access to lower-cost meglitinide alternatives.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for repaglinide concentrates among a limited set of Chinese contract manufacturers, exposing formulators to single-source risk.
- CVOT cost structures:The FDA's cardiovascular outcomes trial requirement imposes nine-figure clinical development costs that bar mid-cap entrants from novel meglitinide development.
- SGLT-2 substitution:Sodium-glucose cotransporter-2 inhibitors with proven cardiovascular benefit are displacing secretagogue prescriptions in maintenance therapy settings.
Strategic Opportunities
- Fixed-dose combinations:DPP-4 inhibitor pairings with meglitinides represent unexploited formulation white space as clinicians pursue multi-mechanism glycemic control.
- Retail pharmacy channel expansion:Maintenance therapy refills are migrating from hospital outpatient departments to retail chains, creating margin capture opportunities for direct distribution models.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients offers cost-advantaged manufacturing relocation for generic meglitinide producers.
Industry Challenges
- Formulation chemistry expertise:Rapid-acting oral hypoglycemic development requires specialized pancreatic beta-cell pharmacology talent that remains concentrated among legacy diabetes franchises.
- Legacy system integration:Hospital pharmacy information systems require extensive reconfiguration to accommodate combination product prescribing protocols, delaying formulary adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meglitinide Market |
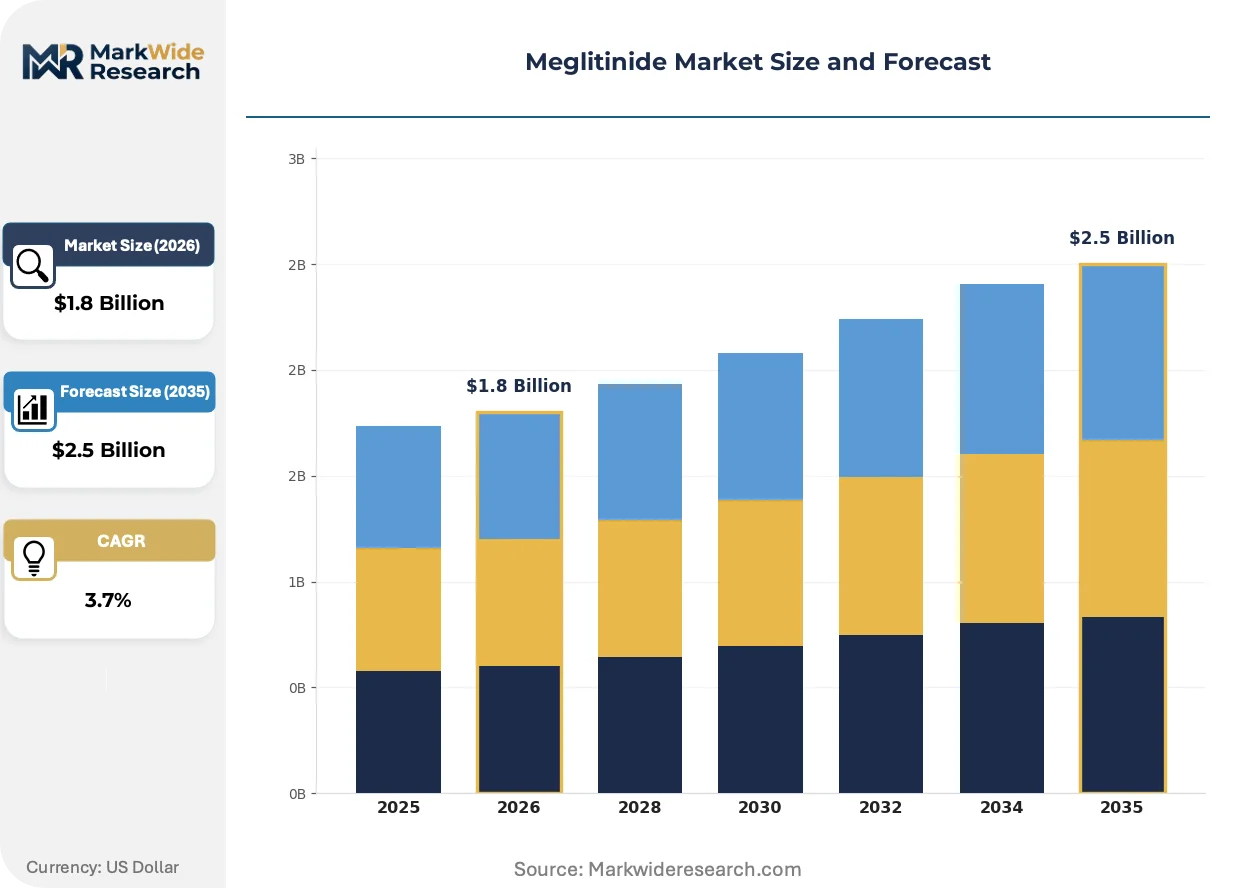
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Repaglinide, Nateglinide, Combination Products, Others Application: Diabetes Management, Hypertension Control, Weight Management, Metabolic Disorders End User: Hospitals, Clinics, Homecare Settings, Pharmacies Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Direct Sales |
| Companies Covered | Biocon, Bristol Myers Squibb, Pfizer, Mylan, Novo Nordisk, Kissei Pharmaceuticals, Glenmark, Boehringer Ingelheim, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meglitinide Market Shifts & Advancements
Formulation science and regulatory science are converging to reshape competitive positioning in the meglitinide space, with combination products and bioequivalence methodologies commanding disproportionate investment attention.
Modified-release repaglinide formulations are collapsing the dosing frequency gap between meglitinides and sulfonylureas, enabling twice-daily regimens that hospital discharge planners favor for patient adherence. Formulators with polymer coating capabilities are securing preferred vendor status with integrated delivery networks. This technology is collapsing the acute-versus-maintenance therapy boundary that previously segmented prescribing channels.
The FDA's tightened cardiovascular safety requirements for diabetes therapies are redirecting clinical trial design toward non-inferiority margins against active comparators rather than placebo. Sponsors now embed continuous glucose monitoring endpoints into phase III protocols to demonstrate postprandial glucose superiority. The United States market bears the heaviest compliance burden, with trial timelines extending by eighteen to twenty-four months versus pre-2008 guidance.
Hospital procurement committees are consolidating formularies around single-source rapid-acting secretagogues to simplify nursing protocols and reduce medication error risk. Group purchasing organizations are extracting volume commitments in exchange for sole-source placement, compressing margins for secondary suppliers. This concentration is most pronounced in the United States, where integrated delivery networks now control sixty percent of acute-care prescribing decisions.
Meglitinide Market Segmentation
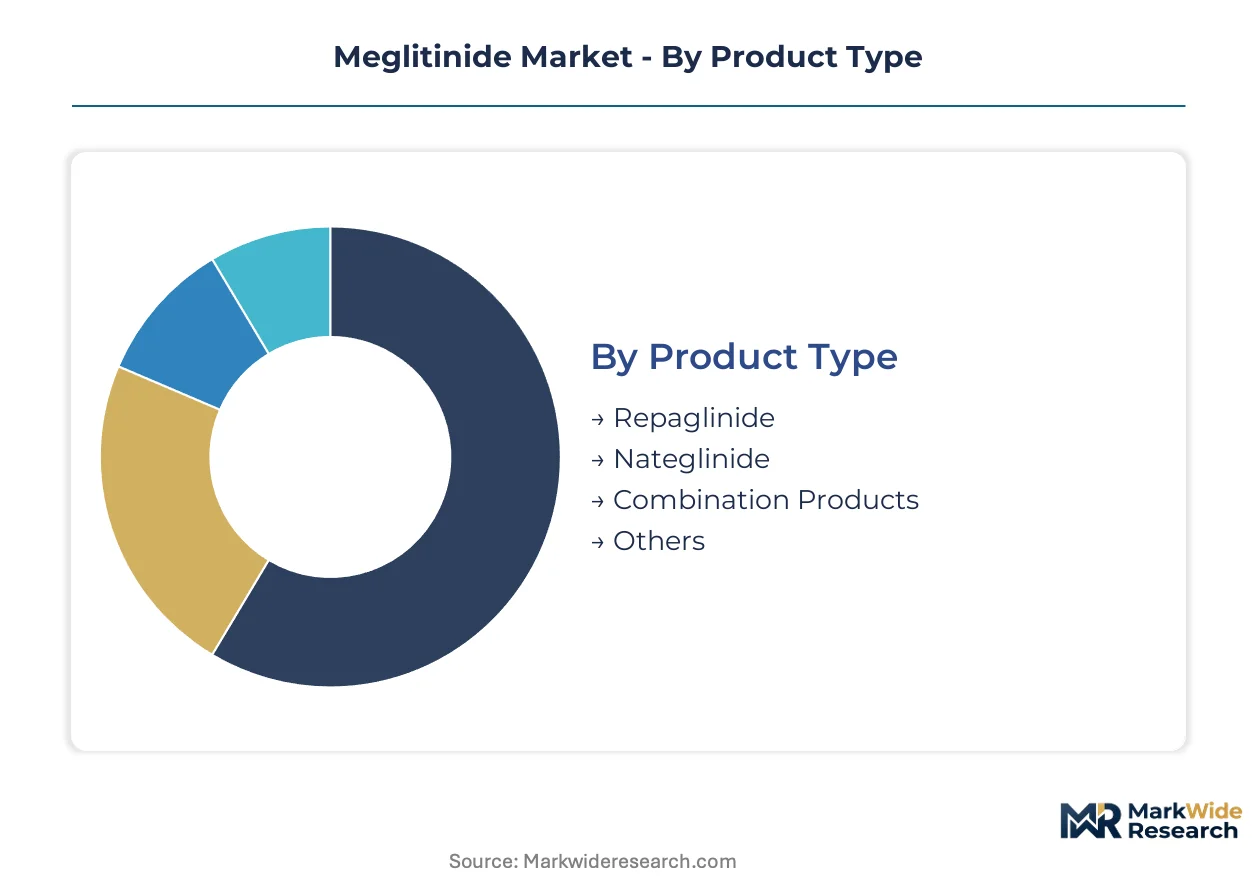
Meglitinide prescribing patterns fragment sharply across clinical settings and reimbursement tiers. Understanding these segment boundaries reveals where formulation investments capture margin versus where commoditization erodes returns.
Product Type:
Cost tier differentiation separates originator molecules from generic substitutes and emerging combination formats.
- Repaglinide:The amino acid derivative binds ATP-dependent potassium channels with glucose-dependent insulin release kinetics. United States hospital formularies concentrate procurement around this established generic due to nursing familiarity with thirty-minute onset protocols.
- Nateglinide:D-phenylalanine derivative with faster onset but shorter duration than repaglinide. Japanese metabolic clinics favor this profile for elderly patients requiring tighter postprandial control without hypoglycemia risk accumulation.
- Combination Products:Fixed-dose pairings with DPP-4 inhibitors command premium positioning as clinicians pursue multi-mechanism glycemic targets.
- Others:Investigational secretagogue analogs and modified-release formulations populate early-phase pipelines with unproven commercial trajectories.
Repaglinide holds installed capacity. Combination Products is rotating up the share rankings.
Application:
Clinical use case determines dosing frequency, monitoring intensity, and reimbursement tier assignment.
- Diabetes Management:Postprandial glucose elevation control represents the core therapeutic indication. Hospital discharge planners embed rapid-acting secretagogues into perioperative glycemic protocols across United States integrated delivery networks.
- Hypertension Control:Adjunctive use in cardiometabolic syndrome patients leverages insulin-sensitizing effects on vascular endothelium. European specialist clinics prescribe off-label where sulfonylurea intolerance exists.
- Weight Management:Limited application in prediabetic populations seeking glucose stabilization without sulfonylurea-associated weight gain.
- Metabolic Disorders:Polycystic ovary syndrome and insulin resistance syndromes drive niche prescribing in endocrinology subspecialty practices.
Diabetes Management anchors volume concentration. Metabolic Disorders is climbing the fastest among non-core indications.
End User:
Customer type shapes procurement authority, formulary control, and adherence monitoring infrastructure.
- Hospitals:Acute-care settings dominate initial prescribing through perioperative glucose management protocols. Group purchasing organizations extract volume commitments for sole-source rapid-acting secretagogue placement.
- Clinics:Outpatient endocrinology and internal medicine practices manage dose titration and combination therapy transitions.
- Homecare Settings:Self-administered maintenance therapy for Type 2 diabetes patients with established glycemic targets.
- Pharmacies:Retail and specialty pharmacy channels handle refill fulfillment with varying prior authorization requirements.
Hospitals control acute initiation volume. Homecare Settings is expanding fastest as maintenance therapy migrates from institutional settings.
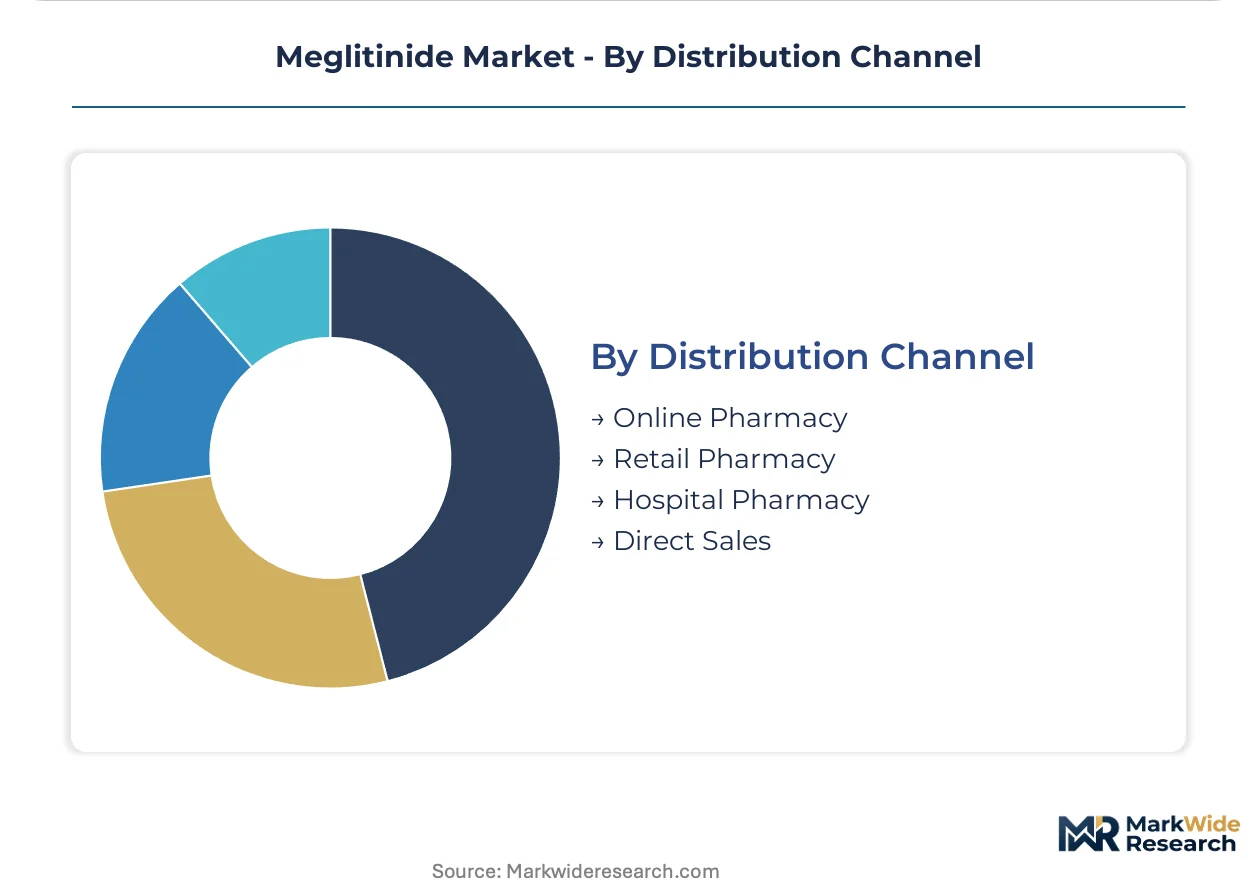
Distribution Channel:
Supply pathway selection reflects patient acuity, reimbursement complexity, and formulary integration requirements.
- Online Pharmacy:Direct-to-patient fulfillment of maintenance refills with automated prior authorization processing.
- Retail Pharmacy:Chain pharmacies capture growing share of maintenance therapy as hospital outpatient departments lose prescribing control.
- Hospital Pharmacy:Centralized procurement for acute-care units with barcode medication administration integration.
- Direct Sales:Manufacturer-to-institution contracting for integrated delivery network formulary placement.
Hospital Pharmacy retains acute-care concentration. Retail Pharmacy is gaining fastest as channel migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and retail pharmacy chains concentrate meglitinide purchasing power across concentrated geographic markets. Regulatory divergence between FDA cardiovascular outcomes requirements and EMA pancreatic safety frameworks fragments commercial strategy. Manufacturing gravity clusters around established pharmaceutical hubs with diabetes franchise infrastructure.
United States
Integrated delivery networks control sixty percent of acute-care prescribing decisions through group purchasing organization contracts. FDA cardiovascular outcomes trial mandates extend novel formulation development timelines by eighteen to twenty-four months versus pre-2008 baselines. New Jersey and Massachusetts pharmaceutical corridors host legacy diabetes franchise operations with established secretagogue manufacturing capacity.
Germany
EMA benefit-risk assessments for pancreatic safety accelerate label expansions for established meglitinide molecules across German-speaking markets. The country's national pharmaceutical regulator maintains stringent pharmacovigilance requirements that shape European prescribing confidence. Rhine-Ruhr and Bavarian pharmaceutical clusters concentrate formulation expertise for rapid-acting oral hypoglycemic development.
China
NMPA generic consistency evaluation timelines compress pricing power for originator molecules while expanding patient access to lower-cost alternatives. The country's national pharmaceutical regulator has accelerated bioequivalence certification for domestic repaglinide manufacturers. Yangtze River Delta pharmaceutical hubs concentrate active pharmaceutical ingredient production for global meglitinide supply.
Japan
Metabolic clinics favor nateglinide for elderly patients requiring tighter postprandial control without hypoglycemia risk accumulation. PMDA maintains distinct pancreatic safety evaluation frameworks that influence regional labeling requirements. Osaka and Tokyo pharmaceutical corridors anchor Kissei Pharmaceuticals' rapid-acting oral hypoglycemic specialization.
India
Production-linked incentive frameworks for active pharmaceutical ingredients attract cost-advantaged manufacturing relocation for generic meglitinide producers. CDSCO accelerated approval pathways for bioequivalent formulations expand domestic market penetration. Gujarat and Maharashtra pharmaceutical clusters concentrate contract manufacturing capacity for global generic supply.
Meglitinide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented capital requirements in the meglitinide space. Hospital formulary gatekeepers and retail pharmacy chains extract volume commitments that compress margins for secondary suppliers. Strategic archetypes include diabetes franchise incumbents with manufacturing scale, rapid-acting oral hypoglycemic specialists with deep chemistry expertise, and cardiometabolic channel players with established reimbursement relationships. Competitive moves center on fixed-dose combination development and direct distribution model expansion into retail pharmacy channels.
Among diabetes franchise incumbents, Novo Nordisk leverages manufacturing scale across analog and secretagogue portfolios, while Bristol Myers Squibb occupies a position within cardiometabolic channel relationships that extend formulary access. Kissei Pharmaceuticals exemplifies the rapid-acting oral hypoglycemic specialist archetype with concentrated expertise in pancreatic beta-cell pharmacology. These three anchors represent distinct competitive positioning vectors—scale-driven franchise breadth, channel-controlled reimbursement access, and deep chemistry specialization—rather than overlapping strategic territory.
| Leading Market Players |
|---|
| Biocon |
| Bristol Myers Squibb |
| Pfizer |
| Mylan |
| Novo Nordisk |
| Kissei Pharmaceuticals |
| Glenmark |
| Boehringer Ingelheim |
| Novartis |
| Others |
Supply & Pricing Matrix
Single-source dependency on Yangtze River Delta API manufacturers determines both the compressed margin spreads between originator and generic repaglinide tiers and the elongated payment term structures that characterize downstream procurement. FDA cardiovascular outcomes trial mandates add regulatory chokepoint costs that propagate through contract pricing indexation clauses.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate hospital procurement agreements for repaglinide formulations. Price differentiation hinges on bioequivalence certification tier under China's NMPA consistency evaluation framework and vertical integration depth of the formulator. Cost compression in generic tiers intensifies as Indian PLI-supported manufacturers enter with cost-advantaged API sourcing. Retail pharmacy chains exhibit highest price sensitivity due to automated prior authorization systems that flag cost-equivalent alternatives, while integrated delivery networks maintain lowest sensitivity through sole-source volume commitments.
Supply Chain Analysis
Extended payment terms from hospital group purchasing organizations now stretch to ninety days, forcing API suppliers into supply-chain finance facilities. Active pharmaceutical ingredient production concentrates in China, India, and Germany, with formulation finishing clustered in the United States and Japan. Raw material dependencies include potassium channel chemistry precursors, polymer coating substrates for modified-release formulations, and DPP-4 inhibitor co-formulants. Single-source vulnerability persists at the API level where three Yangtze River Delta contract manufacturers supply global repaglinide demand. Distribution runs through hospital pharmacy central procurement for acute initiation, with retail pharmacy chains capturing maintenance refill migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
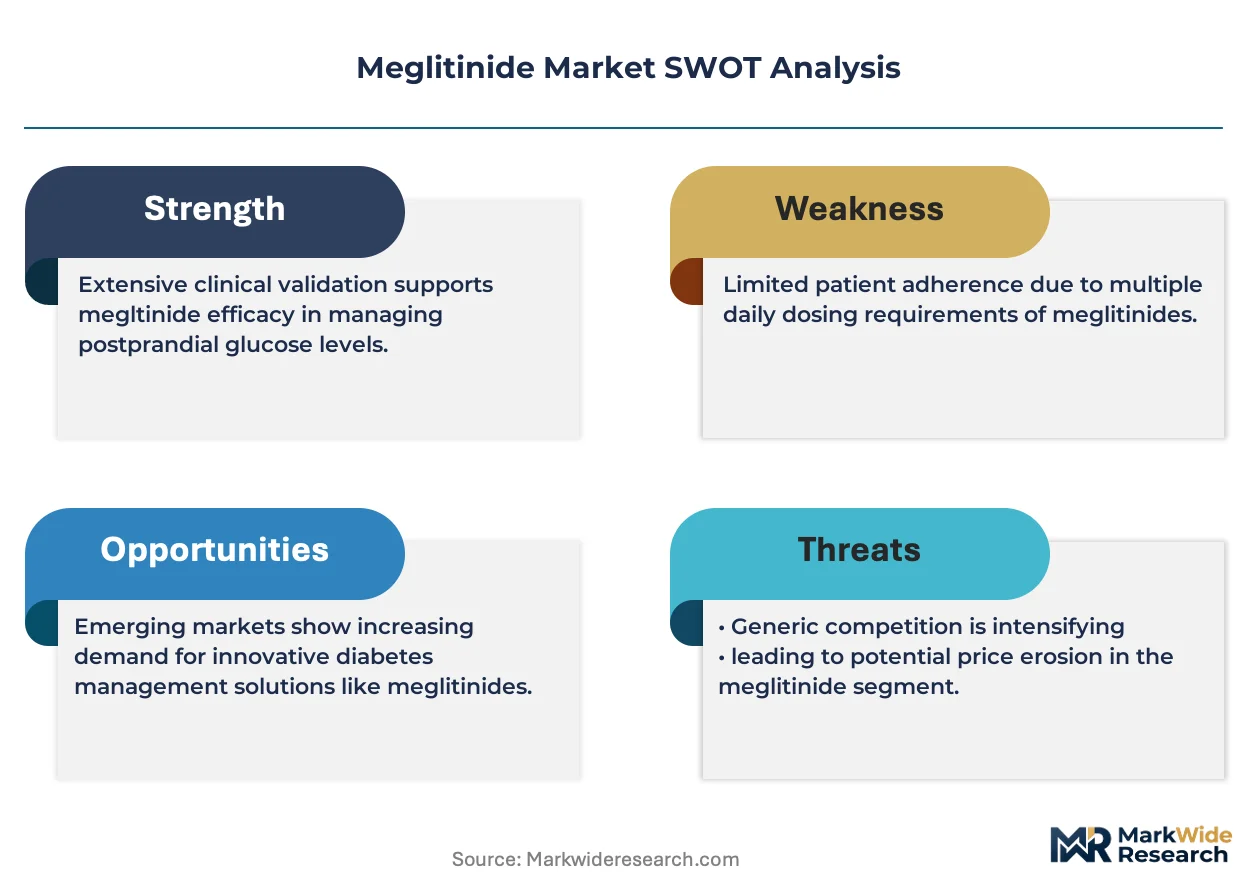
Sodium-glucose cotransporter-2 inhibitors with proven cardiovascular benefit present an existential substitution threat that meglitinide incumbents must navigate through combination product development and channel control reinforcement.
For Market Incumbents: Build regulatory data moats around fixed-dose combination formulations with DPP-4 inhibitors to defend against SGLT-2 displacement in maintenance therapy settings. Secure sole-source placement with integrated delivery networks through modified-release polymer coating capabilities that simplify nursing protocols. Add captive API capacity in India under PLI scheme alignment to reduce Yangtze River Delta concentration risk. For New Entrants and Emerging Players: Establish a beachhead in retail pharmacy direct distribution models for maintenance therapy refills, where hospital outpatient department control is eroding fastest. Target bioequivalent repaglinide certification under accelerated NMPA timelines to capture China's expanding generic substitution volume. Lead with automated prior authorization integration as the go-to-market wedge against incumbent formulary relationships. For Investors and Strategic Acquirers: Rapid-acting oral hypoglycemic specialists with deep pancreatic beta-cell pharmacology expertise represent the highest-conviction acquisition archetype in this space. Long-term viability hinges on combination product pipeline depth rather than standalone secretagogue exposure. Watch for EMA label expansion decisions on pancreatic safety as the inflection signal for European margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | DPP-4 inhibitor pairings with meglitinides capture multi-mechanism glycemic control demand from SGLT-2 substitution. |
| Modified-Release Formulation Investment | Polymer coating capabilities secure preferred vendor status with hospital discharge planners seeking adherence simplification. |
| API Manufacturing Relocation | India PLI scheme alignment reduces cost structures and single-source dependency on Chinese contract manufacturers. |
| Retail Pharmacy Channel Expansion | Direct distribution models capture margin from maintenance therapy migration away from hospital outpatient departments. |
| Regulatory Data Package Expansion | Continuous glucose monitoring endpoints in phase III protocols satisfy FDA post-2008 cardiovascular safety requirements. |
Research Methodology
The analysis maps meglitinide product types, application segments, and distribution channels, each validated through primary interviews with drug development executives, formulary directors at integrated delivery networks, hospital procurement managers, and regulatory affairs specialists at diabetes franchise incumbents. Secondary validation draws from FDA New Drug Application filings, EMA benefit-risk assessment documentation, NMPA generic consistency evaluation records, and ClinicalTrials.gov protocol registries. Bottom-up prescription volume modeling triangulates against top-down pharmaceutical market sizing from customs and trade data.
Assumptions held fixed across the projection horizon include FDA cardiovascular outcomes trial mandates, EMA pancreatic safety frameworks, and NMPA bioequivalence certification timelines; variables tested include SGLT-2 substitution rates, hospital formulary consolidation velocity, and retail pharmacy channel migration speed. Segmentation dimensions span product type, clinical application, end-user setting, and distribution channel, with regional regulatory clusters as a cross-cutting dimension. CAGRs derive from prescription volume trajectories by segment, adjusted for pricing compression under generic consistency evaluations and combination product premium capture.
Stress conditions across API supply disruption scenarios, accelerated SGLT-2 guideline preference shifts, and EMA label restriction outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market