
 Pygeum Bark Extract Market | 2026-2036
Pygeum Bark Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Pygeum Bark Extract Market Analytics
The pygeum bark extract market is shifting along a widening gap between certified-pharmaceutical grades and unstandardized commodity powders. Euromed leverages its vertical integration from African sourcing to European extraction to command premium positioning in regulated channels. Naturex anchors its competitive stance through deep R&D investment in marker compound standardization for dietary supplement clients. Alchem International competes on cost-optimized bulk supply to Asian manufacturers, occupying a fundamentally different margin tier.
Pygeum bark extract is a botanical preparation derived from Prunus africana bark, typically standardized to 13% total sterols including beta-sitosterol and campesterol, and employed primarily for lower urinary tract symptom management and anti-inflammatory formulations. Powder formulations dominate current volume flows, though capsule segments attract stronger margin pools as finished brands command retail price premiums. Liquid extracts are gaining traction among compounding pharmacies and functional beverage developers, while tincture demand remains niche, concentrated in traditional medicine practitioners and specialized herbalists.
FDA dietary supplement cGMP rules and EMA herbal monograph standards collectively elevate barrier costs for new entrants, forcing sustained investment in analytical validation and supply chain traceability. France's national phytotherapy reimbursement framework and Germany's Commission E tradition create divergent market access conditions within Europe. Stakeholders must monitor evolving pharmacovigilance requirements for botanical prostate health claims, as regulatory stringency in major consuming markets will increasingly determine which extract specifications remain commercially viable.
Market Dynamics
The Pygeum Bark Extract Market is bifurcating sharply between pharmaceutical-grade certified extracts and unstandardized commodity powders, with EMA herbal monograph tightening creating divergent compliance cost burdens across supplier tiers.
Growth Catalysts
- France's phytotherapy reimbursement framework:The national insurance coverage for prescription botanicals sustains patient access and physician prescribing rates for pygeum-based BPH therapies.
- Standardized extract demand from German pharmaceutical formulators:Commission E tradition drives procurement of 13% total sterol specifications for urinary tract symptom formulations.
- Compounding pharmacy expansion:Liquid extract formats gain traction among specialized pharmacies serving aging male populations seeking alternative delivery mechanisms.
Market Restraints
- Raw material concentration in Cameroon and Madagascar:Over 80% of wild Prunus africana harvest originates from limited East African range states, creating geopolitical and climate vulnerability.
- EMA heavy metal threshold compliance:Tightening limits on lead, cadmium, and arsenic in herbal monographs force costly purification upgrades for existing extraction facilities.
- Synthetic 5-alpha-reductase inhibitors:Finasteride and dutasteride formulations compete directly on efficacy claims and physician familiarity in reimbursed markets.
Strategic Opportunities
- Functional beverage channel development:Liquid extract integration into men's health positioned drinks targets preventive consumption among 40-55 demographic in North American wellness retail.
- CITES certification premium tier:Verified sustainable harvesting documentation commands 15-25% price premiums in environmentally screened European pharmacy chains.
- South Korean MFDS botanical drug pathway:Regulatory framework for standardized herbal extracts creates formal pharmaceutical registration opportunity distinct from supplement positioning.
Industry Challenges
- Phytochemical assay standardization:Variable beta-sitosterol/campesterol ratios across harvest batches complicate consistent certificate of analysis documentation for GMP auditors.
- Wild harvest supply chain reconfiguration:Transitioning from wild collection to cultivated Prunus africana requires 12-15 year maturation cycles and substantial nursery infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pygeum Bark Extract Market |
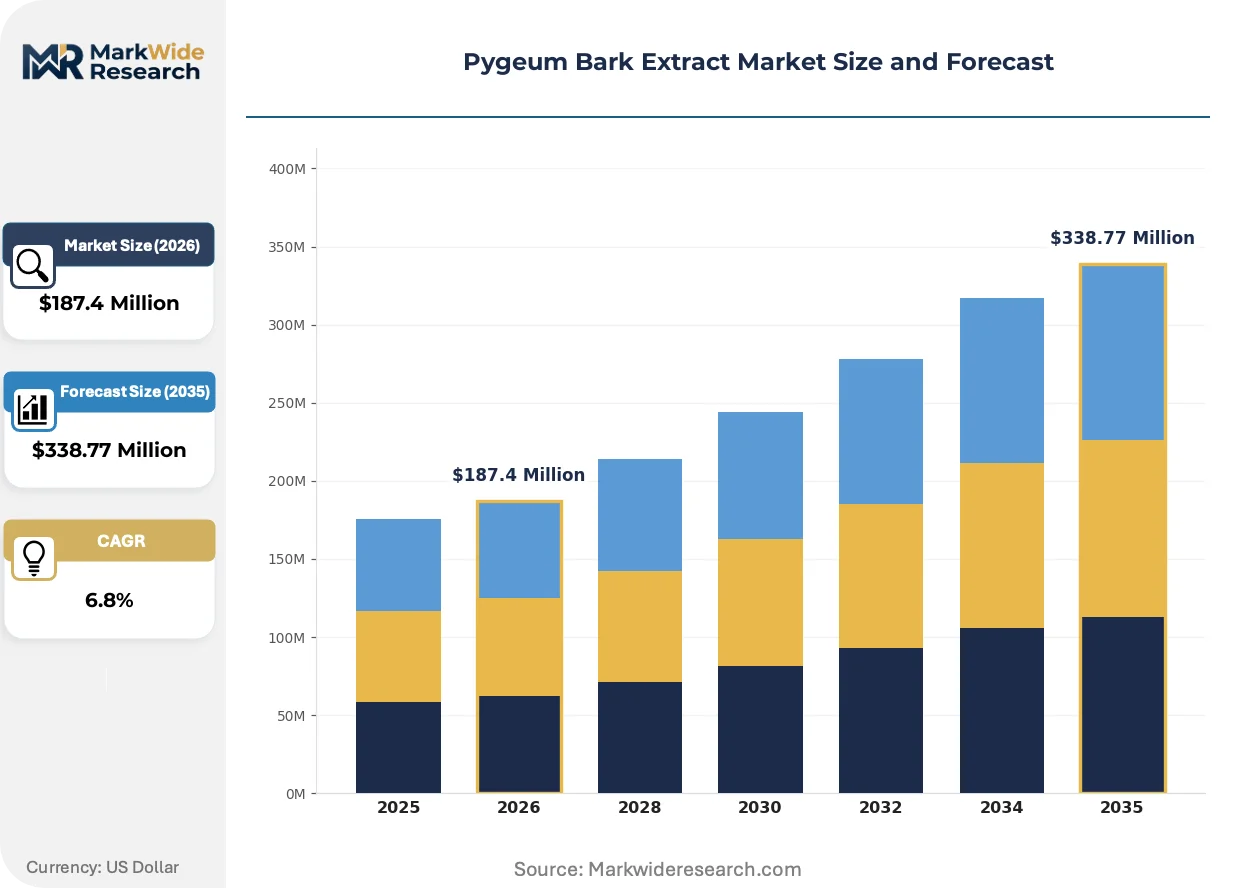
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Tincture Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Food & Beverages End User: Healthcare Providers, Retail Consumers, Manufacturers, Researchers Packaging Type: Bottles, Sachets, Blister Packs, Bulk Containers |
| Companies Covered | Naturex, Euromed, Maypro, Alchem International, Natural Field, Xi'an Herbking, Naturactive, Indena, Nature's Way, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pygeum Bark Extract Market Evolving Landscape
Extraction technology and regulatory documentation standards are reshaping competitive differentiation, with marker compound verification and sustainable sourcing traceability emerging as primary value drivers across supply tiers.
Supercritical CO2 extraction is integrating into mid-scale European processing facilities to replace traditional solvent-based methods. German and Swiss botanical manufacturers adopt this technology to meet residual solvent limits in revised pharmacopeial standards. The shift is compressing batch-to-batch variability while elevating capital requirements for market participation.
EMA's updated herbal monograph for Pygeum africanum bark tightens specifications for total sterol content and heavy metal thresholds. European extractors must retool analytical laboratories and purification stages to maintain compliance. French and Italian pharmaceutical clients now require third-party monograph certification as a procurement prerequisite, displacing informal quality assurances.
Specialized compounding pharmacies are consolidating procurement through direct relationships with certified African processors. This channel disintermediation bypasses traditional wholesale distributors in Germany and Austria. The pattern concentrates volume with vertically integrated suppliers capable of batch-specific documentation and shorter lead times.
Pygeum Bark Extract Market Segmentation
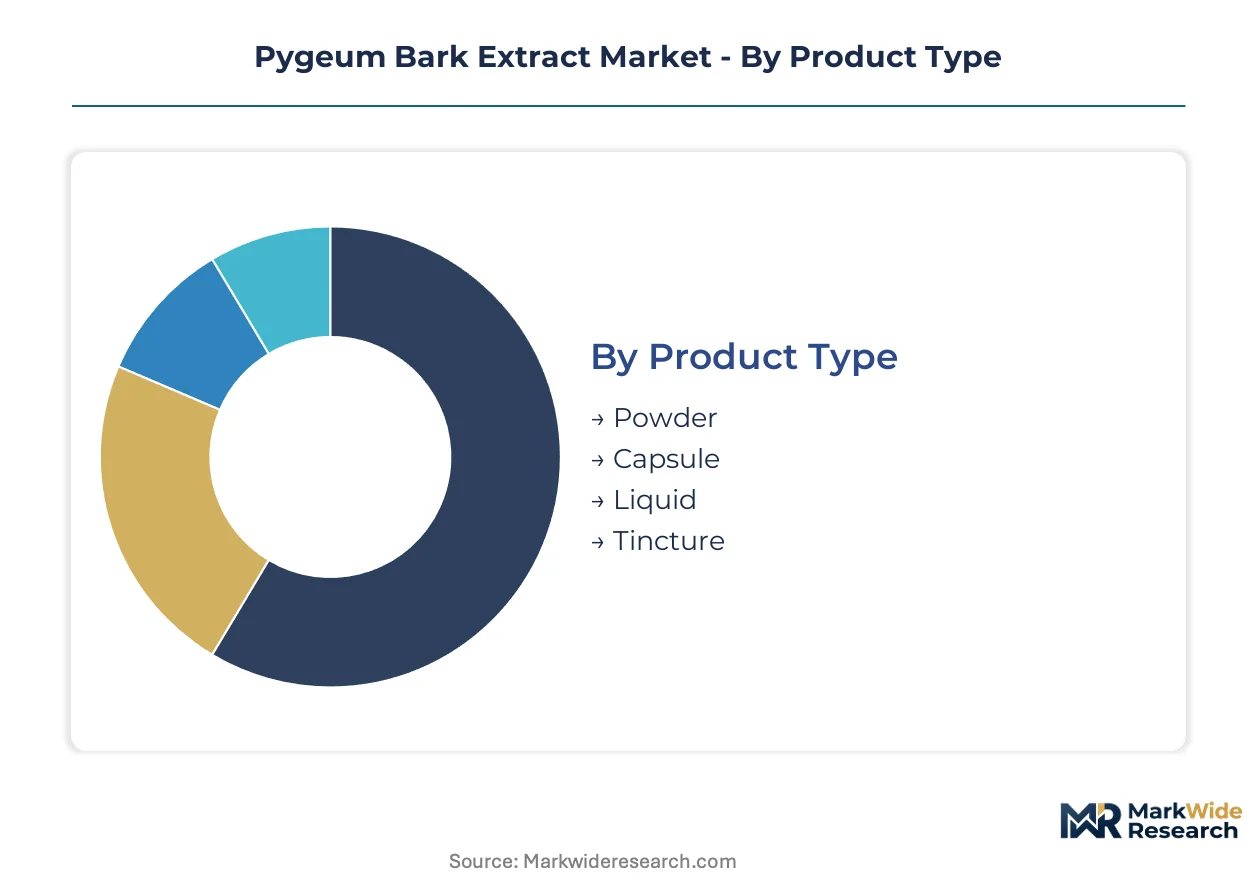
Pygeum bark extract segmentation reveals divergent margin architectures across delivery formats and procurement channels. Product specifications, application requirements, and packaging configurations each impose distinct compliance burdens and pricing power dynamics on suppliers.
Product Type:
Powder formats dominate volume throughput while liquid and capsule variants capture premium positioning through enhanced bioavailability claims and finished-form convenience.
- Powder:Unstandardized and standardized powders constitute the bulk of commercial flows, typically specified at 13% total sterols for pharmaceutical procurement. German formulators and Asian contract manufacturers absorb the majority of volume, though margin compression is severe due to commodity competition and minimal differentiation.
- Liquid:Hydroalcoholic extracts and glycerites serve compounding pharmacies and functional beverage developers seeking dose flexibility. French and North American wellness retail channels are expanding procurement, driven by preventive health positioning among aging male demographics seeking alternatives to solid dosage forms.
- Capsule:Hard-shell and soft-gel encapsulations command retail price premiums through finished-brand positioning. Quality documentation requirements from EMA herbal monograph compliance elevate barrier costs for suppliers serving European pharmacy chains.
- Tincture:Alcohol-based preparations remain niche, concentrated among traditional medicine practitioners and specialized herbalists in German-speaking markets with Commission E prescribing traditions.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquid.
Application:
Regulatory classification determines channel access, with pharmaceutical-grade extracts subject to EMA monograph standards and dietary supplement variants operating under less stringent quality benchmarks.
- Dietary Supplements:Capsule and tablet formats dominate this channel, with beta-sitosterol standardization serving as the primary quality marker. North American wellness retail and European direct-to-consumer e-commerce are expanding procurement, though FDA cGMP compliance costs pressure smaller suppliers.
- Pharmaceuticals:Prescription botanicals in France's reimbursed phytotherapy framework require batch-specific sterol assays and heavy metal documentation. German Commission E tradition sustains demand for standardized extracts in benign prostatic hyperplasia formulations, with ANSM and BfArM pharmacovigilance monitoring shaping claim permissibility.
- Cosmetics:Anti-inflammatory and skin-soothing applications utilize lower-concentration extracts in dermal preparations. South Korean and French cosmetic formulators are testing incorporation, though clinical substantiation requirements from European Cosmetics Regulation (EC) No 1223/2009 limit rapid scaling.
- Food & Beverages:Functional beverage developers in North American wellness retail are piloting liquid extract integration for men's health positioning. Novel food approval requirements from EFSA constrain European deployment, confining near-term growth to jurisdictions with more permissive botanical ingredient frameworks.
Established revenue concentration centers on Pharmaceuticals. Steepest expansion trajectory is emerging in Food & Beverages.
End User:
Procurement sophistication varies sharply, with healthcare providers demanding certificate of analysis documentation and retail consumers prioritizing brand recognition over technical specifications.
- Healthcare Providers:Urologists and general practitioners in France and Germany prescribe reimbursed phytotherapeutics, requiring suppliers to maintain EMA herbal monograph compliance and pharmacovigilance reporting capabilities.
- Retail Consumers:Direct purchasing through pharmacy chains and e-commerce platforms emphasizes finished-brand trust markers over extract specifications. French consumers exhibit strongest phytotherapy familiarity due to national reimbursement culture.
- Manufacturers:Contract supplement and pharmaceutical formulators in Germany, Switzerland, and India procure bulk extracts for further processing. Technical audits and supplier qualification requirements favor established extractors with captive African sourcing.
- Researchers:Academic and clinical trial procurement represents minimal volume but shapes future standardization protocols through pharmacokinetic and efficacy studies.
Volume concentration remains with Manufacturers. Quality specification leadership sits with Healthcare Providers.
Packaging Type:
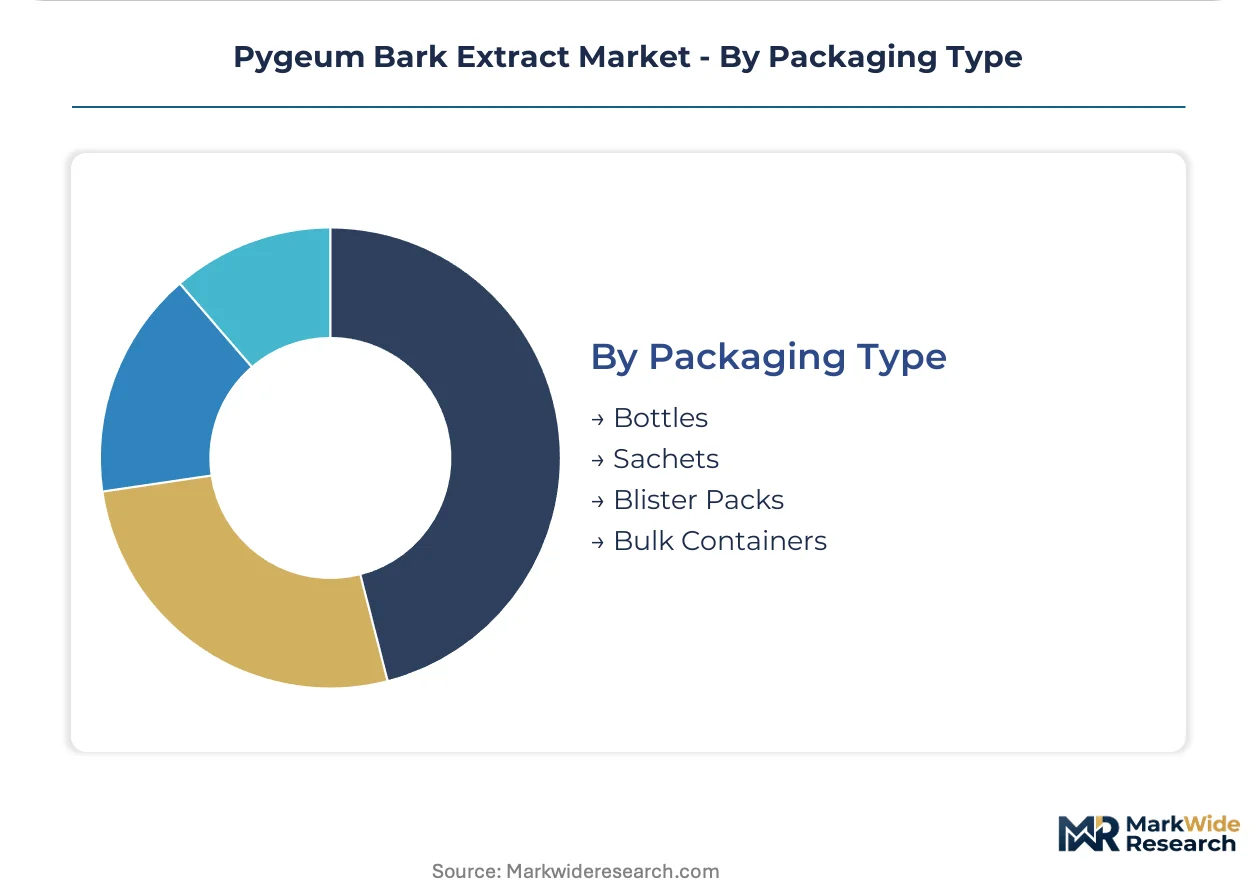
Packaging configuration directly influences shelf stability, dosing precision, and regulatory labeling requirements across distribution channels.
- Bottles:Amber glass and HDPE containers serve liquid extracts and bulk powder for compounding pharmacies and manufacturer procurement. German and Austrian pharmacy chains require child-resistant closures and tamper-evident seals.
- Sachets:Single-serve powder packets target travel and trial-size positioning in wellness retail. French and Italian direct-to-consumer brands are expanding sachet deployment for subscription model compatibility.
- Blister Packs:Unit-dose capsules for pharmaceutical and premium supplement channels support adherence tracking and oxidation protection. EMA packaging material compliance elevates qualification costs for film and foil suppliers.
- Bulk Containers:Fiber drums and multi-layer bags serve manufacturer-to-manufacturer supply, with CITES documentation and chain-of-custody seals mandatory for sustainable harvesting verification in environmentally screened European procurement.
Pharmaceutical-grade deployment favors Blister Packs. Supply chain efficiency drives concentration in Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marseille's port infrastructure anchors European import flows for pygeum bark raw material, with specialized cold storage facilities handling CITES-certified shipments from Cameroon and Madagascar before redistribution to extraction facilities across the continent.
France
Paris-based phytotherapy prescribing sustains reimbursed demand for standardized extracts, with ANSM pharmacovigilance frameworks shaping claim permissibility for benign prostatic hyperplasia indications. The national insurance coverage for prescription botanicals distinguishes France from neighboring markets. Lyon and Grenoble house compounding pharmacy networks expanding liquid extract procurement for aging male populations.
Germany
BfArM oversight of Commission E monographs drives pharmaceutical-grade specifications for urinary tract symptom formulations, with 13% total sterol standardization serving as procurement baseline. Commission E tradition embeds pygeum within urological practice guidelines. Bavaria's botanical extraction cluster around Munich and Nuremberg processes the majority of certified imports for domestic and export markets.
United States
FDA dietary supplement cGMP enforcement elevates analytical validation costs for domestic distributors, compressing margins for smaller operators while favoring established importers with captive African sourcing. Wellness retail channels in California and New York Metro pilot functional beverage applications targeting preventive consumption. NSF International and USP verification programs create tiered quality signaling for finished brands.
South Korea
MFDS botanical drug registration pathways offer formal pharmaceutical positioning distinct from dietary supplement classification, attracting Korean formulators seeking regulatory differentiation from commodity imports. Seoul-based pharmaceutical companies evaluate standardized extract partnerships for prostate health indications. The Busan-Ulsan manufacturing corridor provides extraction capacity for regional re-export to Japanese and Southeast Asian markets.
Italy
AIFA reimbursement negotiations for phytotherapeutics create variable market access conditions across regions, with northern pharmacy chains exhibiting stronger procurement of EMA-compliant extracts than southern counterparts. Milan and Turin serve as distribution hubs for Alpine-bordering markets. Swissmedic-aligned quality documentation from Italian processors facilitates cross-border supply into Swiss and Austrian pharmacy channels.
Pygeum Bark Extract Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across sharply tiered quality segments, with pharmaceutical-grade certification requiring captive African sourcing and European extraction assets while commodity traders operate through spot procurement and third-party toll processing. The market structure concentrates certified supply among three to four vertically integrated operators with CITES documentation capabilities and EMA-compliant laboratories. Strategic archetypes separate premium pharmaceutical certifiers, mid-tier supplement standardizers, and bulk commodity traders serving Asian contract manufacturers. Dominant competitive moves include backward integration into Cameroonian and Madagascan harvesting cooperatives and technology licensing for supercritical CO2 extraction replacement of solvent-based methods.
Within the premium pharmaceutical tier, Euromed anchors positioning through European extraction assets and EMA monograph compliance, while Indena represents Italian specialist capabilities in marker compound standardization. Alchem International occupies the scale-driven commodity segment with cost-optimized bulk supply orientation toward Asian manufacturers. Naturex exemplifies the mid-tier supplement standardizer archetype, bridging quality documentation requirements for North American wellness retail channels without full pharmaceutical certification burdens.
| Leading Market Players |
|---|
| Naturex |
| Euromed |
| Maypro |
| Alchem International |
| Natural Field |
| Xi'an Herbking |
| Naturactive |
| Indena |
| Nature's Way |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification divergence from commodity powders manifests in parallel pricing architectures and sourcing configurations, with EMA monograph compliance creating a 15-25% premium tier sustained by captive African harvesting cooperatives and European extraction assets while spot-market traders operate through third-party toll processing without traceability documentation.
Pricing Analysis
Value-based pricing anchors on therapeutic outcome verification through batch-specific sterol assays and heavy metal documentation, with French and German pharmaceutical formulators absorbing premium tiers for reimbursed BPH therapies while Asian contract manufacturers drive cost compression in unstandardized powder segments. Price differentiation stems from certification grade and volume scale, with CITES-verified sustainable harvesting commanding premiums in environmentally screened European pharmacy chains. Pricing pressure intensifies in commodity tiers due to synthetic 5-alpha-reductase inhibitor competition and raw material volatility. Retail consumers exhibit lowest price sensitivity for finished capsule brands, while bulk procurement managers at contract manufacturers negotiate aggressively on standardized powder specifications.
Supply Chain Analysis
Prunus africana bark supply rests on wild harvest operations concentrated in Cameroon and Madagascar, with over 80% of commercial volume originating from these East African range states before consolidation through Marseille port infrastructure for European redistribution. Extraction feedstock, hydroalcoholic solvents, and supercritical CO2 processing equipment constitute critical input dependencies. Single-source vulnerability from geopolitical instability and climate-driven harvest variability threatens supply continuity. Distribution runs through vertically integrated European processors serving pharmaceutical formulators, specialized compounding pharmacy networks, and wellness retail channels with divergent documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable operators, with EMA herbal monograph tightening and pharmacovigilance requirements forcing sub-scale extractors without captive African sourcing into exit or acquisition.
For Market Incumbents: Anchor market position through backward integration into Cameroonian and Madagascan harvesting cooperatives with CITES certification capabilities, while investing in supercritical CO2 extraction technology to meet tightening residual solvent limits in revised pharmacopeial standards. Synthetic pharmaceutical competition and raw material supply volatility represent primary threats requiring defensive capacity buffers. For New Entrants and Emerging Players: Enter via functional beverage channel partnerships in North American wellness retail, targeting the 40-55 male demographic with liquid extract formulations for preventive health positioning. South Korean MFDS botanical drug registration offers a regulatory-differentiated pathway distinct from saturated supplement markets, with compounding pharmacy networks providing lower barrier entry than pharmaceutical certification tiers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated botanical specialists seeking EMA-compliant laboratory assets and established African sourcing relationships. Five-to-ten year viability favors operators with demonstrated pharmacovigilance reporting capabilities and sustainable harvesting documentation. Watch for ANSM reimbursement policy adjustments as inflection signals for French market access profitability.| Strategic Initiative | Industry Significance |
|---|---|
| CITES Certification Program | Verified sustainable harvesting documentation unlocks 15-25% price premiums in European pharmacy chains. |
| Supercritical CO2 Technology Deployment | Replacement of solvent-based methods meets EMA residual solvent limits while compressing batch variability. |
| Backward Integration into Harvesting Cooperatives | Captive African sourcing secures supply continuity and quality traceability for pharmaceutical-grade certification. |
| MFDS Botanical Drug Registration | Formal pharmaceutical positioning in South Korea creates regulatory differentiation from commodity supplement imports. |
| Compounding Pharmacy Channel Development | Direct relationships with specialized pharmacies bypass wholesale distributors and concentrate volume with documentation-capable suppliers. |
Research Methodology
Multi-period observation of EMA herbal monograph revisions, French phytotherapy reimbursement policy adjustments, and CITES certification adoption rates anchored the trend analysis, supplemented by interviews with extraction facility technical directors, pharmaceutical formulator procurement leads, compounding pharmacy network managers, and African harvesting cooperative coordinators. Secondary validation drew from EMA submissions, ANSM pharmacovigilance reports, CITES trade database records, and customs documentation through Marseille port authorities. Bottom-up volume modeling from individual processor capacities and top-down demand calibration from national reimbursement statistics were triangulated for consistency.
Input-output matrices structured the analytical framework across product type, application classification, end-user procurement sophistication, and regional regulatory cluster dimensions over the projection horizon. CAGRs were derived from segmented growth rate differentials weighted by revenue concentration, with sterol standardization protocol adoption curves and synthetic pharmaceutical substitution elasticity serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EMA heavy metal threshold revisions or Prunus africana wild harvest restrictions. Assumptions regarding cultivation transition timelines and reimbursement policy continuity shape output sensitivity. A small set of named triggers—ANSM phytotherapy framework adjustments, MFDS botanical drug pathway implementation pace, and supercritical CO2 capital expenditure cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Magtein Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Tetrahydropalmatine Market