
 Oral Clinical Nutrition Supplements Market | 2026-2036
Oral Clinical Nutrition Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Clinical Nutrition Supplements Market Outlook
Market Context
Homecare patient demand is unwinding the historical hospital-centric procurement model that long dominated oral clinical nutrition distribution. Abbott Nutrition leverages its direct-to-patient logistics infrastructure to sustain recurring revenue streams outside institutional channels. Nestle Health Science anchors its portfolio in disease-specific formulations, competing against commodity-oriented suppliers. Danone Nutricia differentiates through specialized metabolic products that command premium positioning in outpatient protocols.
Technical Definition and Segment Structure
Oral clinical nutrition supplements comprise medically formulated ingestible products delivering calibrated macronutrients, micronutrients, and bioactive compounds under healthcare supervision, typically manufactured through aseptic liquid processing or controlled-atmosphere powder blending to meet pharmacopeial purity standards. Ready-to-drink liquid formats dominate hospital procurement due to dosing precision and contamination control, while powder supplements capture the fastest expansion in homecare settings where storage flexibility and cost efficiency matter. Malnutrition applications occupy the largest revenue pool, though post-surgery recovery segments generate superior per-patient margins as protocols extend beyond acute episodes.
Regulatory Framework
The FDA maintains Current Good Manufacturing Practice requirements for medical foods, while the EMA's Food for Special Medical Purposes framework governs compositional claims and labeling across European markets. Japan's Ministry of Health, Labour and Welfare applies distinct FOSHU and medical food classifications that create dual compliance pathways for entrants. Stakeholders must monitor evolving reimbursement eligibility criteria as payers scrutinize clinical outcome evidence before approving coverage for premium formulations.
Market Dynamics
Reimbursement frameworks are unwinding hospital-centric procurement models across major markets, redirecting patient volume toward homecare channels and forcing suppliers to rebuild distribution infrastructure around direct-to-patient logistics rather than institutional contracts.
Growth Catalysts
- Japan's FOSHU framework:Dual classification pathways for medical foods and functional health claims accelerate product registration timelines for qualified entrants. Manufacturers leverage this regulatory clarity to compress market entry cycles.
- Ready-to-drink liquid processing:Aseptic manufacturing advances reduce contamination risk profiles while enabling extended shelf stability without refrigeration. Hospital procurement teams prioritize these formats for dosing precision in acute protocols.
- German outpatient reimbursement:Statutory health insurance expansions for domiciliary nutrition therapy sustain recurring prescription volumes outside institutional settings. This policy shift anchors recurring revenue streams for compliant suppliers.
Market Restraints
- Whey protein isolate volatility:Dairy commodity price swings compress formulation margins for high-protein clinical products. Manufacturers absorb input cost spikes or reformulate toward plant-based alternatives with inferior amino acid completeness.
- EMA compositional rigidity:Food for Special Medical Purposes frameworks restrict label claims and bioactive ingredient inclusion levels. Product developers face extended reformulation cycles to achieve compliance without clinical efficacy compromise.
- Hospital formulary concentration:Group purchasing organizations consolidate procurement authority across health systems. Smaller suppliers confront exclusion risk without scale to meet contract minimums or rebate structures.
Strategic Opportunities
- Post-surgery recovery protocols:Extended nutrition interventions beyond acute episodes generate superior per-patient margins compared to malnutrition management. Formulators target immunonutrition and wound healing-specific compositions.
- Subscription-based homecare delivery:Direct-to-patient platforms bypass traditional wholesale distribution. Logistics investments capture recurring revenue while building adherence data for payer negotiations.
- EMA-REACH convergence:Harmonized contaminant thresholds and packaging material safety standards reduce dual-compliance burdens for pan-European suppliers. Early alignment with integrated requirements accelerates multi-market launches.
Industry Challenges
- Enteral-grade certification timelines:Pharmacopeial purity validation for aseptic liquid processing extends facility qualification periods. Capital remains deployed without revenue generation during extended regulatory review.
- Legacy ERP integration:Direct-to-patient channels require real-time inventory visibility and cold-chain traceability that incumbent systems cannot support. Technology migrations disrupt operations during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Clinical Nutrition Supplements Market |
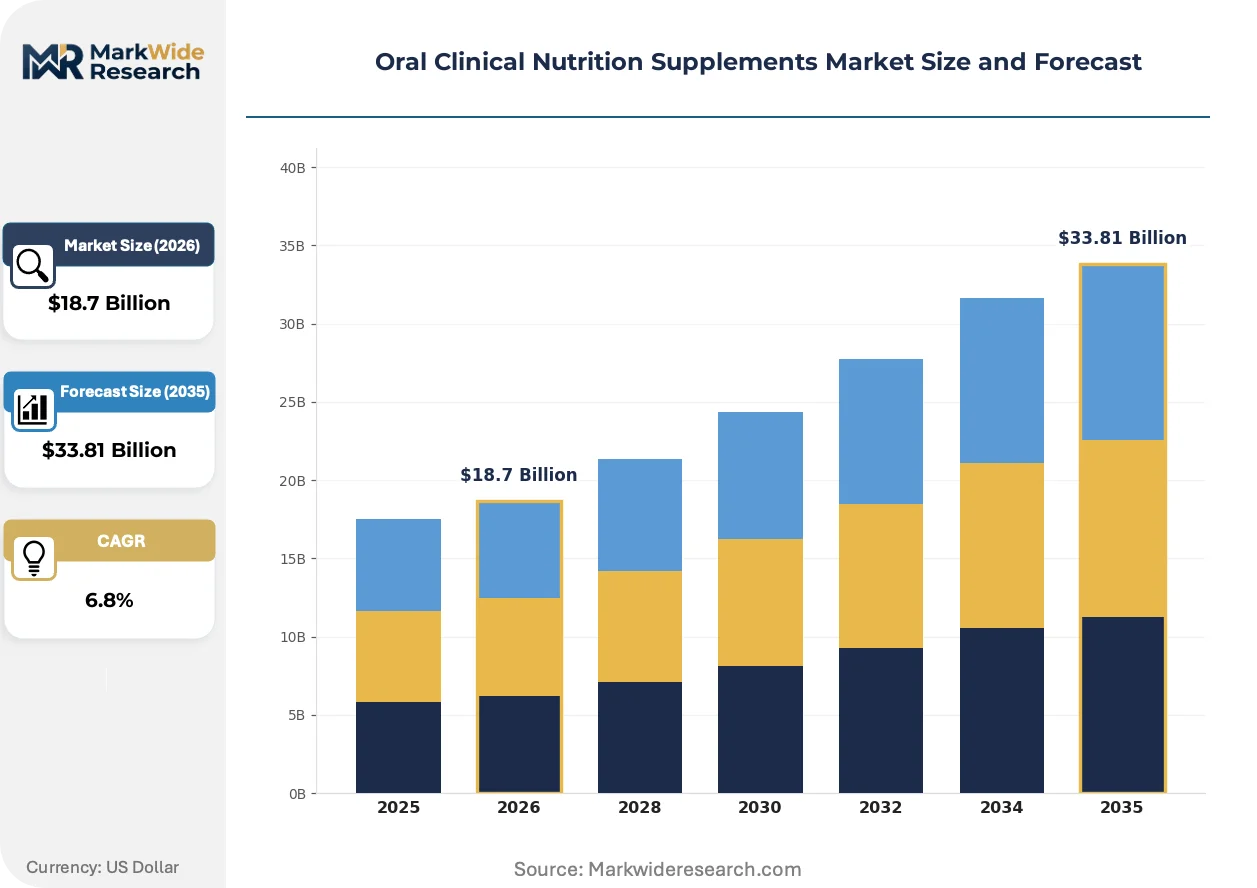
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Supplements, Powder Supplements, Ready-to-Drink, Nutrition Bars End User: Hospitals, Long-term Care Facilities, Homecare Patients, Outpatients Application: Malnutrition, Weight Management, Chronic Diseases, Post-surgery Recovery Formulation: High Protein, Low Sugar, Fiber-enriched, Gluten-free |
| Companies Covered | Abbott Nutrition, Nestle Health Science, Danone Nutricia, Fresenius Kabi, B. Braun, Mead Johnson Nutrition, GlaxoSmithKline, Nestlé S.A., Pfizer Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Clinical Nutrition Supplements Market Strategic Shifts
Formulation science and patient-interface design are converging to reshape how clinical nutrition products are developed, regulated, and consumed across care settings. Three distinct vectors are compressing traditional competitive advantages.
Microencapsulation technology for bioactive compounds is displacing conventional powder blending methods that degrade sensitive ingredients through thermal exposure and oxidation. Pediatric and geriatric formulation specialists adopt these processes to preserve probiotic viability and omega-3 structural integrity through shelf life. This capability is displacing commodity suppliers who lack pharmaceutical-grade processing infrastructure or in-house particle engineering expertise.
REACH regulation amendments targeting packaging material migration limits are forcing reformulation of multilayer carton and bottle structures used in ready-to-drink products. Industrial consequence includes accelerated validation cycles for alternative barrier materials and supplier qualification costs that favor integrated packaging operations. Liquid format manufacturers with European distribution exposure are responding by vertically controlling primary packaging specification and testing protocols.
Homecare patients now initiate therapy selection through digital health platforms that aggregate formulary coverage, flavor preference, and delivery scheduling. This channel is compressing traditional physician-directed prescribing and pharmacy fulfillment models. The United States exhibits the most visible disruption as Medicare Advantage plans deploy remote monitoring incentives that tie nutrition adherence to risk-adjusted reimbursement rates.
Oral Clinical Nutrition Supplements Market Segmentation
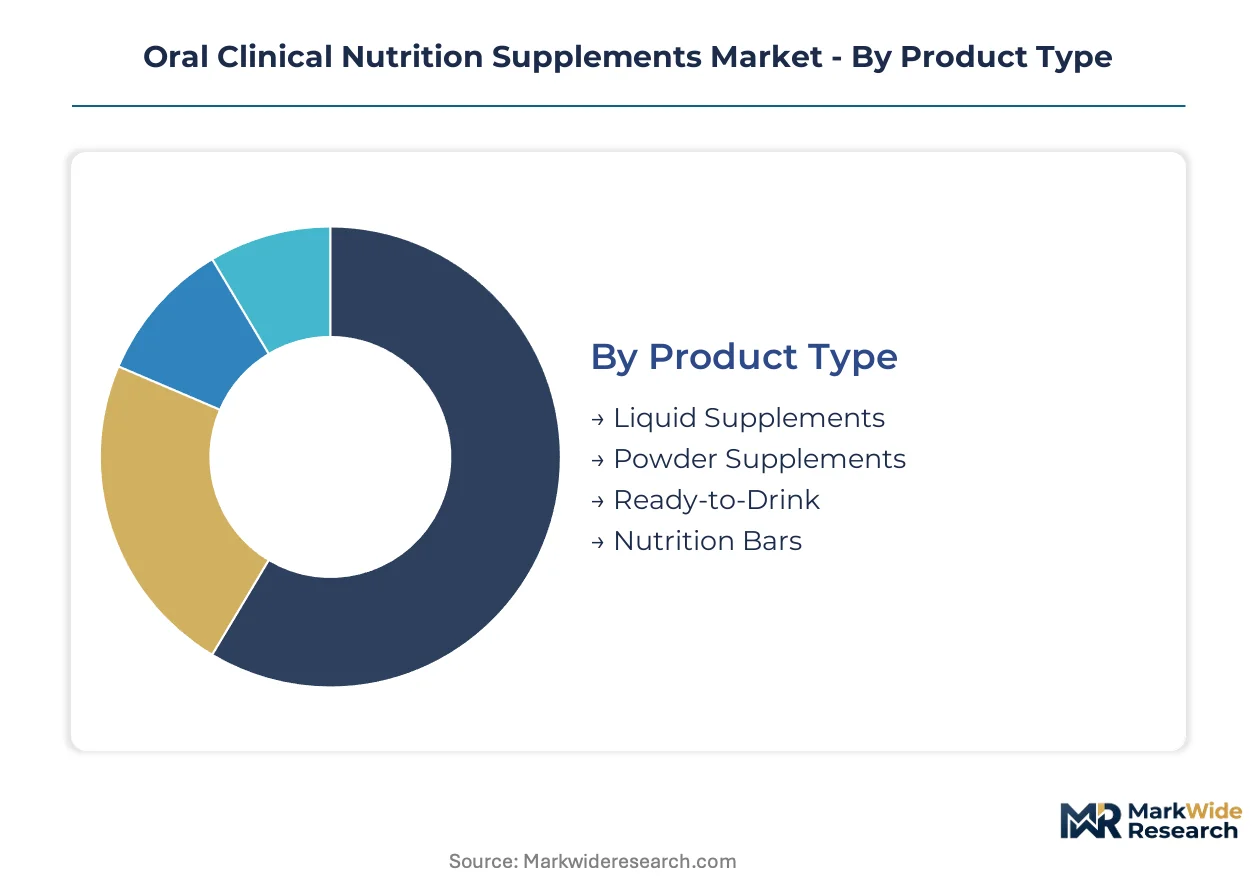
Segmentation in oral clinical nutrition supplements reveals divergent competitive dynamics across product formats, care settings, and therapeutic applications. Procurement authority and reimbursement eligibility vary sharply by channel, forcing suppliers to optimize for distinct margin structures and compliance burdens simultaneously.
Product Type:
Ready-to-drink liquid formats face the strongest substitution pressure from powder alternatives as homecare cost sensitivity intensifies, while aseptic processing investments create defensive moats for incumbent manufacturers.
- Liquid Supplements:Aseptically processed enteral-grade formulations deliver precise macronutrient dosing through multilayer barrier packaging. Hospital procurement teams in Germany and Japan prioritize these formats for contamination control in acute protocols, though refrigeration requirements constrain distribution reach.
- Powder Supplements:Controlled-atmosphere blending enables extended ambient shelf stability and freight cost efficiency. Homecare adoption accelerates fastest in United States Medicare Advantage networks where patients self-administer and storage flexibility reduces logistics overhead.
- Ready-to-Drink:Single-serve tetra-pak and bottle formats dominate institutional contracts requiring minimal preparation.
- Nutrition Bars:Solid oral formats compete with conventional food fortification in outpatient weight management protocols.
Liquid Supplements anchors the volume base while Powder Supplements gains share at the steepest rate.
End User:
Cost tier stratification separates acute institutional buyers from recurring homecare subscribers, with reimbursement policy determining accessible price points across channels.
- Homecare Patients:Direct-to-patient logistics platforms enable subscription-based replenishment with adherence monitoring. United States reimbursement expansion toward outpatient models redirects patient volume from hospital discharge into domiciliary protocols, building recurring revenue streams for compliant suppliers.
- Hospitals:Group purchasing organization consolidation concentrates procurement authority across integrated delivery networks. Formulary inclusion demands pharmacopeial-grade manufacturing documentation and rebate structures that exclude smaller entrants.
- Long-term Care Facilities:Skilled nursing operators balance dysphagia-appropriate texture modifications against per-diem cost constraints.
- Outpatients:Clinic-based dispensing bridges acute episodes with home transition, capturing prescription volumes before channel shift.
Hospitals retains the largest absolute prescription volume while Homecare Patients climbs fastest as reimbursement frameworks unwind institutional bias.
Application:
Margin concentration concentrates in extended-intervention indications where clinical outcome data supports premium pricing negotiations with payers.
- Post-surgery Recovery:Immunonutrition formulations targeting wound healing and infection resistance command superior per-patient margins through extended protocol duration. Japanese and German reimbursement frameworks explicitly cover domiciliary immunonutrition for major abdominal surgery, anchoring addressable demand.
- Malnutrition:Protein-energy malnutrition protocols represent the largest treated population across geriatric and oncology populations. Commodity-oriented competition compresses pricing, though disease-specific compositions preserve differentiation in cancer cachexia subsegments.
- Chronic Diseases:Diabetes and renal failure drive demand for micronutrient-modified formulations with restricted electrolyte or carbohydrate profiles.
- Weight Management:Bariatric surgery pre- and post-operative protocols create episodic demand with adherence monitoring requirements.
Malnutrition underpins the broadest patient base while Post-surgery Recovery expands most quickly as protocols lengthen beyond acute episodes.
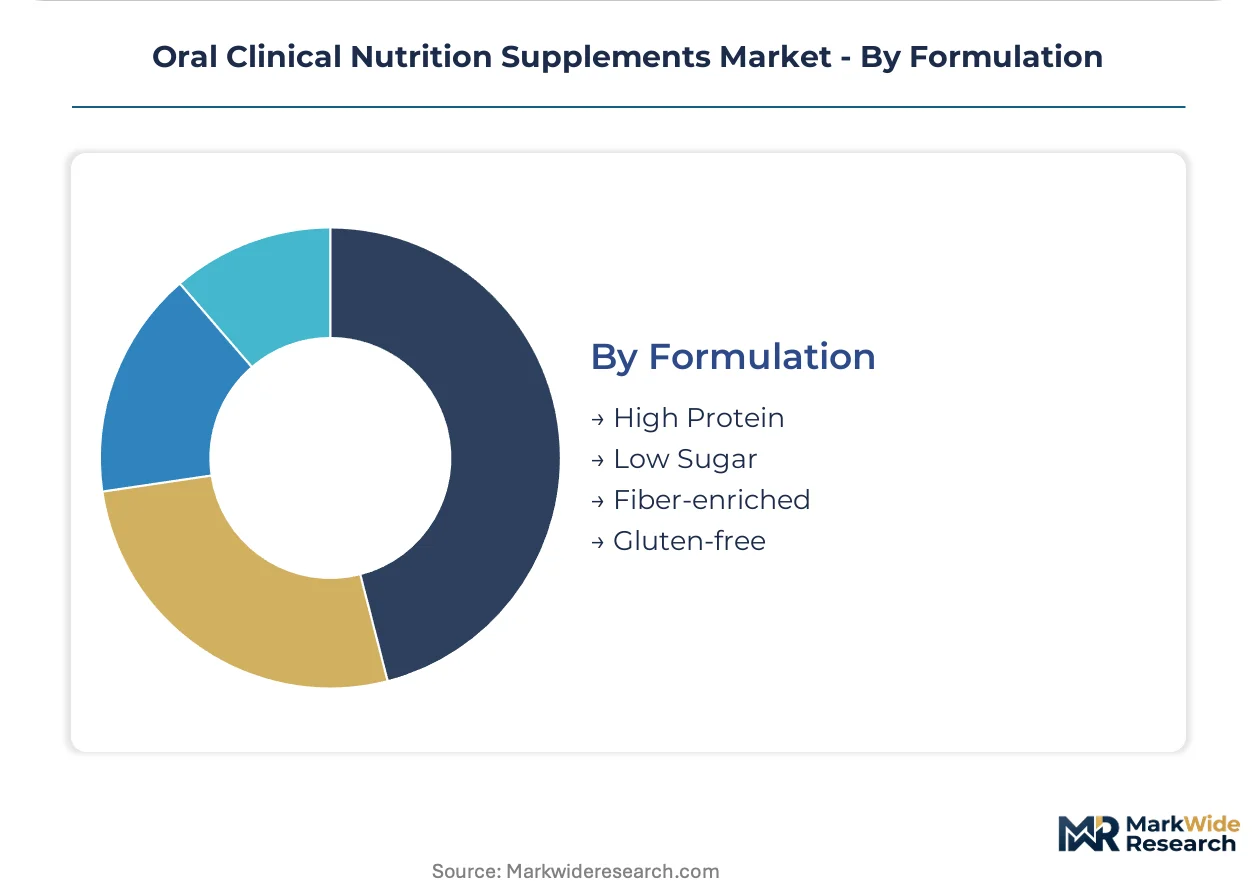
Formulation:
Supply concentration in dairy-derived protein isolates exposes high-protein segments to commodity volatility, accelerating plant-based alternative development with amino acid fortification.
- High Protein:Whey and casein-based formulations delivering 15-20g protein per serving dominate sarcopenia and oncology applications. Dairy commodity price swings force reformulation toward pea and rice protein blends with enzymatic amino acid completeness enhancement.
- Low Sugar:Glycemic-controlled compositions target diabetes and metabolic syndrome populations with non-nutritive sweetener systems. FDA and EMA scrutiny of alternative sweetener labeling claims extends product development timelines.
- Fiber-enriched:Prebiotic supplementation addresses gut microbiome modulation in immunocompromised and antibiotic-exposed patients.
- Gluten-free:Celiac disease and wheat sensitivity protocols require certified allergen-control manufacturing with third-party validation.
High Protein generates the largest formulation volume while Low Sugar attracts the steepest development investment as metabolic disease prevalence climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany and Japan concentrate the highest per-patient spending on enteral-grade formulations, while United States reimbursement expansion redirects patient volume toward domiciliary channels. Payer archetypes diverge sharply across these three markets, forcing suppliers to maintain parallel compliance and logistics infrastructures.
United States
Medicare Advantage plans deploy remote monitoring incentives that tie nutrition adherence to risk-adjusted reimbursement rates, accelerating homecare channel shift. The FDA maintains Current Good Manufacturing Practice requirements for medical foods, with recent guidance tightening pharmacopeial purity documentation. Greater Boston anchors specialized immunonutrition research clusters where academic medical centers pilot extended post-surgical protocols.
Germany
Statutory health insurance expansions for domiciliary nutrition therapy sustain recurring prescription volumes outside institutional settings, building predictable revenue streams for compliant suppliers. The EMA's Food for Special Medical Purposes framework governs compositional claims and labeling, with REACH amendments now targeting packaging material migration limits. North Rhine-Westphalia concentrates aseptic liquid processing capacity serving pan-European distribution networks.
Japan
Aging demographics and chronic disease prevalence sustain clinical nutrition protocol penetration rates exceeding Western benchmarks. The Ministry of Health, Labour and Welfare applies distinct FOSHU and medical food classifications that create dual compliance pathways, compressing registration timelines for qualified entrants. Kanto region manufacturing clusters specialize in microencapsulation technology for bioactive compound preservation.
United Kingdom
NHS Integrated Care Systems consolidate procurement authority across regional networks, favoring suppliers with pharmacopeial-grade documentation and rebate structures. The Medicines and Healthcare products Regulatory Agency aligns with EMA Food for Special Medical Purposes standards post-Brexit transition. London/Southeast corridor hosts disease-specific formulation specialists targeting oncology cachexia subsegments.
Australia
Private health insurance funds increasingly cover oral clinical nutrition supplements for post-surgical recovery, expanding addressable demand beyond public hospital formularies. The Therapeutic Goods Administration applies medical device and food classification boundaries that require careful product positioning. New South Wales anchors regional distribution hubs serving Asia-Pacific export markets with ambient-stable powder formulations.
Oral Clinical Nutrition Supplements Market Competitive Environment
Player mix skews toward diversified nutrition conglomerates with pharmaceutical-grade manufacturing infrastructure, creating tiered competitive dynamics where scale-driven procurement advantages separate institutional contract winners from homecare specialists. Market structure concentrates around three strategic archetypes: disease-specific formulation developers, direct-to-patient logistics operators, and commodity-oriented suppliers competing on rebate structures. Dominant competitive moves include backward integration into aseptic liquid processing capacity and strategic partnerships with Medicare Advantage plans for adherence data capture.
Within the diversified nutrition conglomerate tier, Abbott Nutrition and Nestle Health Science exemplify contrasting strategic positioning. Abbott leverages direct-to-patient logistics infrastructure to sustain recurring revenue streams outside institutional channels, while Nestle anchors its portfolio in disease-specific formulations competing against commodity-oriented suppliers. Danone Nutricia occupies a distinct position through specialized metabolic products commanding premium positioning in outpatient protocols. These three entities collectively represent the competitive archetypes reshaping procurement authority across hospital, homecare, and long-term care channels.
| Leading Market Players |
|---|
| Abbott Nutrition |
| Nestle Health Science |
| Danone Nutricia |
| Fresenius Kabi |
| B. Braun |
| Mead Johnson Nutrition |
| GlaxoSmithKline |
| Nestlé S.A. |
| Pfizer Nutrition |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with whey protein suppliers lock in both raw material access and margin visibility for oral clinical nutrition manufacturers facing dairy commodity volatility. These arrangements insulate formulators from spot market swings while constraining flexibility to pivot toward plant-based alternatives as cost pressures mount.
Pricing Analysis
Cost-plus contracts indexed to dairy commodity benchmarks dominate procurement between manufacturers and protein isolate suppliers. Three-tier pricing structure across enteral-grade, medical food, and standard nutritional tiers separates hospital formulary products from retail-accessible alternatives. Pricing pressure stems from German statutory insurance reimbursement caps tightening per-diem allowances for domiciliary nutrition. Homecare patients exhibit highest price sensitivity as out-of-pocket exposure rises, while hospital procurement teams prioritize pharmacopeial documentation over unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability across Asia-Europe trade lanes. Manufacturing concentrates in Germany, the United States, and Japan where aseptic liquid processing capacity clusters. Whey protein isolate, omega-3 concentrates, and microencapsulated probiotics constitute critical input dependencies. Single-source vulnerability runs through New Zealand and Australian dairy protein suppliers. Distribution runs through direct-to-patient platforms alongside traditional wholesale channels serving institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of pharmaceutical-grade aseptic processing capability constrains competitive entry and sustains incumbent pricing power. Formulation science expertise in bioactive compound stabilization represents the decisive capability gap separating market leaders from commodity suppliers.
For Market Incumbents: Compound formulary lock-in through extended post-surgical protocol evidence generation, while securing backward integration into microencapsulation capacity. Plant-based protein sourcing diversification hedges against dairy commodity volatility threatening margin compression. Prioritize adherence data capture from Medicare Advantage partnerships to defend reimbursement eligibility against emerging biosimilar nutrition competitors. For New Entrants and Emerging Players: Japan's FOSHU certification fast-track compresses registration timelines versus EMA medical food pathways. Target homecare powder supplements where storage flexibility and cost efficiency attract price-sensitive patients outside hospital procurement concentration. Deploy digital health platform partnerships to bypass traditional physician-directed prescribing and capture subscription-based recurring revenue. For Investors and Strategic Acquirers: Disease-specific formulation developers with immunonutrition IP and proven clinical outcome data represent the most defensible acquisition archetype. Five-to-ten year viability hinges on reimbursement expansion sustaining outpatient protocol coverage. Monitor EMA-REACH packaging material harmonization progress as inflection indicator for pan-European multi-market launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Capacity Expansion | Enteral-grade certification barriers protect qualified manufacturers from commodity competition. |
| Direct-to-Patient Platform Development | Medicare Advantage adherence incentives redirect prescription volume outside hospital channels. |
| Microencapsulation Technology Licensing | Bioactive compound preservation capabilities command premium positioning in immunonutrition segments. |
| Japanese FOSHU Registration Pathway | Dual classification framework accelerates market entry versus European medical food compliance. |
| Plant-Based Protein Reformulation | Amino acid fortification advances reduce dairy commodity exposure while meeting clinical completeness standards. |
Study Parameters
A spread of perspectives from hospital procurement managers, formulary directors, regulatory affairs leads at nutrition manufacturers, and payer access specialists converged on the working assumptions. Primary interview insights combined with FDA medical food guidance documents, EMA Food for Special Medical Purposes registrations, Japanese MHLW FOSHU approvals, and hospital GPO contract databases. Bottom-up prescription volume modeling and top-down expenditure triangulation validated segment-level outputs.
Segmentation dimensions modeled span product format, care setting, therapeutic application, and formulation composition across the analysis window. CAGRs derived from patient population growth, protocol penetration rates, and reimbursement expansion trajectories. Forecast inputs incorporate aging demographic projections, chronic disease prevalence curves, and regulatory pathway timeline assumptions specific to medical food and FOSHU classifications.
Decision-makers should treat outputs as directional under base assumptions of continued outpatient reimbursement expansion and stable dairy protein supply; material deviation would warrant model refresh. Forecasts reflect documented assumptions regarding EMA-REACH convergence timing and Medicare Advantage remote monitoring incentive durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Sleep Supplement Market
Dietary Supplements
Mediterranean Mood and Stress Support Complexes Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Pediatric Supplements Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Fertility Supplements Market