
 Prescription Drugs Market | 2026-2036
Prescription Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Drugs Market Intelligence
The proliferation of AI-driven drug discovery and development platforms is fragmenting traditional, linear R&D models. This shift enables faster candidate screening and biomarker identification. Pfizer leverages its vast manufacturing and distribution network to commercialize blockbuster drugs at scale. F. Hoffmann-La Roche Ltd differentiates through its leadership in diagnostics-led personalized oncology treatments, while AstraZeneca expands its portfolio in complex biologics.
Prescription drugs are pharmaceutical compounds requiring a licensed healthcare professional's authorization for dispensation. These substances are formulated with specific active pharmaceutical ingredients to interact with biological targets and achieve a therapeutic effect. Within therapy areas, oncology and neurology command the highest R&D investment, leading to premium pricing. The drug type landscape shows biologics, including advanced antivirals and immunosuppressants, capturing share from traditional drugs.
Market access is governed by stringent regulatory bodies such as the US FDA, the European Medicines Agency (EMA), and Japan's PMDA. These agencies' requirements for extensive clinical trial data and GMP-compliant manufacturing directly influence development costs and market entry timelines. Successfully aligning drug pipelines with the evolving evidentiary standards of payers and health technology assessment bodies remains a critical challenge for manufacturers.
Market Dynamics
The convergence of diagnostics and therapeutics is the central force reshaping the prescription drug market. This shift toward personalized medicine, where treatment is tailored to individual patient biomarkers, is altering R&D priorities, regulatory pathways, and commercial models away from one-size-fits-all blockbuster drugs.
Growth Catalysts
- Regulatory Modernization:The FDA's accelerated approval and breakthrough therapy designations shorten development timelines for drugs addressing unmet medical needs, particularly in oncology and rare diseases, encouraging investment in novel therapies.
- Aging Demographics:Advanced economies, notably Japan and Germany, face rapidly aging populations, which increases the prevalence of chronic conditions like cardiovascular disease and neurodegenerative disorders, sustaining demand for long-term medications.
- AI in Drug Discovery:The application of artificial intelligence and machine learning platforms enables rapid screening of compound libraries and identification of novel biological targets, significantly accelerating the pre-clinical phase of drug development.
Market Restraints
- Patent Expiration:The recurring "patent cliff" exposes blockbuster drugs to generic and biosimilar competition, leading to steep and rapid revenue erosion for originator companies and pressuring investment in new R&D.
- Stringent Clinical Requirements:Regulatory bodies like the European Medicines Agency (EMA) mandate extensive and costly clinical trials to prove safety and efficacy, creating high barriers to entry and long development cycles.
- High R&D Investment:The development of complex biologics, cell therapies, and gene therapies requires substantial capital investment with a high rate of failure, concentrating market power among large, well-capitalized firms.
Strategic Opportunities
- Orphan Drug Development:Regulatory incentives, such as market exclusivity provisions under the US Orphan Drug Act, create commercially attractive opportunities for developing treatments for rare diseases with small patient populations.
- Emerging Market Expansion:Rising disposable incomes and expanding government healthcare coverage in countries like China and Brazil create new, large-scale markets for both innovative and established prescription medicines.
- Gene Editing Technologies:Platforms like CRISPR-Cas9 offer the potential to develop curative therapies for a range of genetic disorders, representing a paradigm shift from chronic treatment to one-time intervention.
Industry Challenges
- Payer and HTA Scrutiny:Gaining favorable reimbursement decisions from health technology assessment (HTA) bodies requires increasingly sophisticated real-world evidence, complicating market access for high-priced specialty drugs.
- Biomanufacturing Complexity:Scaling up production for biologics and cell therapies while maintaining GMP compliance presents significant technical and logistical hurdles, creating potential supply bottlenecks for new treatments.
- Data Science Talent Gap:A shortage of bioinformaticians and data scientists capable of analyzing large, complex datasets from clinical trials and genomic research hinders the full utilization of data-driven drug development strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Drugs Market |
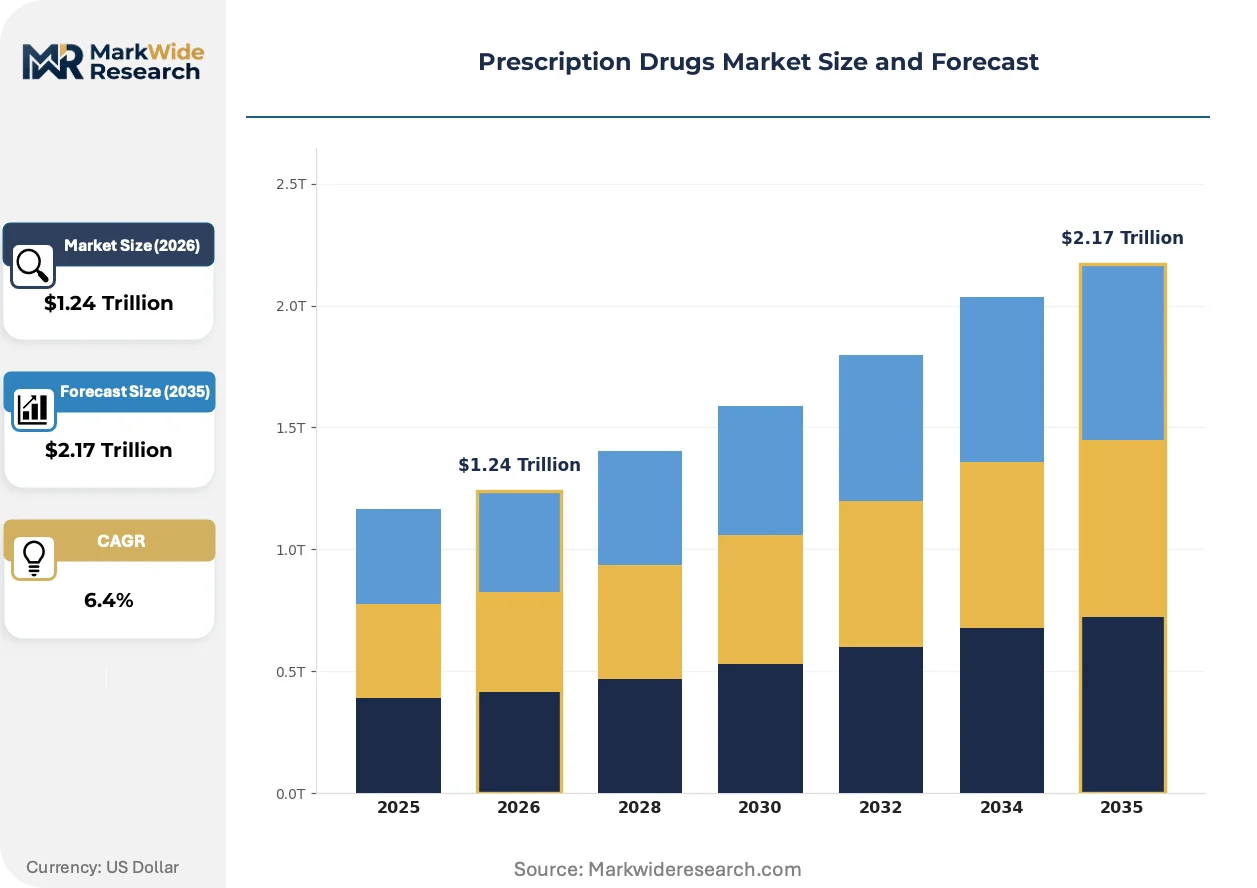
| Market Size in 2026 | $1.24 Trillion |
| Market Size in 2035 | $2.17 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Antibiotics, Antidepressants, Antihypertensives, Antidiabetics, Antivirals, Immunosuppressants Therapy Area: Cardiology, Oncology, Neurology, Endocrinology, Respiratory, Dermatology End User: Hospitals, Specialty Clinics, Community Pharmacies, Long-Term Care Facilities, Rehabilitation Centers Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers, Direct Sales |
| Companies Covered | Novartis AG, Pfizer, F. Hoffmann-La Roche Ltd, Johnson & Johnson Services, Sanofi, Merck & Co., AbbVie, GlaxoSmithKline plc, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Drugs Market Strategic Shifts & Innovations
Data-driven personalization is reshaping the pharmaceutical value chain. The integration of advanced analytics and genomic data is moving drug development from a probabilistic to a deterministic model, influencing everything from candidate selection to post-market surveillance and prescribing decisions.
Multi-omics platforms integrate genomics, proteomics, and metabolomics data to create a holistic molecular profile of a disease. Pharmaceutical R&D departments are adopting these platforms for precise biomarker discovery and patient stratification in clinical trials. This deep biological insight is collapsing the traditionally linear and siloed phases between target identification, preclinical research, and clinical development into a more integrated, iterative process.
Regulatory frameworks are adapting to real-world evidence (RWE). Agencies like the US FDA and Japan's PMDA are increasingly accepting RWE from electronic health records and patient registries to support post-approval studies and label expansions. This shift impacts therapies for chronic conditions most, allowing manufacturers to demonstrate long-term value and safety outside the confines of traditional clinical trials.
A fundamental change in commercial engagement is underway as value-based agreements gain traction. This model replaces traditional volume-based pricing, tying reimbursement for expensive therapies directly to their performance and observed patient outcomes. This trend is most visible in the United States and select European countries for high-cost oncology drugs, gene therapies, and treatments for rare diseases.
Prescription Drugs Market Segmentation
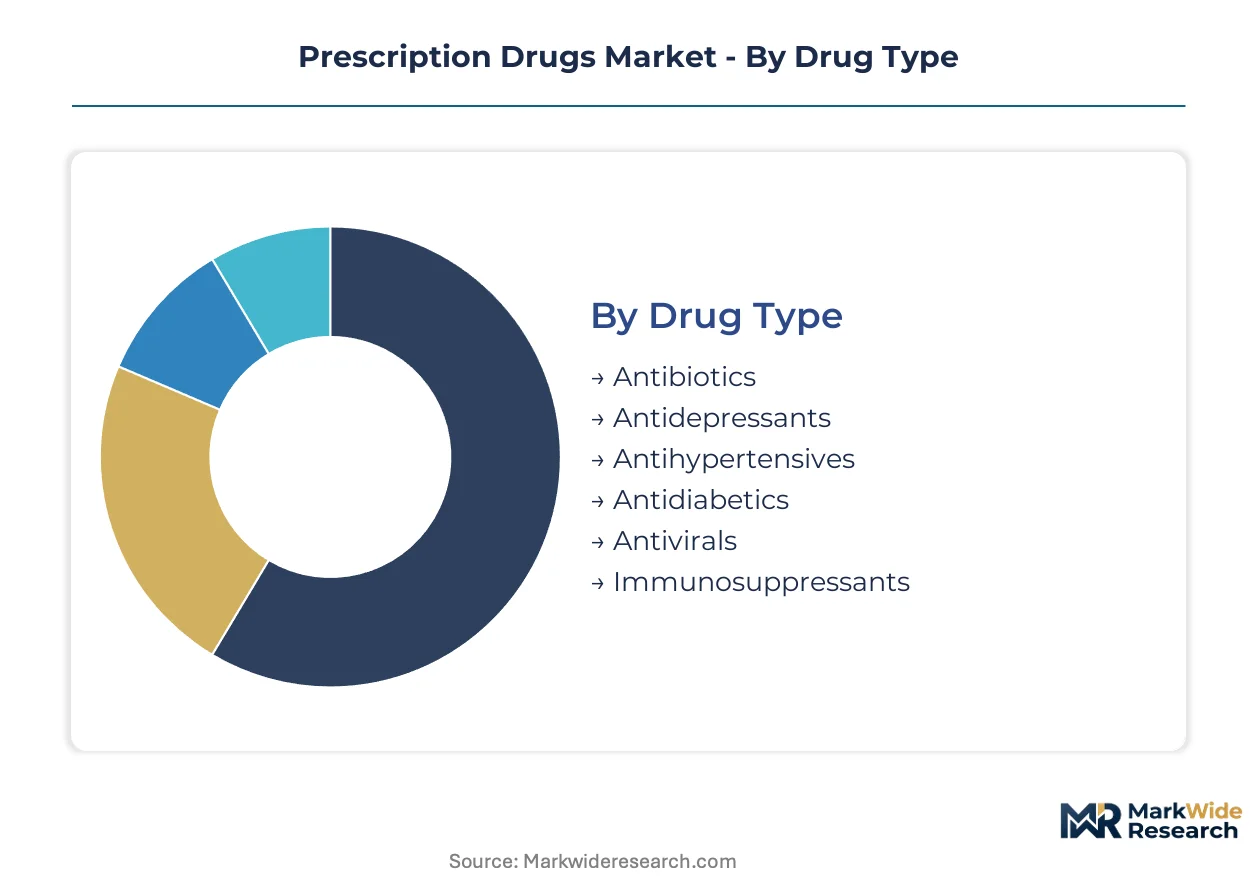
The prescription drugs market is segmented to provide a comprehensive understanding of therapeutic applications, patient access points, and commercial flow. This classification helps pharmaceutical companies prioritize research and development efforts and optimize market entry strategies. It also clarifies the complex interplay between drug modalities and healthcare delivery.
Drug Type:
The spectrum of drug types addresses various disease mechanisms, from infectious agents to chronic conditions requiring long-term management.
- Antivirals:These pharmaceutical agents target specific viral replication pathways, inhibiting viral spread and reducing disease burden. Demand for advanced antivirals is concentrating in global pandemic preparedness efforts and chronic viral infection management in countries like the United States.
- Immunosuppressants:Designed to modulate or suppress the body's immune response, these drugs are crucial for preventing organ transplant rejection and managing autoimmune diseases. Increased organ transplantation rates and a rising prevalence of autoimmune disorders drive their demand in European healthcare systems.
- Antibiotics:These compounds combat bacterial infections by inhibiting bacterial growth or killing the pathogens directly.
- Antidepressants:These medications work by balancing neurochemicals in the brain to alleviate symptoms of depression and other mood disorders.
- Antihypertensives:Used to lower blood pressure, these drugs are essential in managing cardiovascular diseases and preventing related complications.
- Antidiabetics:This class of drugs helps control blood glucose levels in patients with diabetes, ranging from oral medications to injectable insulins.
The dominant share belongs to Antihypertensives, while Antivirals are closing the gap fastest.
Therapy Area:
Drug development and commercialization efforts are intensely focused on specific therapy areas, reflecting unmet medical needs and investment priorities.
- Oncology:This area encompasses drugs for treating various cancers, including chemotherapies, targeted therapies, and immunotherapies. High R&D investment and breakthrough designations in oncology are driving significant pipeline expansion, particularly in China.
- Neurology:Focused on disorders of the nervous system, this segment includes treatments for conditions like Alzheimer's, Parkinson's, and multiple sclerosis. An aging global population sustains robust demand for novel neurological treatments in countries such as Japan and Germany.
- Cardiology:This segment includes medications for heart conditions, such as antiarrhythmics, anticoagulants, and lipid-lowering agents.
- Endocrinology:Drugs in this area address hormonal imbalances and metabolic disorders, including treatments for thyroid conditions and growth hormone deficiencies.
- Respiratory:Medications for respiratory conditions like asthma, COPD, and cystic fibrosis fall under this therapy area.
- Dermatology:This segment covers treatments for skin conditions, ranging from topical creams to systemic therapies for severe dermatological diseases.
Oncology medications currently hold the largest market presence, with neurology treatments demonstrating the steepest expansion trajectory.
End User:
The final recipients of prescription drugs vary, influencing packaging, administration, and patient education requirements.
- Hospitals:These institutions serve as primary points for acute care, surgical procedures, and complex disease management, requiring a broad spectrum of specialized drugs. Hospitals in the United States represent a significant purchasing volume due to complex inpatient care needs.
- Community Pharmacies:These retail outlets dispense prescription medications directly to outpatients, providing convenient access for chronic disease management. Expanding healthcare access in emerging economies like Brazil is increasing the footprint of community pharmacies.
- Specialty Clinics:Focused on specific medical fields, these clinics administer highly specialized and often high-cost treatments for conditions like autoimmune disorders or certain cancers.
- Long-Term Care Facilities:These facilities cater to elderly or chronically ill patients requiring continuous medical supervision and medication management.
- Rehabilitation Centers:Patients in these centers receive medications to support recovery from injury, surgery, or substance abuse.
Hospitals command the largest share of prescription drug consumption, while specialty clinics are rapidly expanding their therapeutic reach.
Distribution Channel:
The pathways through which prescription drugs reach end-users are diverse, each with unique logistical and regulatory considerations.
- Retail Pharmacies:These are storefront pharmacies where patients purchase prescribed medications directly, often after a doctor's visit. Retail pharmacies in India are experiencing significant growth due to increased patient footfall and accessibility.
- Hospital Pharmacies:Integrated within healthcare facilities, these pharmacies manage drug inventories for inpatient use and dispense medications upon discharge. Hospital pharmacies in the European Union handle complex drug formularies and patient-specific dosing.
- Online Pharmacies:These platforms allow patients to order prescription drugs remotely, offering convenience and often competitive pricing.
- Wholesalers:These entities act as intermediaries, purchasing large volumes of drugs from manufacturers and distributing them to pharmacies, hospitals, and other healthcare providers.
- Direct Sales:Some specialized or high-cost drugs are distributed directly from manufacturers to healthcare providers or patients, often for specific therapeutic programs.
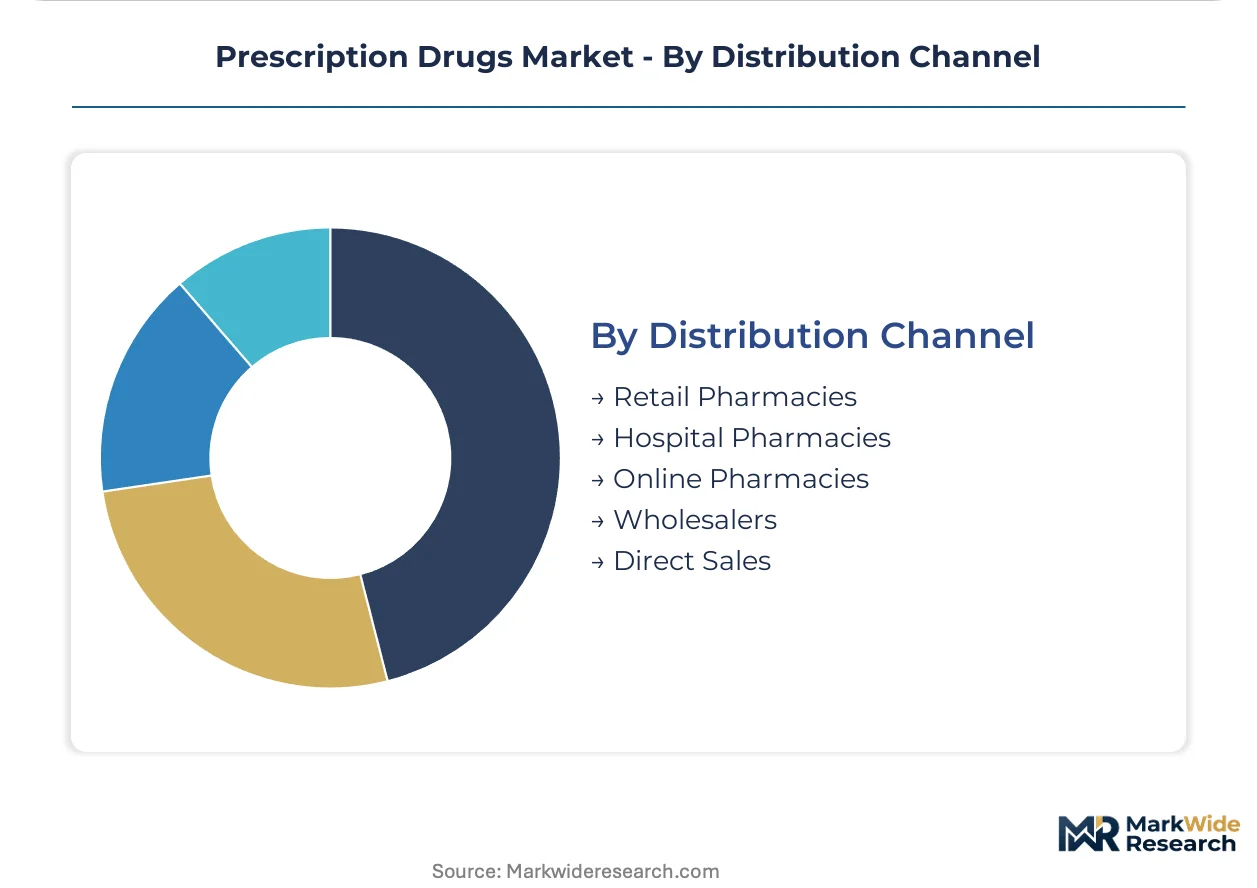
Retail Pharmacies maintain the largest distribution volume, with Online Pharmacies exhibiting the most dynamic growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences regional market dynamics for prescription drugs. Advanced economies drive demand for novel and specialized therapies due to sophisticated healthcare systems. Emerging markets focus on expanding access to essential medicines for their growing populations.
United States
Demand for prescription drugs in the United States is driven by significant R&D investment and a high prevalence of chronic diseases. The FDA's accelerated approval pathways encourage the introduction of novel therapies, particularly for oncology. Major pharmaceutical research hubs like Boston and San Francisco are centers for biotech innovation and clinical trials.
China
China's prescription drug market expands due to increasing healthcare access and a rapidly aging population. The NMPA's regulatory reforms aim to streamline drug approvals and encourage domestic innovation. Shanghai's Zhangjiang Hi-Tech Park serves as a critical cluster for pharmaceutical manufacturing and R&D activities.
Japan
Aging demographics in Japan sustain robust demand for treatments addressing neurodegenerative disorders and chronic conditions. The PMDA ensures drug safety and efficacy while adapting to global regulatory standards. Tokyo and Osaka host significant pharmaceutical companies and research institutions, focusing on advanced therapeutics.
Germany
Germany's market is shaped by an aging populace and the need for long-term medications for chronic conditions. The European Medicines Agency (EMA) influences drug approvals and market access across the region, including Germany. The Rhine-Main region, including Frankfurt, is a hub for pharmaceutical companies and biotech startups.
Brazil
Expanding government healthcare coverage and rising disposable incomes fuel demand for prescription medicines in Brazil. ANVISA, the national health surveillance agency, regulates drug registration and market entry. São Paulo is a major center for pharmaceutical distribution and manufacturing within the Latin American market.
Prescription Drugs Market Key Industry Players
Channel-controlling players compete with product-specialist players across the prescription drug market. The market exhibits a tiered structure, with large multinational pharmaceutical corporations dominating established therapy areas. These firms leverage vast R&D budgets and global commercial footprints. Smaller biotech firms often focus on niche segments or novel drug discovery platforms, driving innovation. Strategic partnerships and technology licensing are prevalent competitive moves, enabling market access and portfolio diversification.
Companies operating at a global scale, such as Pfizer, exemplify the archetype of broad portfolio pharmaceutical giants, leveraging extensive manufacturing and distribution networks for blockbuster drugs. F. Hoffmann-La Roche Ltd, a Swiss AG, occupies a strong position in diagnostics-led personalized oncology treatments, demonstrating specialization within a high-value therapy area. AstraZeneca, a UK-based plc, represents a major player actively expanding its portfolio in complex biologics and targeted therapies, reflecting significant R&D investment.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson Services |
| Sanofi |
| Merck & Co. |
| AbbVie |
| GlaxoSmithKline plc |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
The global pharmaceutical logistics corridor, particularly cold chain infrastructure, significantly impacts drug pricing by concentrating specialized manufacturing in key regions and influencing distribution costs for advanced biologics.
Pricing Analysis
Cost-plus contracting, often indexed to R&D intensity and clinical value, defines pricing for many novel prescription drugs. Price differentiation stems from regulatory approval status and demonstrated patient outcomes, particularly for oncology treatments. Pricing pressure stems from payer and health technology assessment (HTA) scrutiny demanding real-world evidence for high-cost specialty drugs. Community pharmacies often exhibit higher price sensitivity for generic medications compared to specialty clinics purchasing high-value biologics.
Supply Chain Analysis
Upstream pharmaceutical active pharmaceutical ingredients (APIs) largely originate from manufacturing hubs in China and India. This reliance creates single-source vulnerability for many essential medicines, impacting global supply stability. Excipients and specialized biologics manufacturing inputs also contribute to complex sourcing strategies. Regulatory restrictions and biomanufacturing complexity present a structural supply chain risk. Distribution runs through a multi-channel model involving retail pharmacies, hospital pharmacies, and a robust wholesale network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prescription drugs market represents a high-growth disruption, fundamentally reshaped by the integration of AI in drug discovery and development platforms.
For Market Incumbents: Harden intellectual property portfolios against biosimilar erosion through aggressive patent defense and next-generation formulation development. Consolidate market share in established therapy areas like cardiology by leveraging existing distribution networks against emerging generic competition. Invest in advanced biomanufacturing capacity within regulated markets to mitigate supply bottlenecks.
For New Entrants and Emerging Players: Niche therapeutic areas, particularly rare diseases and orphan drug development, present penetrable entry points for specialized biotechs. Focus on gene editing technologies like CRISPR-Cas9 offers a distinct go-to-market angle for curative therapies. Target unmet medical needs in neurology with novel small molecule candidates.
For Investors and Strategic Acquirers: Early-stage biotech firms specializing in multi-omics platforms offer compelling long-term viability within the precision medicine landscape. A key signal to watch is successful Phase 2 clinical trial data for novel biologics targeting oncology indications. Prioritize companies with strong regulatory track records and diversified therapeutic pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel therapies addressing unmet medical needs in oncology. |
| Manufacturing Scale-Up | Ensures efficient production of complex biologics, reducing supply chain risks for new treatments. |
| Licensing Agreement | Expands therapeutic portfolios and market reach by accessing innovative drug candidates from smaller firms. |
| Pipeline Diversification | Reduces reliance on blockbuster drugs, mitigating revenue erosion from patent expirations across therapy areas. |
| Digital Health Integration | Enhances patient adherence and real-world evidence collection for chronic disease management. |
Research Approach
Operator-level perspectives from drug development executives, regulatory affairs leads, and hospital procurement managers anchored the qualitative base. Primary interviews were triangulated with secondary validation from FDA filings, EMA submissions, and ClinicalTrials.gov. This approach ensured robust bottom-up and top-down data triangulation.
Scenario-bracketing across conservative, base, and aggressive outlooks informed the market projection over the analysis window. Segmentation dimensions included drug type, therapy area, end-user, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and expert consensus on novel drug introductions.
Practitioners should monitor evolving regulatory frameworks and significant patent expirations for early signals of market shifts. Forecasts reflect assumptions regarding R&D investment and healthcare access. Cross-checking against WHO pharmaceutical expenditure data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Global Montelukast Sodium Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Global Antacids Market