
 Systemic Antibiotics Market | 2026-2036
Systemic Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Systemic Antibiotics Market Analytics
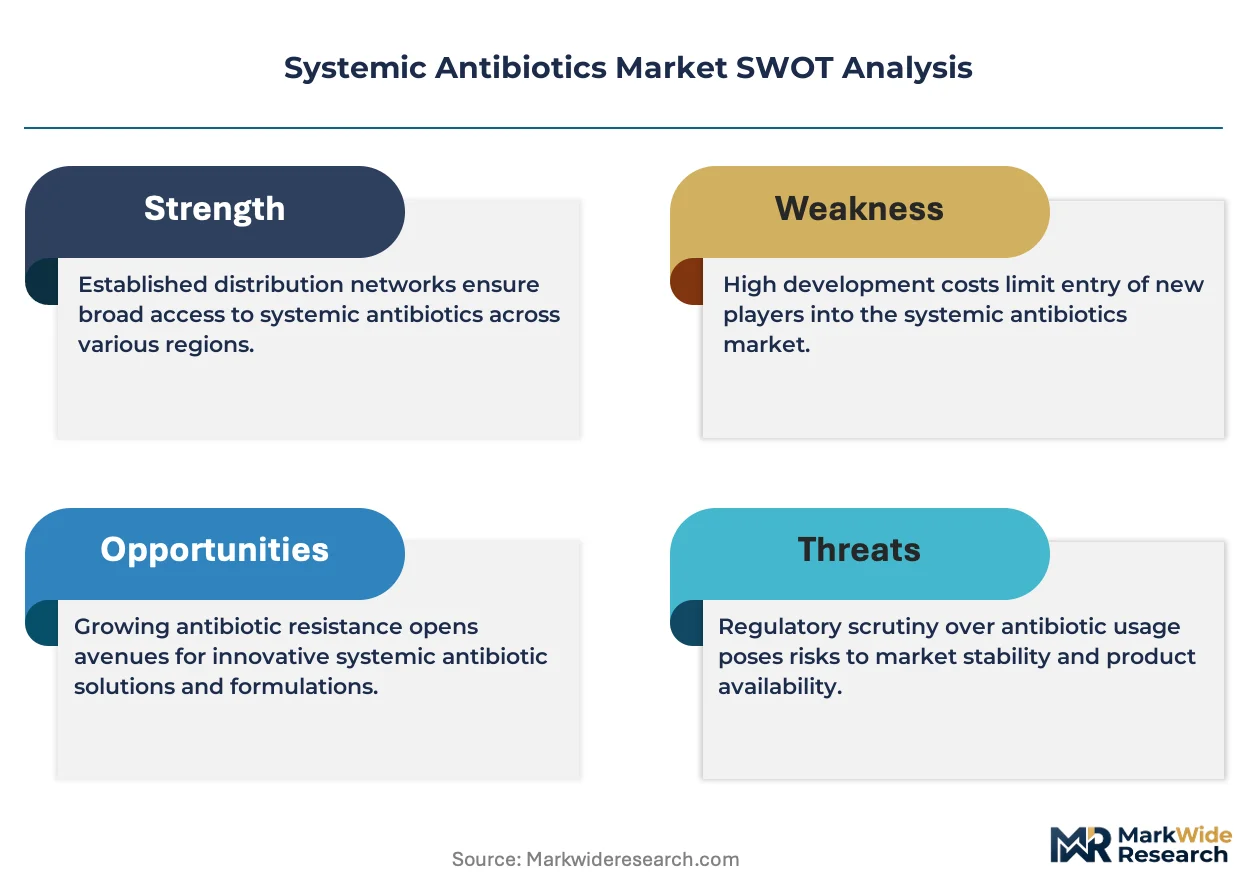
Hospital end-user procurement is restructuring systemic antibiotics demand as inpatient sepsis protocols expand and outpatient parenteral antimicrobial therapy contracts. Pfizer Inc. leverages its established hospital formulary relationships to sustain intravenous beta-lactam volumes. Merck & Co., Inc. anchors its position through carbapenem manufacturing scale, while Sun Pharmaceutical Industries Ltd. competes on cost-engineered oral generics across emerging markets.
Systemic antibiotics comprise orally or parenterally administered antibacterial agents that achieve therapeutic concentrations in blood and tissues to inhibit or kill pathogenic organisms, with minimum inhibitory concentration thresholds guiding clinical dosing protocols. Penicillins and cephalosporins dominate prescription volumes as first-line hospital therapy, while macrolides occupy the outpatient respiratory infection channel where oral compliance drives selection. Intravenous administration routes capture the highest per-dose value in acute bacteremia and pneumonia indications, whereas oral formulations generate volume in skin infection and urinary tract infection management across clinics and homecare settings.
FDA's Qualified Infectious Disease Product incentives and EMA's priority medicines pathways shape R&D investment toward resistant Gram-negative coverage, while WHO's Access, Watch, Reserve classification steers national stewardship programs and formulary restrictions. The EU's pharmaceutical strategy and antimicrobial resistance framework further tighten environmental discharge standards for manufacturing facilities. Stakeholders must monitor regulatory shifts in approval incentives and stewardship mandates to align pipeline priorities with evolving access and reimbursement conditions.
Market Dynamics
Hospital formulary consolidation is compressing supplier margins as integrated delivery networks centralize antibiotic procurement under stewardship protocols. Pfizer and Merck compete for limited intravenous beta-lactam slots while generic oral manufacturers face price erosion from tender aggregation.
Growth Catalysts
- FDA Qualified Infectious Disease Product incentives:Accelerated review timelines and extended exclusivity periods pull venture capital toward novel Gram-negative agents targeting carbapenem-resistant Enterobacteriaceae.
- Sepsis protocol expansion:Emergency departments in the United States, China, and India mandate earlier broad-spectrum coverage, driving intravenous cephalosporin and carbapenem consumption in acute care settings.
- Antimicrobial resistance surveillance intensification:National health agencies in India and China deploy real-time resistance mapping, creating demand for targeted therapy guided by local susceptibility patterns.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India control fermentation capacity for key beta-lactam intermediates, exposing formulators to supply disruption and input cost volatility.
- Environmental discharge compliance:EU pharmaceutical strategy mandates tighter manufacturing effluent standards, raising capital requirements for European production facilities.
- Oral bioavailability limitations:Poor gastrointestinal absorption of certain macrolides restricts outpatient conversion from intravenous therapy, prolonging hospital length of stay.
Strategic Opportunities
- Outpatient parenteral antimicrobial therapy expansion:Home infusion services in the United States capture hospital-discharge volumes through specialized pharmacy networks and reimbursement carve-outs.
- β-lactamase inhibitor combinations:Novel agents pairing ceftazidime with avibactam address resistant Pseudomonas aeruginosa in cystic fibrosis and nosocomial pneumonia populations.
- CDSCO fast-track pathways:India's streamlined approval for critical antibiotics reduces time-to-market for manufacturers targeting hospital tenders in Mumbai, Delhi, and Bangalore clusters.
Industry Challenges
- Pharmacovigilance workforce scarcity:Post-market surveillance requirements for novel antibiotics exceed qualified safety data analyst availability in emerging manufacturing hubs.
- Stewardship compliance complexity:WHO Access, Watch, Reserve classification demands real-time formulary adjustments that strain hospital pharmacy information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systemic Antibiotics Market |
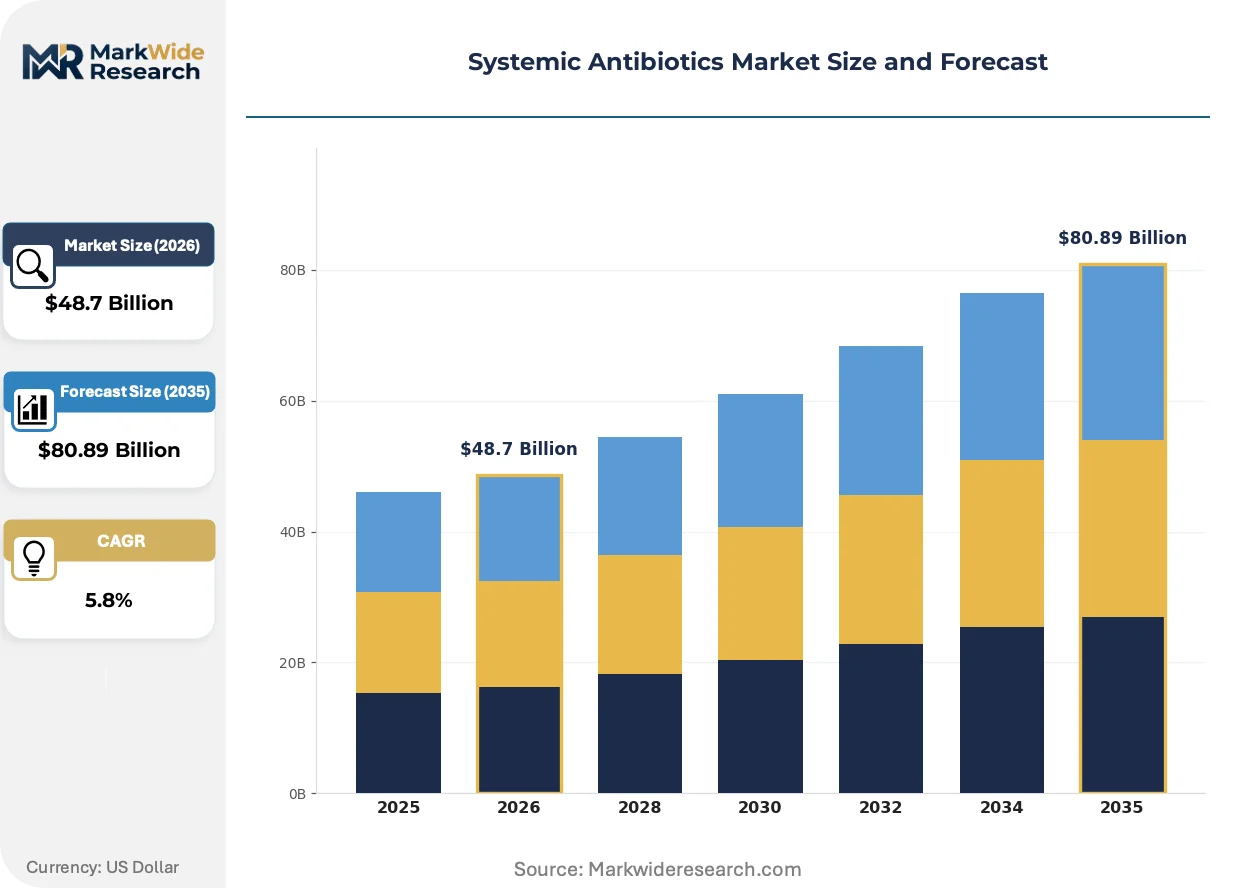
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Penicillins, Cephalosporins, Macrolides, Tetracyclines Indication: Pneumonia, Urinary Tract Infections, Skin Infections, Bacteremia Administration Route: Intravenous, Oral, Intramuscular, Subcutaneous End User: Hospitals, Clinics, Homecare, Long-term Care Facilities |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Novartis AG, AbbVie, GSK plc, Bayer AG, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systemic Antibiotics Market Evolving Landscape
Artificial intelligence is compressing antibiotic discovery timelines while regulatory incentives reshape competitive priorities toward resistance coverage rather than spectrum expansion.
Machine learning platforms for de novo molecular design is rewriting early-stage R&D economics. Biotech startups deploy neural networks to predict bacterial permeability and efflux susceptibility. Large pharmaceutical firms license these tools to replenish drying pipelines. The technology is rewriting how discovery budgets allocate between internal chemistry and external algorithmic partnerships.
REACH environmental discharge amendments tighten active pharmaceutical ingredient manufacturing standards across European production sites. The regulation forces fermentation facilities to install advanced effluent treatment or relocate to jurisdictions with weaker enforcement. Contract manufacturers in Portugal and Ireland face capital decisions that will determine regional supply continuity.
Integrated delivery networks now bundle antibiotic procurement with diagnostic stewardship contracts. Hospital systems negotiate multi-year agreements combining susceptibility testing platforms with formulary commitment tiers. This consolidation is most visible in United States metropolitan markets where three or four health systems control eighty percent of acute care beds.
Systemic Antibiotics Market Segmentation
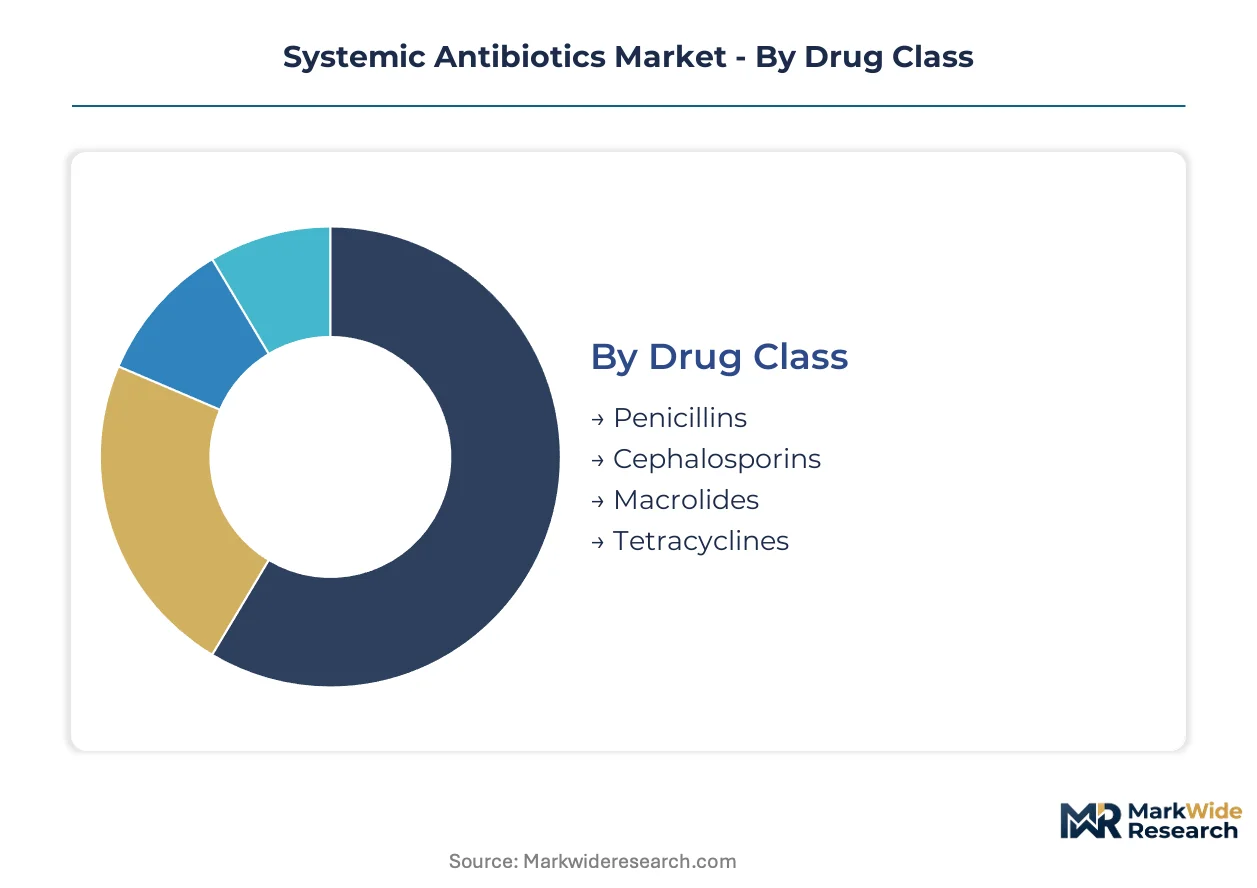
Antibiotic procurement decisions split across clinical urgency, resistance profiles, and reimbursement pathways. Hospital formulary committees weight drug class efficacy against stewardship mandates when allocating limited intravenous slots.
Drug Class:
Prescribers select beta-lactam cores based on local resistance maps and institutional protocols.
- Penicillins:Narrow-spectrum agents retain first-line status for community-acquired streptococcal infections. Demand concentrates in United States emergency departments where sepsis bundles mandate rapid beta-lactam initiation.
- Cephalosporins:Third and fourth-generation variants dominate hospital gram-negative coverage. Indian tertiary centers drive volume for extended-spectrum agents targeting nosocomial Klebsiella pneumoniae.
- Macrolides:Outpatient respiratory indications sustain prescription volumes despite rising pneumococcal resistance.
- Tetracyclines:Tigecycline and eravacycline address carbapenem-resistant Acinetobacter in intensive care units.
Cephalosporins lead on scale; tetracyclines lead on momentum.
Indication:
Acuity and mortality risk determine route selection and duration economics.
- Pneumonia:Community-acquired cases drive oral macrolide consumption in clinics. Hospital-acquired ventilator-associated pneumonia requires intravenous antipseudomonal beta-lactams with China accounting for substantial intensive care volume.
- Urinary Tract Infections:Uncomplicated cases generate oral fluoroquinolone and fosfomycin prescriptions in United States retail pharmacy channels.
- Skin Infections:Methicillin-resistant Staphylococcus aureus coverage shapes hospital discharge decisions for outpatient parenteral therapy.
- Bacteremia:Bloodstream infections mandate extended intravenous courses with infectious disease consultation requirements extending length of stay.
Pneumonia leads on scale; bacteremia leads on momentum.
Administration Route:
Site-of-care economics and bioavailability constraints shape delivery method selection.
- Intravenous:Achieves immediate therapeutic concentrations for critically ill patients. United States integrated delivery networks centralize procurement under stewardship contracts that limit supplier diversity.
- Oral:Bioequivalent generics compete on tender price in India's government hospital supply chains.
- Intramuscular:Long-acting depot formulations support adherence in substance use disorder populations requiring gonorrhea coverage.
- Subcutaneous:Outpatient parenteral antimicrobial therapy programs in United States home infusion networks capture hospital discharge volumes.
Intravenous leads on scale; subcutaneous leads on momentum.
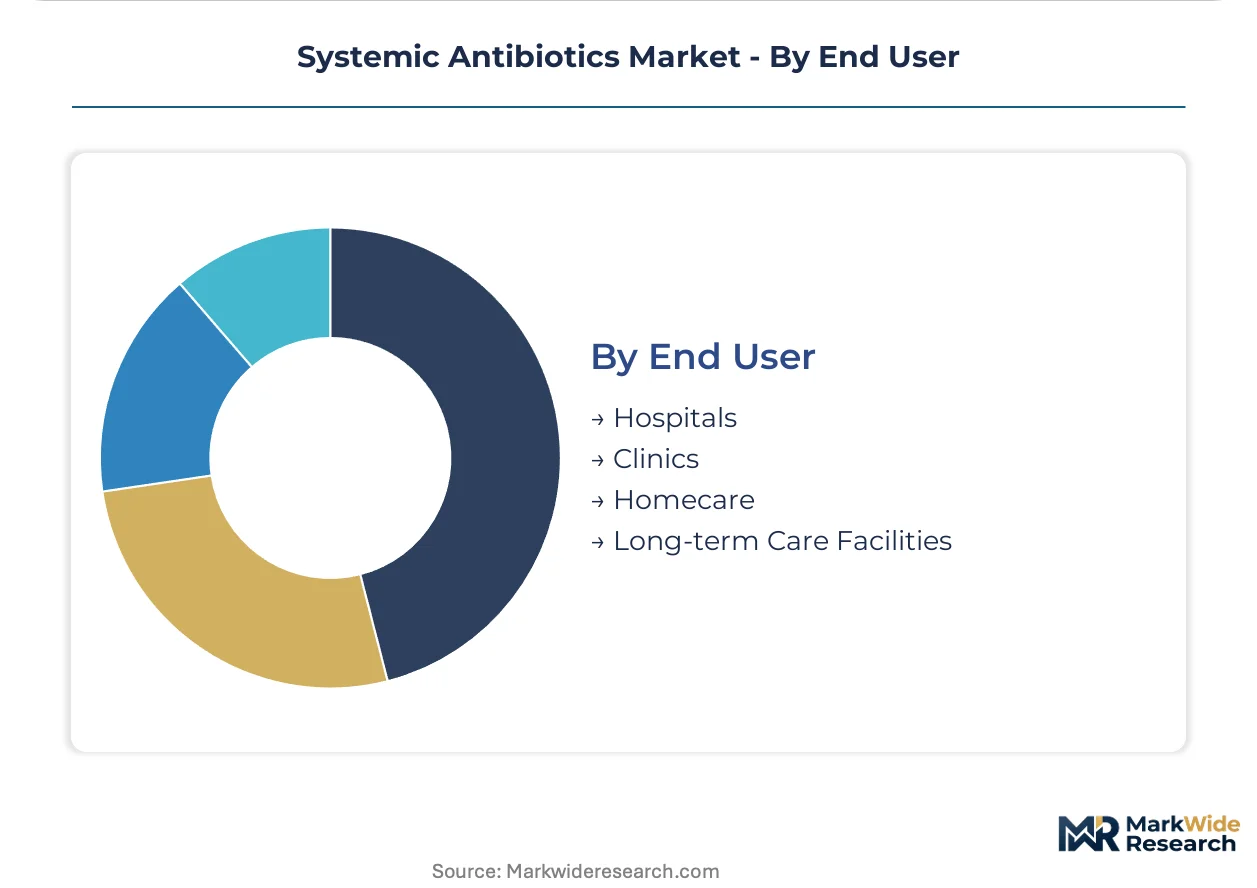
End User:
Facility type determines formulary autonomy and procurement aggregation potential.
- Hospitals:Stewardship programs restrict broad-spectrum agent use to culture-confirmed indications. China's tier-three hospitals concentrate demand for carbapenems and novel beta-lactamase inhibitor combinations.
- Clinics:Retail health and urgent care settings drive oral azithromycin and amoxicillin-clavulanate volume.
- Homecare:Infusion nursing services manage peripherally inserted central catheter lines for extended gram-negative therapy.
- Long-term Care Facilities:Urinary and respiratory colonization patterns drive empiric coverage decisions with limited diagnostic capacity.
Hospitals lead on scale; homecare leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as European environmental compliance costs push fermentation capacity toward jurisdictions with less stringent discharge oversight. Producers now weigh REACH-mandated effluent treatment capital against relocation economics.
United States
Integrated delivery networks in Chicago, Houston, and Atlanta concentrate intravenous antibiotic procurement under stewardship contracts that limit supplier slots. FDA's Qualified Infectious Disease Product incentives accelerate novel agent development timelines. The Boston-Cambridge corridor anchors venture-funded biotech discovery platforms targeting resistant Gram-negative coverage.
China
Tier-three hospitals in Shanghai, Beijing, and Guangzhou drive carbapenem consumption as sepsis protocols expand in intensive care units. NMPA streamlined approval pathways for critical antibiotics reduce regulatory lag for hospital-tender participants. The Yangtze River Delta fermentation cluster supplies beta-lactam intermediates to domestic formulators and export markets.
India
Government hospital supply chains in Mumbai, Delhi, and Bangalore aggregate tender volumes for cost-engineered oral generics. CDSCO fast-track designation for essential antibiotics compresses time-to-market for manufacturers targeting public procurement. The Hyderabad-Visakhapatnam corridor concentrates active pharmaceutical ingredient fermentation capacity for cephalosporin intermediates.
Germany
Hospital formulary committees in Berlin, Munich, and Hamburg restrict broad-spectrum agent use to culture-confirmed indications under national stewardship mandates. EMA priority medicines pathways shape R&D investment toward resistant pathogen coverage. The Rhine-Ruhr industrial region hosts formulation facilities facing REACH environmental discharge compliance decisions.
Japan
Metropolitan hospital systems in Tokyo, Osaka, and Nagoya maintain infectious disease consultation requirements that extend intravenous therapy duration. PMDA accelerated review pathways for antimicrobial resistance countermeasures pull domestic R&D toward novel beta-lactamase inhibitors. The Kanto region concentrates pharmaceutical manufacturing subject to METI industrial emissions guidelines.
Systemic Antibiotics Market Competitive Landscape
Capacity consolidation dominates the current landscape as fermentation economics and environmental compliance costs reshape viable production footprints. The supplier base stratifies between multinational innovators with hospital formulary anchoring and emerging-market generic manufacturers competing on tender price. Three archetypes define positioning: novel-agent developers leveraging regulatory incentives, scale-driven intermediate producers controlling fermentation capacity, and cost-optimized formulators serving public procurement channels. M&A activity and geographic capacity relocation represent the dominant competitive moves as players arbitrage regulatory cost differentials.
Within the multinational innovator tier, Pfizer Inc., Merck & Co., Inc., and Sun Pharmaceutical Industries Ltd. occupy distinct strategic positions. Pfizer exemplifies the hospital-formulary anchoring archetype through established intravenous beta-lactam relationships. Merck represents manufacturing-scale defense of carbapenem positions. Sun Pharmaceutical occupies the cost-engineered generic formulation segment targeting emerging-market tender aggregation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| AbbVie |
| GSK plc |
| Bayer AG |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the United States now command pricing power through consolidated intravenous antibiotic procurement under stewardship contracts. Hospital formulary committees leverage volume aggregation to compress supplier margins while tiering formulary slots by resistance coverage and bioavailability profiles.
Pricing Analysis
Distributor margins on intravenous beta-lactams compress as integrated delivery networks negotiate direct manufacturer contracts bypassing wholesale tiers. Pricing stratifies across premium novel beta-lactamase inhibitor combinations, standard third-generation cephalosporins, and economy oral generics competing on Indian government tender price. Cost compression in oral macrolides intensifies because tender aggregation in emerging markets pools demand across multiple hospital systems. Government procurement channels in India exhibit highest price sensitivity; United States hospital systems with limited formulary slots show lowest sensitivity due to clinical protocol mandates.
Supply Chain Analysis
Fermentation capacity for 7-aminocephalosporanic acid and 6-aminopenicillanic acid rests on facilities in China, India, and select European sites. Active pharmaceutical ingredient production draws from corn-derived dextrose fermentation feedstocks, specialized enzyme catalysts, and solvent recovery systems. Single-source vulnerability concentrates in Yangtze River Delta intermediates suppliers facing environmental compliance inspections. Distribution runs through regional formulators in Hyderabad, Shanghai, and the Rhine-Ruhr corridor who convert bulk APIs into finished dosage forms for hospital and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The systemic antibiotics market functions as a stable compounder anchored by non-discretionary hospital demand for sepsis protocols and antimicrobial resistance surveillance expansion.
For Market Incumbents: Cement hospital formulary anchoring through infectious disease stewardship partnership contracts that bundle susceptibility testing with multi-year supply agreements. Add fermentation capacity in India to offset REACH-driven European environmental compliance costs. Generic oral manufacturers face tender price erosion from aggregated procurement in emerging markets. For New Entrants and Emerging Players: The gap between premium novel Gram-negative agents and economy oral generics offers white-space targeting for mid-tier beta-lactamase inhibitor combinations. Home infusion services for outpatient parenteral antimicrobial therapy represent the most penetrable segment in United States metropolitan markets. Pursue CDSCO fast-track designation to compress regulatory timelines for Indian hospital tender participation. For Investors and Strategic Acquirers: Hospital systems and specialty pharmacy networks are the most active acquirer in this space, consolidating home infusion capabilities to capture discharge volumes. Long-term viability rests on pipeline depth for resistant pathogen coverage rather than spectrum expansion. Watch FDA Qualified Infectious Disease Product designation velocity as inflection indicator for venture capital flow into novel Gram-negative programs.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Fermentation capacity additions in India and China secure beta-lactam intermediate supply continuity for formulators. |
| Regulatory Approval Pathway | FDA Qualified Infectious Disease Product designation accelerates novel agent timelines and extends market exclusivity periods. |
| Backward Integration | Formulators acquiring fermentation assets reduce exposure to Chinese intermediate price volatility and supply disruption. |
| Hospital System Partnership | Integrated delivery network stewardship contracts bundle susceptibility testing with multi-year formulary commitments. |
| Pipeline Diversification | Biotech discovery platforms deploy machine learning for de novo antibiotic molecular design against resistant Gram-negative targets. |
Research Methodology
Multiple input streams — primary interviews with infectious disease specialists, hospital formulary directors, and API manufacturing executives; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and Indian government tender databases; plus customs trade data on beta-lactam intermediate flows — were reconciled through bottom-up prescription volume modeling and top-down market sizing triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon by drug class, indication, administration route, and end-user facility type, with regional regulatory clusters as an overlay dimension. CAGRs were derived from longitudinal prescription audit data and hospital procurement contract analysis, incorporating sepsis protocol expansion rates and antimicrobial resistance surveillance deployment timelines as demand drivers.
Caveats apply where FDA incentive program modifications, REACH environmental discharge enforcement shifts, or API supply disruptions could materially shift the outlook. A small set of named triggers — stewardship mandate acceleration, novel resistance mechanism emergence, and fermentation facility inspection outcomes — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Topical Drugs CDMO Market