
 Global Statin Market | 2026-2036
Global Statin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Statin Market Intelligence
The application of statins for primary cardiovascular disease prevention is expanding, shifting prescribing patterns beyond just treating hypercholesterolemia. Pfizer Inc. leverages its legacy brand Lipitor, while AstraZeneca positions its potent rosuvastatin for high-risk patient cohorts. Generic manufacturers like Aurobindo Pharma and Sun Pharmaceutical compete primarily on cost and volume, capturing significant share across global markets.
Statins are a class of lipid-lowering medications that inhibit the enzyme HMG-CoA reductase, a key component in the cholesterol synthesis pathway in the liver. Their primary function is to reduce levels of low-density lipoprotein (LDL) cholesterol, mitigating the risk of atherosclerosis. Within product types, atorvastatin and rosuvastatin dominate due to superior efficacy and extensive clinical data. Hospital pharmacies and retail pharmacies constitute the largest distribution channels, with online pharmacies showing notable growth in patient accessibility.
Market access is governed by stringent bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). In parallel, China's NMPA and India's Central Drugs Standard Control Organisation (CDSCO) enforce manufacturing standards and approve marketing authorizations. Future competitive positioning will depend on developing novel combination therapies and successfully navigating diverse national reimbursement frameworks.
Market Dynamics
The central dynamic is the collision between widespread patent expirations, which fuels intense generic price competition, and expanding clinical guidelines for primary prevention, which creates new volume demand for both branded and generic statins globally.
Growth Catalysts
- Guideline Expansion:Evolving clinical recommendations from bodies like the American Heart Association for primary cardiovascular disease prevention broaden the eligible patient population beyond severe hypercholesterolemia.
- Demand in Asia:Rising incidence of cardiovascular disease in populous nations like China and India, linked to lifestyle shifts, increases the diagnosed and treated patient base.
- Manufacturing Efficiency:Advances in chemical synthesis and process optimization are lowering the production cost for high-volume generic statins like atorvastatin, improving affordability.
Market Restraints
- Price Erosion:The saturation of the market with multiple generic versions of atorvastatin and rosuvastatin creates severe downward price pressure, compressing margins for all manufacturers.
- Substitution by New Therapies:The emergence of non-statin lipid-lowering agents, particularly PCSK9 inhibitors for high-risk or statin-intolerant patients, presents a significant therapeutic alternative.
- Post-Market Surveillance:Stringent safety monitoring and reporting requirements from regulators like the FDA and EMA add significant long-term compliance costs and risks.
Strategic Opportunities
- Combination Therapies:Development of fixed-dose combinations (FDCs) that pair a statin with other cardiovascular drugs, such as ezetimibe or antihypertensives, offers a path to differentiation.
- Online Pharmacy Channels:The growth of digital and mail-order pharmacies provides a new distribution channel to improve patient access and medication adherence, particularly in developed markets.
- Untapped Latin American Markets:Countries such as Brazil and Mexico represent significant growth potential as healthcare access and cardiovascular disease screening programs expand.
Industry Challenges
- Reimbursement Complexity:Navigating disparate national reimbursement policies and government price controls, especially in markets with single-payer systems, complicates market access strategies.
- Counterfeit Drug Proliferation:The high volume of generic statins in the global supply chain increases the risk of counterfeit products, requiring robust track-and-trace systems for verification.
- Formulation Patent Litigation:Frequent and costly intellectual property disputes over new formulations or combination products create significant legal and commercial uncertainty for innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Statin Market |
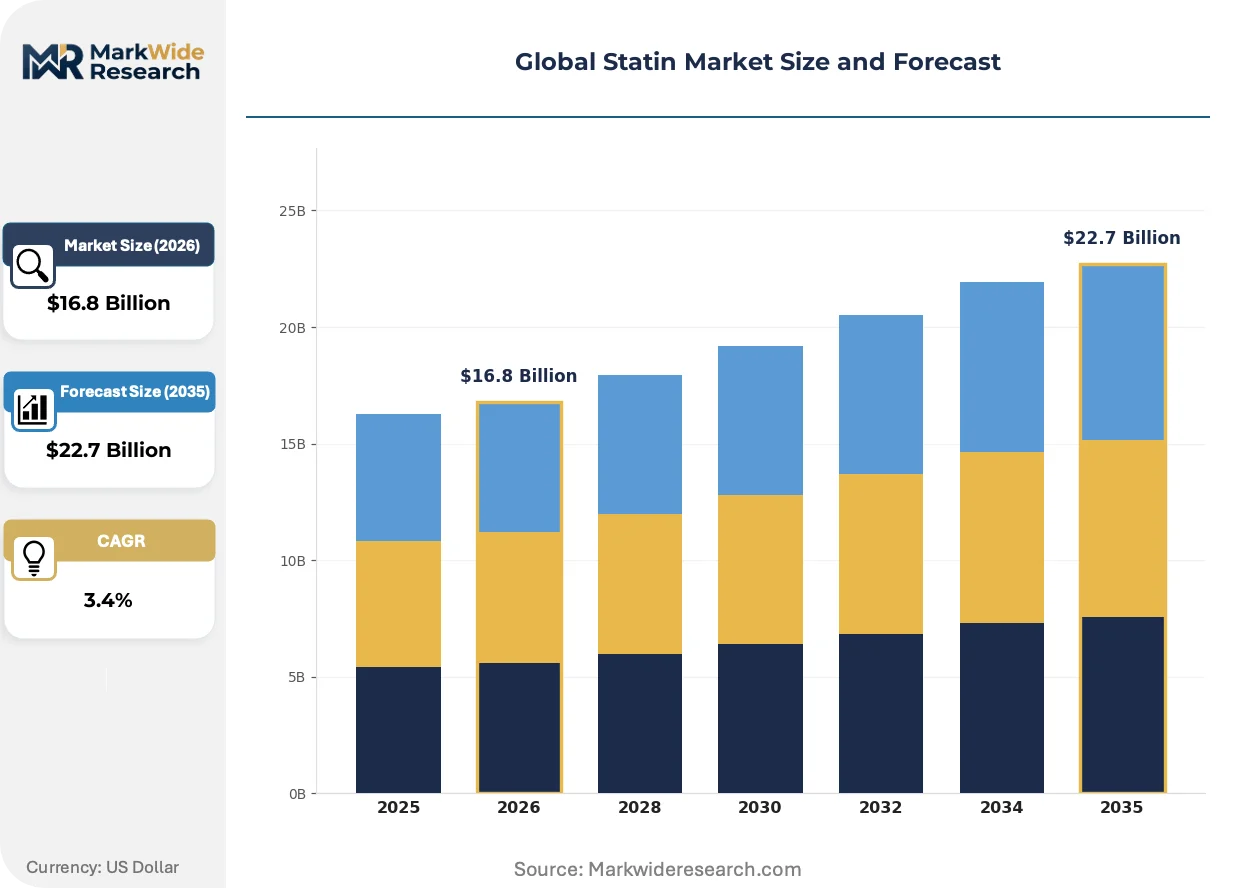
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $22.7 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atorvastatin, Rosuvastatin, Simvastatin, Pravastatin, Lovastatin Application: Hypercholesterolemia, Cardiovascular Disease Prevention, Stroke Prevention, Peripheral Artery Disease, Atherosclerosis End User: Primary Care Clinics, Cardiology Centers, Specialty Hospitals, Outpatient Clinics, Diagnostic Laboratories Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors, Direct Sales |
| Companies Covered | Novartis AG, Abbott Laboratories, Pfizer Inc., Sun Pharmaceutical, Aurobindo Pharma, AstraZeneca, Amgen Inc., Teva Pharmaceutical, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Statin Market Strategic Shifts & Innovations
Product innovation is shifting from novel single-molecule discovery toward combination therapies and digital health wrappers that improve adherence. This evolution reflects a market where value is increasingly defined by patient outcomes rather than just LDL reduction efficacy.
Digital health platforms provide tools for medication management. Health systems and insurers are adopting these systems to manage large patient populations on chronic statin therapy. This technology is automating patient reminders and adherence tracking, linking medication use directly to measurable cardiovascular risk reduction and supporting value-based care models.
China’s Volume-Based Procurement (VBP) policy for pharmaceuticals mandates that companies offer steep price discounts to win large-volume government contracts. This policy has radically restructured the generic statin market in China, favoring large-scale, low-cost domestic producers. Multinational firms are forced to either exit the VBP segment or drastically reduce prices.
A shift toward risk-based prescribing is altering how statins are initiated. Instead of treating a cholesterol number, primary care physicians increasingly use cardiovascular risk calculators to guide decisions, expanding use in patients with normal cholesterol but other risk factors. This preventative approach is most visible in the US and UK.
Global Statin Market Segmentation
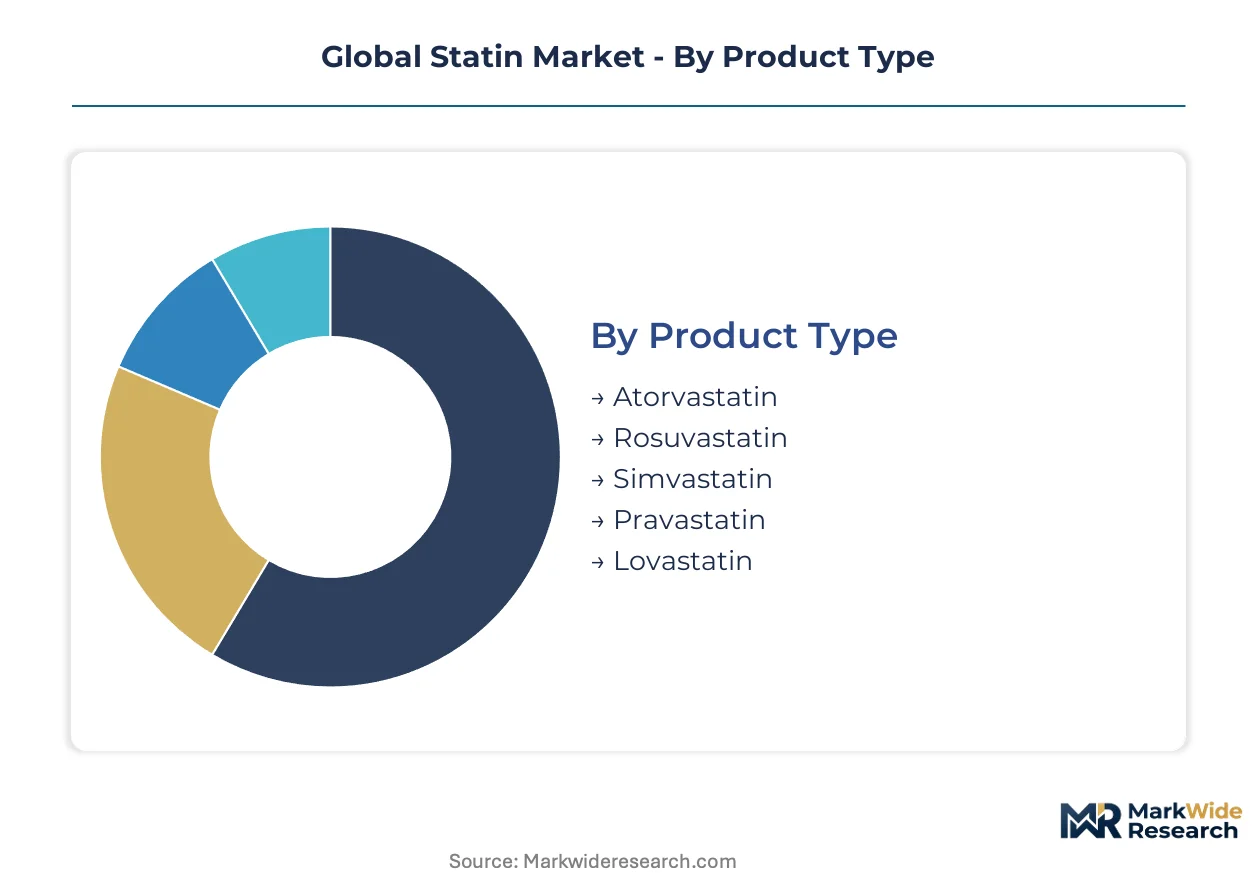
The global statin market segmentation provides a granular view of product types, applications, end-users, and distribution channels. This detailed breakdown helps stakeholders understand where demand concentrates, how treatment protocols evolve, and which access points are most critical for patient care.
Product Type:
The statin market differentiates by the specific HMG-CoA reductase inhibitor molecule, each with distinct pharmacokinetic profiles and clinical applications.
- Atorvastatin:This potent lipid-lowering agent is widely prescribed for both primary and secondary prevention of cardiovascular events. Demand concentrates in emerging markets like India due to its generic availability and proven efficacy in diverse patient populations.
- Rosuvastatin:Known for its superior efficacy in reducing low-density lipoprotein cholesterol (LDL-C), rosuvastatin is often reserved for high-risk patient cohorts requiring aggressive lipid management. Prescribing patterns show strong demand in developed economies such as the United States for its powerful therapeutic effect.
- Simvastatin:An older generation statin, simvastatin remains a cost-effective option for managing hypercholesterolemia.
- Pravastatin:This hydrophilic statin is often favored for patients with potential drug-drug interactions due to its metabolic pathway.
- Lovastatin:One of the earliest statins introduced, lovastatin is still prescribed for general hypercholesterolemia management.
Mature deployment sits with Simvastatin. Newer deployment is concentrated in Rosuvastatin.
Application:
Volume demand for statins is primarily driven by specific disease indications and evolving clinical guidelines.
- Cardiovascular Disease Prevention:This application involves the prophylactic use of statins to reduce the risk of heart attacks and strokes in eligible individuals. Global guidelines from bodies like the American Heart Association significantly expand its use across broad patient populations, including those without overt hypercholesterolemia.
- Hypercholesterolemia:This segment focuses on the direct treatment of elevated LDL cholesterol levels to mitigate associated health risks. It remains a foundational application, with significant patient numbers in countries like China due to lifestyle and dietary shifts impacting lipid profiles.
- Stroke Prevention:Statins effectively reduce the risk of both ischemic and hemorrhagic strokes, especially in patients with existing cardiovascular disease or high-risk factors.
- Peripheral Artery Disease:Statins improve outcomes and reduce cardiovascular events for patients suffering from reduced blood flow to the limbs.
- Atherosclerosis:This application addresses the underlying process of arterial plaque buildup, where statins play a critical role in slowing progression and promoting plaque stabilization.
The broadest patient base is addressed by Hypercholesterolemia. Cardiovascular Disease Prevention is expanding most quickly.
End User:
Different healthcare provider types serve as primary access points for statin therapy, influencing prescribing patterns and patient management strategies.
- Primary Care Clinics:General practitioners within these clinics initiate the majority of statin prescriptions for routine lipid management and primary prevention. Patient visits to these clinics represent a significant volume of initial diagnoses and ongoing care in countries such as the UK.
- Cardiology Centers:Specialists in cardiology centers manage complex cases, high-risk patients, and those requiring intensive lipid-lowering strategies or combination therapies. These centers in Germany often prescribe potent statins or advanced treatment protocols.
- Specialty Hospitals:Hospitals provide statins for acute cardiovascular events, post-procedure care, and for patients with severe comorbidities.
- Outpatient Clinics:These facilities manage chronic conditions, including hyperlipidemia, offering a convenient setting for ongoing statin therapy outside of acute hospital care.
- Diagnostic Laboratories:Laboratories support statin use by providing essential cholesterol level monitoring and risk assessment, guiding treatment initiation and adjustment.
Routine prescriptions originate mostly from Primary Care Clinics. Specialized treatment pathways are managed by Cardiology Centers.
Distribution Channel:
Distribution channels exhibit varying operational complexities and margin structures within the statin supply chain, impacting patient access and market reach.
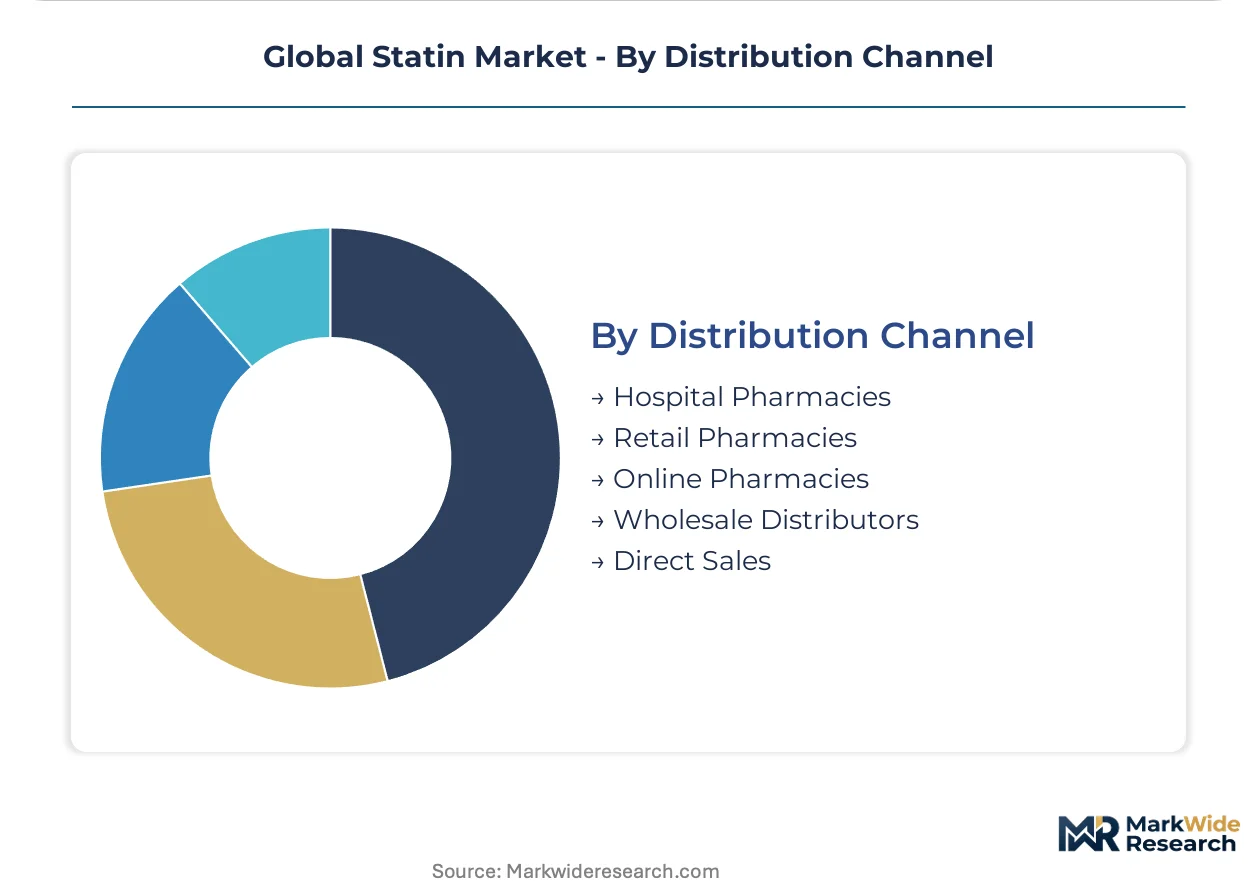
- Hospital Pharmacies:These pharmacies dispense statins for inpatient use, emergency situations, and discharge prescriptions, often managing large formularies and bulk procurement. These pharmacies in France handle significant volumes for acute care and initial therapy stabilization.
- Retail Pharmacies:Retail pharmacies represent the primary outlet for outpatient statin prescriptions, offering widespread geographical coverage, convenience, and direct patient interaction. These pharmacies in Japan cater to long-term maintenance therapy for chronic conditions, ensuring medication adherence.
- Online Pharmacies:This channel provides home delivery and increased accessibility, particularly in urban areas and for patients seeking convenience.
- Wholesale Distributors:Wholesale distributors serve as essential intermediaries, supplying bulk statins to various healthcare facilities and retail pharmacies.
- Direct Sales:This is a more limited channel, typically employed for specialized institutional procurement or specific branded products with direct manufacturer relationships.
The largest volume of patient prescriptions flows through Retail Pharmacies. Online Pharmacies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global statin market dynamics reveal a distinct divide between regions driving high-volume generic production and those exhibiting premium-segment consumption. Demand concentration in populous nations significantly influences manufacturing strategies for pharmaceutical companies. Regulatory frameworks further shape market access and pricing structures across diverse economies.
United States
Demand for statins in the United States primarily stems from the expanding application for cardiovascular disease prevention and the use of potent molecules like rosuvastatin for high-risk patients. The US Food and Drug Administration (FDA) maintains stringent safety monitoring and reporting requirements for all approved statins. Boston's biotech hub drives advanced lipid-lowering research, focusing on novel combination therapies. Primary care clinics initiate the majority of statin prescriptions for routine lipid management.
China
China's statin market experiences significant demand due to lifestyle shifts impacting lipid profiles and the rising incidence of cardiovascular disease. The National Medical Products Administration (NMPA) enforces manufacturing standards and approves marketing authorizations for pharmaceutical products. China's Volume-Based Procurement (VBP) policy mandates steep price discounts for generic statins, favoring large domestic producers. Cities within the Yangtze River Delta see rapid expansion of generic statin production and distribution.
India
Demand in India concentrates on cost-effective atorvastatin, driven by its generic availability and proven efficacy across diverse patient populations. The Central Drugs Standard Control Organisation (CDSCO) regulates pharmaceutical manufacturing and approvals within the country. India's Production-Linked Incentive (PLI) scheme supports domestic pharmaceutical manufacturing, including statin APIs. Hyderabad's Pharma City emerges as a major hub for high-volume generic statin API and formulation production.
Germany
Germany's market for statins sees demand from cardiology centers managing complex cases and patients requiring intensive lipid-lowering strategies. The European Medicines Agency (EMA) oversees market access for new therapies and ensures drug quality across the European Union. Specialized treatment pathways are managed by these cardiology centers, often prescribing potent statins. Munich's medical technology sector collaborates on digital health platforms designed to improve medication adherence.
Japan
Japan's statin market is characterized by extensive retail pharmacy networks that cater to long-term maintenance therapy for chronic conditions. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures drug quality and efficacy for all pharmaceutical products in the country. Retail pharmacies represent the primary outlet for outpatient statin prescriptions, offering widespread geographical coverage. Tokyo's large metropolitan area facilitates extensive retail pharmacy networks for patient access and medication dispensing.
Global Statin Market Key Industry Players
Top-tier vendors anchor the branded segment, while generic manufacturers compete primarily on cost and volume across global markets. The market structure exhibits a clear bifurcation between innovator companies focusing on patented formulations and high-volume generic producers. Strategic archetypes include legacy brand holders, potent molecule specialists targeting high-risk patients, and cost-efficient generic powerhouses. Companies pursue geographic expansion into emerging markets, alongside strategic partnerships for novel combination therapies and digital health integration.
Within the potent molecule specialist archetype, Pfizer Inc. leverages its enduring legacy brand Lipitor, maintaining market presence through established patient loyalty. AstraZeneca, a UK-based pharmaceutical company, strategically positions its highly potent rosuvastatin for high-risk patient cohorts, exemplifying a focus on superior efficacy and specialized applications. India-based Sun Pharmaceutical represents the cost-efficient generic powerhouse segment, competing intensely on volume and affordability across diverse global markets, capturing significant share through its extensive distribution networks. These players navigate complex reimbursement frameworks and evolving clinical guidelines.
| Leading Market Players |
|---|
| Novartis AG |
| Abbott Laboratories |
| Pfizer Inc. |
| Sun Pharmaceutical |
| Aurobindo Pharma |
| AstraZeneca |
| Amgen Inc. |
| Teva Pharmaceutical |
| Merck & Co. |
| Others |
Cost & Logistics Intelligence
Stringent regulatory compliance mandates from bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) gate qualified supply and influence premium-tier pricing access for statin manufacturers. This creates a dual-market structure where highly regulated, quality-assured products command higher prices, while generic competition drives down costs in less stringent segments.
Pricing Analysis
Margin compression across generic statins reflects intense price competition following widespread patent expirations. The dominant pricing structure for high-volume generics is contract-based, often influenced by national procurement policies like China's Volume-Based Procurement (VBP). Price differentiation drivers include superior efficacy for branded rosuvastatin and volume scale for generic atorvastatin. Generic buyers, particularly in emerging markets, exhibit high price sensitivity, while high-risk patient cohorts often prioritize therapeutic effect over cost.
Supply Chain Analysis
Statin API production largely relies on geographic concentrations in India and China, particularly Hyderabad's Pharma City and cities within the Yangtze River Delta. Raw material dependencies include various chemical intermediates essential for synthesizing high-volume generic statins. A significant supply chain risk is the proliferation of counterfeit drugs, which necessitates robust track-and-trace systems. Distribution runs primarily through wholesale distributors to hospital pharmacies and retail pharmacies globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global statin market presents a cost-of-compliance story, where stringent regulatory oversight from agencies like the FDA creates a significant barrier-to-entry moat for compliant pharmaceutical players.
For Market Incumbents: Extend product lifecycles through the development of novel fixed-dose combination therapies, mitigating the threat of generic price erosion and substitution by new non-statin agents. Invest in digital health platforms to improve patient adherence and demonstrate value-based outcomes, reinforcing existing market share. Leverage established brand loyalty for potent molecules like Lipitor while exploring strategic partnerships for advanced delivery mechanisms.
For New Entrants and Emerging Players: Capture market share by focusing on cost-effective generic statins in underpenetrated emerging markets, such as Latin America. Target the online pharmacy channel as a go-to-market angle to improve patient access and convenience in developed economies. Prioritize manufacturing efficiency and robust distribution networks to compete effectively on volume and affordability, especially in regions with volume-based procurement policies.
For Investors and Strategic Acquirers: Successful clinical trial advancement for novel combination therapies is the leading indicator that signals long-term growth potential in this mature market. The chronic nature of cardiovascular disease ensures stable demand across the long-term horizon. Identify specialty generic manufacturers with strong regional distribution or digital health solution providers as prime acquisition targets, seeking to consolidate market position or expand value-added services.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Secures future revenue streams for novel statin combination therapies. |
| Manufacturing Scale-Up | Reduces per-unit costs for high-volume generic statins in competitive markets. |
| Strategic Partnership | Integrates digital health platforms to enhance patient adherence and outcomes. |
| Geographic Expansion | Accesses new patient populations in untapped Latin American markets. |
| Regulatory Approval Pathway | Ensures market access for new formulations and combination products globally. |
Research Approach
Industry association reports, regulatory filings from the FDA and EMA, and national health organization guidelines formed the secondary backbone for this analysis. This was triangulated with primary interviews involving regulatory affairs leads, hospital procurement managers, primary care physicians, and cardiology specialists. Both bottom-up and top-down approaches validated market sizing and segmentation across various parameters.
Historical trendline analysis informed the quantitative model, projecting market growth across the analysis window. Segmentation dimensions included product type, application, end-user, distribution channel, and regional regulatory cluster. Compound annual growth rates were derived from volume and value projections, incorporating key industry-specific forecast inputs such as patent expiration timelines and evolving clinical guideline updates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving reimbursement policies and the emergence of new non-statin therapies. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Stroke Management Market
Cardiovascular
Tachycardia Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Ticagrelor Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Cardiometabolic Disease Market