
 Global Doxorubicin Market | 2026-2036
Global Doxorubicin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Doxorubicin Market Foresight
Oncology pharmacist specialization is bifurcating the competitive landscape between facilities capable of complex compounding and standard infusion centers. Pfizer Inc. leverages its established liposomal manufacturing infrastructure to sustain supply security for high-volume hospital networks. Sun Pharmaceutical Industries Ltd anchors its position through cost-optimized conventional doxorubicin production serving emerging markets. Teva Pharmaceutical Industries Ltd competes on breadth, offering both branded and generic formulations across multiple delivery modes.
Doxorubicin is an anthracycline cytotoxic antibiotic produced by Streptomyces peucetius var. caesius, functioning by intercalating DNA base pairs and inhibiting topoisomerase II to arrest tumor cell replication. Its primary commercial purpose centers on treating hematologic malignancies and solid tumors through intravenous administration in controlled clinical settings. Liposomal Doxorubicin commands premium positioning due to reduced cardiotoxicity and extended circulation half-life, while Conventional Doxorubicin retains volume leadership in price-sensitive procurement environments. Among therapy areas, Breast Cancer and Lymphoma represent the deepest existing demand pools, with Sarcoma applications gaining attention from research-focused prescribers seeking off-label efficacy signals.
FDA batch-release requirements and EMA GMP inspections shape manufacturing location decisions and compliance cost structures for doxorubicin suppliers seeking multi-territory market access. China's NMPA bioequivalence standards for liposomal generics are tightening quality thresholds for domestic producers aspiring to export registration. WHO prequalification pathways influence tender eligibility for public-sector oncology programs across low- and middle-income countries. Stakeholders must monitor regulatory divergence between major agencies on liposomal bioequivalence methodology, as this will determine which manufacturing investments retain strategic optionality across jurisdictions.
Market Dynamics
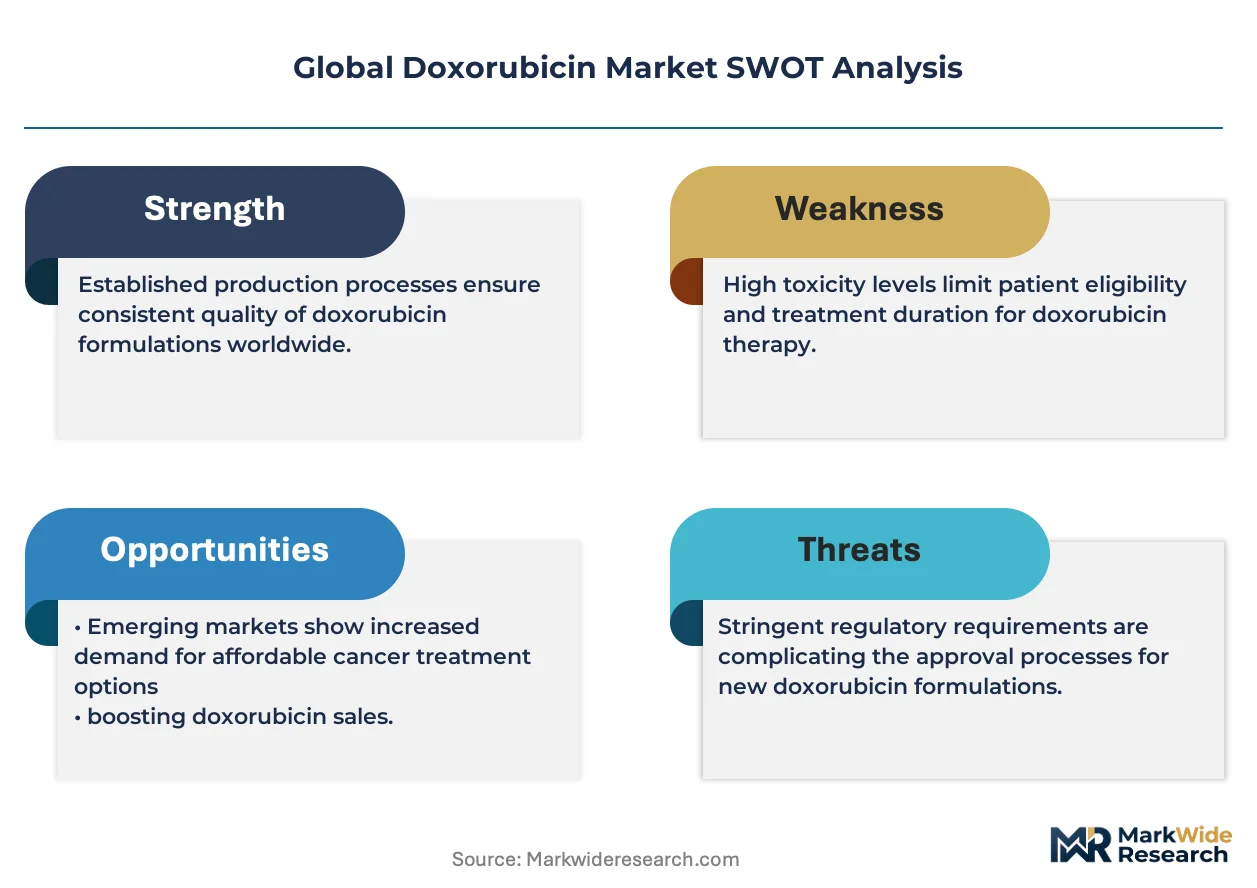
Liposomal formulation superiority is compressing conventional doxorubicin margins while oncology clinic expansion accelerates throughput requirements. Manufacturing location decisions now hinge on divergent bioequivalence standards between FDA and EMA, reshaping supplier investment priorities.
Growth Catalysts
- NMPA GMP Scaling:China's tightened bioequivalence standards for liposomal generics are elevating quality thresholds, enabling domestic manufacturers to secure export registrations into WHO-prequalified tender programs.
- Cardiotoxicity Reduction:Liposomal encapsulation technology extends circulation half-life and attenuates cardiac damage, driving substitution in adjuvant breast cancer protocols across tertiary hospital networks.
- Oncology Infusion Capacity:Hospital systems in the United States and Germany are expanding dedicated chemotherapy suites, creating pull-through for high-volume anthracycline procurement.
Market Restraints
- Streptomyces Fermentation Concentration:Active pharmaceutical ingredient production clusters in India and China, exposing buyers to single-source disruption risks from environmental compliance actions.
- Liposomal Manufacturing Capex:Aseptic nanoliposome production requires dedicated cleanroom infrastructure and specialized extrusion equipment, elevating barrier-to-entry for mid-scale entrants.
- Anthracycline Substitution:Trastuzumab emtansine and other antibody-drug conjugates are capturing HER2-positive breast cancer market segments previously served by doxorubicin-based regimens.
Strategic Opportunities
- Biosimilar Liposomal Pathways:EMA's evolving guidance on complex generic equivalence creates first-mover advantage for European manufacturers mastering pharmacokinetic bridging studies.
- Sarcoma Off-Label Expansion:Research-focused prescribers in Japan and Australia are generating real-world evidence for soft-tissue sarcoma applications, potentially unlocking new therapy area labels.
- Direct Hospital Contracting:Large oncology networks in Brazil and Saudi Arabia are bypassing wholesale distributors, enabling price-volume negotiations with manufacturers holding WHO prequalification.
Industry Challenges
- Oncology Pharmacy Specialization:Complex compounding certification requirements for liposomal preparation are constraining workforce availability, limiting infusion center expansion timelines.
- Multi-Territory Registration Synchronization:Divergent FDA and EMA expectations for liposomal bioequivalence studies force manufacturers to run parallel clinical programs, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Doxorubicin Market |
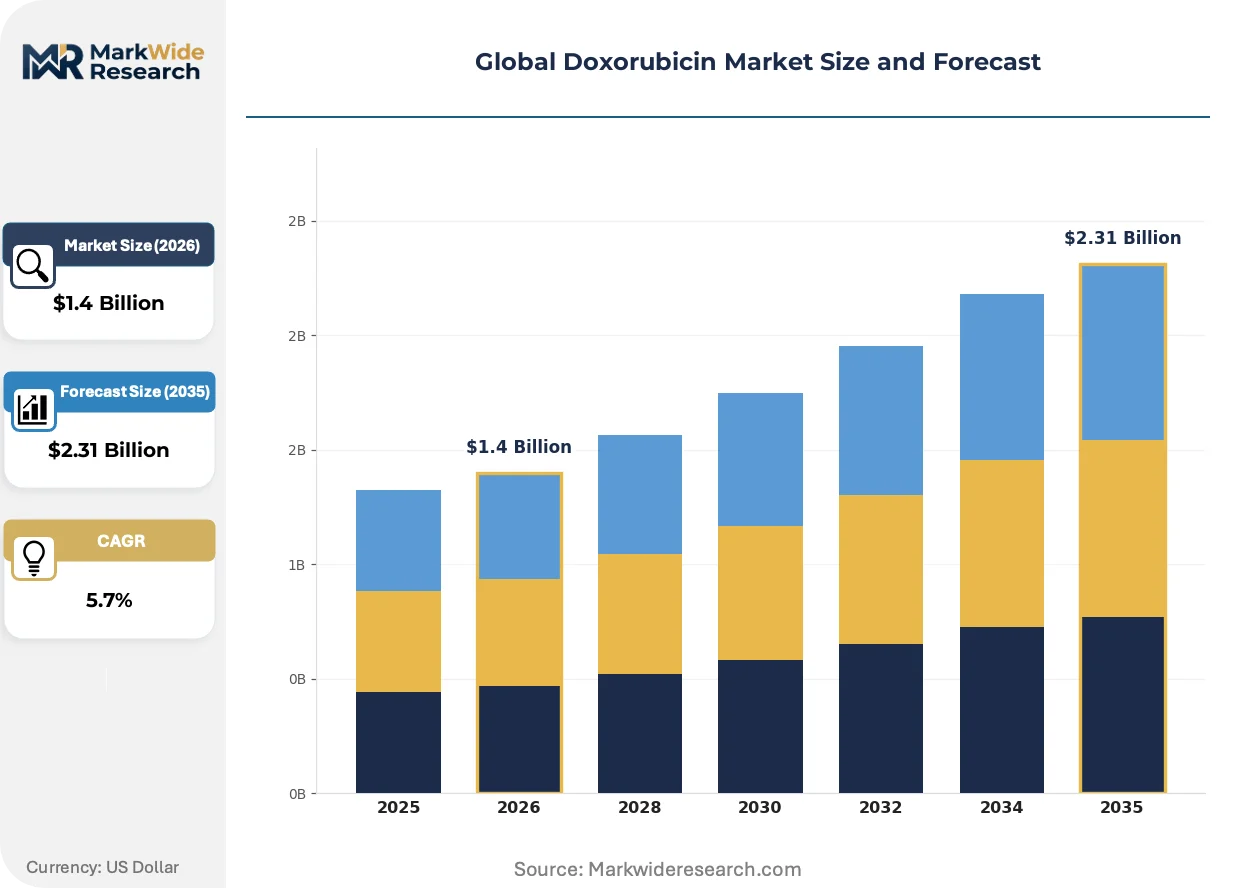
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomal Doxorubicin, Conventional Doxorubicin, PEGylated Doxorubicin, Doxorubicin Hydrochloride Therapy Area: Breast Cancer, Leukemia, Lymphoma, Sarcoma, Ovarian Cancer End User: Oncology Clinics, Cancer Research Institutes, Specialized Hospitals, Diagnostic Laboratories Delivery Mode: Intravenous Injection, Oral Administration, Subcutaneous Injection, Intraperitoneal Delivery |
| Companies Covered | Pfizer Inc., Sun Pharmaceutical Industries Ltd, Johnson & Johnson, Teva Pharmaceutical Industries Ltd, Baxter International Inc., Cipla, Dr. Reddy’s Laboratories Ltd., Cadila Pharmaceuticals, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Doxorubicin Market Shifts & Advancements
Formulation science and regulatory science are advancing in lockstep, with manufacturing process innovation outpacing clinical protocol evolution. These developments are compressing traditional competitive advantages rooted in scale alone.
PEGylated liposomal encapsulation is displacing conventional doxorubicin in first-line lymphoma protocols. Academic medical centers in the United States and Switzerland are adopting liposomal formulations as standard-of-care for elderly patients with pre-existing cardiac risk factors. This substitution pattern is compressing average selling prices for non-liposomal supply while concentrating volume with manufacturers possessing aseptic nanotechnology capabilities.
EMA's tightened GMP Annex 1 requirements for sterile medicinal products are forcing facility upgrades across European manufacturing sites. The revised contamination control expectations mandate continuous environmental monitoring and barrier technology investments, elevating compliance costs for legacy injectable plants. Suppliers serving EU and UK hospital networks are consolidating production into dedicated oncology suites to satisfy inspection intensity.
Hospital procurement committees are consolidating anthracycline purchasing through single-source agreements tied to total oncology spend. Group purchasing organizations in Germany and France are aggregating demand across regional hospital networks, extracting volume discounts in exchange for formulary exclusivity. This concentration is marginalizing smaller distributors and rewarding manufacturers with integrated supply chain control spanning API fermentation through finished dose.
Global Doxorubicin Market Segmentation
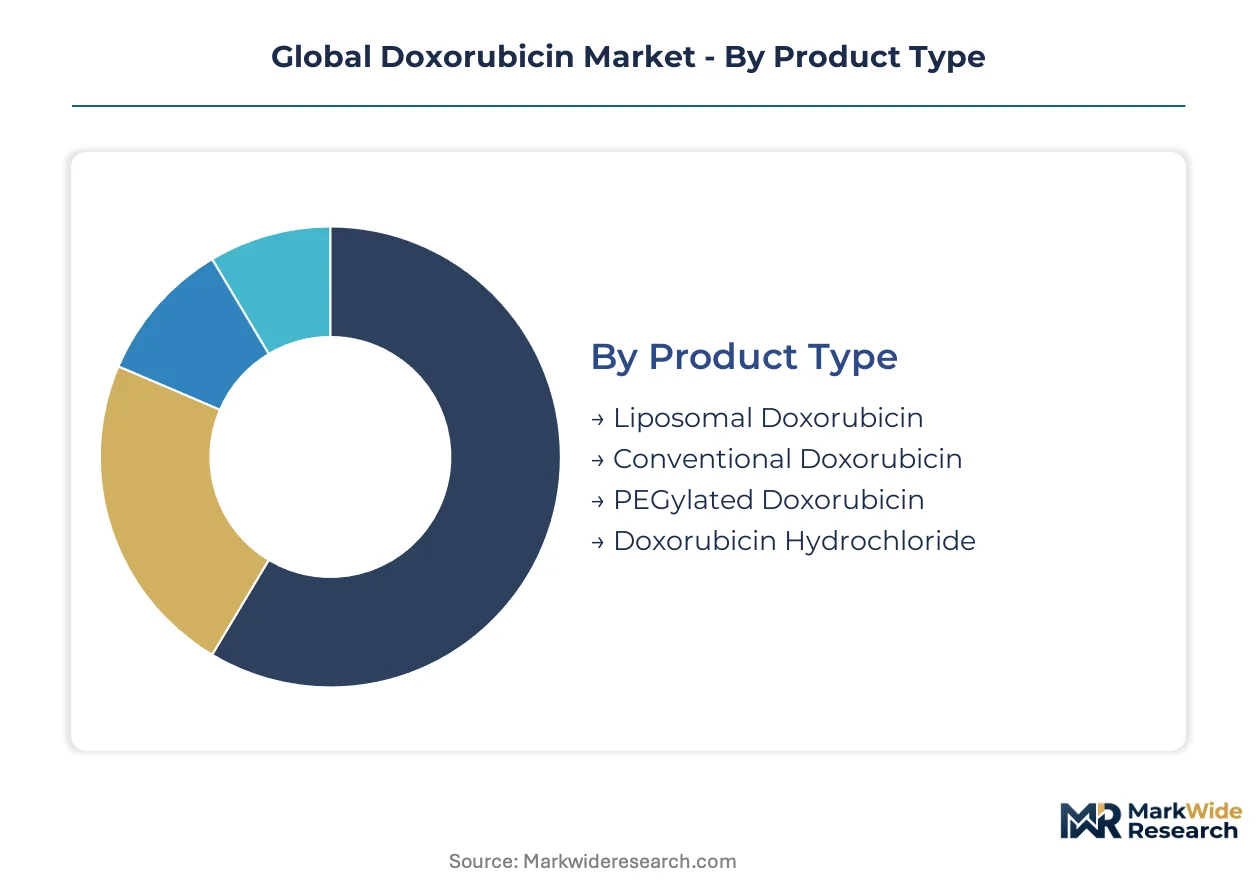
Segmentation in the doxorubicin market reflects divergent manufacturing capabilities, clinical risk profiles, and procurement sophistication across healthcare systems. Formulation complexity and therapy area specialization create distinct margin architectures that reshape supplier competitive positioning.
Product Type:
Margin pools concentrate in nanotechnology-enabled formulations where cardiotoxicity reduction commands pricing power, while commodity-grade supply competes on fermentation scale and regulatory compliance cost.
- Liposomal Doxorubicin:Encapsulation within phospholipid bilayers extends circulation half-life and attenuates cardiac damage. Demand clusters in tertiary hospital networks across the United States and Germany where adjuvant breast cancer protocols prioritize safety margins in elderly cohorts.
- Conventional Doxorubicin:Unencapsulated anthracycline antibiotic produced through Streptomyces fermentation retains volume leadership in price-sensitive procurement environments. Procurement committees in India and Brazil prioritize this segment for first-line lymphoma regimens where cost constraints dominate clinical decision-making.
- PEGylated Doxorubicin:Polyethylene glycol surface modification enhances stealth properties and reduces reticuloendothelial clearance.
- Doxorubicin Hydrochloride:Salt formulation optimized for pH stability and solubility in standard infusion protocols.
Conventional Doxorubicin holds installed capacity. Liposomal Doxorubicin is rotating up the share rankings.
Therapy Area:
Application-specific demand intensity varies with protocol standardization, biomarker stratification, and competitive pressure from targeted therapies.
- Breast Cancer:Anthracycline-containing regimens retain adjuvant positioning despite HER2-directed therapy encroachment. Oncology networks in France and Japan maintain formulary inclusion for triple-negative subtypes where targeted alternatives remain limited.
- Lymphoma:CHOP-protocol standardization sustains predictable demand curves across academic medical centers. Research institutes in Australia generate real-world evidence supporting liposomal substitution in elderly diffuse large B-cell populations.
- Leukemia:Acute myeloid induction protocols incorporate doxorubicin in combination cytarabine regimens.
- Sarcoma:Soft-tissue applications gain prescriber attention through off-label efficacy signals in refractory cases.
- Ovarian Cancer:Platinum-resistant recurrence settings utilize liposomal formulations for palliative cytoreduction.
Breast Cancer maintains protocol penetration depth. Sarcoma is climbing the fastest as research-focused prescribers explore expanded indications.
End User:
Customer type segmentation tracks compounding complexity certification, infusion capacity investment, and research trial participation rates.
- Oncology Clinics:Dedicated chemotherapy suites in the United States and Germany are expanding throughput capacity. These facilities concentrate liposomal demand through direct hospital contracting arrangements that bypass wholesale distribution layers.
- Specialized Hospitals:Tertiary referral centers with integrated pharmacy compounding capabilities manage high-volume anthracycline procurement across multiple malignancy service lines.
- Cancer Research Institutes:Academic medical centers in Switzerland and Japan conduct pharmacokinetic bridging studies for biosimilar development.
- Diagnostic Laboratories:Companion testing facilities support therapeutic monitoring for cardiotoxicity biomarkers.
Specialized Hospitals anchor procurement volume. Oncology Clinics are gaining share fastest through network consolidation and dedicated infusion infrastructure expansion.
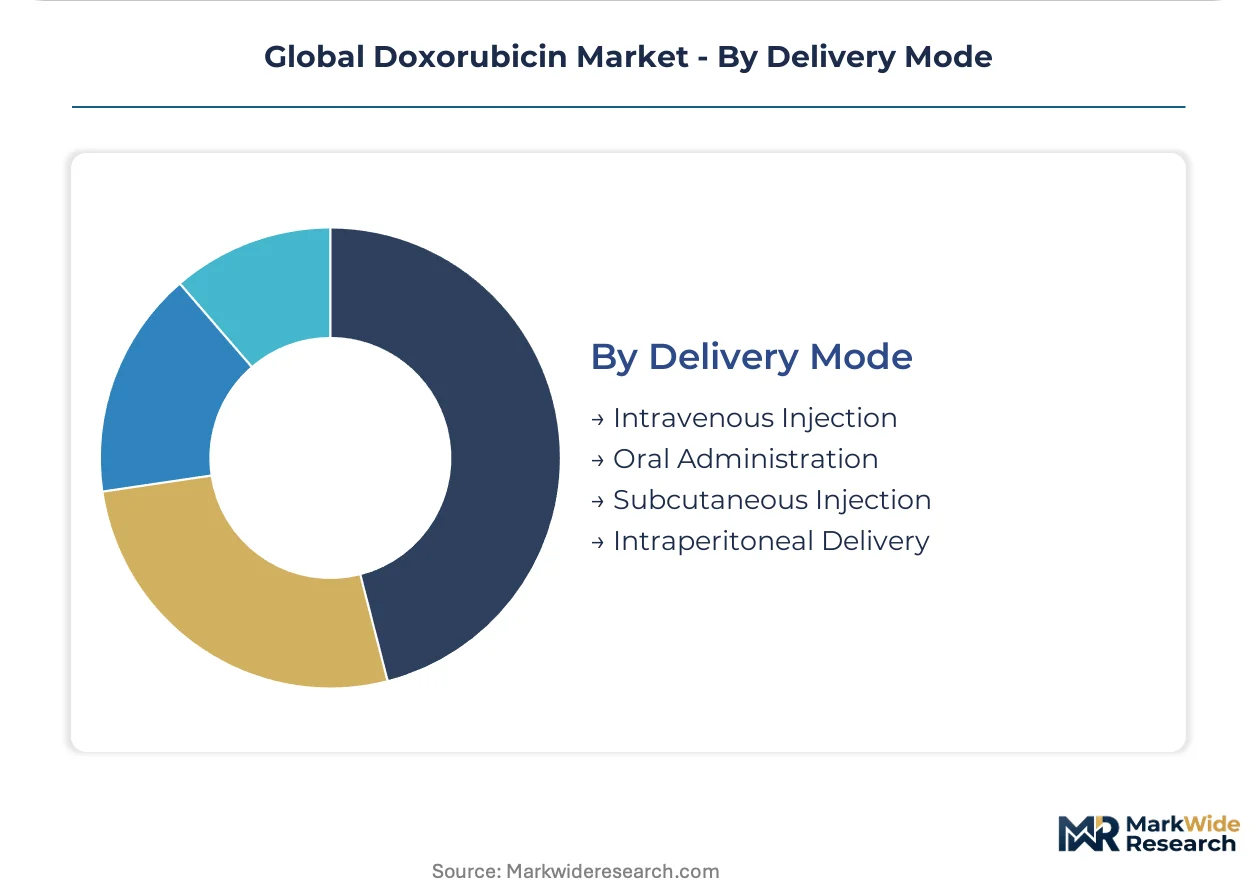
Delivery Mode:
Route of administration segmentation aligns with bioavailability requirements, patient compliance constraints, and compounding infrastructure availability.
- Intravenous Injection:Direct vascular administration enables precise dose control and immediate bioavailability. This mode dominates hospital-based care across China and Saudi Arabia where infusion center capacity expansion accelerates patient throughput.
- Oral Administration:Formulation stability challenges limit clinical adoption despite convenience advantages in outpatient settings.
- Subcutaneous Injection:Alternative vascular access for patients with compromised venous integrity.
- Intraperitoneal Delivery:Regional chemotherapy administration for peritoneal carcinomatosis in ovarian cancer protocols.
Intravenous Injection retains infrastructure dominance. Intraperitoneal Delivery represents the steepest expansion trajectory through cytoreductive surgery integration programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA batch-release protocols anchor the United States as the primary regulatory reference point for liposomal bioequivalence studies, while manufacturing investments cluster in jurisdictions with converging GMP standards. Hospital procurement consolidation and oncology clinic expansion are reshaping demand geography across four major markets.
United States
Tertiary hospital networks in Boston and Houston are expanding dedicated chemotherapy infusion capacity to accommodate rising lymphoma patient throughput. FDA liposomal bioequivalence guidance drives parallel clinical program requirements for manufacturers seeking abbreviated new drug approval pathways. Manufacturing concentration in the Research Triangle and Puget Sound corridor reflects proximity to academic medical centers conducting pharmacokinetic bridging studies.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces are scaling GMP-compliant fermentation capacity to serve both local oncology clinic demand and WHO prequalification export eligibility. NMPA tightened bioequivalence standards for liposomal generics are elevating quality thresholds and filtering smaller producers from tender participation. Shanghai and Suzhou industrial clusters host integrated facilities spanning Streptomyces API production through finished dose aseptic filling.
Germany
Group purchasing organizations across Bavaria and North Rhine-Westphalia are consolidating anthracycline procurement through single-source agreements tied to total oncology spend. EMA GMP Annex 1 revisions mandate continuous environmental monitoring upgrades for sterile injectable facilities serving EU hospital networks. Heidelberg and Munich academic centers generate real-world evidence supporting liposomal substitution in elderly breast cancer cohorts.
India
Cost-optimized conventional doxorubicin production in Hyderabad and Ahmedabad serves emerging market tender programs across Africa and Southeast Asia. CDSCO manufacturing license requirements and WHO prequalification pathways shape investment decisions for suppliers targeting public-sector oncology procurement. API fermentation clusters in Telangana and Gujarat concentrate Streptomyces production capacity.
Japan
PMDA pharmacovigilance requirements for anthracycline cardiotoxicity monitoring influence formulary positioning in Tokyo and Osaka tertiary referral centers. Research institutes in Kansai and Kanto regions conduct biosimilar liposomal development programs targeting domestic and Asian export registration. Aging demographics drive demand for cardiotoxicity-sparing formulations in adjuvant breast cancer protocols.
Global Doxorubicin Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation scale and liposomal manufacturing capability determining competitive position. The structure bifurcates between multinational pharmaceutical conglomerates with aseptic nanotechnology infrastructure and regional generic manufacturers competing on cost-optimized conventional supply. Three archetypes dominate: integrated liposomal specialists, high-volume fermentation-scale producers, and diversified injectable portfolio suppliers. Capacity expansion into dedicated oncology suites and strategic partnerships for pharmacokinetic bridging study execution represent the primary competitive moves reshaping positioning.
Within the integrated multinational tier, Pfizer Inc. and Johnson & Johnson occupy positions anchored by established liposomal manufacturing infrastructure and hospital network contracting relationships. Sun Pharmaceutical Industries Ltd and Dr. Reddy's Laboratories Ltd exemplify the fermentation-scale specialist archetype, with cost-optimized production serving price-sensitive procurement environments. Teva Pharmaceutical Industries Ltd represents the diversified portfolio approach, spanning both branded and generic formulation supply across multiple delivery modes.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd |
| Baxter International Inc. |
| Cipla |
| Dr. Reddy's Laboratories Ltd. |
| Cadila Pharmaceuticals |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between tertiary hospital networks and liposomal manufacturers lock in supply access while compressing price visibility for spot-market buyers, particularly as FDA batch-release protocols and EMA GMP Annex 1 revisions elevate compliance costs across multi-territory suppliers.
Pricing Analysis
Contract-based long-term offtake dominates procurement for liposomal formulations, with price differentiation resting on WHO prequalification status and aseptic manufacturing certification tiers. Cost compression in conventional doxorubicin intensifies as Indian and Chinese fermentation-scale producers compete for emerging market tenders. Oncology clinics in Germany and the United States exhibit lowest price sensitivity due to formulary exclusivity agreements, while public-sector procurement committees in Brazil and Saudi Arabia prioritize economy-tier supply.
Supply Chain Analysis
Inventory cycles for Streptomyces-derived API stretch 18-24 months from fermentation seed to finished dose, creating lead-time vulnerability for buyers lacking captive production. Supply concentrates in Telangana and Gujarat for conventional API, with Jiangsu and Zhejiang hosting integrated liposomal filling capacity. Raw material dependencies include pharmaceutical-grade phospholipids, polyethylene glycol for PEGylation, and specialized extrusion membranes. Single-source vulnerability runs through environmental compliance actions against Indian fermentation clusters. Distribution runs through hospital procurement committees and group purchasing organizations in consolidated European and North American networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The doxorubicin market sits at a platform-economics inflection where liposomal manufacturing capability and pharmacokinetic bridging study execution determine ecosystem access, with EMA-FDA regulatory divergence creating interoperability barriers for suppliers lacking parallel clinical infrastructure.
For Market Incumbents: Shield formulary positioning by consolidating production into dedicated oncology suites satisfying EMA Annex 1 contamination control mandates, while securing pharmacovigilance partnerships with Tokyo and Osaka academic centers to generate cardiotoxicity-sparing real-world evidence. Capacity addition in Suzhou industrial clusters addresses NMPA export registration requirements. Antibody-drug conjugate substitution in HER2-positive breast cancer segments demands pipeline diversification into biosimilar liposomal pathways. For New Entrants and Emerging Players: Anchor in sarcoma off-label expansion opportunities across Australian and Japanese research institutes where protocol standardization remains incomplete. Direct hospital contracting in Brazilian and Saudi Arabian oncology networks bypasses wholesale margin extraction. WHO prequalification investment unlocks public-sector tender eligibility across African and Southeast Asian markets. Master EMA pharmacokinetic bridging methodology to capture first-mover advantage in complex generic equivalence. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-scale specialists with captive Streptomyces capacity and upgradeable aseptic filling infrastructure, as backward integration into API production insulates against single-source disruption. Long-term viability hinges on regulatory optionality across FDA, EMA, and NMPA jurisdictions. Monitor EMA-NMPA convergence on liposomal bioequivalence methodology as the inflection signal determining which manufacturing investments retain cross-border strategic value.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacokinetic Bridging Study Investment | EMA's evolving complex generic guidance rewards European manufacturers mastering equivalence methodology. |
| Backward Integration into Streptomyces Fermentation | Captive API production in Telangana or Gujarat insulates against environmental compliance disruption. |
| WHO Prequalification Pathway Completion | Unlocks tender eligibility for public-sector oncology programs across low- and middle-income countries. |
| Direct Hospital Contracting Expansion | Bypasses wholesale distribution layers in Brazilian and Saudi Arabian consolidated oncology networks. |
| Aseptic Nanoliposome Capacity Buildout | Cleanroom infrastructure and specialized extrusion equipment capture substitution demand from conventional formulations. |
Research Methodology
A standing panel of oncology pharmacy directors, hospital procurement managers, regulatory affairs leads, and formulary specialists provided ongoing calibration across primary fieldwork, with secondary validation drawing from FDA Orange Book filings, EMA assessment reports, ClinicalTrials.gov protocol registries, and WHO prequalification databases. Bottom-up demand modeling across formulation types, therapy areas, and end-user segments triangulated against top-down manufacturer capacity disclosures.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for API movements, hospital procurement database aggregations, and group purchasing organization contract disclosures. The analytical framework modeled patient throughput expansion, regulatory cluster divergence, and substitution patterns across the projection horizon. CAGRs derived from segmented growth rate reconciliation incorporating infusion capacity buildout, bioequivalence standard evolution, and competitive entry timing.
Decision-makers should treat outputs as directional under assumptions of sustained oncology clinic expansion and stable regulatory divergence between FDA and EMA; material convergence on liposomal bioequivalence methodology or abrupt fermentation cluster disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Global Rotavirus Vaccine Market