
 Daratumumab Market | 2026-2036
Daratumumab Market Size, Share, and Industry Trends Forecast 2026-2036
Daratumumab Market Analysis
China is reconfiguring biologics manufacturing capacity through dedicated monoclonal antibody production parks in Suzhou and Shanghai. Johnson & Johnson anchors daratumumab commercialization through its Janssen Biotech division, leveraging decades of oncology infrastructure. Genmab A/S sustains antibody engineering leadership through its DuoBody platform, while Bristol-Myers Squibb competes with rival CD38-directed therapies in overlapping indication spaces.
Daratumumab constitutes a human CD38-directed immunoglobulin G1 kappa monoclonal antibody produced in Chinese hamster ovary cells via recombinant DNA technology, administered intravenously or subcutaneously to induce direct on-tumor and immunomodulatory mechanisms in multiple myeloma treatment. The monoclonal antibody segment dominates current value generation due to originator pricing power and protected intellectual estate, while the biosimilar category is accumulating pipeline assets that will pressure reimbursement thresholds post-patent expiration. Multiple Myeloma therapy area captures the deepest clinical investment, though lymphoma label expansions represent the fastest-growing application frontier as investigators explore CD38 expression patterns.
FDA accelerated approval and breakthrough therapy designations shape development economics for daratumumab developers, while EMA centralized marketing authorization procedures govern European market entry and pricing negotiations. The EU AI Act and GDPR frameworks increasingly condition how real-world evidence platforms collect post-market safety data for biologics. Stakeholders must monitor how CMS Medicare coverage determinations and NICE technology appraisals diverge on subcutaneous formulation value claims.
Market Dynamics
Subcutaneous formulation adoption is compressing administration timeframes and shifting site-of-care economics from infusion centers toward outpatient settings, forcing reimbursement recalibration across Medicare and private payers.
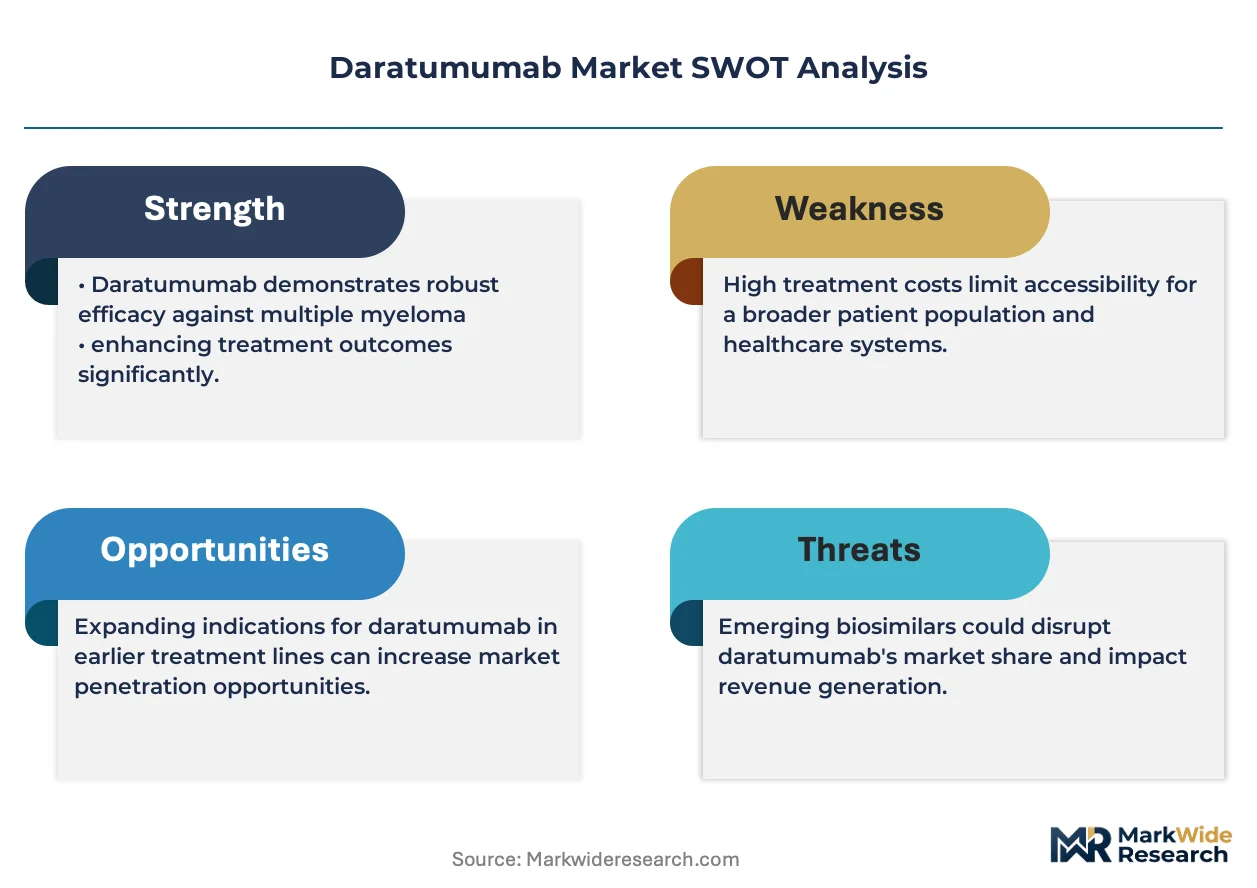
Growth Catalysts
- Frontline label expansion:FDA accelerated approval pathways compress development timelines for combination regimens in newly diagnosed multiple myeloma, expanding addressable patient pools beyond relapsed settings.
- CD38 expression profiling:Diagnostic laboratories are standardizing CD38 immunohistochemistry protocols, enabling precision patient selection for daratumumab-containing protocols.
- Subcutaneous administration infrastructure:Hospital-based oncology departments are retrofitting pharmacy compounding workflows to support subcutaneous daratumumab preparation, reducing chair time requirements.
Market Restraints
- Chinese hamster ovary cell supply concentration:Active pharmaceutical ingredient production clusters in Suzhou and Shanghai create geopolitical exposure for global supply continuity.
- High-dose immunoglobulin competition:Intravenous immunoglobulin manufacturers are capturing overlapping immunomodulatory indications, pressuring daratumumab positioning in some neurology-adjacent protocols.
- EMA centralized procedure delays:European marketing authorization timelines for subcutaneous formulation extensions lag FDA approvals by 12-18 months, compressing commercialization windows.
Strategic Opportunities
- Lymphoma label expansion:CD38 expression in diffuse large B-cell lymphoma subtypes represents an underpenetrated therapeutic frontier with distinct reimbursement pathways.
- Real-world evidence platforms:EU AI Act-compliant data infrastructure enables post-market safety surveillance that supports label extensions and health technology assessment submissions.
- Home administration models:Specialty pharmacy networks are piloting home healthcare nurse administration for subcutaneous daratumumab, displacing traditional infusion center dependency.
Industry Challenges
- Cold chain integrity maintenance:Subcutaneous formulation temperature excursions during last-mile distribution compromise product stability and trigger batch destruction protocols.
- Companion diagnostic co-development:CD38 assay standardization across CLIA-certified laboratories requires harmonization with FDA-approved diagnostic platforms, extending clinical validation timelines.
- Biosimilar manufacturing complexity:Glycosylation pattern replication in follow-on biologics demands specialized bioreactor expertise that concentrates among limited contract development organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Daratumumab Market |
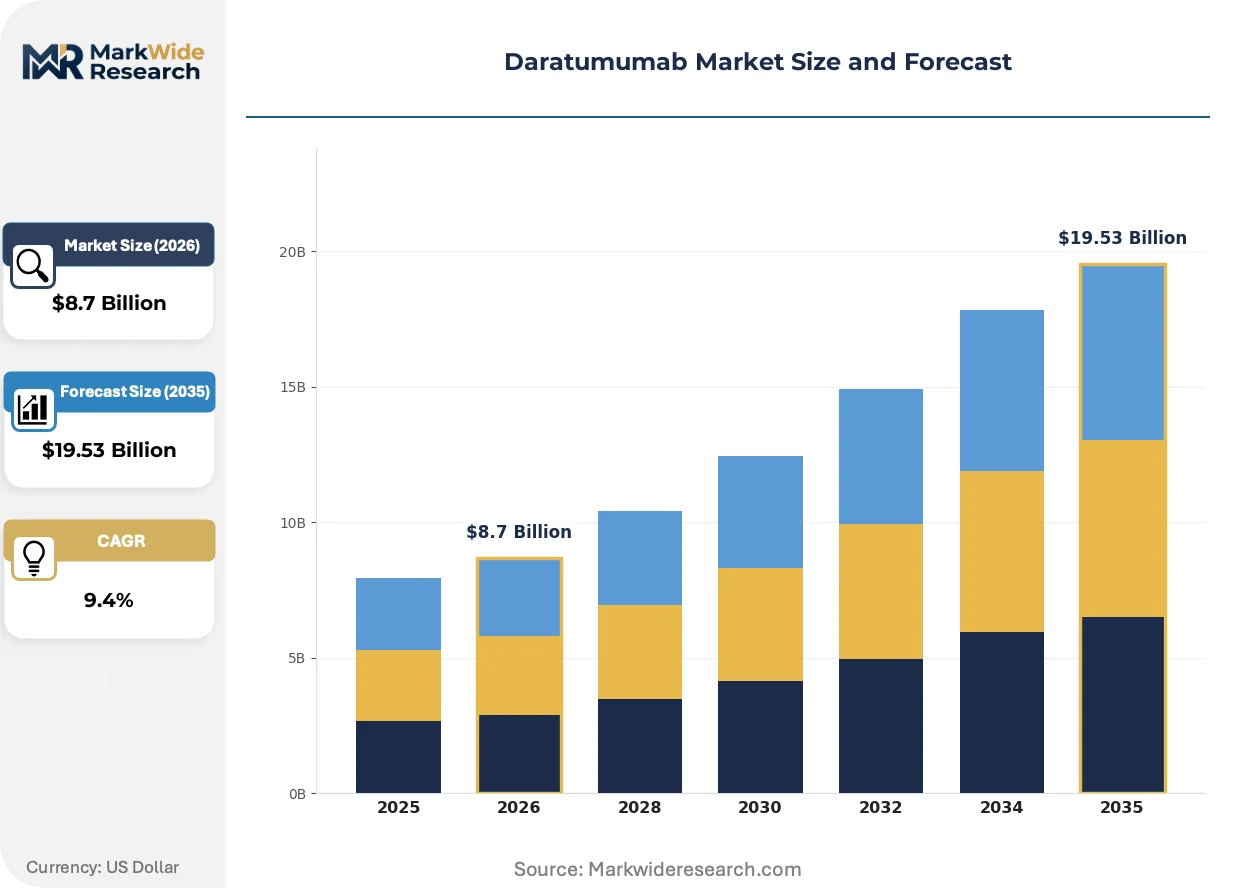
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibody, Biosimilar, Combination Therapy, Injectable Therapy Area: Multiple Myeloma, Lymphoma, Autoimmune Disorders, Solid Tumors End User: Hospitals, Clinics, Homecare Settings, Research Institutions Distribution Channel: Pharmacies, Direct Sales, Wholesalers, Online Channels |
| Companies Covered | Johnson & Johnson (Janssen Biotech), Genmab A/S, Amgen, Bristol-Myers Squibb, Novartis AG, Pfizer, Roche Holding AG, Sanofi, Takeda Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Daratumumab Market Emerging Trajectories
Digital infrastructure is penetrating clinical trial execution and commercial operations simultaneously, compressing evidence generation cycles while enabling direct-to-physician engagement models that bypass traditional field force structures.
Electronic patient-reported outcome capture is digitizing safety surveillance for subcutaneous daratumumab administration. Oncology practices in the United States are deploying smartphone-based symptom logging platforms that feed directly into EHR systems, enabling real-time toxicity management and reducing unplanned emergency department utilization.
EMA's MDR and IVDR convergence is tightening in vitro diagnostic requirements for CD38 companion assays. European notified bodies are demanding extended clinical performance studies for immunohistochemistry platforms, delaying co-launch synchronization between therapeutic and diagnostic approvals and forcing staggered market entry strategies.
Hospital procurement committees are consolidating oncology biologics purchasing through specialty pharmacy benefit managers. Large academic medical centers in the United States are negotiating outcomes-based contracts that tie daratumumab reimbursement to progression-free survival milestones, transferring clinical risk from payers to providers and manufacturers.
Daratumumab Market Segmentation
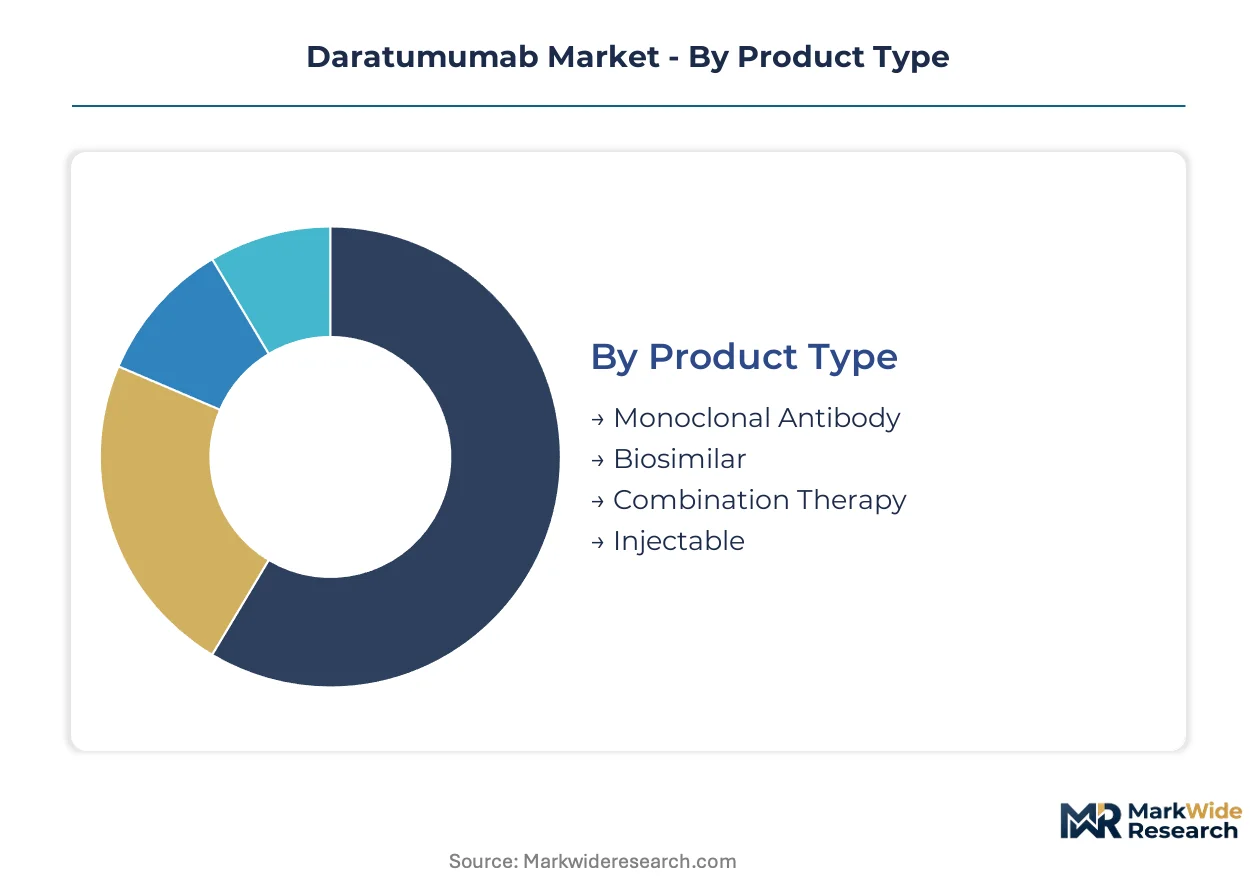
Daratumumab market segmentation reveals distinct commercial rhythms across product lifecycles and care settings. Therapy area and formulation type drive divergent margin profiles, while distribution channel selection determines access speed to prescriber networks.
Product Type:
Cycle times vary dramatically: originator monoclonal antibodies turn inventory slowly due to cold chain requirements and high unit values, while biosimilar development cycles compress as patent cliffs approach and manufacturing platforms mature.
- Monoclonal Antibody:Human CD38-directed immunoglobulin G1 kappa produced in Chinese hamster ovary cells via recombinant DNA technology. Demand concentrates in United States hospital-based oncology departments where Medicare reimbursement frameworks support frontline multiple myeloma therapy access and subcutaneous infusion protocols expand.
- Biosimilar:Follow-on biologics replicating glycosylation patterns through specialized bioreactor expertise. European markets show fastest uptake as EMA centralized procedures and national pricing negotiations create substitution incentives ahead of United States adoption curves.
- Combination Therapy:Daratumumab paired with proteasome inhibitors or immunomodulatory agents in fixed-dose protocols.
- Injectable:Subcutaneous formulation enabling reduced chair time and outpatient administration migration.
Monoclonal antibody dominates installed base. Biosimilar is where expansion concentrates.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention settings, with oncology commanding premium pricing and autoimmune applications requiring volume-based contracting.
- Multiple Myeloma:Primary indication capturing deepest clinical investment through frontline and relapsed/refractory protocols. United States Medicare reimbursement frameworks anchor demand concentration, while diagnostic laboratories standardize CD38 immunohistochemistry for precision patient selection.
- Lymphoma:CD38 expression in diffuse large B-cell lymphoma subtypes drives fastest label expansion activity. European investigators lead exploratory protocols, though FDA accelerated approval pathways compress eventual commercialization timelines for approved indications.
- Autoimmune Disorders:Neurology-adjacent protocols where intravenous immunoglobulin manufacturers compete for overlapping immunomodulatory indications.
- Solid Tumors:Investigational applications exploring CD38 expression patterns beyond hematologic malignancies.
Multiple Myeloma captures revenue concentration. Lymphoma is climbing the fastest.
End User:
Customer type determines service intensity requirements, with hospitals demanding 24-hour pharmacy support and homecare settings requiring specialized nursing networks.
- Hospitals:Academic medical centers and community oncology departments with infusion infrastructure. United States sites retrofit pharmacy compounding workflows for subcutaneous preparation while negotiating outcomes-based contracts tying reimbursement to progression-free survival milestones.
- Clinics:Outpatient oncology practices deploying smartphone-based patient-reported outcome capture for real-time toxicity management.
- Homecare Settings:Specialty pharmacy networks piloting home healthcare nurse administration for subcutaneous daratumumab.
- Research Institutions:Clinical trial sites executing FDA breakthrough therapy designation protocols.
Hospitals dominate installed base. Homecare Settings is gaining share fastest.
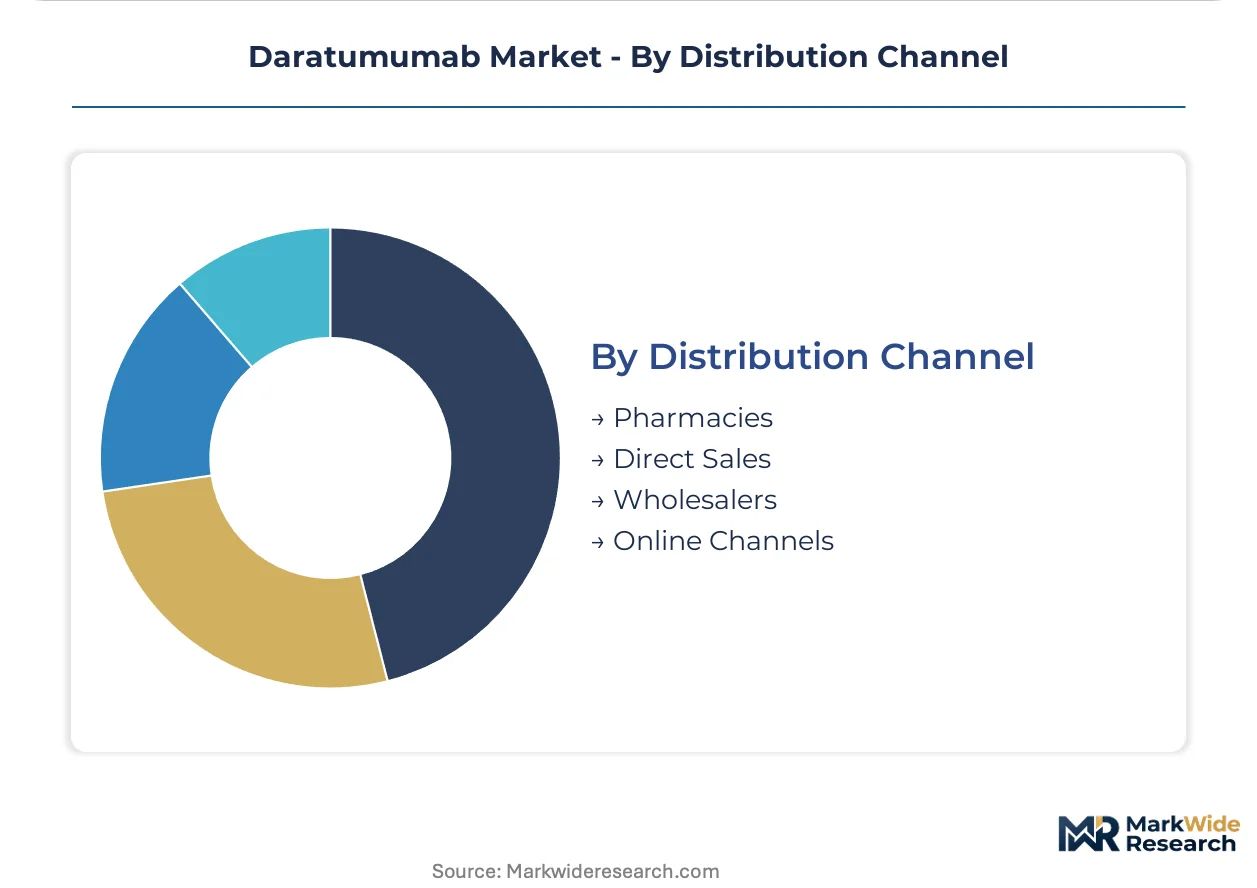
Distribution Channel:
Supply concentration shapes channel selection, with manufacturer-controlled direct sales preserving margin and wholesale relationships enabling geographic reach.
- Pharmacies:Hospital outpatient and specialty pharmacy benefit managers consolidating oncology biologics purchasing. Large United States academic medical centers leverage this channel for outcomes-based contracting structures.
- Direct Sales:Manufacturer-controlled distribution preserving cold chain integrity through dedicated logistics networks. EMA MDR and IVDR convergence tightens requirements for temperature excursion monitoring during last-mile delivery.
- Wholesalers:Regional distributors serving community oncology practices with limited cold chain infrastructure.
- Online Channels:Emerging platform for patient education and copay assistance program enrollment.
Pharmacies dominate installed base. Direct Sales is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production clusters in Suzhou and Shanghai concentrate manufacturing exposure for global daratumumab supply continuity. Demand patterns diverge sharply across reimbursement environments, with Medicare frameworks in the United States anchoring frontline therapy access while European pricing negotiations compress commercialization windows.
United States
Medicare reimbursement frameworks support frontline multiple myeloma therapy access through hospital-based oncology departments. FDA accelerated approval pathways compress development timelines for combination regimens, expanding addressable patient pools. Academic medical centers in Boston and New York Metro retrofit pharmacy compounding workflows for subcutaneous daratumumab preparation.
Germany
EMA centralized marketing authorization procedures govern European market entry, though subcutaneous formulation extensions lag FDA approvals. National pricing negotiations create substitution incentives as biosimilar pipelines mature. The Rhine-Ruhr and Bavarian biotech clusters host contract development organizations specializing in glycosylation pattern replication for follow-on biologics.
China
NMPA regulatory frameworks condition biologics manufacturing capacity expansion through dedicated monoclonal antibody production parks. Domestic CD38-directed therapy development accelerates as national reimbursement lists expand oncology coverage. Suzhou and Shanghai production parks concentrate Chinese hamster ovary cell supply for regional and export markets.
Japan
PMDA marketing authorization timelines for oncology biologics maintain rigorous safety surveillance requirements that extend clinical validation periods. METI industrial policy supports biologics manufacturing infrastructure upgrades. The Kanto region around Tokyo anchors pharmaceutical distribution networks serving aging multiple myeloma patient populations.
United Kingdom
NICE technology appraisals diverge from CMS coverage determinations on subcutaneous formulation value claims, creating reimbursement uncertainty. MHRA post-Brexit regulatory autonomy enables accelerated access pathways for innovative oncology therapies. The Golden Triangle research corridor between London, Oxford, and Cambridge hosts clinical trial sites executing CD38 expression profiling protocols.
Daratumumab Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in antibody engineering and manufacturing infrastructure. The daratumumab market consolidates around originator pricing power and protected intellectual estate, with biosimilar developers accumulating pipeline assets for post-patent pressure. Three archetypes dominate: originator biopharmaceuticals with oncology infrastructure depth, antibody engineering specialists with platform technologies, and diversified pharmaceuticals with overlapping CD38-directed portfolios. Competitive moves concentrate on subcutaneous formulation extensions and real-world evidence platform development.
Among originator biopharmaceuticals, Johnson & Johnson and Genmab A/S occupy positions reflecting distinct strategic foundations. Johnson & Johnson exemplifies the integrated commercialization archetype through its Janssen Biotech division, leveraging decades of oncology field force infrastructure. Genmab A/S represents the antibody engineering specialist tier, sustaining technical leadership through proprietary platform technologies. Bristol-Myers Squibb sits within the diversified competitor category, fielding rival CD38-directed therapies that create indication overlap and pricing tension.
| Leading Market Players |
|---|
| Johnson & Johnson (Janssen Biotech) |
| Genmab A/S |
| Amgen |
| Bristol-Myers Squibb |
| Novartis AG |
| Pfizer |
| Roche Holding AG |
| Sanofi |
| Takeda Pharmaceutical |
| Others |
Supply Flow & Price Mechanics
Chinese hamster ovary cell supply concentration in Suzhou and Shanghai production parks determines both the premium pricing tier spread for originator monoclonal antibodies and the geographic shape of global API sourcing networks, forcing manufacturers to absorb geopolitical risk premiums or diversify bioreactor capacity.
Pricing Analysis
Medicare reimbursement frameworks dictate the pricing tier structure across the United States market, separating premium originator daratumumab from emerging biosimilar alternatives. Price differentiation rests on glycosylation pattern complexity and FDA breakthrough therapy designation status, with hospital procurement committees extracting volume discounts through outcomes-based contracts. Cost compression in the biosimilar tier is intensifying as EMA centralized procedures accelerate European substitution, while academic medical centers remain least price-sensitive due to protected formulary access for combination therapy protocols.
Supply Chain Analysis
Export control regimes on recombinant DNA technology and specialized bioreactor equipment limit technology transfer to emerging manufacturing hubs. Active pharmaceutical ingredient production draws from China, the United States, and Germany, with Chinese hamster ovary cell lines and single-use bioreactor systems serving as critical input dependencies. Single-source vulnerability concentrates in Shanghai-area production parks, where temperature excursion risks during last-mile cold chain distribution trigger batch destruction protocols. Distribution runs through manufacturer-controlled direct sales networks preserving cold chain integrity, supplemented by specialty pharmacy benefit managers consolidating hospital outpatient purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face intensifying substitution pressure from CD38-directed biosimilars and rival immunomodulatory therapies, requiring defensive repositioning around formulation innovation and real-world evidence generation to protect originator value capture.
For Market Incumbents: Harden intellectual estate defense through subcutaneous formulation patent extensions and companion diagnostic co-development with CLIA-certified laboratories. Anchor manufacturing capacity in diversified bioreactor locations beyond Suzhou and Shanghai to mitigate geopolitical exposure. Prioritize vertical integration into glycosylation analytics to preserve quality differentiation against follow-on biologics.
For New Entrants and Emerging Players: Build out lymphoma indication development programs targeting diffuse large B-cell lymphoma subtypes with distinct CD38 expression profiles, where clinical validation timelines remain compressed relative to saturated multiple myeloma markets. Establish European market entry first through EMA centralized procedures, leveraging national pricing negotiation frameworks that favor biosimilar substitution ahead of United States adoption curves. Deploy real-world evidence platforms compliant with EU AI Act data infrastructure requirements as a differentiated regulatory submission strategy.
For Investors and Strategic Acquirers: The market sits at a pre-patent cliff phase that favors antibody engineering specialists with platform technologies and established bioreactor manufacturing partnerships. Long-term viability hinges on subcutaneous formulation market share retention and label expansion execution into lymphoma indications over the next decade. Monitor CMS Medicare coverage determinations on subcutaneous versus intravenous formulation value claims as the critical inflection signal for reimbursement trajectory shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Extension | FDA accelerated approval compresses development timelines while shifting site-of-care economics toward outpatient settings. |
| CD38 Companion Diagnostic Co-development | Harmonization with FDA-approved diagnostic platforms extends clinical validation timelines but locks in precision patient selection. |
| Real-World Evidence Platform Deployment | EU AI Act-compliant data infrastructure enables post-market safety surveillance supporting label extensions and health technology assessments. |
| Specialty Pharmacy Network Integration | Home healthcare nurse administration pilots for subcutaneous daratumumab displace traditional infusion center dependency. |
| Biosimilar Manufacturing Scale-Up | Glycosylation pattern replication expertise concentrates among limited contract development organizations in the Rhine-Ruhr cluster. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Primary interviews engaged drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across the United States, Germany, and China. Bottom-up patient population modeling and top-down revenue triangulation validated segmentation outputs across therapy area, formulation type, and distribution channel dimensions.
Forecast inputs considered treatment line positioning, administration route adoption curves, regional regulatory cluster dynamics, and biosimilar pipeline maturation across the projection horizon. Value outputs reflect segment-specific pricing trajectories and volume assumptions derived from formulary penetration models and Medicare claims analysis. CAGRs were computed from compound growth pathways anchored in frontline label expansion timelines and subcutaneous formulation substitution rates.
Stress conditions across Chinese hamster ovary cell supply disruption, EMA centralized procedure delays, and CMS coverage determination reversals were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding patent expiration sequencing and biosimilar substitution elasticity. Material shifts in FDA accelerated approval pathway requirements or NICE technology appraisal methodologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market