
 Mtor Inhibitors Market | 2026-2036
Mtor Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Mtor Inhibitors Market Outlook
Oncology centers within hospital systems are redrawing procurement priorities for mTOR inhibitors as combination regimens displace monotherapy protocols across renal cell carcinoma and breast cancer lines. Novartis AG leverages its vertical control over everolimus supply chains to sustain pricing power in transplant and oncology indications. Pfizer Inc. competes through differentiated kinase inhibitor portfolios that anchor mTOR combinations in clinical practice guidelines. AstraZeneca PLC specializes in immuno-oncology pairings that extend mTOR utility into checkpoint inhibitor protocols.
mTOR inhibitors constitute a class of serine/threonine kinase inhibitors that block the mechanistic target of rapamycin pathway, disrupting cell cycle progression and angiogenesis in mammalian cells through allosteric binding to FKBP12. These compounds serve primarily as antiproliferative agents in oncology, transplant immunosuppression, and cardiovascular stent coatings. Everolimus dominates current revenue pools due to its breadth of approved oncology and transplant indications, while zotarolimus occupies a narrower but defensible niche in drug-eluting stent applications. Injectable delivery modes command premium reimbursement in hospital settings, though oral formulations drive volume in outpatient oncology clinics where patient compliance determines protocol adherence.
The FDA, EMA, and WHO collectively shape mTOR inhibitor development through oncology-specific accelerated approval frameworks, pediatric investigation plans, and bioequivalence standards for generic rapamycin analogs. These regulators mandate cardiovascular safety monitoring for sirolimus derivatives and enforce manufacturing quality standards that limit market entry to validated API producers. Stakeholders must monitor how FDA breakthrough therapy designations and EMA conditional marketing authorizations reshape competitive timelines for next-generation mTORC1/mTORC2 dual inhibitors.
Market Dynamics
Combination therapy protocols are compressing mTOR inhibitor utilization patterns as oncology departments prioritize first-line regimens over sequential monotherapy, forcing manufacturers to anchor clinical trial designs around checkpoint inhibitor pairings rather than standalone efficacy endpoints.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses Phase II-to-launch timelines for dual mTORC1/mTORC2 inhibitors, enabling earlier commercialization in renal cell carcinoma lines.
- Hospital-based oncology procurement:Integrated delivery networks in the United States are consolidating formularies around mTOR combinations, creating volume concentration in academic medical centers.
- Biomarker-driven patient stratification:PI3K/AKT/mTOR pathway genomic testing is expanding addressable populations for targeted therapy selection in breast cancer and neuroendocrine tumor indications.
Market Restraints
- API supply concentration:Rapamycin derivative active pharmaceutical ingredient production clusters in Chinese and Indian contract manufacturers, exposing sponsors to single-source risk and customs inspection delays.
- Cardiovascular safety monitoring mandates:FDA and EMA post-marketing requirements for sirolimus derivatives impose ongoing trial costs that erode margin on mature transplant indications.
- Immuno-oncology substitution:PD-1/PD-L1 checkpoint inhibitors are capturing first-line renal cell carcinoma share previously held by mTOR-based regimens, compressing addressable patient pools.
Strategic Opportunities
- Pediatric oncology expansion:EMA Paediatric Investigation Plans and FDA Pediatric Study Requirements create exclusivity extensions for sponsors completing mandated trials in tuberous sclerosis complex and high-grade glioma.
- Drug-eluting stent coating innovation:Zotarolimus-limus analog formulations for peripheral artery disease represent underpenetrated vascular intervention segments with differentiated pharmacokinetic profiles.
- Oral bioavailability advancement:Nanoparticle and amorphous solid dispersion technologies are improving everolimus absorption variability, enabling outpatient administration models that reduce hospital infusion center dependency.
Industry Challenges
- Biostatistical talent scarcity:Adaptive trial design expertise for oncology combination studies commands premium compensation, constraining mid-cap developers' clinical operations capacity.
- Legacy immunosuppression protocol integration:Transplant centers face workflow friction embedding mTOR inhibitors into calcineurin-inhibitor-sparing regimens due to therapeutic drug monitoring complexity and graft rejection risk protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mtor Inhibitors Market |
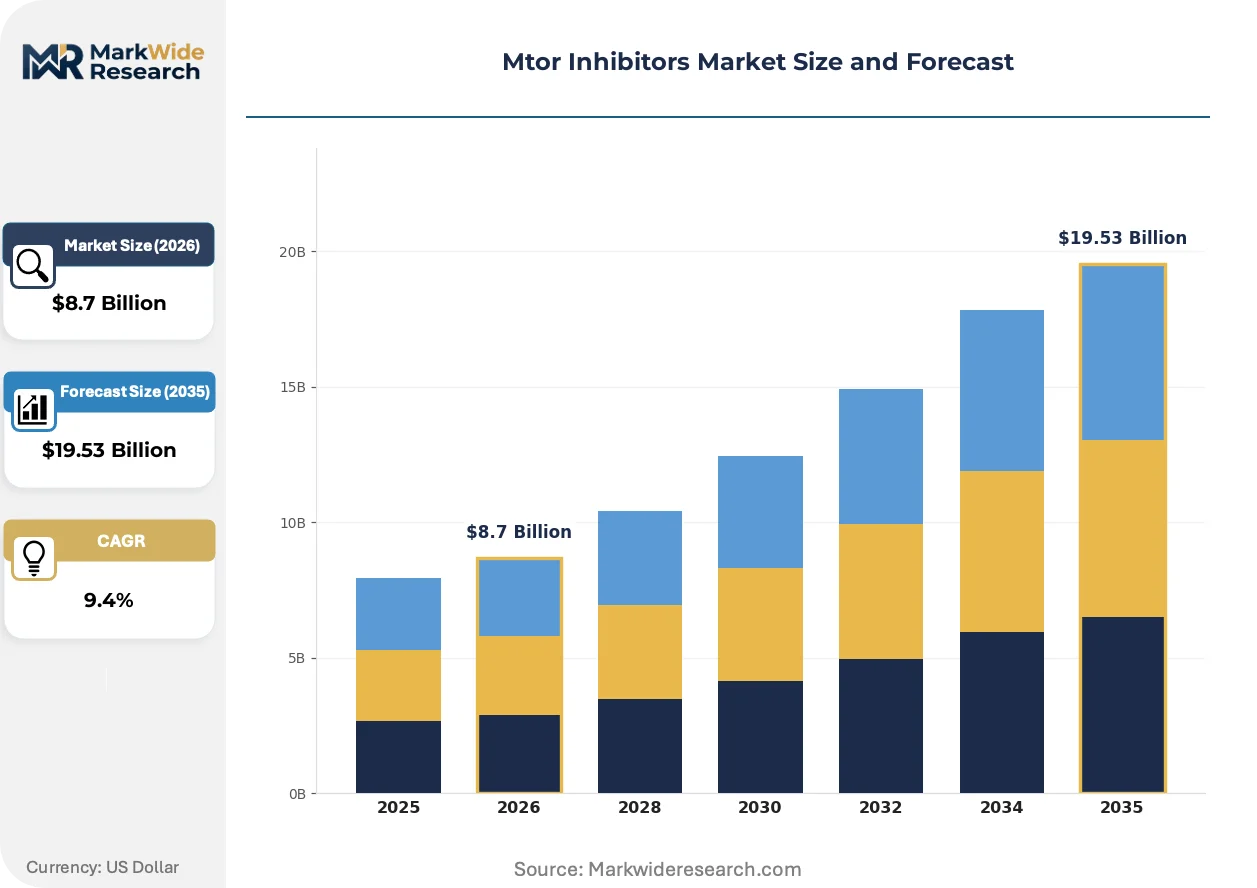
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Everolimus, Temsirolimus, Zotarolimus, Sirolimus End User: Hospitals, Clinics, Research Institutions, Pharmaceutical Companies Delivery Mode: Oral, Injectable, Patch, Implant Application: Oncology, Autoimmune Diseases, Organ Transplantation, Cardiology |
| Companies Covered | Novartis AG, Pfizer Inc., AstraZeneca PLC, Merck & Co. Inc., AbbVie Inc., Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd, Johnson & Johnson, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mtor Inhibitors Market Strategic Shifts
Next-generation mTOR pathway modulation is fragmenting into distinct mechanistic approaches as developers pursue selectivity advantages over allosteric rapamycin analogs, with regulatory science and reimbursement mechanics adapting to biomarker-defined patient subsets.
ATP-competitive mTOR kinase inhibitors are displacing allosteric FKBP12-dependent compounds in early-phase oncology pipelines by enabling complete mTORC1 and mTORC2 blockade. Academic medical centers in the United States are prioritizing these agents for triple-negative breast cancer and castration-resistant prostate cancer protocols. The shift is compressing development timelines for rapamycin-insensitive indications while forcing legacy sponsors to defend transplant and cardiovascular stent franchises through formulation patents.
EMA's revised Guideline on Clinical Evaluation of Anticancer Agents mandates overall survival endpoints for mTOR inhibitor maintenance therapy approvals, elevating trial costs and duration. The industrial consequence is a bifurcation between large-cap sponsors funding registrational survival studies and mid-cap developers retreating to biomarker-enriched Phase II strategies. Oncology divisions in Germany and France are responding by conditioning formulary inclusion on mature survival data rather than progression-free survival surrogates.
Hospital procurement committees are consolidating mTOR inhibitor purchasing through oncology-focused group purchasing organizations, displacing individual pharmacy-level contracting. The channel disruption concentrates volume leverage in three United States-based GPOs that demand standardized dosing protocols and adherence metrics. Academic medical centers in the Northeast and Midwest are most visibly consolidating purchasing, with transplant and oncology service lines merging formulary decision-making under integrated pharmacy leadership.
Mtor Inhibitors Market Segmentation
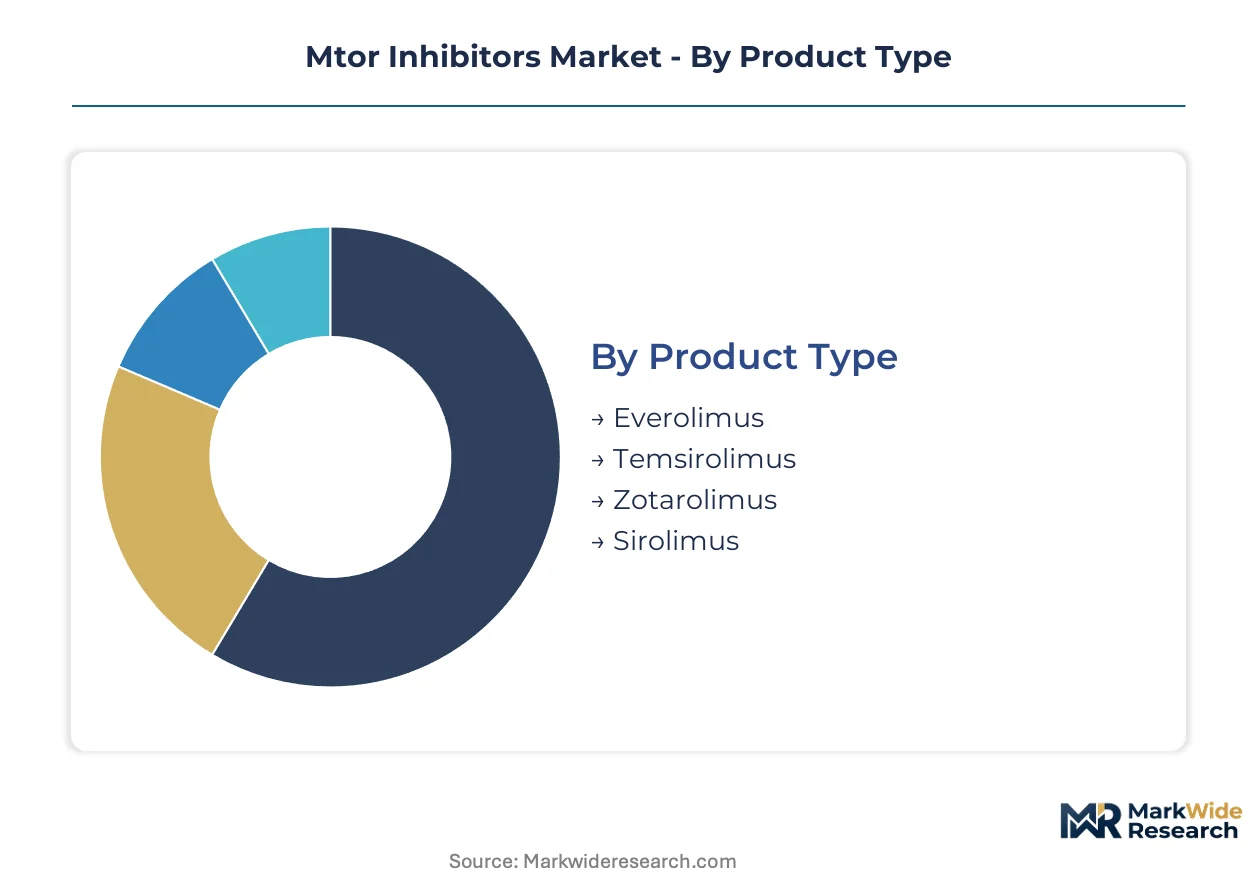
mTOR inhibitor procurement patterns diverge sharply across delivery modes and clinical settings, with regulatory approval pathways determining which segments capture hospital formulary slots versus outpatient pharmacy volume. Understanding these structural divisions reveals where pricing power concentrates and where generic substitution pressures mount.
Product Type:
FDA and EMA approval histories for each rapamycin analog have created divergent commercial ecosystems, with oncology label expansions and transplant maintenance protocols determining which compounds sustain premium reimbursement versus commodity pricing.
- Everolimus:This hydroxyethyl ether derivative of sirolimus achieves higher oral bioavailability through improved metabolic stability, enabling once-daily dosing in renal cell carcinoma and breast cancer protocols. Demand concentrates in United States academic medical centers where NCCN guideline inclusion drives formulary placement for neuroendocrine tumor and tuberous sclerosis complex indications. The compound's breadth across oncology and transplant immunosuppression creates pricing resilience against generic entry.
- Temsirolimus:A prodrug ester formulation designed for intravenous administration, this agent delivers rapid systemic exposure in patients with compromised gastrointestinal absorption. United States hospital oncology departments prioritize temsirolimus for first-line renal cell carcinoma where rapid disease control takes precedence over oral convenience, though infusion center capacity constraints limit volume expansion.
- Zotarolimus:Tetrazole-containing macrocyclic lactone engineered for controlled release from drug-eluting stent coatings, exhibiting tissue-selective retention kinetics distinct from systemic immunosuppressants.
- Sirolimus:The foundational rapamycin compound now facing accelerated generic penetration in transplant maintenance, with API oversupply from Indian contract manufacturers compressing margin on mature indications.
Established volume favors everolimus; emerging adoption favors zotarolimus as peripheral artery disease stent protocols expand.
End User:
Procurement authority and reimbursement mechanics fragment demand across institutional settings, with integrated delivery networks consolidating purchasing leverage while research institutions drive early-phase clinical trial volume.
- Hospitals:Inpatient oncology and transplant service lines command mTOR inhibitor procurement through 340B drug pricing program eligibility and bundled payment models, with pharmacy and therapeutics committees gatekeeping formulary access based on clinical pathway adherence metrics.
- Clinics:Community oncology practices in the United States face reimbursement compression under the Oncology Care Model, driving preference for oral everolimus regimens that minimize infusion center overhead.
- Research Institutions:Academic medical centers with NCI-designated cancer centers anchor investigator-initiated trials for next-generation mTORC1/mTORC2 inhibitors, creating demand concentration for experimental compounds prior to regulatory submission.
- Pharmaceutical Companies:Contract manufacturing organizations and sponsor companies procure reference-grade API for bioequivalence studies and formulation development, with quality standards exceeding commercial pharmaceutical grade.
Reimbursement concentration favors hospitals; protocol flexibility favors clinics.
Delivery Mode:
Patient compliance requirements and site-of-care economics determine which formulation technologies capture volume, with hospital infusion centers defending injectable revenue against oral displacement.
- Oral:Tablet and liquid formulations enable outpatient administration, reducing hospital dependency but requiring patient adherence monitoring programs.
- Injectable:Intravenous and subcutaneous routes command premium reimbursement in hospital settings, with temsirolimus and investigational mTOR inhibitors targeting this channel for acute oncology indications.
- Patch:Transdermal delivery systems in development for sirolimus aim to bypass first-pass metabolism and improve therapeutic drug monitoring predictability in transplant populations.
- Implant:Zotarolimus-eluting stents and intravitreal inserts represent device-drug combination products regulated under distinct FDA pathways, with cardiovascular and ophthalmology specialists driving adoption.
Cost efficiency favors oral; therapeutic control favors injectable.
Application:
Clinical evidence requirements and regulatory precedent create divergent competitive dynamics across therapeutic areas, with oncology commanding the most intensive trial investment and transplant offering the most defensible maintenance revenue.
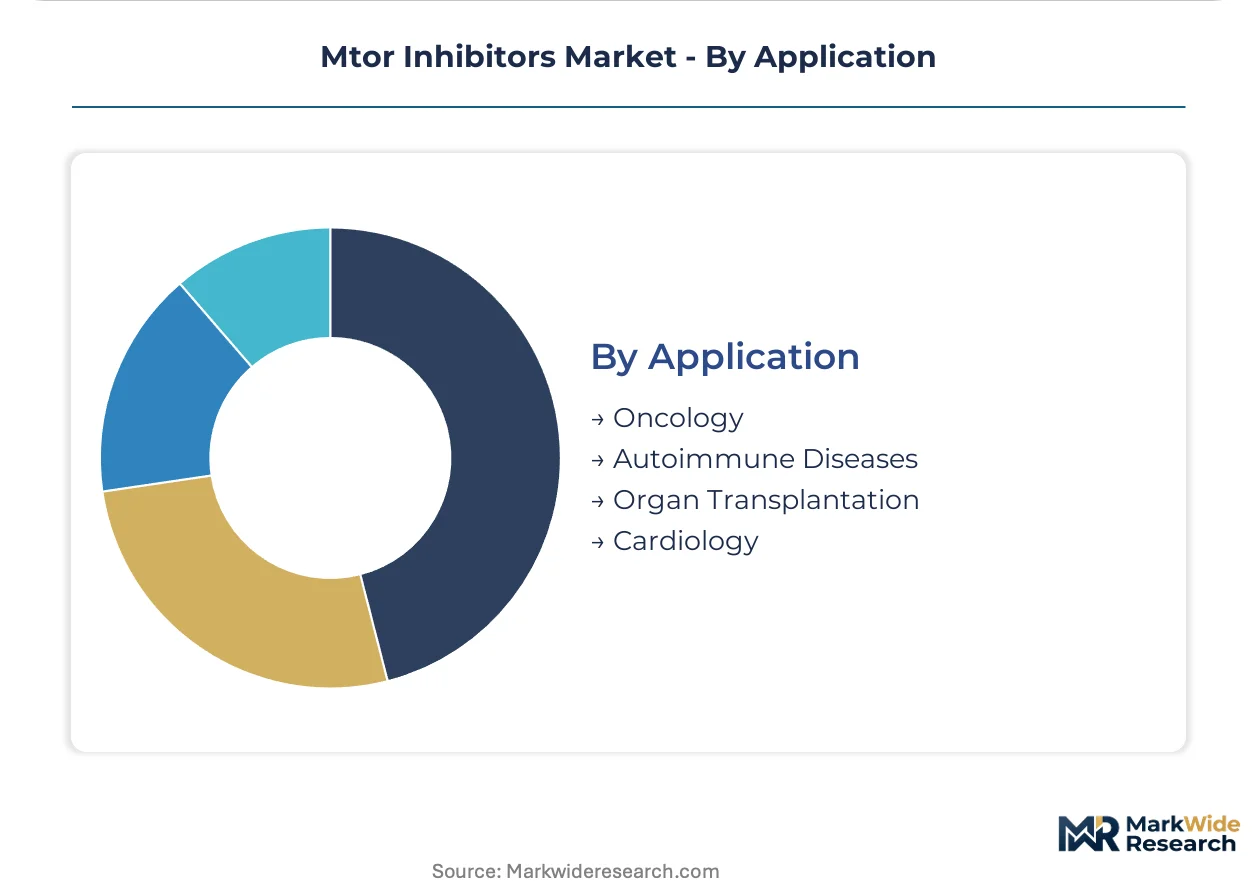
- Oncology:Renal cell carcinoma, breast cancer, and neuroendocrine tumor indications dominate prescription volume, with biomarker-enriched patient selection expanding addressable populations.
- Autoimmune Diseases:Lupus nephritis and rheumatoid arthritis represent exploratory indications where mTOR modulation offers immunosuppression with potentially reduced infection risk versus conventional agents.
- Organ Transplantation:Calcineurin-inhibitor-sparing regimens in kidney and liver transplantation sustain long-term revenue through chronic administration, though generic sirolimus erosion pressures originator sponsors.
- Cardiology:Drug-eluting stent coatings constitute a specialized segment where zotarolimus competes with paclitaxel and everolimus analogs on vessel healing profiles and late stent thrombosis rates.
Evidence investment favors oncology; duration economics favor transplantation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution for temperature-sensitive mTOR compounds, while direct rail links from Basel to Frankfurt secure Swiss-German manufacturing corridors.
United States
Memorial Sloan Kettering Cancer Center and MD Anderson anchor investigator-initiated trials for dual mTORC1/mTORC2 inhibitors. The FDA's breakthrough therapy designation compresses Phase II-to-launch timelines for renal cell carcinoma indications. Hospital procurement committees in the Northeast and Midwest consolidate purchasing through oncology-focused group purchasing organizations.
Germany
Heidelberg University Hospital and Charité Berlin drive biomarker-driven patient stratification for PI3K/AKT/mTOR pathway testing. The EMA's revised Guideline on Clinical Evaluation of Anticancer Agents mandates overall survival endpoints for maintenance therapy approvals. The Rhine-Main biotechnology cluster concentrates formulation development for oral bioavailability advancement.
Switzerland
University Hospital Basel and Lausanne University Hospital specialize in immuno-oncology pairings extending mTOR utility into checkpoint inhibitor protocols. Swissmedic enforces manufacturing quality standards that limit market entry to validated API producers. The Basel pharmaceutical hub coordinates European supply chain logistics for rapamycin derivatives.
Japan
Tokyo's National Cancer Center Hospital anchors clinical trial networks for pediatric oncology expansion in tuberous sclerosis complex. The PMDA's Sakigake designation system accelerates review for innovative oncology therapies. The Kansai region's pharmaceutical manufacturing belt produces reference-grade API for bioequivalence studies.
India
Apollo Hospitals and Tata Memorial Centre drive adoption of generic sirolimus in calcineurin-inhibitor-sparing transplant regimens. The CDSCO's accelerated approval pathway for oncology drugs enables earlier market access for domestic manufacturers. Hyderabad's active pharmaceutical ingredient corridor supplies rapamycin derivatives to global contract manufacturers.
Mtor Inhibitors Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates controlling vertically integrated supply chains from API production to hospital distribution. The competitive terrain splits between originator sponsors defending oncology and transplant franchises through formulation patents, and generic manufacturers exploiting rapamycin derivative commoditization. Two strategic archetypes dominate: large-cap sponsors funding registrational survival studies, and mid-cap developers retreating to biomarker-enriched Phase II strategies. Dominant competitive moves include portfolio diversification into immuno-oncology pairings and geographic expansion through oncology-focused group purchasing organization contracts.
Among Swiss-based pharmaceutical conglomerates, Novartis AG exemplifies the integrated archetype through captive supply chain control. Pfizer Inc. and AstraZeneca PLC represent the diversified portfolio approach, anchoring mTOR combinations in clinical practice guidelines through differentiated kinase inhibitor portfolios and immuno-oncology specialization respectively.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| AstraZeneca PLC |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Bristol Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Generic sirolimus substitution is compressing originator margins across transplant maintenance indications while simultaneously shifting API procurement gravity toward Indian and Chinese contract manufacturers. This input displacement is reshaping supply geography toward Hyderabad's pharmaceutical corridor and Zhejiang's chemical synthesis clusters, with pricing economics now tethered to spot-market rapamycin derivative costs rather than innovator-determined benchmarks.
Pricing Analysis
Three-tier pricing structure across originator, authorized generic, and commodity generic levels dominates mTOR inhibitor procurement. Price differentiation hinges on FDA Orange Book exclusivity status and therapeutic drug monitoring service bundling. Cost compression in the commodity tier is intensifying because Indian API oversupply enables aggressive tender bidding. Community oncology clinics exhibit highest price sensitivity, while academic medical centers prioritize clinical pathway adherence over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States hospital systems, though European distributors maintain strategic stockpiles of temperature-sensitive everolimus formulations. API production draws from India, China, and Switzerland, with rapamycin fermentation broth and hydroxyethyl ether intermediates constituting critical inputs. Single-source vulnerability concentrates in Zhejiang province's specialty chemical manufacturers. Distribution runs through oncology-focused group purchasing organizations that consolidate volume leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mTOR inhibitor market functions as a service-attach opportunity where patient adherence monitoring programs and therapeutic drug testing services expand faster than pharmaceutical product revenue. This recurring-revenue layer captures value through protocol compliance data that secures formulary placement.
For Market Incumbents: Shield oncology franchise value by deepening backward integration into rapamycin fermentation capacity and securing 340B contract pharmacy networks. PD-1/PD-L1 checkpoint inhibitor substitution in renal cell carcinoma represents the primary threat. Captive API production constitutes the critical defensive lever against generic margin erosion.
For New Entrants and Emerging Players: Differentiate on biomarker-driven patient stratification capabilities for PI3K/AKT/mTOR pathway testing. Peripheral artery disease drug-eluting stent coatings offer the most penetrable white space, with zotarolimus-analog formulations commanding premium positioning. Pursue cardiovascular device-drug combination regulatory pathways as the go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap developers with adaptive trial design expertise and EMA Paediatric Investigation Plan completion. Long-term viability hinges on dual mTORC1/mTORC2 inhibitor pipelines that escape rapamycin-insensitive resistance mechanisms. Watch FDA breakthrough therapy designation velocity as the inflection signal for competitive timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Dual mTORC1/mTORC2 inhibitor programs in triple-negative breast cancer compress development timelines against allosteric analogs. |
| Regulatory Approval Pathway | EMA conditional marketing authorizations enable earlier commercialization in renal cell carcinoma maintenance settings. |
| Manufacturing Scale-Up | Backward integration into rapamycin fermentation secures API supply continuity for everolimus originators. |
| Pipeline Diversification | Immuno-oncology pairings with checkpoint inhibitors extend mTOR utility into PD-1/PD-L1 combination protocols. |
| Long-term Supply Agreement | Group purchasing organization contracts consolidate hospital procurement volume and standardize dosing protocols. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated on segment estimates.
Segmentation dimensions modeled include product type, delivery mode, application, and end-user setting across the projection horizon. CAGRs derived from patient population epidemiology, label expansion timelines, and reimbursement trajectory analysis. Forecast inputs incorporated biomarker testing adoption curves and group purchasing organization contract renewal patterns.
Forecasts assume regulatory continuity in FDA breakthrough therapy designations and EMA conditional marketing authorizations; material policy shifts would require re-modeling. Revision becomes warranted when checkpoint inhibitor substitution rates in first-line renal cell carcinoma cross thresholds that compress mTOR combination addressable populations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market