
 Global Fibrinogen Concentrates Market | 2026-2036
Global Fibrinogen Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fibrinogen Concentrates Market Intelligence
Plasma-derived purity standards are redrawing competitive boundaries in fibrinogen concentrates. CSL Behring leverages vertical integration across plasma collection and fractionation to sustain supply security in North American and European markets. Octapharma anchors its position through specialized expertise in plasma protein therapies, while Grifols differentiates via manufacturing scale across multiple international production sites.
Fibrinogen concentrates are purified plasma-derived proteins with standardized clotting activity measured in milligrams per vial, manufactured through cryoprecipitation or chromatographic fractionation of human plasma to restore hemostasis during bleeding episodes. Human fibrinogen dominates current revenue pools due to established clinical validation and regulatory familiarity, while recombinant fibrinogen represents the fastest-growing product category as manufacturers invest in cell-line expression systems to reduce plasma dependency. Hospital end users command the largest share of procurement volume given their central role in managing perioperative bleeding and trauma coagulopathy.
The FDA enforces Current Good Manufacturing Practice requirements for plasma-derived products, while the EMA's MDR framework imposes strengthened traceability and post-market surveillance obligations across European markets. China's NMPA has accelerated review pathways for innovative biologics including recombinant coagulation factors, reshaping market access dynamics for multinational suppliers. Stakeholders must monitor evolving plasma collection economics and recombinant manufacturing yields as determinants of long-term competitive positioning and pricing power.
Market Dynamics
Plasma supply scarcity and recombinant manufacturing maturation are restructuring competitive boundaries in fibrinogen concentrates, forcing manufacturers to choose between securing donor networks or investing in cell-line production platforms.
Growth Catalysts
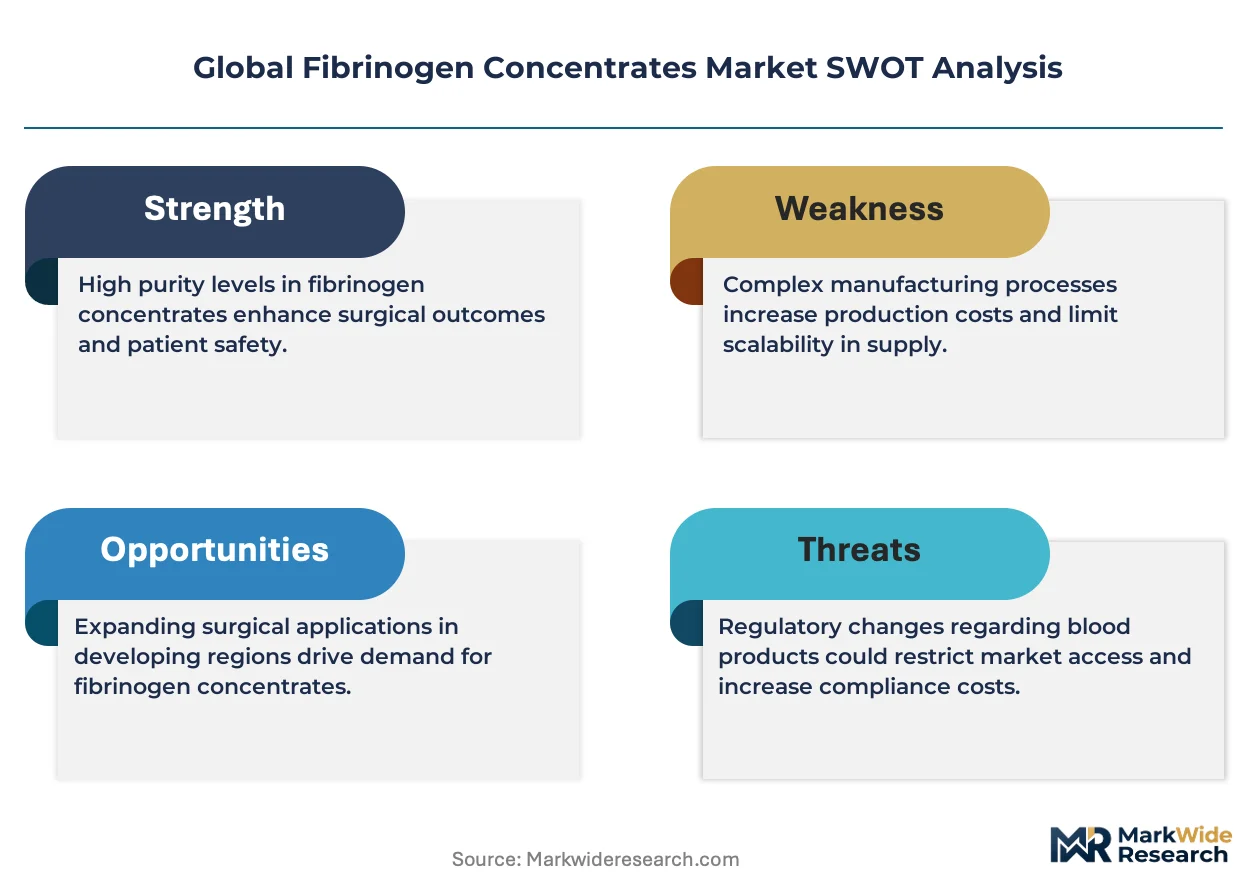
- EU MDR traceability mandates:Strengthened post-market surveillance requirements are accelerating hospital adoption of certified concentrates with documented viral inactivation records.
- Cardiovascular surgery complexity:German and US hospitals are expanding perioperative hemostasis protocols to manage bleeding in aortic procedures and ECMO circuits.
- China NMPA accelerated pathways:Fast-track biologics review is compressing market entry timelines for recombinant coagulation factors.
Market Restraints
- Plasma collection economics:Volatile donor compensation costs and cryoprecipitate yield variability constrain margin stability for fractionators dependent on human-source material.
- FDA Current Good Manufacturing Practice:Stringent viral validation and facility inspection schedules create compliance friction for new market entrants.
- Fresh frozen plasma substitution:Lower-cost allogeneic blood products remain clinically entrenched in trauma settings where rapid availability outweighs concentrate precision.
Strategic Opportunities
- Indian tertiary hospital expansion:Underpenetrated cardiac surgery centers in Mumbai and Delhi present volume growth potential as surgical infrastructure scales.
- Recombinant-plasma hybrid portfolios:Dual-source supply strategies are enabling manufacturers to hedge against donor plasma shortages while maintaining regulatory familiarity.
- Direct-to-hospital distribution:Bypassing wholesale blood bank intermediaries allows concentrate suppliers to capture margin and secure formulary placement.
Industry Challenges
- Fractionation biochemist scarcity:Specialized expertise in chromatographic purification and viral inactivation is concentrating at established plasma processors.
- EMA MDR technical documentation:Extended conformity assessment timelines for plasma-derived biologics are delaying product launches across European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fibrinogen Concentrates Market |
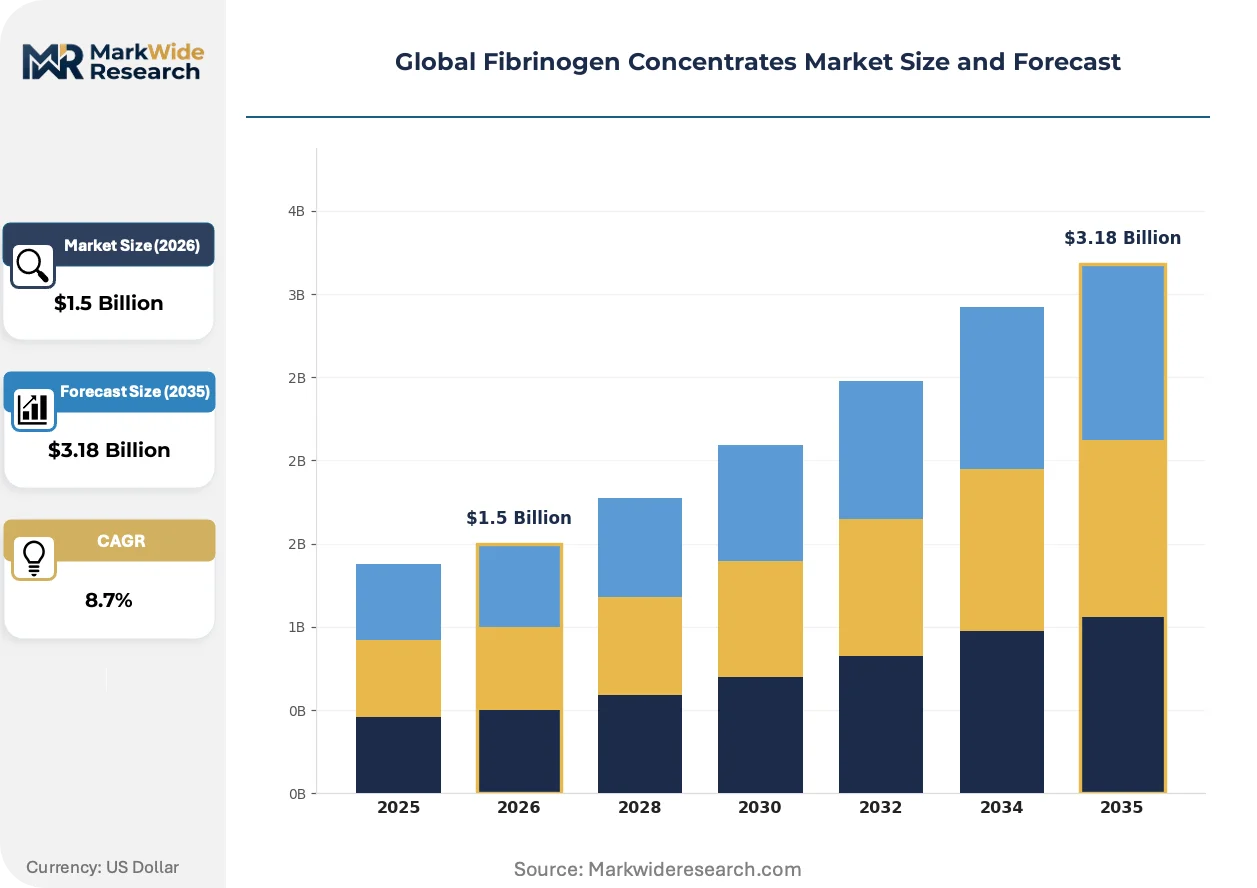
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Fibrinogen, Animal Fibrinogen, Recombinant Fibrinogen, Modified Fibrinogen End User: Hospitals, Surgical Centers, Blood Banks, Research Institutions Application: Surgery, Trauma Care, Hemophilia Treatment, Dental Procedures Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | LFB, Biotest, CSL Behring, Hualan Biological Engineering Co. Ltd., Shanghai RAAS Blood Products Co. Ltd., Octapharma, Kedrion Biopharma, Jiangxi Boya Biological Technology Co. Ltd., Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fibrinogen Concentrates Market Strategic Shifts & Innovations
Recombinant expression systems are disrupting the traditional plasma-dependent production model, while regulatory frameworks and hospital procurement patterns adapt to new supply architectures.
Cell-line-derived fibrinogen is supplanting cryoprecipitate-based manufacturing as the preferred production pathway for next-generation concentrates. Early adopters in US academic medical centers are integrating recombinant products into massive transfusion protocols. This technology is compressing the competitive advantage of legacy plasma fractionators with captive donor networks.
EMA's Medical Device Regulation imposes device-classification obligations on combination products incorporating fibrinogen sealants. Manufacturers must now maintain parallel quality systems for pharmaceutical and device compliance. Surgical sealant developers in Germany and Switzerland are restructuring regulatory submissions to accommodate dual-framework requirements.
Hospital blood management committees are consolidating hemostasis product decisions under centralized pharmacy governance. This shift is displacing surgeon-driven preference purchasing with formulary-based contracting. The concentration of buying authority is most pronounced in US integrated delivery networks and German university hospital clusters.
Global Fibrinogen Concentrates Market Segmentation
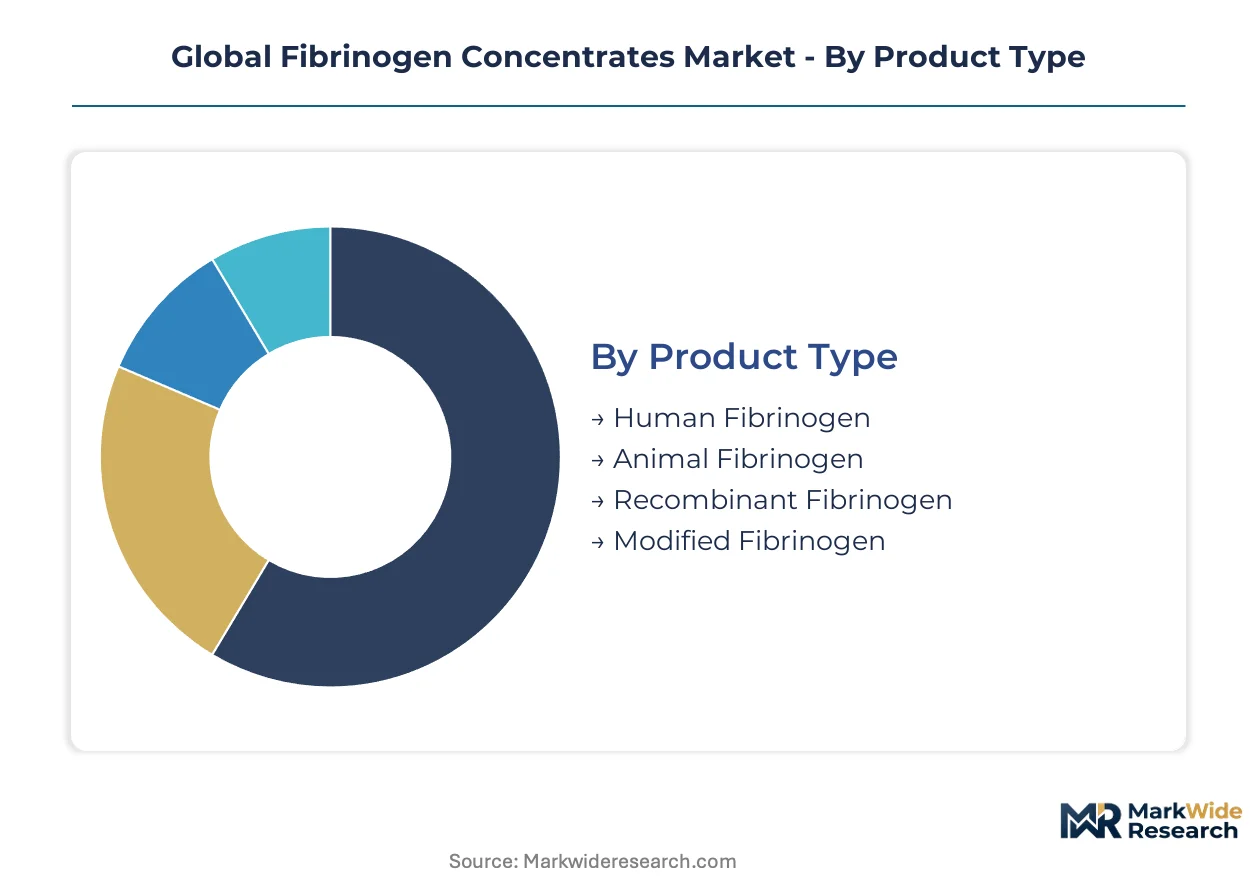
Fibrinogen concentrates fragment across four distinct axes that determine pricing power and procurement pathways. Product source dictates manufacturing economics and regulatory burden. End-user concentration shapes channel strategy and margin capture.
Product Type:
Human-source concentrates command the dominant margin pool due to established reimbursement codes and clinical familiarity, though recombinant alternatives are compressing this advantage through supply security premiums.
- Human Fibrinogen:Purified from cryoprecipitate or chromatographic fractionation of pooled human plasma with standardized clotting activity measured in milligrams per vial. Demand concentrates in German and US hospital surgical suites where perioperative bleeding protocols require documented viral inactivation records under EU MDR traceability mandates.
- Recombinant Fibrinogen:Manufactured through cell-line expression systems in bioreactor facilities, eliminating plasma donor dependency. Chinese NMPA accelerated review pathways are driving fastest adoption in Shanghai and Beijing tertiary centers seeking supply chain resilience.
- Animal Fibrinogen:Bovine or porcine-derived variants used in research settings and select veterinary applications where human-source material faces religious or availability constraints.
- Modified Fibrinogen:Chemically altered variants with extended half-life or enhanced polymerization kinetics, currently concentrated in early-stage clinical trials and specialized hemostasis research.
Human Fibrinogen holds installed capacity. Recombinant Fibrinogen is rotating up the share rankings.
End User:
Procurement authority determines contract structure, with centralized pharmacy governance displacing surgeon-driven purchasing across integrated delivery networks.
- Hospitals:Academic medical centers and community hospitals managing perioperative bleeding, trauma coagulopathy, and massive transfusion protocols. Blood management committees in US integrated delivery networks and German university hospital clusters are consolidating formulary decisions under centralized governance.
- Surgical Centers:Ambulatory facilities performing orthopedic and cardiovascular procedures where rapid hemostasis reduces recovery times and transfer risk.
- Blood Banks:Regional transfusion services maintaining emergency reserves and coordinating plasma-derived product distribution to affiliated hospitals.
- Research Institutions:Academic laboratories and contract research organizations evaluating novel fibrinogen formulations, sealant combinations, and regenerative medicine applications.
Hospitals anchor procurement volume. Surgical Centers are climbing the fastest in absolute spend growth.
Application:
Clinical setting dictates dosing regimen, reimbursement pathway, and competitive substitution risk from alternative hemostasis products.
- Surgery:Complex cardiovascular, hepatic, and orthopedic procedures where acquired hypofibrinogenemia drives concentrate utilization. German hospitals are expanding protocols for aortic procedures and ECMO circuit management.
- Trauma Care:Emergency department and field administration for hemorrhagic shock, though fresh frozen plasma substitution remains entrenched where rapid availability outweighs concentrate precision.
- Hemophilia Treatment:Congenital fibrinogen deficiency management in specialized coagulation centers with established factor replacement programs.
- Dental Procedures:Oral surgery and periodontal applications where localized hemostasis reduces bleeding complications in anticoagulated patients.
Surgery commands the revenue base. Trauma Care is expanding most quickly as massive transfusion protocols evolve.
Distribution Channel:
Channel selection determines margin capture and formulary access, with direct engagement displacing traditional blood bank intermediaries.
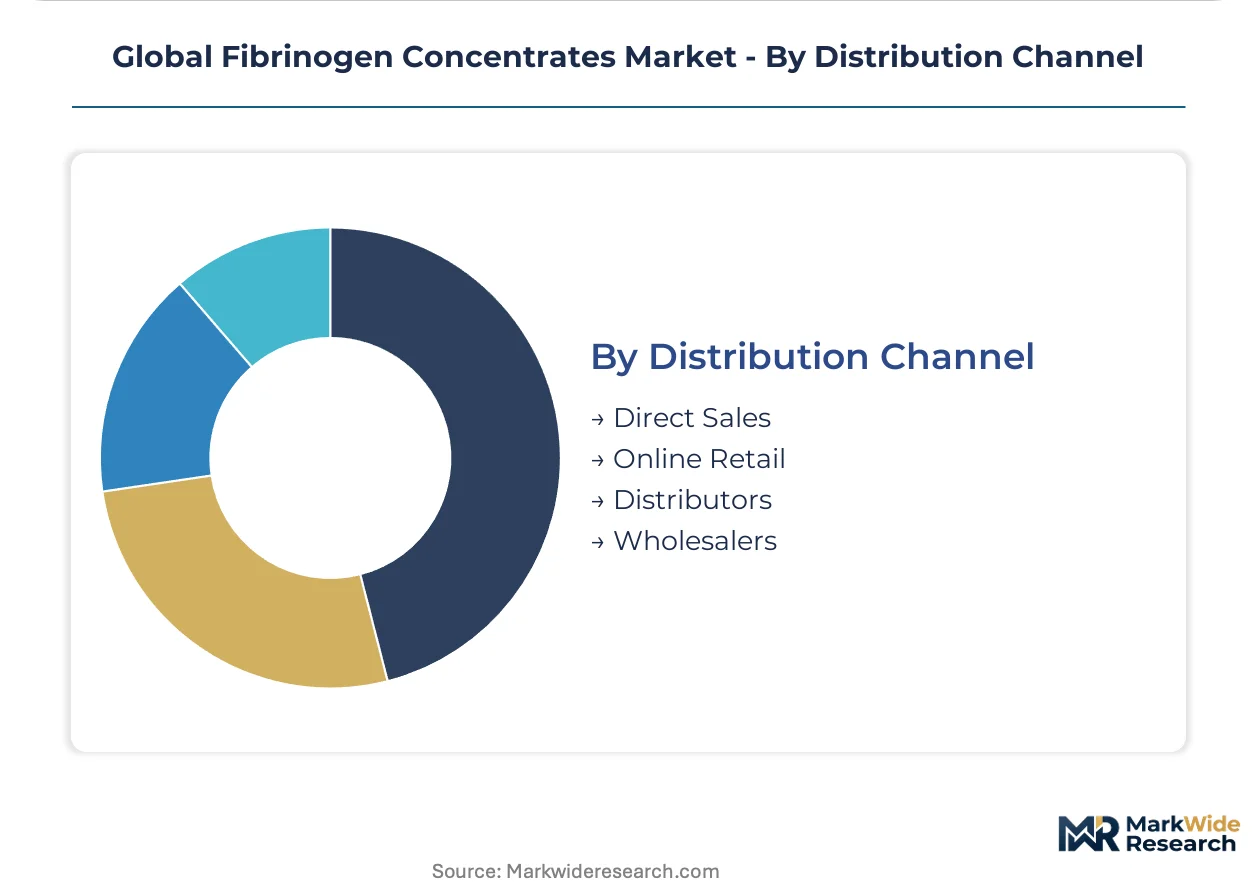
- Direct Sales:Manufacturer-to-hospital contracts securing formulary placement and volume commitments, particularly in US integrated delivery networks and German university hospital clusters.
- Distributors:Regional medical supply intermediaries serving community hospitals and surgical centers without centralized procurement infrastructure.
- Wholesalers:Large-scale blood bank and plasma product wholesalers maintaining cold-chain logistics for fibrinogen concentrates and complementary coagulation factors.
- Online Retail:Emerging channel for research-grade materials and select veterinary applications, constrained by cold-chain requirements and prescription status for human therapeutic use.
Direct Sales holds relationship density. Distributors are gaining share fastest in underpenetrated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation capacity clusters in Germany, the United States, and China, with regulatory stringency and hospital procurement scale determining market access trajectories across jurisdictions.
United States
Academic medical centers in Boston and Houston are embedding fibrinogen concentrates into massive transfusion protocols for trauma and cardiovascular surgery. FDA Current Good Manufacturing Practice requirements enforce viral validation standards that favor established plasma processors with inspection histories. The Southeast hospital cluster around Atlanta and Nashville is consolidating blood management decisions under centralized pharmacy governance.
Germany
University hospital clusters in Munich and Heidelberg are expanding perioperative hemostasis protocols for aortic procedures and ECMO circuit management. EMA MDR traceability mandates are accelerating procurement of certified concentrates with documented viral inactivation records. The Baden-Württemberg surgical corridor is driving concentrate volume through complex cardiac and hepatic procedure specialization.
China
Tertiary centers in Shanghai and Beijing are adopting recombinant fibrinogen to reduce plasma dependency and secure supply chain resilience. NMPA accelerated review pathways for innovative biologics are compressing market entry timelines for cell-line-derived coagulation factors. The Yangtze River Delta hospital network is prioritizing domestic plasma fractionators for procurement security.
India
Cardiac surgery centers in Mumbai and Delhi are scaling fibrinogen concentrate utilization as surgical infrastructure expands. The country's national pharmaceutical regulator maintains stringent import licensing for plasma-derived products that favors multinational suppliers with established distribution. Western India medical corridors are developing cold-chain logistics to support concentrate availability in tertiary settings.
Switzerland
Swissmedic oversees specialized coagulation centers in Zurich and Geneva managing congenital fibrinogen deficiency with established factor replacement programs. Precision manufacturing requirements for plasma-derived biologics align with the country's pharmaceutical quality infrastructure. The Basel biotech corridor is attracting recombinant protein development investment from international manufacturers.
Global Fibrinogen Concentrates Market Key Industry Players
Concentration sits with integrated plasma fractionators possessing captive donor networks and viral inactivation expertise. The market structure tiers across legacy plasma processors, emerging recombinant specialists, and regional blood product suppliers. Three archetypes dominate: vertically integrated fractionators with global collection infrastructure, cell-line technology developers reducing plasma dependency, and domestic plasma processors serving protected procurement markets. Competitive moves center on securing donor plasma supply agreements and licensing recombinant expression platforms.
Among the integrated plasma fractionators, CSL Behring, Octapharma, and Grifols exemplify the archetype of manufacturers controlling collection-to-fractionation value chains. CSL Behring represents Australian-originated vertical integration across North American and European markets. Octapharma occupies a position as a family-owned specialist in plasma protein therapies with European operational roots. Grifols anchors the Spanish-German manufacturing scale archetype through multiple international production sites. These three entities sit within the tier where plasma supply security and regulatory familiarity determine hospital formulary access.
| Leading Market Players |
|---|
| LFB |
| Biotest |
| CSL Behring |
| Hualan Biological Engineering Co. Ltd. |
| Shanghai RAAS Blood Products Co. Ltd. |
| Octapharma |
| Kedrion Biopharma |
| Jiangxi Boya Biological Technology Co. Ltd. |
| Grifols |
| Others |
Cost & Logistics Intelligence
FDA Current Good Manufacturing Practice certification gates both supplier qualification and hospital formulary pricing tiers simultaneously, creating a bifurcated market where viral validation documentation commands premium placement against uncertified alternatives.
Pricing Analysis
FDA Current Good Manufacturing Practice dictates the pricing tier structure across the fibrinogen concentrates landscape. Three-tier pricing separates GMP-certified premium concentrates from standard hospital-grade products and economy-positioned cryoprecipitate alternatives. Price differentiation rests on viral inactivation certification depth and documented EU MDR traceability compliance. Cost compression in the standard tier is intensifying because plasma collection economics are squeezing fractionator margins. Blood banks and community hospitals exhibit highest price sensitivity, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
Container availability constraints on trans-Atlantic lanes are elevating inbound logistics costs for plasma-derived intermediates sourced from European fractionators. Manufacturing gravity centers on the United States, Germany, and China, with each jurisdiction hosting vertically integrated collection-to-fractionation infrastructure. Raw material dependencies encompass source plasma, chromatography resins, and viral inactivation reagents. Single-source vulnerability concentrates in cryoprecipitate feedstock supply from captive donor networks. Distribution runs through direct manufacturer-to-hospital contracts in consolidated procurement markets, with regional wholesalers serving fragmented community hospital segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fibrinogen concentrates sit in early-cycle expansion as recombinant manufacturing platforms penetrate hospital formularies previously locked to plasma-derived supply.
For Market Incumbents: Shield installed base relationships by securing long-term plasma supply agreements with donor network operators before recombinant alternatives achieve cost parity. Invest in chromatographic purification capacity expansion in Germany to satisfy EMA MDR traceability mandates. Defensive consolidation around viral inactivation expertise creates barriers against cell-line technology entrants lacking regulatory familiarity. For New Entrants and Emerging Players: China's NMPA accelerated review pathway offers fastest certification fast-track for recombinant fibrinogen candidates seeking market entry. Target underpenetrated cardiac surgery centers in Mumbai and Delhi where surgical infrastructure scaling outpaces plasma-derived supply availability. Pursue direct-to-hospital distribution partnerships bypassing wholesale blood bank intermediaries to capture margin and secure formulary placement. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents seeking to divest non-core plasma protein portfolios. The 5-10 year viability window favors recombinant technology developers with demonstrated cell-line expression yields above industry benchmarks. Watch recombinant manufacturing cost curves crossing plasma-derived equivalent pricing as the inflection signal for portfolio reallocation toward cell-line platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Expression Platform Licensing | Cell-line technology access reduces plasma dependency for manufacturers in China and Germany. |
| EMA MDR Technical Documentation Investment | Parallel quality systems satisfy dual pharmaceutical-device compliance for sealant combination products. |
| Direct-to-Hospital Distribution Buildout | Bypassing blood bank intermediaries secures formulary placement in US integrated delivery networks. |
| Plasma Collection Network Expansion | Captive donor infrastructure insulates fractionators against raw material scarcity in North America. |
| Hospital Blood Management Committee Engagement | Centralized pharmacy governance displaces surgeon-driven preference purchasing in German university clusters. |
Research Approach
A spread of perspectives from plasma fractionation executives, hospital procurement managers, regulatory affairs specialists, and blood bank operations directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA marketing authorization databases, NMPA biologics registration records, and hospital GPO contract repositories. Bottom-up demand modeling triangulated against top-down plasma collection volume estimates across the analysis window.
Segmentation dimensions modeled encompass product source architecture, end-user procurement concentration, clinical application setting, and regional regulatory cluster. CAGRs were derived from installed capacity trajectories, hospital admission projections for cardiovascular surgery, and recombinant manufacturing yield improvement curves. Forecast inputs incorporated plasma donor compensation inflation assumptions and NMPA review timeline compression for innovative biologics.
Decision-makers should treat outputs as directional under sustained plasma supply scarcity and recombinant cost parity assumptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market