
 Malaysia Oral Anti-Diabetic Drug Market | 2026-2036
Malaysia Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Oral Anti-Diabetic Drug Market Insights
Good Manufacturing Practice certification under NPRA guidelines is reorganizing competitive access for multinational and domestic manufacturers alike. AstraZeneca leverages its SGLT2 inhibitor portfolio to sustain positioning in hospital formularies. Sanofi anchors its presence through established sulfonylurea and insulin-adjacent oral therapies. Duopharma Biotech Berhad competes on localized packaging and distribution reach into government health facilities.
Oral anti-diabetic drugs comprise pharmaceutical formulations administered perorally to reduce blood glucose levels in diabetic patients, with active pharmaceutical ingredients ranging from biguanide derivatives to sodium-glucose cotransporter-2 inhibitors formulated as immediate-release or extended-release tablets. Metformin retains dominant volume share as first-line monotherapy under clinical practice guidelines, while SGLT2 inhibitors represent the fastest-expanding product class driven by cardiovascular outcome benefits. Among end users, hospital procurement channels capture the largest institutional volumes, though homecare dispensing through community pharmacies is gaining structural share as chronic disease management decentralizes.
NPRA operates under Malaysia's Ministry of Health to enforce drug registration, quality control, and post-market surveillance for all imported and locally manufactured oral anti-diabetic products. The Control of Drugs and Cosmetics Regulations 1984, administered by the Drug Control Authority, mandates bioequivalence documentation for generic substitutions entering public tender systems. Stakeholders must monitor evolving pharmacoeconomic assessment criteria at Malaysia's Ministry of Health, where health technology evaluation increasingly determines formulary inclusion and reimbursement tiers for newer therapeutic classes.
Market Dynamics
Hospital formulary centralization under Malaysia's Ministry of Health is concentrating procurement authority for oral anti-diabetic drugs into fewer institutional buyers, reshaping how manufacturers negotiate access across Peninsular Malaysia's specialist endocrinology corridors.
Growth Catalysts
- Klang Valley specialist clustering:Kuala Lumpur and Selangor host Malaysia's densest endocrinology services, generating concentrated prescription volumes for newer therapeutic classes.
- NPRA bioequivalence mandates:The Control of Drugs and Cosmetics Regulations 1984 now requires rigorous documentation for generic substitutions entering public tender systems, elevating quality-verified suppliers.
- SGLT2 inhibitor cardiovascular outcomes:Hospital formularies are expanding coverage for this drug class based on demonstrated heart failure risk reduction in diabetic populations.
Market Restraints
- API import dependency:Malaysia lacks domestic active pharmaceutical ingredient manufacturing, exposing formulators to currency volatility and supply chain disruptions from Indian and Chinese sources.
- Public tender price compression:Government procurement through the Ministry of Health's centralized purchasing imposes aggressive cost benchmarks that constrain margin recovery for patented formulations.
- Specialist physician scarcity:Endocrinologist density remains insufficient outside the Klang Valley, limiting guideline-concordant prescribing in northern and eastern Peninsular states.
Strategic Opportunities
- East Malaysia expansion:Sabah and Sarawak remain underpenetrated relative to Peninsular Malaysia, with government health facilities representing untapped institutional volume.
- Community pharmacy chronic disease management:Homecare dispensing channels are gaining structural share as Malaysia decentralizes diabetes care from hospital-centric models.
- Pharmacoeconomic assessment integration:Malaysia's Ministry of Health is formalizing health technology evaluation criteria, creating pathways for premium-priced therapies with demonstrated cost-effectiveness.
Industry Challenges
- Good Manufacturing Practice certification timelines:NPRA facility inspections and documentation reviews create extended approval windows for new manufacturing entrants.
- Post-market surveillance compliance:Adverse event reporting obligations under the Drug Control Authority require dedicated pharmacovigilance infrastructure that smaller domestic formulators struggle to maintain.
- Generic substitution resistance:Established clinician prescribing habits favor originator brands despite bioequivalence verification, complicating market access for qualified alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Oral Anti-Diabetic Drug Market |
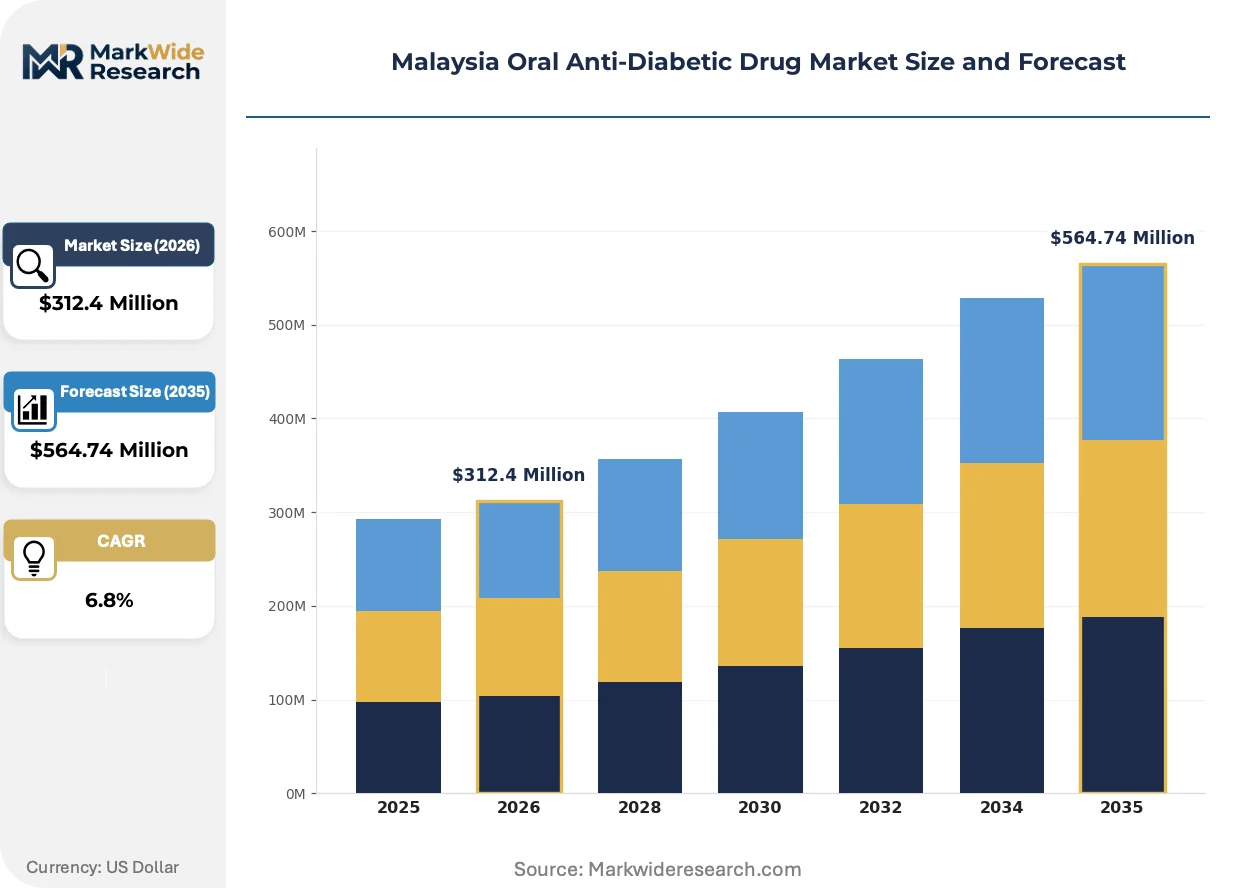
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Retail, Online, Wholesalers, Institutional Therapy Area: Type 2 Diabetes, Gestational Diabetes, Prediabetes, Others |
| Companies Covered | AstraZeneca, Sanofi, Eli Lilly, Johnson & Johnson, Astellas, Pharmaniaga Berhad, Duopharma Biotech Berhad, Novartis, Boehringer Ingelheim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Oral Anti-Diabetic Drug Market Trends and Innovations
Extended-release formulation technologies and cardiovascular outcome data integration are redefining competitive positioning among oral anti-diabetic drug classes in Malaysia's hospital procurement channels.
Fixed-dose combination tablets pairing metformin with SGLT2 inhibitors are decomposing traditional monotherapy prescribing patterns. Hospital endocrinology departments in Selangor are adopting these formulations at accelerating rates. This convergence is compressing standalone sulfonylurea volumes while expanding reimbursement complexity for combination therapies.
NPRA's tightening interpretation of bioequivalence standards under the Control of Drugs and Cosmetics Regulations is elevating documentation requirements for generic entrants. Domestic manufacturers must now submit additional pharmacokinetic studies to qualify for public tender participation. Malaysian generic formulators are responding by deepening analytical capabilities and pre-submission consultation investments.
Homecare dispensing through community pharmacy networks is displacing hospital outpatient pharmacy dominance for stable Type 2 diabetes patients. Government health facilities in Johor and Penang are piloting referral pathways that channel maintenance prescriptions to accredited retail pharmacies. This channel rotation is most visible in urban corridors where pharmacy density supports chronic disease monitoring protocols.
Malaysia Oral Anti-Diabetic Drug Market Segmentation
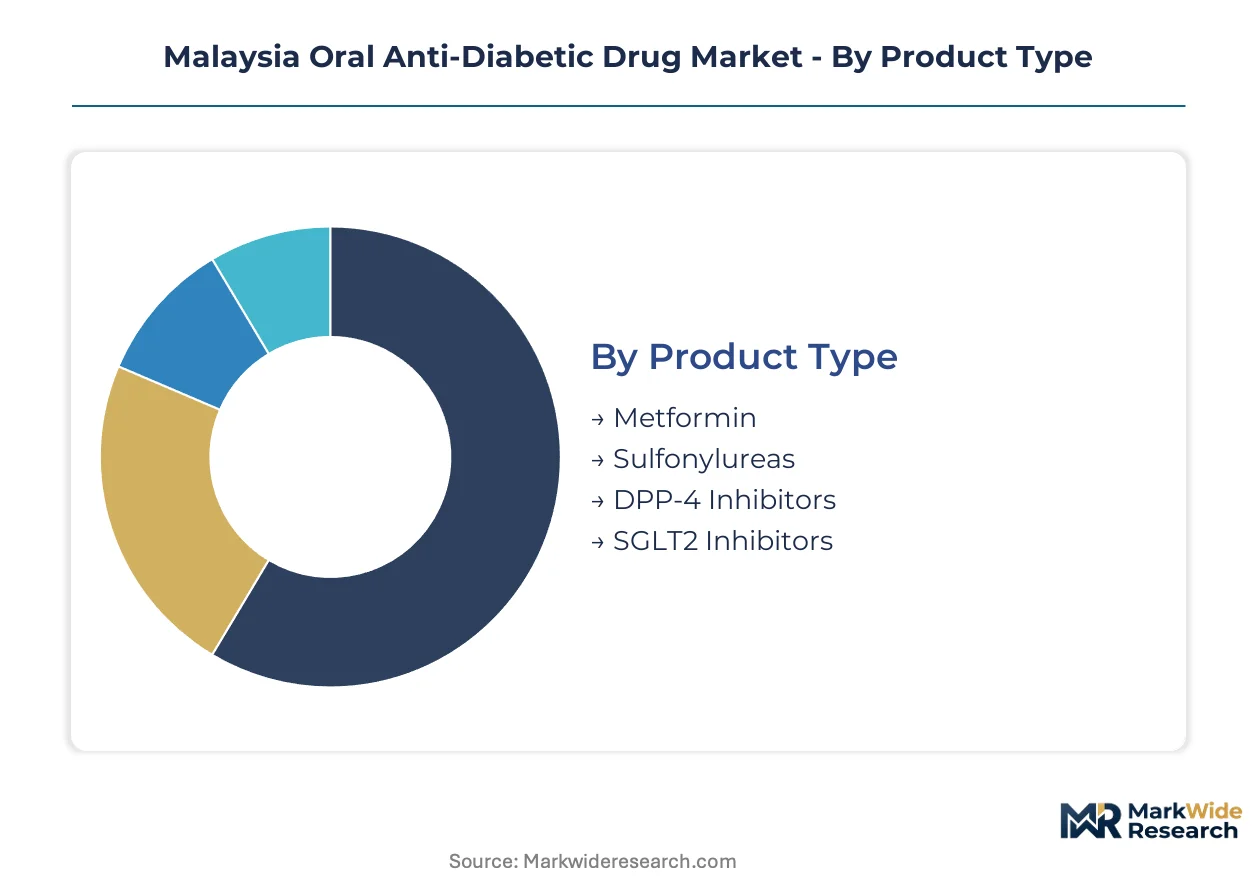
Malaysia's oral anti-diabetic drug market fragments across therapeutic classes, procurement channels, and care settings. NPRA registration requirements and Ministry of Health tender systems create divergent compliance burdens across these divisions, reshaping manufacturer prioritization.
Product Type:
NPRA bioequivalence documentation thresholds vary sharply by molecular complexity, with newer mechanisms facing extended pharmacokinetic study requirements.
- Metformin:Biguanide derivative formulated as immediate-release or extended-release tablets. Demand concentrates in government health facilities across the Klang Valley corridor, where first-line monotherapy protocols dominate prescribing. Established volume favors Metformin; emerging adoption favors SGLT2 inhibitors.
- Sulfonylureas:Insulin secretagogue class including glipizide and glimepiride formulations. Prescription volumes cluster in older patient cohorts managed through Selangor hospital outpatients, constrained by hypoglycemia risk profiles.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors with weight-neutral glucose lowering. Penetration tracks specialist endocrinologist availability in Kuala Lumpur tertiary centers.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 inhibitors demonstrating cardiovascular outcome benefits. Hospital formularies in Penang and Johor are expanding coverage based on heart failure risk reduction data.
Cost tier stratification separates mature generics from outcome-validated premium formulations.
End User:
Procurement authority concentration under Ministry of Health central purchasing creates asymmetric negotiating leverage across institutional buyers.
- Hospitals:Tertiary and secondary care facilities with specialist endocrinology departments. Volume concentrates in Klang Valley specialist corridors where centralized tender systems aggregate demand. Established volume favors Hospitals; emerging adoption favors Homecare.
- Clinics:Primary care and polyclinic networks managing stable Type 2 diabetes patients. Government health clinics in northern Peninsular states face specialist physician scarcity limiting guideline-concordant prescribing.
- Pharmacies:Community retail and hospital outpatient dispensaries. Pilot referral pathways in Johor and Penang are channeling maintenance prescriptions to accredited retail pharmacies.
- Homecare:Patient-managed chronic disease settings with caregiver support. Decentralization initiatives are gaining structural share as diabetes care shifts from hospital-centric models.
Geographic penetration depth correlates with endocrinology service density and pharmacy accreditation coverage.
Distribution Channel:
Channel margin structures reflect inventory carrying costs and cold-chain requirements for specific formulations.
- Retail:Community pharmacy networks with direct patient dispensing. Duopharma Biotech Berhad leverages localized packaging reach into this channel.
- Online:E-pharmacy platforms and telemedicine-integrated delivery. Regulatory clarity under NPRA post-market surveillance remains evolving for digital dispensing.
- Wholesalers:Regional distributors serving government health facilities. Tender participation requires Good Manufacturing Practice certification and bioequivalence documentation.
- Institutional:Direct hospital procurement and Ministry of Health central purchasing. AstraZeneca sustains positioning through cardiovascular outcome data integration.
Supply chain configuration determines which manufacturers capture public tender volumes versus private market premiums.
Therapy Area:
Patient population heterogeneity drives distinct clinical endpoint requirements and reimbursement tier placement.
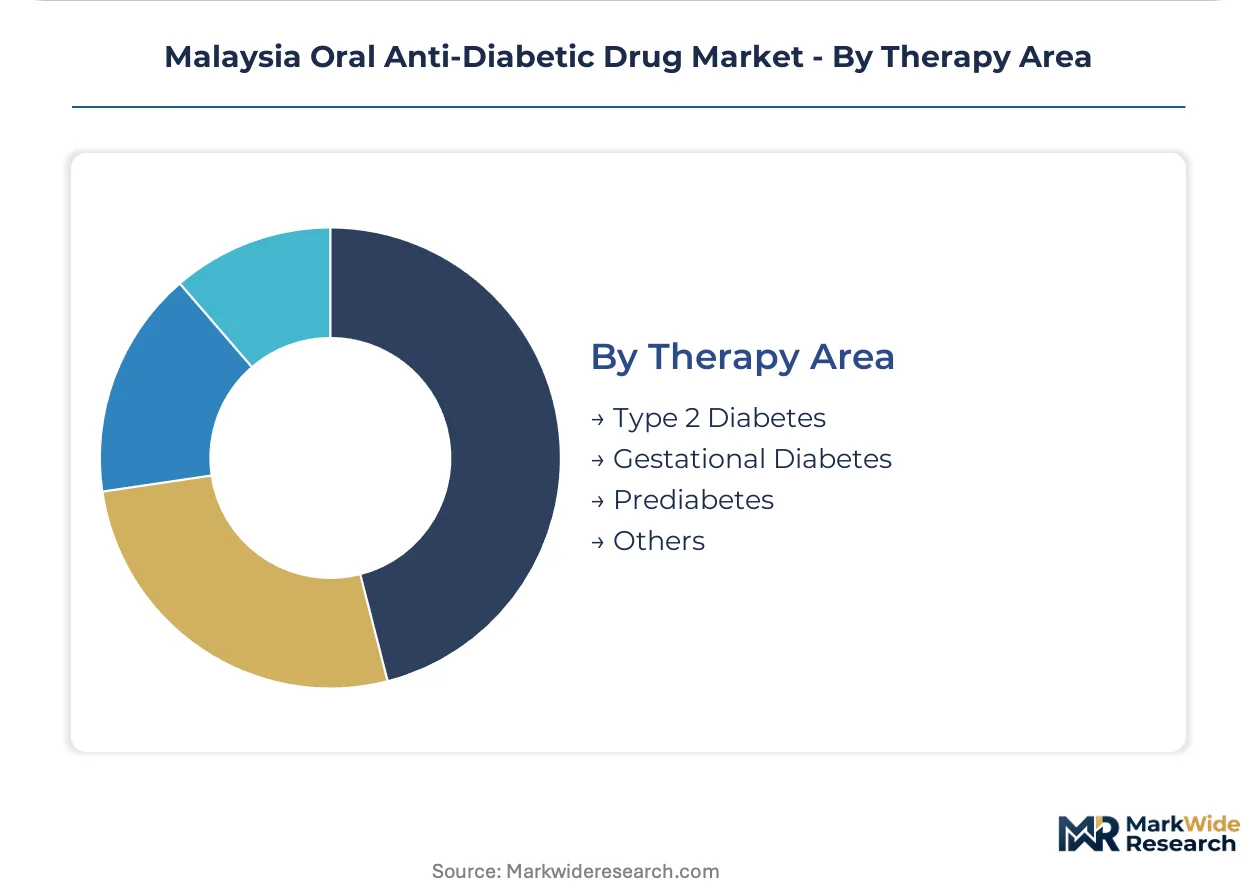
- Type 2 Diabetes:Insulin resistance and progressive beta-cell dysfunction requiring oral pharmacotherapy. This segment captures the dominant prescription volume across all Malaysian procurement channels.
- Gestational Diabetes:Glucose intolerance during pregnancy with strict glycemic targets. Specialist obstetric endocrinology services in Kuala Lumpur tertiary hospitals manage concentrated demand.
- Prediabetes:Impaired glucose tolerance with lifestyle intervention emphasis. Pharmacologic intervention thresholds vary across Ministry of Health clinic protocols.
- Others:Secondary diabetes forms and comorbidity-driven prescribing. Niche volumes track rare endocrine disorder prevalence in specialist referral networks.
Volume concentration in Type 2 Diabetes subsidizes development investments for narrower indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NPRA's bioequivalence mandates under the Control of Drugs and Cosmetics Regulations are redistributing procurement authority across Malaysia's federal states. State-level health ministries now enforce divergent documentation timelines for generic tender participation.
Selangor
Klang Valley specialist corridors concentrate endocrinology prescription volumes for newer therapeutic classes. Hospital formularies in Shah Alam and Petaling Jaya prioritize SGLT2 inhibitors with cardiovascular outcome documentation. Centralized tender systems aggregate demand from tertiary facilities across the Greater Kuala Lumpur metropolitan cluster.
Johor
Government health facilities pilot referral pathways channeling maintenance prescriptions to accredited retail pharmacies. Community pharmacy density in Johor Bahru supports chronic disease monitoring protocols for stable Type 2 diabetes patients. State health authorities coordinate with NPRA on post-market surveillance compliance for decentralized dispensing.
Penang
Hospital formularies in George Town expand coverage for SGLT2 inhibitors based on heart failure risk reduction data. Northern Peninsular specialist availability remains constrained relative to central corridors, limiting guideline-concordant prescribing. State procurement participates in Ministry of Health central purchasing with extended bioequivalence study requirements.
Sabah
East Malaysian government health facilities represent underpenetrated institutional volume relative to Peninsular benchmarks. Kota Kinabalu hospital networks rely on consolidated shipments from West Malaysian distribution hubs. NPRA registration timelines extend for manufacturers lacking established East Malaysia cold-chain partnerships.
Sarawak
Kuching specialist endocrinology services manage concentrated demand across vast rural catchment areas. State health infrastructure depends on air-freighted pharmaceutical supplies from Peninsular manufacturing centers. Domestic formulators compete on localized packaging reach into dispersed government clinic networks.
Malaysia Oral Anti-Diabetic Drug Market Competitive Landscape
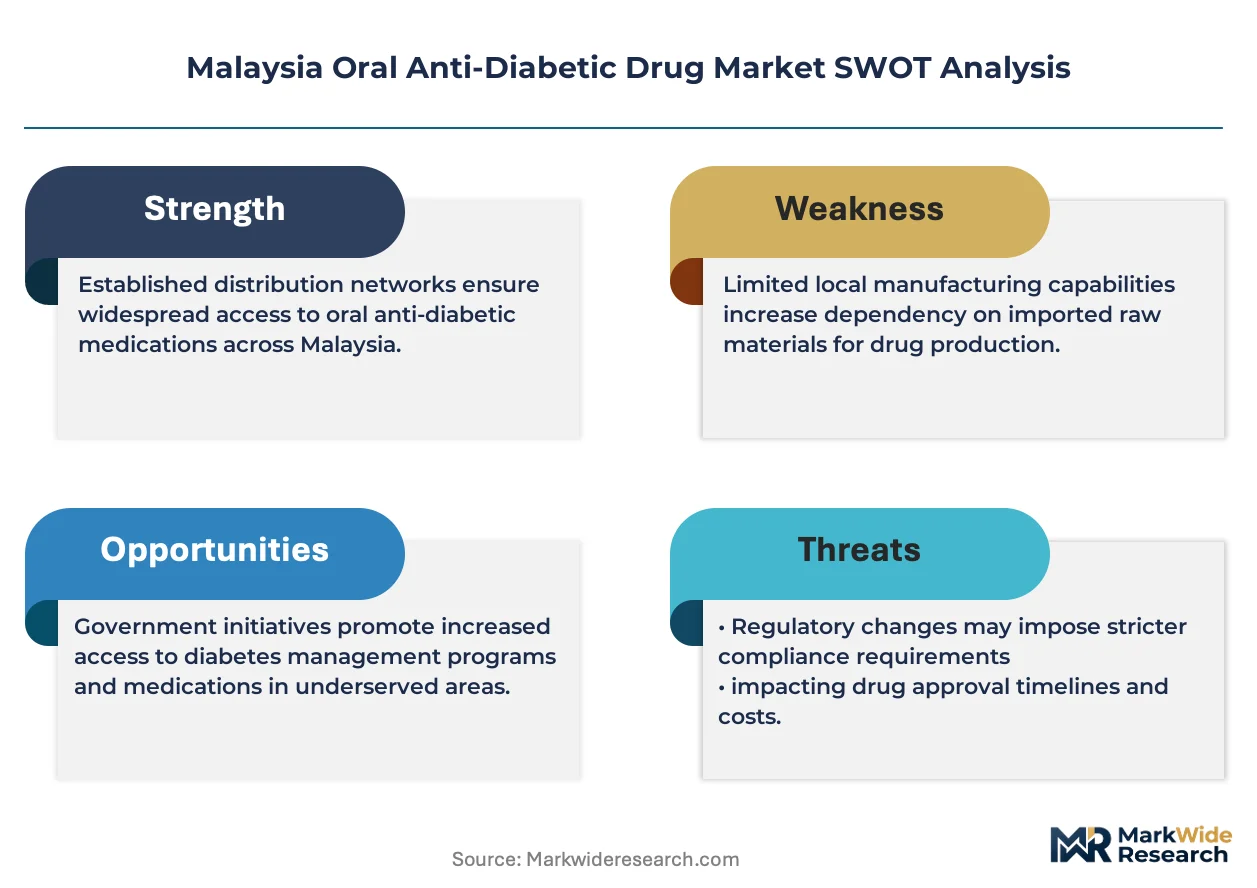
Listed leaders compete with private specialists across hospital formulary access and tender participation channels. The market exhibits tiered concentration with multinational originators dominating cardiovascular-validated therapeutic classes while domestic formulators capture generic volume in government procurement. Three archetypes define competitive positioning: originator multinationals with outcome data assets, regional generics with bioequivalence certification, and integrated domestic players with distribution depth into public facilities. Competitive moves center on pharmacoeconomic dossier preparation for Ministry of Health evaluation and backward integration into analytical testing capabilities.
Within the originator multinational tier, AstraZeneca and Sanofi exemplify positioning through cardiovascular outcome integration. Duopharma Biotech Berhad represents the domestic integrated archetype with government facility reach. These anchors illustrate how competitive advantage separates data-driven formulary inclusion from volume-driven tender capture across Malaysia's divergent procurement channels.
| Leading Market Players |
|---|
| AstraZeneca |
| Sanofi |
| Eli Lilly |
| Johnson & Johnson |
| Astellas |
| Pharmaniaga Berhad |
| Duopharma Biotech Berhad |
| Novartis |
| Boehringer Ingelheim |
| Others |
Pricing and Supply Chain Analysis
Generic metformin substitution for originator sulfonylureas in Malaysia's public tender systems is redistributing procurement volume toward Indian and Chinese API sources while compressing margin structures for domestic formulators lacking backward integration into active pharmaceutical ingredient manufacturing.
Pricing Analysis
Certification level under NPRA Good Manufacturing Practice standards creates the primary spread between premium originator formulations and economy generic entrants. Three-tier pricing structure across premium, standard, and economy levels reflects bioequivalence documentation depth and cardiovascular outcome data availability. Cost compression in the economy tier is intensifying because Ministry of Health central purchasing imposes aggressive tender benchmarks. Government health facilities exhibit highest price sensitivity, while private hospital formularies prioritize clinical outcome data over unit cost.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose Malaysian formulators to logistics disruptions when consolidating API shipments from Indian and Chinese manufacturing centers. Active pharmaceutical ingredient supply concentrates in Hyderabad and Zhejiang province, with excipient sourcing anchored in European specialty chemical producers. Single-source vulnerability from concentrated Indian generic API production presents structural risk to domestic tablet manufacturers. Distribution runs through Duopharma Biotech Berhad's government facility network and regional wholesalers serving hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's oral anti-diabetic drug market sits in a cyclical recovery phase driven by Ministry of Health formulary modernization and expanding SGLT2 inhibitor reimbursement eligibility.
For Market Incumbents: Consolidate formulary positioning through cardiovascular outcome data integration and NPRA pharmacoeconomic dossier investment. Originators must deepen bioequivalence analytical capabilities to defend against qualified generic substitution. Channel control through hospital specialist relationships remains the critical lever against tender price erosion.
For New Entrants and Emerging Players: Differentiate on East Malaysia distribution reach where cold-chain partnerships and localized packaging create defensive moats. Sabah and Sarawak government health facilities represent the most penetrable geography given underdeveloped institutional supply lines. Community pharmacy chronic disease management pilot programs offer a viable go-to-market angle bypassing centralized hospital procurement.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors domestic formulators with NPRA certification and government tender track records. Long-term viability hinges on backward integration into analytical testing and pharmacovigilance infrastructure. Watch SGLT2 inhibitor volume share crossing threshold levels in Selangor hospital formularies as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| NPRA Bioequivalence Certification Investment | Domestic formulators gain tender participation eligibility under Control of Drugs and Cosmetics Regulations. |
| East Malaysia Distribution Partnership | Cold-chain logistics alliances unlock Sabah and Sarawak government health facility procurement channels. |
| Cardiovascular Outcome Data Integration | Hospital formularies in Penang and Johor expand SGLT2 inhibitor coverage based on heart failure risk reduction. |
| Community Pharmacy Accreditation Program | Retail channel expansion captures decentralizing diabetes care from hospital-centric dispensing models. |
| Pharmacoeconomic Dossier Preparation | Ministry of Health health technology evaluation creates pathways for premium therapy reimbursement tiers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, NPRA regulatory affairs specialists, pharmaceutical procurement managers at Ministry of Health facilities, and community pharmacy network operators. Secondary validation drew from NPRA registration databases, Ministry of Health tender documentation, ClinicalTrials.gov cardiovascular outcome trials, and Malaysian pharmaceutical trade customs records. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources.
Across the analysis window, forecasts reflect therapeutic class adoption curves, formulary inclusion timelines, and channel shift dynamics segmented by product type, end user procurement authority, and geographic penetration depth. CAGRs were derived from trend extrapolation of hospital dispensing data and tender award patterns. Modeled inputs include specialist endocrinologist density by state, generic substitution rates under bioequivalence mandates, and decentralized care pilot program expansion trajectories.
Forecasts assume regulatory continuity in NPRA bioequivalence enforcement and Ministry of Health central purchasing frameworks; material policy shifts would require re-modeling. Specific risks include API import disruption from Indian manufacturing consolidation, currency volatility affecting formulation costs, and adverse cardiovascular outcome data altering SGLT2 inhibitor reimbursement status. Revision becomes warranted when generic tender participation thresholds or specialist physician supply constraints cross critical intervention levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Aripiprazole Market