
 Dyslipidemia Therapeutics Market | 2026-2036
Dyslipidemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Dyslipidemia Therapeutics Market Foresight
Aftermarket patient support and adherence monitoring revenue is fragmenting across digital platforms, telehealth providers, and pharmacy networks as manufacturers seek stickier relationships beyond the prescription fill. Pfizer leverages its primary care infrastructure to sustain broad statin distribution. Amgen anchors the injectable segment with biologic manufacturing scale that competitors struggle to replicate.
Dyslipidemia therapeutics comprise pharmacological agents that modulate lipid metabolism through hepatic enzyme inhibition, intestinal cholesterol absorption blockade, or monoclonal antibody-mediated clearance of circulating PCSK9 protein, with primary commercial purpose of reducing atherosclerotic cardiovascular event rates in high-risk patients. The statin category retains dominant volume share despite maturation, while PCSK9 inhibitors represent the fastest-expanding margin pool due to premium pricing and residual cardiovascular risk positioning. Oral delivery maintains majority share in routine primary care, though injectable formats capture disproportionate value in specialty clinic and hospital settings where compliance monitoring justifies higher intervention costs.
FDA cardiovascular outcome trial mandates and EMA benefit-risk reassessment frameworks elevate the bar for new molecular entities seeking approval in saturated statin-adjacent categories. The EU MDR and national health technology assessment bodies in Germany and Japan increasingly condition reimbursement on demonstrated hard endpoint superiority rather than surrogate lipid marker improvement. Stakeholders must monitor evolving payer evidence requirements and decide whether to allocate R&D capital toward next-generation RNA interference platforms or differentiated formulation strategies in established drug classes.
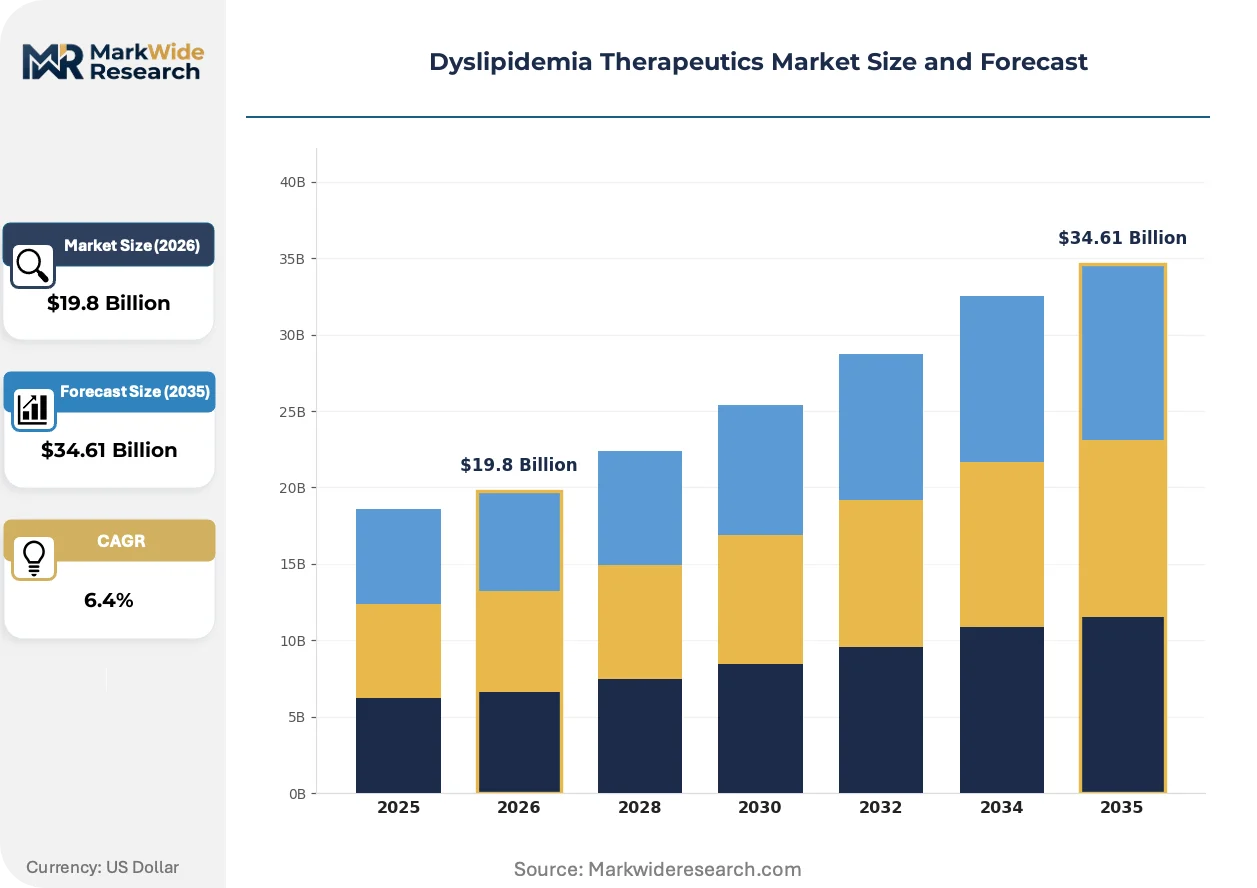
Market Dynamics
FDA cardiovascular outcome trial mandates and EMA benefit-risk reassessment frameworks are compressing development timelines for new molecular entities while elevating evidence requirements beyond surrogate lipid markers. Manufacturers now face binary decisions between RNA interference platform investment and differentiated formulation strategies in mature drug classes.
Growth Catalysts
- EMA MDR pathway acceleration:Streamlined conformity assessment for Class III cardiovascular devices is shortening time-to-market for combination drug-delivery systems in Germany and the Netherlands.
- Hospital-based cardiovascular programs:Expansion of structured lipid management clinics in the United States is driving injectable therapy uptake among high-risk patient cohorts.
- RNA interference platform maturation:Inclisiran's annual dosing schedule is virtualizing patient adherence monitoring requirements and reducing pharmacy network touchpoint costs.
Market Restraints
- Biologic manufacturing concentration:Injectable PCSK9 production capacity clusters among three contract manufacturers, creating single-source vulnerability for fill-finish operations.
- Reimbursement friction from HTA bodies:Germany's IQWiG and Japan's Chuikyo increasingly condition coverage on hard endpoint superiority rather than LDL-C reduction magnitude.
- Statin generic substitution:Atorvastatin and rosuvastatin commoditization is compressing physician willingness to escalate therapy despite residual cardiovascular risk.
Strategic Opportunities
- Underpenetrated Japanese specialist clinics:Lipid management remains concentrated in general practice; dedicated dyslipidemia centers in Osaka and Tokyo represent greenfield expansion targets.
- Digital therapeutic adjacencies:Telehealth-enabled adherence monitoring is creating new revenue pools beyond prescription dispensing for pharmacy networks.
- EU Green Deal manufacturing incentives:Sustainable process chemistry investments for statin active pharmaceutical ingredients qualify for preferential EIB financing in Portugal and Spain.
Industry Challenges
- Cardiovascular outcome trial execution:Event-driven study designs require 3-5 year horizons and 15,000+ patient enrollment, straining R&D capital allocation discipline.
- Legacy EHR integration:Hospital systems in the United States demand FHIR-compliant lipid panel data exchange that biologic manufacturers struggle to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyslipidemia Therapeutics Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, Fibrates, PCSK9 Inhibitors, Bile Acid Sequestrants Therapy Area: Cardiovascular Disorders, Diabetes, Metabolic Syndrome, Atherosclerosis Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | Pfizer, Sanofi, Amgen, Merck & Co., Novartis, AstraZeneca, Abbott Laboratories, Regeneron Pharmaceuticals, Arrowhead Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyslipidemia Therapeutics Market Shifts & Advancements
RNA interference platforms and digital adherence infrastructure are converging to redefine how lipid-lowering therapies demonstrate value beyond biomarker suppression. Regulatory evidence requirements now favor interventions that compress cardiovascular event rates in hard-to-treat populations.
Small interfering RNA therapeutics targeting PCSK9 synthesis in hepatocytes is virtualizing the traditional monoclonal antibody competitive set by enabling twice-yearly administration. Specialist clinics in Germany and the United States are adopting inclisiran-based protocols for patients with documented statin intolerance. This dosing compression is reducing pharmacy benefit manager administrative burden while shifting reimbursement risk toward outcomes-based contracts.
EMA's 2023 MDR guidance on cardiovascular device-drug combinations is mandating additional clinical data for automated injection systems used in PCSK9 inhibitor delivery. Manufacturers of connected auto-injectors must now submit usability validation studies alongside pharmaceutical filings. The Netherlands and Belgium have emerged as early adopters of this integrated review pathway, compressing total approval timelines for combination products.
Patient support program unbundling is fragmenting adherence monitoring across telehealth platforms, pharmacy networks, and manufacturer-operated digital tools. Hospital systems in Japan are consolidating vendor relationships to reduce platform fragmentation, while United States payers are mandating interoperable data standards. This procurement consolidation is favoring manufacturers with established primary care infrastructure over specialty biologic pure-plays.
Dyslipidemia Therapeutics Market Segmentation
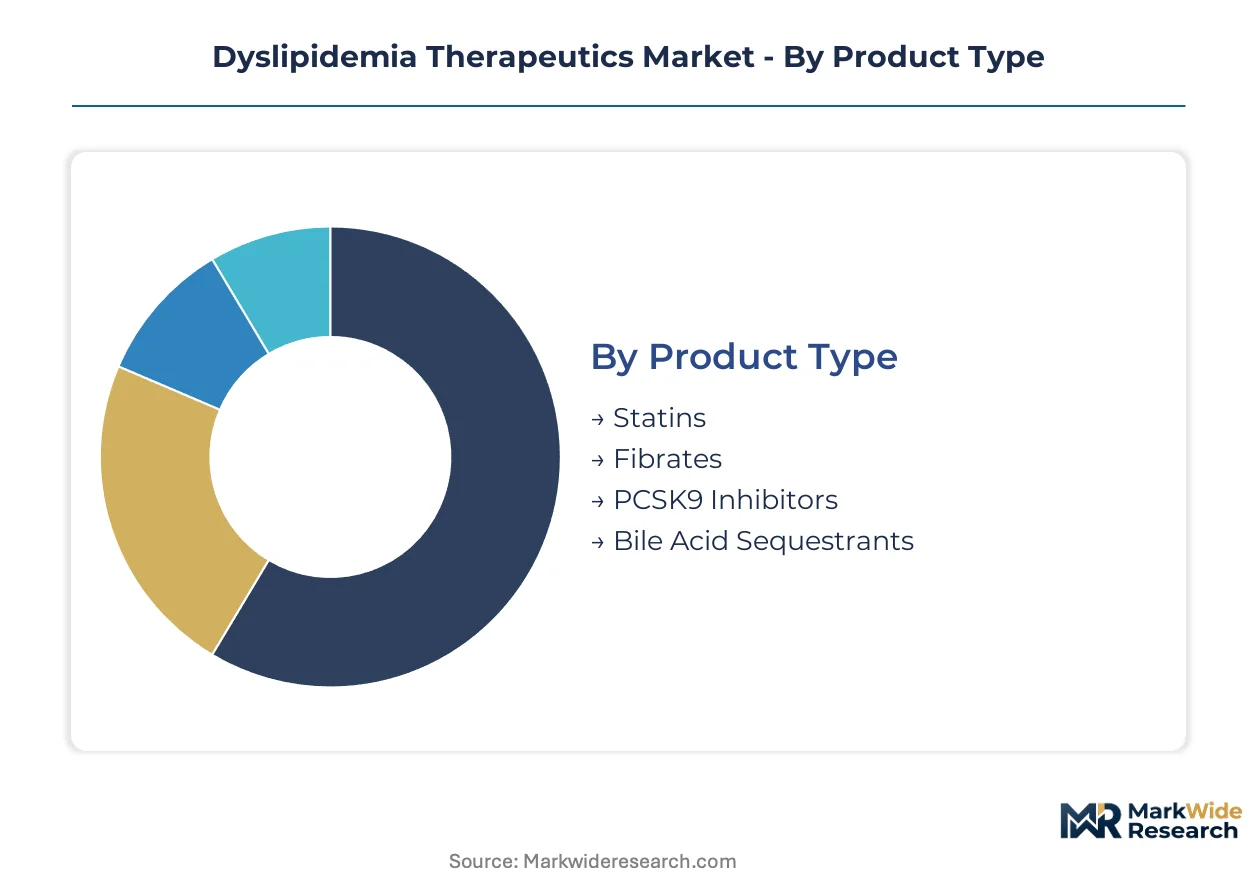
Dyslipidemia therapeutics fragment across molecular mechanisms, clinical settings, and administration formats that each carry distinct reimbursement profiles and competitive dynamics. Understanding these segment boundaries clarifies where manufacturers allocate R&D capital versus where commoditization pressures dominate.
Product Type:
Mature small-molecule categories coexist with emerging biologic platforms that command premium positioning through differentiated efficacy profiles.
- Statins:HMG-CoA reductase inhibitors remain the volume foundation across primary care networks in the United States and Germany. Physician familiarity and extensive generic availability sustain first-line prescribing despite plateauing LDL-C reduction ceilings.
- PCSK9 Inhibitors:Monoclonal antibodies and RNA interference agents target circulating PCSK9 protein to amplify LDL receptor recycling. Injectable formats in United States hospital lipid clinics capture the steepest expansion trajectory as residual cardiovascular risk positioning justifies prior authorization investment.
- Fibrates:PPAR-alpha agonists address hypertriglyceridemia through hepatic lipid metabolism modulation.
- Bile Acid Sequestrants:Intestinal resin binders interrupt enterohepatic cholesterol circulation for statin-intolerant patients.
Statins handle the majority of throughput; PCSK9 inhibitors are climbing the fastest on share.
Therapy Area:
Application concentration tracks cardiovascular comorbidity burden and the presence of outcome trial evidence supporting specific indications.
- Cardiovascular Disorders:Secondary prevention in post-acute coronary syndrome patients drives the largest reimbursement pools. United States Medicare and German SHI systems prioritize lipid lowering in documented atherosclerotic disease over primary prevention populations.
- Atherosclerosis:Imaging-confirmed plaque burden is emerging as a separate reimbursement trigger in Japanese specialist clinics and select United States accountable care organizations. Intravascular ultrasound and CT angiography adoption is creating addressable patient segments beyond traditional risk scores.
- Diabetes:Dyslipidemia management integrates with glycemic control protocols in endocrinology practices.
- Metabolic Syndrome:Clustered risk factor addressing spans primary care and cardiology handoffs.
Cardiovascular disorders anchor volume commitment; atherosclerosis is gaining share fastest as imaging biomarkers penetrate clinical workflows.
Delivery Mode:
Format selection determines site-of-care economics and the viability of patient self-administration versus supervised compliance monitoring.
- Oral:Tablet and capsule formulations dominate statin and fibrate prescribing through retail pharmacy channels in Germany and Japan. Once-daily dosing supports adherence in ambulatory populations without requiring injection training infrastructure.
- Injectable:Prefilled syringes and auto-injectors for PCSK9-targeting biologics concentrate in United States hospital outpatient departments and German lipid specialist centers. Reimbursement coding for physician-administered drugs creates margin structures that oral generics cannot replicate.
- Intravenous:Hospital infusion suites handle acute lipid management in severe hypertriglyceridemia with pancreatitis risk.
- Transdermal:Patch delivery remains experimental for lipid-modifying agents with limited commercial penetration.
Oral formats process the majority of prescription volume; injectable delivery is expanding most quickly on value contribution.
End User:
Care setting fragmentation reflects the split between routine chronic management and high-intensity intervention for residual risk populations.
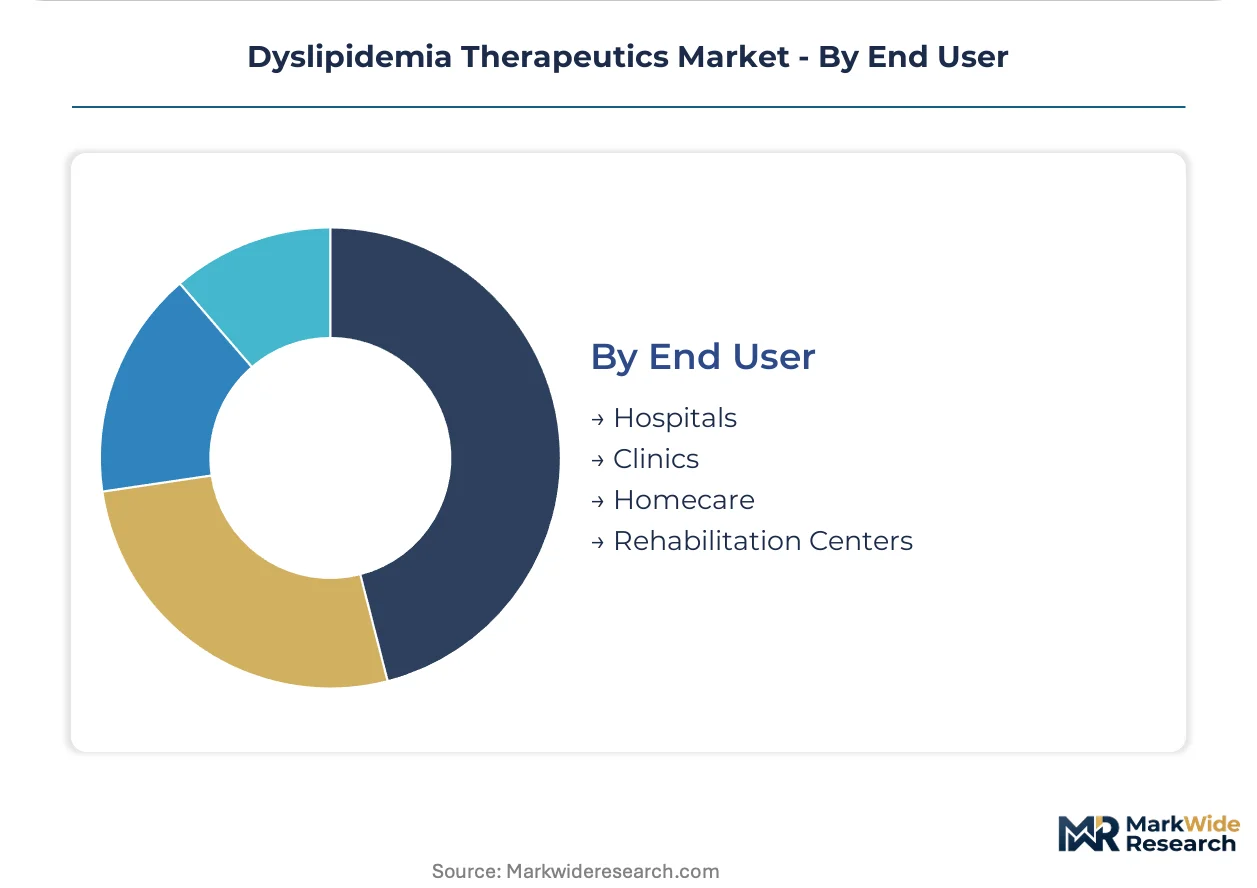
- Hospitals:Cardiovascular service lines in the United States and university medical centers in Germany anchor PCSK9 inhibitor initiation through structured lipid clinics. EHR-integrated risk stratification tools identify candidates for escalation beyond statin therapy.
- Homecare:Self-administered injectable therapies and mail-order pharmacy fulfillment are penetrating Japanese urban corridors and United States Medicare Advantage networks. Remote patient monitoring platforms track adherence for value-based contract reporting.
- Clinics:Primary care and cardiology private practices handle statin titration and maintenance.
- Rehabilitation Centers:Post-event cardiac recovery programs incorporate intensive lipid management protocols.
Hospitals concentrate the highest-value prescribing; homecare is advancing fastest on patient volume as self-injection competence spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany demonstrate the least price elasticity for PCSK9 inhibitors, while United States commercial payers impose the strictest prior authorization requirements. India's out-of-pocket market remains acutely sensitive to statin generic pricing. China's volume expansion hinges on national reimbursement list inclusion timing.
United States
Medicare Advantage plans and hospital outpatient departments drive injectable PCSK9 uptake through structured lipid clinic protocols. FDA cardiovascular outcome trial mandates elevate evidence requirements for new molecular entities beyond LDL-C surrogate markers. The Cleveland Clinic and Mayo Clinic cardiovascular service lines anchor high-intensity prescribing for residual risk populations.
Germany
IQWiG benefit assessments increasingly condition SHI reimbursement on hard endpoint superiority rather than biomarker improvement. EMA MDR streamlined pathways for Class III cardiovascular devices accelerate combination drug-delivery system approvals. The Ruhr industrial corridor hosts concentrated lipid management specialist centers in Essen and Düsseldorf university hospitals.
Japan
Chuikyo reimbursement decisions favor therapies with documented cardiovascular event reduction in elderly populations. PMDA consultation frameworks compress review timelines for RNA interference platforms with annual dosing schedules. Osaka and Tokyo metropolitan areas concentrate underpenetrated specialist clinic expansion targets for dedicated dyslipidemia centers.
China
NMPA innovation pathway designations accelerate review for locally manufactured PCSK9 biosimilars targeting national reimbursement list inclusion. Dual carbon goals and sustainable manufacturing incentives reshape active pharmaceutical ingredient production geography. The Yangtze River Delta biocluster in Shanghai and Suzhou anchors domestic biologic fill-finish capacity expansion.
India
Out-of-pocket statin expenditure dominates primary care prescribing patterns despite rising diabetes-cardiovascular comorbidity burden. CDSCO streamlined approval pathways for fixed-dose combination therapies address polypharmacy adherence challenges. Hyderabad and Ahmedabad pharmaceutical manufacturing clusters concentrate generic atorvastatin active pharmaceutical ingredient production.
Dyslipidemia Therapeutics Market Competitive Landscape
Capability concentration sits with biologic manufacturers commanding monoclonal antibody and RNA interference platforms; scale advantage sits with primary care infrastructure owners sustaining statin volume distribution. The market structures around three archetypes: primary care pharmaceutical incumbents, specialty biologic pure-plays, and emerging RNA interference platform specialists. Dominant competitive moves include backward integration into biologic manufacturing capacity and strategic partnerships for digital adherence infrastructure.
Among established pharmaceutical incumbents, Pfizer and Sanofi occupy positions bridging primary care statin distribution with injectable specialty clinic penetration. Amgen anchors the biologic manufacturing tier with fill-finish scale that competitors struggle to replicate. These three entities exemplify divergent strategic postures: infrastructure leverage versus manufacturing depth versus platform specialization.
| Leading Market Players |
|---|
| Pfizer |
| Sanofi |
| Amgen |
| Merck & Co. |
| Novartis |
| AstraZeneca |
| Abbott Laboratories |
| Regeneron Pharmaceuticals |
| Arrowhead Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Fill-finish undercapacity across contract biologics manufacturers in the United States and Germany is elevating slot premiums for PCSK9 inhibitor production while compressing margins for statin active pharmaceutical ingredient suppliers in India and China. This utilization asymmetry bifurcates supplier behavior: biologic manufacturers command term-of-trade concessions while small-molecule producers absorb cost compression to maintain volume.
Pricing Analysis
Aftermarket adherence monitoring revenue streams now drive lifetime value capture beyond the initial prescription fill. Three-tier pricing structure across premium RNA interference platforms, standard monoclonal antibody injections, and economy statin generics anchors the market. Pricing pressure stems from IQWiG and ChuikG reimbursement demands for hard endpoint evidence rather than LDL-C reduction. United States Medicare Advantage plans exhibit the least price sensitivity for injectable therapies; Indian out-of-pocket statin buyers face acute cost consciousness.
Supply Chain Analysis
Tariff exposure between the United States and China is reshourcing statin active pharmaceutical ingredient production toward Portugal and Spain under EU Green Deal manufacturing incentives. Biologic fill-finish capacity concentrates in the United States, Germany, and Ireland; small-molecule synthesis feeds from India and China. Supply chain risk centers on single-source vulnerability for monoclonal antibody drug substance production. Distribution runs through hospital outpatient departments for injectables and retail pharmacy networks for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA interference platforms are shifting dyslipidemia therapeutics toward subscription-economics logic where dosing frequency determines reimbursement tiering. Interoperable FHIR-compliant data exchange between hospital EHR systems and manufacturer adherence platforms is the critical interoperability threshold.
For Market Incumbents: Harden biologic manufacturing scale advantages through captive fill-finish capacity additions in the Ruhr corridor and Massachusetts bioclusters. Lock in hospital system EHR integration partnerships before RNA interference platforms virtualize patient touchpoints. Defend against pure-play digital therapeutic entrants by consolidating telehealth adherence monitoring under proprietary platforms. For New Entrants and Emerging Players: Build out dedicated dyslipidemia specialist clinics in Osaka and Tokyo metropolitan corridors where lipid management remains concentrated in general practice. Capture Japanese Chuikyo reimbursement pathways by prioritizing elderly cardiovascular outcome data. Anchor go-to-market strategy through hospital system risk-sharing contracts rather than pharmacy benefit manager volume rebates. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because RNA interference dosing compression will eliminate pharmacy network intermediaries and concentrate value with manufacturers controlling patient data infrastructure. Target acquisition archetypes are digital adherence platform specialists with FHIR-compliant hospital integrations. Watch for inflection when United States payers mandate interoperable data standards as procurement preconditions.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive biologic fill-finish capacity in Germany and the United States insulates against contract manufacturer slot scarcity. |
| Regulatory Approval Pathway | EMA MDR streamlined conformity assessment for Class III cardiovascular devices accelerates combination product timelines in the Netherlands. |
| Strategic Partnership | Hospital system EHR integration partnerships with Cleveland Clinic and Mayo Clinic cardiovascular service lines lock in high-intensity prescribing. |
| Pipeline Diversification | RNA interference platform investment virtualizes adherence monitoring requirements and shifts reimbursement toward outcomes-based contracts. |
| Reimbursement Strategy | IQWiG and Chuikyo hard endpoint evidence packages secure premium positioning in German SHI and Japanese national health systems. |
Research Methodology
The analysis maps statin small-molecules, PCSK9 monoclonal antibodies, RNA interference platforms, and combination drug-delivery systems, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview findings triangulate against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare claims data. Bottom-up patient population sizing and top-down pharmaceutical revenue reconciliation anchor volume and value estimates.
Fixed assumptions include regulatory approval timelines for RNA interference platforms and cardiovascular outcome trial completion rates; varied parameters encompass IQWiG and Chuikyo reimbursement decision timing and United States payer prior authorization stringency. Segmentation dimensions span molecular mechanism, therapy area, delivery mode, and end user setting. CAGRs derive from event-driven enrollment curves and dosing frequency adoption slopes across the projection horizon. Modeled inputs include biologic manufacturing capacity utilization and statin generic substitution elasticities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital therapeutic pure-plays or RNA interference platform specialists would shift outcomes through accelerated patient touchpoint virtualization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
North America Travel Vaccines Market