
 Oral Anticoagulant Market | 2026-2036
Oral Anticoagulant Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Anticoagulant Market Outlook
Hospital procurement consolidation is decoupling from traditional distributor relationships as integrated delivery networks centralize formulary decisions. Bristol-Myers Squibb leverages its cardiovascular franchise to sustain institutional contracts across major academic medical centers. Pfizer Inc. anchors its position through manufacturing scale that secures supply continuity for national hospital systems.
Oral anticoagulants comprise small-molecule agents that inhibit thrombin or factor Xa to prevent clot formation, with formulations requiring precise bioavailability control through active pharmaceutical ingredient crystallization and modified-release coating technologies. The apixaban segment leads in prescription volume across atrial fibrillation therapy areas, while the homecare end-user channel shows the fastest structural expansion as oral administration enables patient self-management outside acute settings. Rivaroxaban occupies a mature position in venous thromboembolism prophylaxis with established reimbursement frameworks.
The FDA oversees new drug applications and post-market safety surveillance for oral anticoagulants in the United States, while the EMA coordinates centralized marketing authorization and risk management plans across European member states. These regulators shape demand through pharmacogenomic labeling requirements and real-world evidence mandates that extend development timelines but elevate clinical confidence. Stakeholders must monitor evolving antidote availability protocols and biosimilar entry pathways as determinants of portfolio positioning and pricing flexibility.
Market Dynamics
Hospital procurement consolidation across the United States, Germany, and Japan is forcing manufacturers to restructure commercial operations around integrated delivery network formularies rather than traditional distributor relationships.
Growth Catalysts
- Expanded atrial fibrillation screening programs:Systematic detection protocols in aging populations across Japan and Germany are converting undiagnosed patients into chronic therapy candidates.
- FDA accelerated approval pathways:Streamlined cardiovascular therapy designations compress development timelines for novel anticoagulant mechanisms, rewarding sponsors with earlier revenue recognition.
- Homecare channel infrastructure:Self-administration protocols and remote monitoring capabilities are shifting treatment settings from infusion centers to patient residences.
Market Restraints
- Antidote availability constraints:Limited commercial supply of factor Xa reversal agents creates institutional hesitancy in high-bleeding-risk patient populations.
- Reimbursement compression in European markets:EMA pharmacovigilance mandates extend post-market surveillance costs without corresponding price premiums.
- Warfarin substitution persistence:Established vitamin K antagonist protocols with decades of clinical familiarity resist conversion in cost-sensitive health systems.
Strategic Opportunities
- Pharmacogenomic-guided dosing:CYP2C9 and VKORC1 testing integration enables personalized warfarin alternatives with reduced bleeding event profiles.
- Japan's super-aging demographic:The world's oldest population concentration generates disproportionate stroke prevention demand relative to market size.
- Biosimilar entry pathways:EMA and FDA reference product exclusivity cliffs are opening abbreviated approval routes for follow-on factor Xa inhibitors.
Industry Challenges
- Real-world evidence collection infrastructure:Post-market surveillance mandates require investment in patient registries and health record interoperability.
- Active pharmaceutical ingredient crystallization expertise:Precise polymorph control for bioavailability consistency demands specialized process chemistry capabilities.
- Formulary committee access restrictions:Consolidated hospital network purchasing functions reduce manufacturer touchpoints with prescribing influencers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Anticoagulant Market |
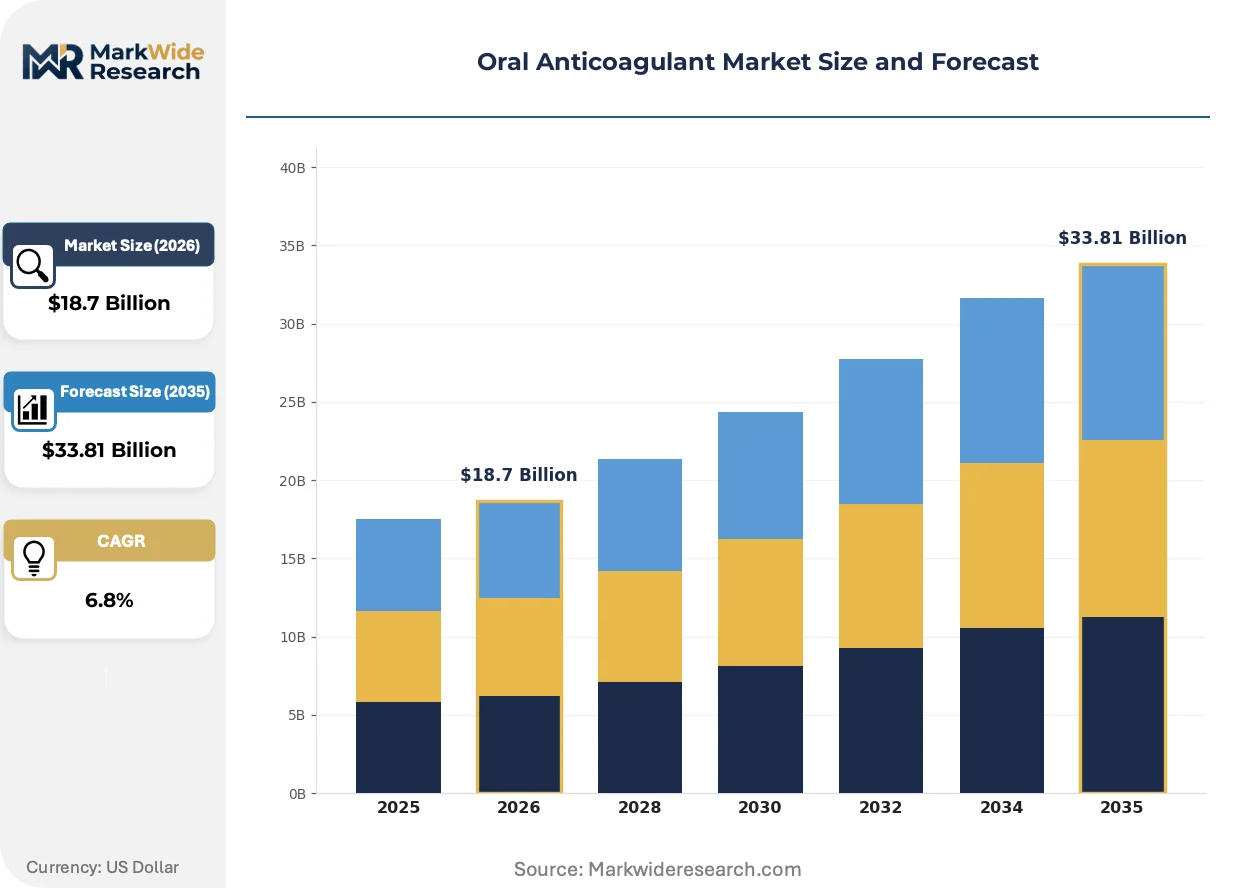
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Warfarin, Dabigatran, Rivaroxaban, Apixaban Therapy Area: Cardiovascular, Stroke Prevention, Atrial Fibrillation, Venous Thromboembolism End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Route of Administration: Oral, Sublingual, Buccal, Gastrointestinal |
| Companies Covered | Bristol-Myers Squibb, Pfizer Inc., Bayer AG, Johnson & Johnson, Boehringer Ingelheim, Daiichi Sankyo Company, Sanofi, AstraZeneca, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Anticoagulant Market Strategic Shifts
Oral anticoagulant development is pivoting toward patient-specific therapeutic windows through biomarker integration and manufacturing precision advances.
Modified-release coating technologies are overtaking immediate-release formulations in new product development pipelines. Academic medical centers in the United States are prioritizing once-daily regimens with reduced peak-trough variability to improve adherence metrics. This shift is compressing the competitive relevance of legacy twice-daily dosing schedules.
EMA's evolving pharmacovigilance standards are extending risk management plan requirements across the product lifecycle. Marketing authorization holders must now maintain active surveillance systems that detect rare bleeding events below traditional clinical trial thresholds. The apixaban therapeutic class faces the steepest compliance cost escalation as the reference product for emerging biosimilar competitors.
Integrated delivery networks are centralizing anticoagulation stewardship programs that override individual physician prescribing preferences. Hospital systems in Germany are deploying algorithm-driven protocols that standardize agent selection across affiliated outpatient clinics. This behavioral shift concentrates volume with formulary winners and marginalizes second-tier alternatives.
Oral Anticoagulant Market Segmentation
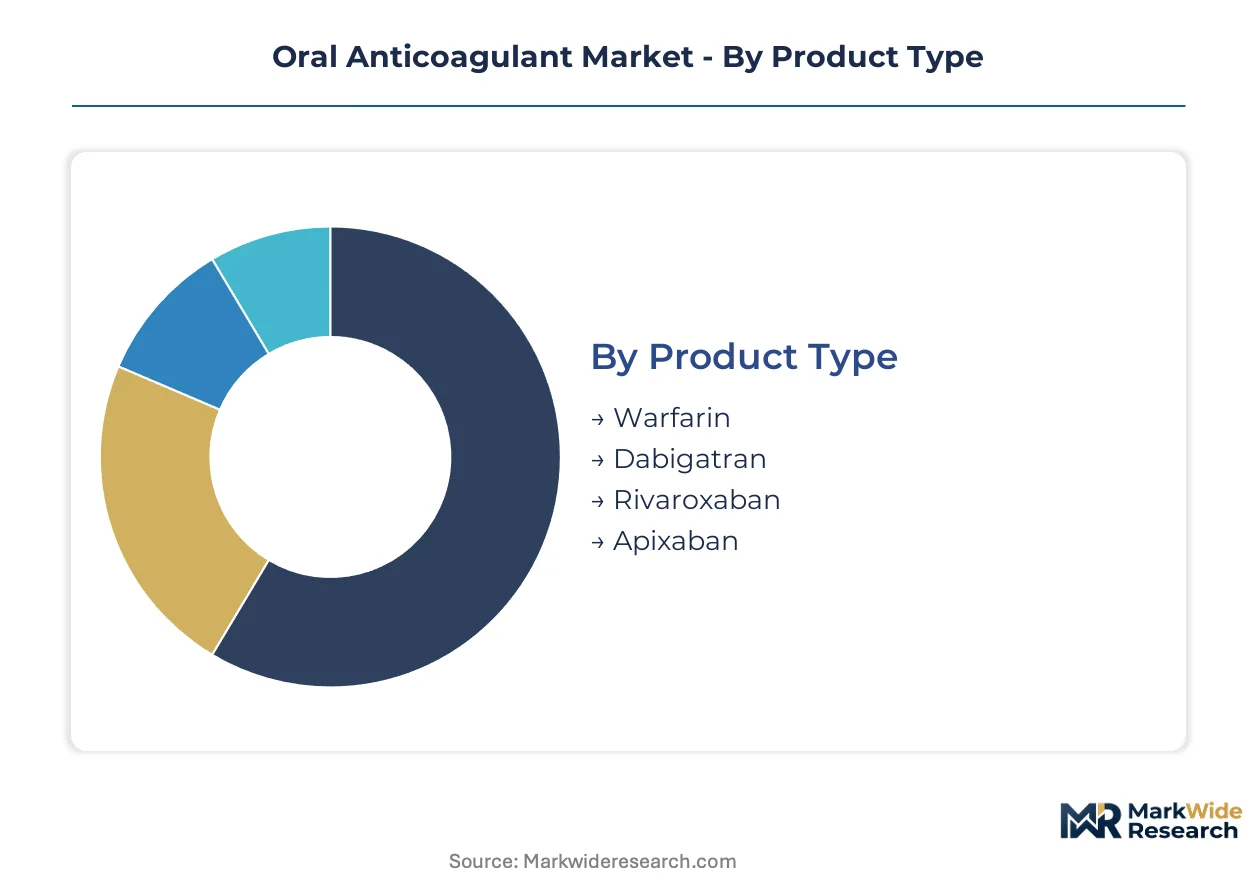
Segmentation in oral anticoagulants reveals how formulation chemistry, clinical setting, and patient acuity stratify commercial opportunity. Manufacturers must align R&D investment and distribution infrastructure with the specific technical and logistical demands of each segment cluster.
Product Type:
Standardization dominates vitamin K antagonists while factor Xa and direct thrombin inhibitors compete on bioavailability precision and dosing convenience.
- Apixaban:Factor Xa inhibition with twice-daily dosing and established renal clearance pathways. Demand concentrates in United States academic medical centers where anticoagulation stewardship programs favor its predictable pharmacokinetic profile for outpatient atrial fibrillation management.
- Rivaroxaban:Once-daily factor Xa inhibitor with single-tablet regimens for venous thromboembolism prophylaxis. German hospital networks prioritize this agent for post-surgical protocols due to streamlined nursing workflows and embedded reversal agent development.
- Warfarin:Vitamin K antagonist requiring INR monitoring and dietary restriction management.
- Dabigatran:Direct thrombin inhibitor with distinct renal elimination characteristics and specific reversal agent availability.
Leading the category by volume: Apixaban. Growing fastest: Rivaroxaban.
Therapy Area:
Acuity gradients separate acute intervention markets from chronic prevention, with reimbursement intensity scaling accordingly.
- Atrial Fibrillation:Chronic rhythm disorder driving sustained prescription volumes in aging populations. Japanese screening programs and United States Medicare preventive service expansions convert undiagnosed patients into long-term therapy candidates with decades-long treatment horizons.
- Venous Thromboembolism:Acute clotting events spanning deep vein thrombosis and pulmonary embolism. Post-surgical prophylaxis protocols in German and United States hospital systems generate concentrated demand windows with standardized dosing algorithms.
- Stroke Prevention:Secondary prevention indication requiring persistent therapy adherence.
- Cardiovascular:Broader cardiac event risk reduction encompassing multiple comorbidity profiles.
Atrial Fibrillation commands the largest prescription base. Venous Thromboembolism is climbing the fastest as surgical volume recovers and prophylaxis protocols tighten.
End User:
Site-of-care migration from institutional settings to patient residences restructures distribution economics and compliance monitoring requirements.
- Hospitals:Acute initiation and perioperative management with formulary committee gatekeeping. Consolidated procurement across United States integrated delivery networks and German hospital alliances concentrates volume with contracted manufacturers.
- Homecare:Self-administration enabled by oral bioavailability and remote monitoring infrastructure. Japan's super-aging demographic and United States telehealth reimbursement expansions accelerate this channel's structural shift.
- Clinics:Outpatient initiation and dose titration with physician oversight.
- Long-term Care Facilities:Institutional chronic management with nursing-mediated administration.
Hospitals retain the dominant volume position. Homecare gains share fastest as patient self-management protocols mature.
Route of Administration:
Absorption kinetics and first-pass metabolism considerations determine formulation development priorities and manufacturing complexity.
- Oral:Standard gastrointestinal absorption with modified-release coating technologies enabling precise plasma concentration control. This route anchors the entire market as the definitive advantage over parenteral alternatives.
- Sublingual:Buccal mucosa absorption bypassing hepatic first-pass metabolism for rapid onset applications.
- Buccal:Extended mucosal contact with modified tablet geometry.
- Gastrointestinal:Enteric-coated formulations protecting acid-labile compounds.
Oral administration dominates absolutely. Sublingual development shows the steepest expansion trajectory as manufacturers target rapid-onset indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient crystallization expertise clusters in Basel, Ludwigshafen, and Osaka anchor formulation supply chains for oral anticoagulant manufacturing. Hospital procurement consolidation and aging demographics concentrate prescription demand in three distinct national markets.
United States
Medicare preventive service expansions and integrated delivery network formulary centralization drive apixaban prescription volumes. The FDA's accelerated approval pathways compress development timelines for novel cardiovascular therapies. Academic medical centers in Boston and the Research Triangle deploy algorithm-driven anticoagulation stewardship programs that standardize agent selection.
Germany
Hospital alliance procurement consolidation and post-surgical prophylaxis protocol tightening concentrate rivaroxaban demand. EMA pharmacovigilance standards extend risk management plan requirements across the product lifecycle. The Rhine-Ruhr industrial corridor hosts specialized modified-release coating technology facilities serving European formulation needs.
Japan
The world's oldest population concentration generates disproportionate stroke prevention demand relative to market size. PMDA oversight of pharmacogenomic labeling requirements shapes personalized warfarin alternative development. The Kansai region's pharmaceutical manufacturing base supplies precision crystallization capabilities for factor Xa inhibitor production.
Switzerland
Swissmedic marketing authorization frameworks attract cardiovascular therapy sponsors seeking European regulatory efficiency. Basel's dense cluster of process chemistry specialists enables polymorph control for bioavailability consistency. The country's contract manufacturing organizations serve as formulation development hubs for multinational sponsors.
United Kingdom
NHS integrated care system procurement reforms consolidate oral anticoagulant purchasing across regional footprints. The MHRA's post-Brexit regulatory autonomy enables tailored pharmacovigilance timelines distinct from EMA coordination. London's clinical trial infrastructure supports real-world evidence collection for bleeding event surveillance below traditional thresholds.
Oral Anticoagulant Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biosimilar factor Xa inhibition and pharmacogenomic-guided dosing adjacents. The vendor base stratifies across three maturity tiers: legacy vitamin K antagonist manufacturers, direct oral anticoagulant originators with institutional contract depth, and biosimilar developers targeting reference product exclusivity cliffs. Three archetypes dominate: cardiovascular franchise holders leveraging cross-product hospital relationships, manufacturing-scale players securing supply continuity for national systems, and specialty pharmaceutical developers integrating diagnostic companion offerings. Competitive positioning depends on formulary committee access and active pharmaceutical ingredient supply security.
Among North American pharmaceutical incumbents, Bristol-Myers Squibb and Pfizer Inc. exemplify the cardiovascular franchise archetype, with the former representing institutional contract depth across academic medical centers and the latter anchoring manufacturing-scale supply relationships with integrated delivery networks. Bayer AG occupies a distinct position within the European-origin tier, reflecting German industrial chemistry heritage in active pharmaceutical ingredient production. These three entities exemplify how commercial operations restructure around consolidated procurement functions rather than traditional distributor channels.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Pfizer Inc. |
| Bayer AG |
| Johnson & Johnson |
| Boehringer Ingelheim |
| Daiichi Sankyo Company |
| Sanofi |
| AstraZeneca |
| Merck & Co. |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient spot indices for heparin precursors and synthetic warfarin intermediates cascade through oral anticoagulant supply chains into tiered pricing structures. German hospital alliances and United States integrated delivery networks exploit procurement consolidation to compress margins on standard-tier agents while premium formulations with modified-release coatings command residual pricing power.
Pricing Analysis
Service bundling separates anticoagulation stewardship program inclusion from unbundled product-only procurement, with United States academic medical centers paying premiums for algorithm-driven dosing support. Three-tier pricing structure across premium, standard, and economy levels stratifies by bioavailability consistency and reversal agent availability. Pricing pressure stems from biosimilar entry pathways opening abbreviated FDA and EMA approval routes. Cost-sensitive health systems in European markets exhibit highest price sensitivity, while Japan's super-aging demographic shows lowest sensitivity due to stroke prevention urgency.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks and German hospital alliances require qualification of alternative API suppliers for factor Xa inhibitors. Active pharmaceutical ingredient production concentrates in Switzerland, Germany, and Japan, with formulation finishing in regional hubs serving respective regulatory clusters. Supply chains draw from naphtha-derived synthetic precursors, crystallization solvents, and specialized coating polymers. Single-source vulnerability persists in polymorph-controlled API manufacturing where Basel and Ludwigshafen process chemistry expertise remains concentrated. Distribution runs through consolidated hospital procurement functions and specialty pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral anticoagulant competitive dynamics have become a vertical-integration race, with manufacturers pursuing backward integration into active pharmaceutical ingredient crystallization to secure supply continuity and pricing leverage.
For Market Incumbents: Anticipate biosimilar factor Xa inhibitor entries by securing captive supply of polymorph-controlled APIs through in-house production or exclusive tolling arrangements in Basel and Ludwigshafen. Deepen formulary committee relationships through bundled anticoagulation stewardship program offerings that embed dosing algorithms and remote monitoring infrastructure. Margins are tightening due to reimbursement compression in European markets and warfarin substitution persistence in cost-sensitive systems. For New Entrants and Emerging Players: Pharmacogenomic-guided dosing platforms represent the most penetrable white-space target, with CYP2C9 and VKORC1 testing integration enabling personalized alternatives to standard warfarin protocols. Japan's super-aging demographic offers disproportionate prescription volume relative to market entry costs, particularly for once-daily regimens with reduced peak-trough variability. Pursue partnership-based go-to-market models with diagnostic companies to bundle testing and therapy initiation. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturing organizations with crystallization expertise in Switzerland and Germany, where specialized process chemistry capabilities face temporary demand softness. Long-term viability centers on API supply security and EMA pharmacovigilance compliance infrastructure. Watch antidote availability protocol expansions as the inflection signal for factor Xa inhibitor portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Active Pharmaceutical Integration | Backward integration into crystallization secures polymorph control for bioavailability consistency. |
| Anticoagulation Stewardship Partnership | Hospital system alliances embed dosing algorithms that standardize formulary selection. |
| Pharmacogenomic Companion Development | CYP2C9 testing integration enables personalized warfarin alternatives with reduced bleeding profiles. |
| Biosimilar Entry Pathway Execution | Abbreviated EMA and FDA approval routes exploit reference product exclusivity cliffs. |
| Homecare Channel Infrastructure Buildout | Remote monitoring capabilities shift treatment settings from infusion centers to patient residences. |
Study Parameters
Document review covered FDA new drug applications, EMA marketing authorization submissions, ClinicalTrials.gov protocols, and hospital formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from SEC pharmaceutical filings, CMS Medicare prescription data, and GPO contract disclosures. Bottom-up prescription volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Segmented outputs reflect product type stratification by mechanism of action, therapy area acuity gradients, end-user site-of-care migration, and regional regulatory cluster variations. CAGRs were derived from patient population epidemiology, screening program expansion timelines, and reimbursement trajectory modeling. Forecast inputs incorporated PMDA pharmacogenomic labeling requirements and integrated delivery network procurement consolidation patterns.
Several conditions sit outside the modeled scope, including antidote availability protocol reversals, warfarin substitution rate accelerations, and abrupt EMA pharmacovigilance standard changes. Forecasts reflect documented assumptions regarding aging demographic trajectories and screening program implementation. Deviation in biosimilar approval timelines or API supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market