
 Counterfeit Drug Detection Device Market | 2026-2036
Counterfeit Drug Detection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Counterfeit Drug Detection Device Market Analysis
Pharmaceutical-grade spectroscopic resolution is reorganizing competitive dynamics across the counterfeit drug detection landscape. Bruker leverages its magnetic resonance and mass spectrometry heritage to anchor premium laboratory installations for regulatory compliance testing. Thermo Fisher Scientific sustains broad channel control through integrated chromatography workflows that span quality control laboratories and field applications. Smiths Detection competes with portable threat-detection architectures originally developed for security screening, now adapted for pharmaceutical supply chain checkpoints.
Counterfeit drug detection devices are analytical instruments that verify pharmaceutical authenticity through molecular fingerprinting, typically resolving active pharmaceutical ingredients at parts-per-million sensitivity using Raman, infrared, or mass spectrometry methods. Their primary purpose is to intercept falsified medicines before they reach patients or to confirm batch integrity during manufacturing. Handheld devices dominate field deployment due to their suitability for customs inspections and rural pharmacy screening, while desktop systems retain margin concentration in centralized quality control laboratories where chromatography and imaging workflows require controlled environments. Machine learning integration represents the fastest-expanding technology segment as spectral pattern recognition reduces operator training burdens and accelerates pass-fail decisions at high-throughput checkpoints.
The FDA's Drug Supply Chain Security Act and the European Medicines Agency's Falsified Medicines Directive together mandate unit-level traceability, compelling manufacturers and distributors to invest in verification infrastructure. India's Central Drugs Standard Control Organization enforces barcode-based authentication for exported pharmaceuticals, creating parallel demand for detection devices that complement electronic tracking systems. Stakeholders must weigh capital intensity against regulatory penalty exposure as enforcement mechanisms evolve and detection thresholds tighten across major pharmaceutical markets.
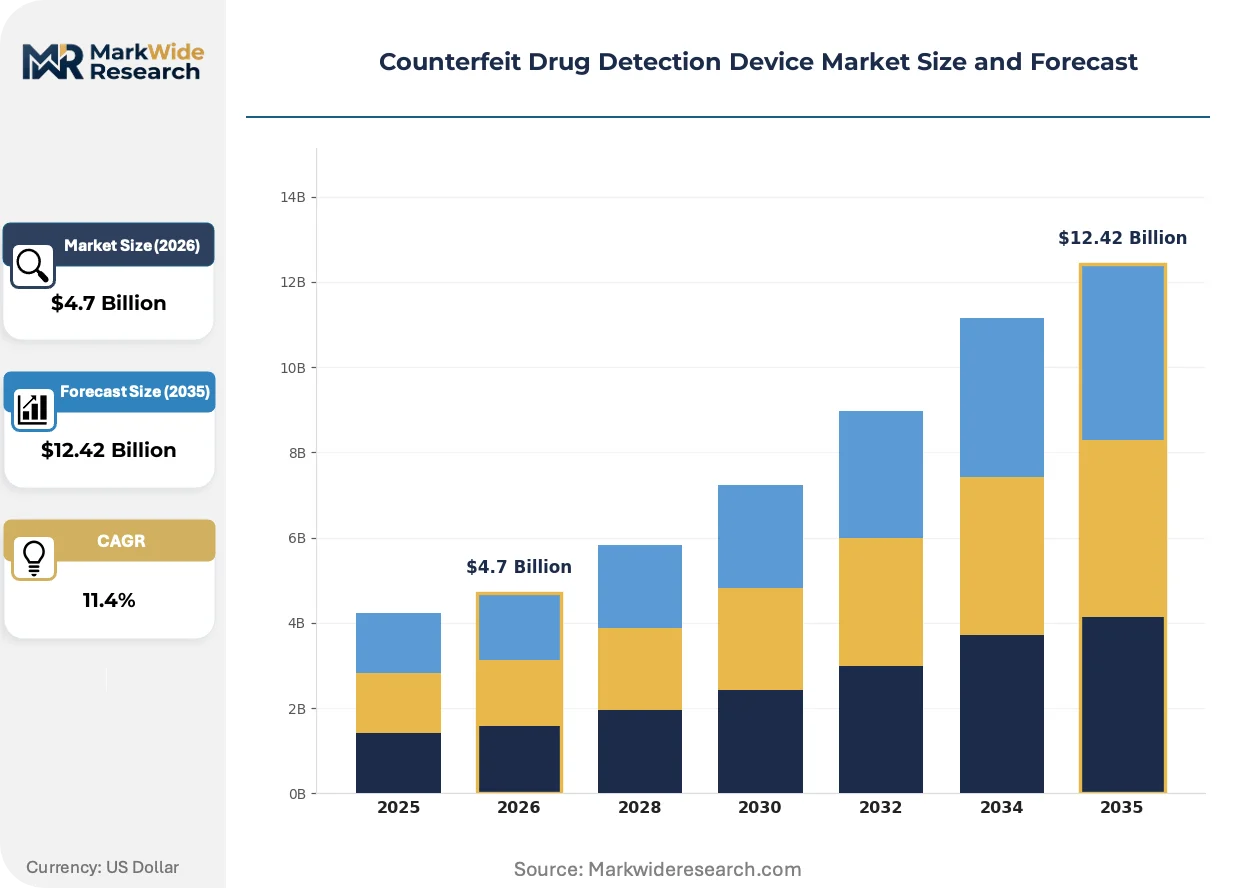
Market Dynamics
Regulatory serialization mandates are compressing deployment timelines for detection infrastructure across pharmaceutical supply chains, forcing manufacturers to integrate verification hardware with electronic track-and-trace systems before enforcement deadlines.
Growth Catalysts
- FDA DSCSA Enforcement:The Drug Supply Chain Security Act mandates unit-level traceability for prescription drugs, compelling wholesale distributors to install verification systems at distribution centers.
- Portable Raman Spectroscopy:Handheld devices capable of parts-per-million API detection are penetrating customs checkpoints and rural pharmacies where laboratory access remains limited.
- India CDSCO Export Rules:Barcode-based authentication requirements for pharmaceutical exports are driving procurement of complementary detection devices at manufacturing sites.
Market Restraints
- Reference Standard Scarcity:Authentic API libraries required for spectral matching face restricted availability from originator manufacturers, limiting device calibration accuracy.
- Optical Component Concentration:High-precision laser diodes and detector arrays concentrate among specialized Japanese and German suppliers, creating input vulnerability.
- EU MDR Certification Burden:Medical device regulation reclassification of certain detection systems extends approval timelines and elevates documentation requirements.
Strategic Opportunities
- Sub-Saharan Africa Distribution:Weak regulatory infrastructure and high counterfeit prevalence create unmet demand for low-cost field screening devices at port-of-entry and clinic level.
- Blockchain-Spectroscopy Convergence:Integration of molecular fingerprinting with distributed ledger verification offers tamper-evident authentication for high-value biologics.
- India PLI Scheme Alignment:Production-linked incentives for domestic medical device manufacturing reduce landed cost for detection equipment deployed across South Asian supply chains.
Industry Challenges
- Spectral Interpretation Expertise:Shortage of analytical chemists capable of resolving ambiguous Raman shifts or infrared spectra creates operational bottlenecks at high-throughput checkpoints.
- Legacy LIMS Integration:Laboratory information management systems at established pharmaceutical quality control facilities require costly middleware development to accept portable device data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Counterfeit Drug Detection Device Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Desktop Systems, Smartphone Applications, Remote Sensors Technology: Spectroscopy, Chromatography, Machine Learning, Imaging End User: Pharmacies, Hospitals, Regulatory Authorities, Manufacturers Application: Quality Control, Regulatory Compliance, Supply Chain Verification, Point-of-Care Testing |
| Companies Covered | Bruker, Spectris, Thermo Fisher Scientific, Smiths Detection, Spectral Engines Oy, Rigaku Corporation, Olympus Corporation, Metrohm, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Counterfeit Drug Detection Device Market Emerging Trajectories
Artificial intelligence pattern recognition is compressing the gap between laboratory-grade analytical precision and field-deployable device performance, reshaping where and how authentication occurs across pharmaceutical value chains.
Machine learning inference at the spectroscopic edge is fragmenting the traditional boundary between centralized quality control and distributed screening. Neural network models trained on expanded molecular libraries now execute pass-fail decisions directly on handheld Raman units without cloud connectivity. Generic drug manufacturers in India and Brazil are deploying these autonomous systems at packaging lines to reduce batch release times.
REACH chemical registration requirements are extending disclosure obligations to detection reagents and calibration standards used in pharmaceutical analysis. Manufacturers of portable devices must now document substance volumes and hazard classifications for EU market access. This regulatory layer disproportionately affects suppliers of mass spectrometry consumables, who are reformulating ionization matrices to reduce restricted substance content.
Hospital pharmacy buyers are consolidating verification equipment procurement under centralized supply chain functions rather than decentralized clinical laboratory budgets. This purchasing concentration favors vendors offering fleet management software and multi-site service agreements over single-device suppliers. The shift is most pronounced in US integrated delivery networks and German hospital alliances, where standardization reduces training overhead across affiliated facilities.
Counterfeit Drug Detection Device Market Segmentation
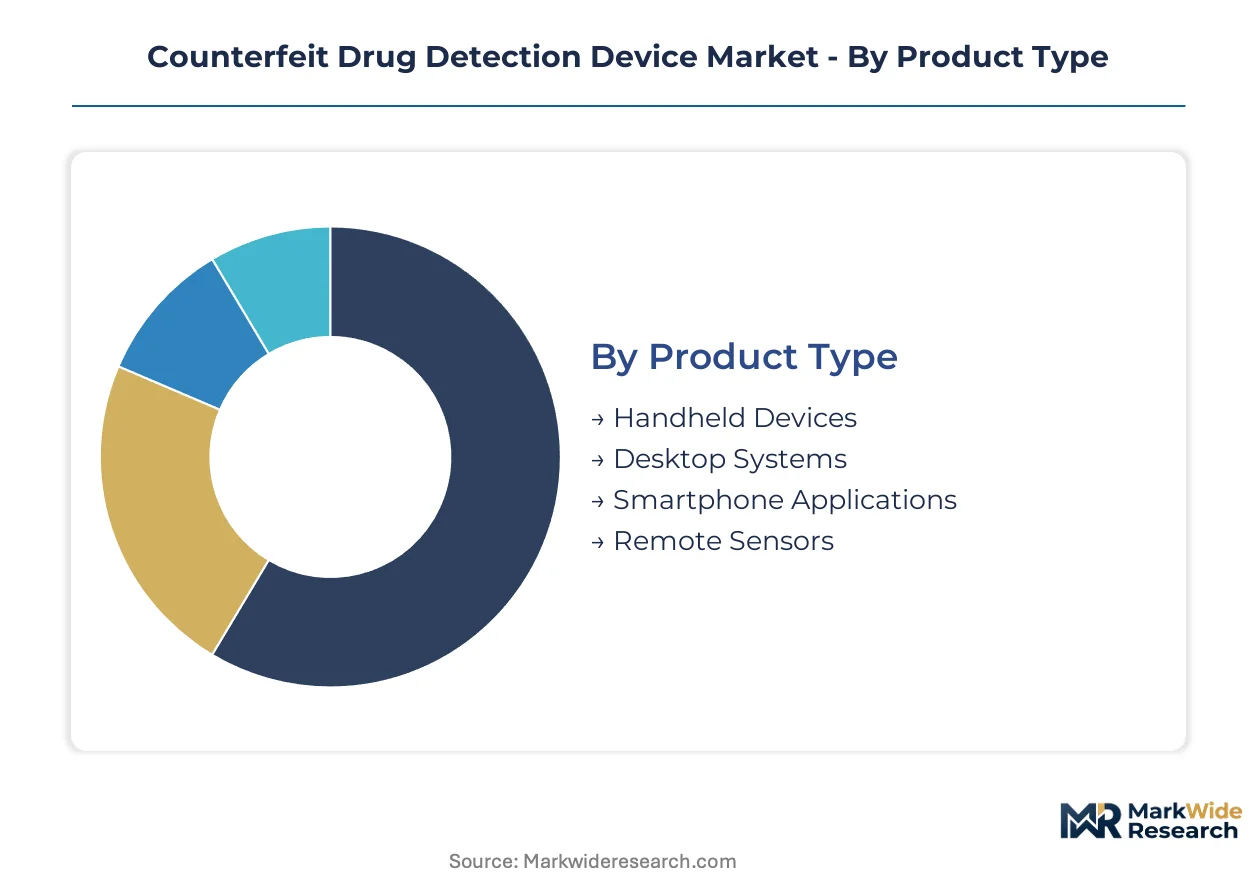
Segmentation in counterfeit drug detection devices reflects divergent technical requirements across enforcement checkpoints, manufacturing workflows, and patient-facing verification scenarios. Procurement decisions hinge on detection sensitivity thresholds, portability constraints, and integration complexity with existing pharmaceutical quality infrastructure.
Product Type:
FDA DSCSA and EU Falsified Medicines Directive enforcement timelines are compressing procurement cycles differently across portable versus fixed installations, with customs agencies and wholesale distributors facing distinct hardware constraints.
- Handheld Devices:Battery-powered Raman and infrared units weighing under 2 kilograms enable non-destructive screening at port-of-entry checkpoints and rural pharmacies lacking laboratory infrastructure. Indian customs authorities at Mumbai and Chennai ports are deploying these units for generic drug export verification under CDSCO track-and-trace mandates.
- Desktop Systems:Laboratory-grade chromatography and mass spectrometry installations deliver parts-per-billion sensitivity for API quantification and impurity profiling. Pharmaceutical manufacturers in Germany and Switzerland utilize these systems for batch release documentation required by EMA centralized procedures.
- Smartphone Applications:Camera-based authentication apps leverage visible-light spectral analysis and blockchain verification for consumer-level drug legitimacy checks.
- Remote Sensors:Networked detection nodes embedded in automated packaging lines enable continuous in-process verification without operator intervention.
Handheld devices handle the majority of throughput across customs and distribution checkpoints; smartphone applications are expanding most quickly on share as consumer authentication demand rises.
Technology:
Cost tiers separate premium analytical methods from scalable screening approaches, with capital intensity determining deployment feasibility across centralized laboratories versus distributed field networks.
- Spectroscopy:Raman, infrared, and near-infrared methods provide molecular fingerprinting without sample destruction, dominating field deployment due to minimal consumable requirements. Portable Raman units from Japanese and German optical component suppliers are penetrating Indian and Brazilian generic manufacturing facilities.
- Chromatography:High-performance liquid chromatography and gas chromatography deliver definitive API quantification with reference standard traceability for regulatory submissions. US and European innovator pharmaceutical companies maintain these systems for FDA and EMA compliance documentation.
- Machine Learning:Neural network inference on spectral data reduces operator training requirements and accelerates pass-fail decisions at high-volume screening points.
- Imaging:Hyperspectral and chemical imaging systems capture spatial distribution of active ingredients for detecting sophisticated physical counterfeits.
Spectroscopy commands the largest installed base; machine learning is climbing the fastest as edge computing capabilities mature.
End User:
Customer type dictates purchasing authority structure, with centralized supply chain functions displacing decentralized laboratory budgets in consolidated health systems.
- Pharmacies:Community and hospital pharmacy procurement focuses on rapid verification to prevent dispensing errors, with US integrated delivery networks standardizing device fleets across affiliated facilities. German hospital alliances are consolidating verification equipment under centralized supply chain functions.
- Hospitals:Clinical pharmacy and emergency department deployment requires integration with electronic health records and medication administration systems.
- Regulatory Authorities:Customs agencies and national pharmaceutical regulators prioritize interdiction volume and evidence chain integrity for enforcement actions.
- Manufacturers:Quality control and packaging line integration demands batch release automation and LIMS connectivity for documentation workflows.
Manufacturers absorb the largest capital expenditure volume; regulatory authorities are gaining share fastest as enforcement infrastructure expands.
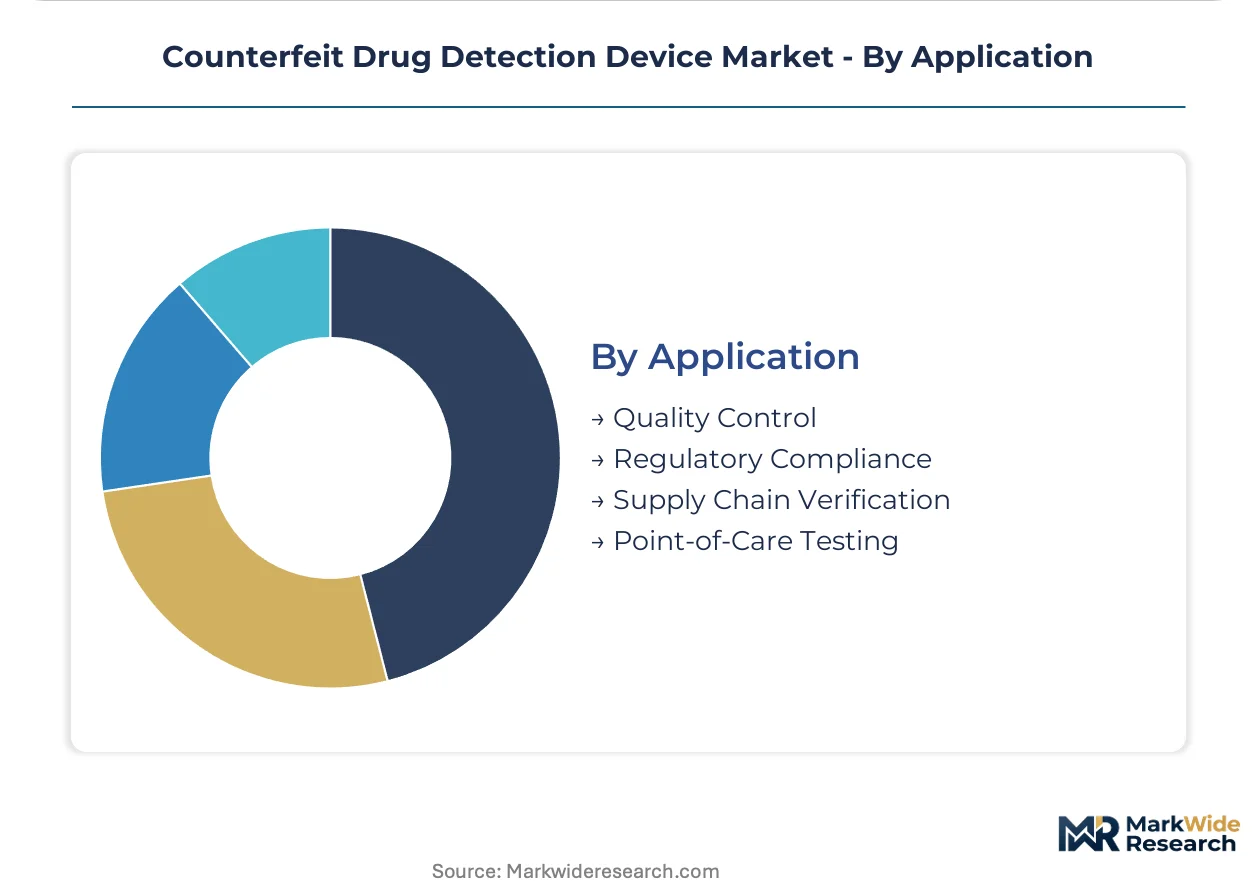
Application:
Volume concentration separates high-throughput screening scenarios from precision analytical workflows, with throughput requirements determining technology selection and staffing models.
- Quality Control:Laboratory-based API identity testing and impurity profiling supports batch release decisions with documented analytical methods. Pharmaceutical manufacturers in India deploy these workflows for CDSCO export certification.
- Regulatory Compliance:Verification systems mandated by FDA DSCSA and EU Falsified Medicines Directive for unit-level traceability and authentication.
- Supply Chain Verification:Checkpoint screening at wholesale distributors, customs facilities, and third-party logistics hubs intercepts falsified medicines before patient exposure.
- Point-of-Care Testing:Bedside and clinic-level authentication addresses immediate patient safety concerns in resource-limited settings.
Quality control retains the deepest technology penetration; supply chain verification is expanding most rapidly as serialization deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized optical component suppliers in Japan and Germany control critical laser diode and detector array inputs, creating geographic chokepoints that shape device availability and pricing across pharmaceutical supply chains.
United States
FDA DSCSA enforcement deadlines are accelerating wholesale distributor procurement of verification systems at distribution centers in New Jersey and Pennsylvania. The Drug Supply Chain Security Act mandates unit-level traceability, compelling pharmaceutical logistics hubs to install authentication hardware before compliance dates. Indianapolis and Memphis distribution clusters are deploying integrated detection networks to intercept falsified medicines.
Germany
EMA centralized procedures require batch release documentation with parts-per-billion sensitivity for API quantification. German pharmaceutical manufacturers in Baden-Württemberg and Bavaria maintain laboratory-grade chromatography installations for regulatory submissions. The EU Falsified Medicines Directive enforcement has tightened supply chain integrity requirements across Rhine-Main logistics corridors.
India
CDSCO track-and-trace regulations and rising generic drug exports are driving adoption of portable spectroscopy devices at manufacturing sites. The Central Drugs Standard Control Organization enforces barcode-based authentication for exported pharmaceuticals, creating parallel demand for complementary detection systems. Mumbai and Chennai port authorities are deploying handheld Raman units for export verification under mandate.
Japan
METI industrial policy supports domestic production of high-precision optical components for spectroscopic devices. Japanese suppliers concentrate laser diode and detector array manufacturing, creating input dependencies for global detection equipment producers. Osaka and Nagoya industrial clusters supply critical components to device assemblers in Asia-Pacific pharmaceutical markets.
Switzerland
Swissmedic regulatory standards for pharmaceutical quality control sustain demand for premium analytical instrumentation. Swiss pharmaceutical innovators in Basel and Geneva maintain centralized quality control laboratories with mass spectrometry installations. The country's precision manufacturing heritage supports specialized component fabrication for detection device supply chains.
Counterfeit Drug Detection Device Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the counterfeit drug detection landscape. Premium laboratory system vendors concentrate analytical precision capabilities for regulatory compliance testing, while portable device specialists compete on field deployment scalability and operator training reduction. Three archetypes dominate: heritage analytical instrumentation conglomerates, security-screening technology adapters, and optical component-integrated specialists. Consolidation pressure is intensifying through strategic partnerships between device manufacturers and machine learning platform providers, alongside geographic expansion into Indian and Brazilian generic manufacturing hubs.
Within the heritage analytical tier, Bruker and Thermo Fisher Scientific occupy positions anchored by magnetic resonance and chromatography legacies. Smiths Detection exemplifies the security-screening adaptation archetype, repurposing threat-detection architectures for pharmaceutical supply chain checkpoints. These three companies represent divergent strategic origins now converging on pharmaceutical authentication demand.
| Leading Market Players |
|---|
| Bruker |
| Spectris |
| Thermo Fisher Scientific |
| Smiths Detection |
| Spectral Engines Oy |
| Rigaku Corporation |
| Olympus Corporation |
| Metrohm |
| Agilent Technologies |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day lead times for high-precision laser diodes from Japanese and German optical suppliers concentrate pricing power upstream, forcing device assemblers to absorb cost volatility or pass through to pharmaceutical buyers facing FDA and EU enforcement deadlines.
Pricing Analysis
FDA DSCSA and EU Falsified Medicines Directive dictate the pricing tier structure across portable and laboratory-grade detection systems. Three-tier pricing structure across premium laboratory installations, standard field-deployable units, and economy handhelds separates Bruker and Thermo Fisher's chromatography platforms from Smiths Detection's security-adapted devices and emerging smartphone-based authentication apps. Pricing pressure stems from India's PLI scheme subsidizing domestic medical device manufacturing, compressing landed costs for South Asian buyers. Hospital pharmacy buyers in US integrated delivery networks exhibit highest price sensitivity due to centralized fleet procurement, while Swiss and German innovator pharmaceutical manufacturers maintain lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for optical component-dependent device assemblers. Manufacturing concentrates in Japan, Germany, and the United States for laser diodes and detector arrays; India and China for final device assembly and packaging. Critical inputs include high-precision laser diodes from Hamamatsu and Osram, germanium detector arrays, and reference standard APIs for spectral calibration libraries. Single-source vulnerability in Japanese optical component supply creates exposure to seismic disruption and export licensing delays. Distribution runs through pharmaceutical OEM direct sales for laboratory systems, specialized medical device distributors for field units, and government procurement channels for customs and regulatory authority deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of analytical chemists capable of interpreting ambiguous Raman spectra and integrating portable device data with legacy LIMS platforms constrain operational scaling across high-throughput pharmaceutical checkpoints.
For Market Incumbents: Consolidate spectral database assets and machine learning training pipelines to defend against AI-native entrants offering autonomous edge inference without cloud dependency. Acquire specialized optical component suppliers in Japan or Germany to secure laser diode supply against tariff exposure and geographic concentration risk. Deepen backward integration into reference standard API libraries to circumvent originator manufacturer access restrictions. For New Entrants and Emerging Players: Lead with low-cost handheld Raman units for Sub-Saharan African port-of-entry and clinic-level screening, where regulatory infrastructure gaps and high counterfeit prevalence create unmet demand absent incumbent presence. Target Brazilian generic manufacturing facilities adopting autonomous packaging line verification to reduce batch release times. Pursue blockchain-spectroscopy convergence partnerships for high-value biologics authentication as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from security-screening technology conglomerates seeking to monetize pharmaceutical-adapted threat detection architectures outside core defense revenue streams. Long-term viability hinges on regulatory enforcement durability across FDA, EMA, and CDSCO jurisdictions rather than discretionary pharmaceutical capital expenditure cycles. Watch for CDSCO mandate expansion to domestic Indian pharmaceutical distribution as an inflection signal for portable device demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Platform Acquisition | Neural network inference on spectral data reduces operator training burdens at high-throughput Indian generic manufacturing sites. |
| Reference Standard Library Expansion | Proprietary API spectral databases circumvent originator manufacturer scarcity constraints limiting device calibration accuracy. |
| Optical Component Backward Integration | In-house laser diode production mitigates single-source dependency on Hamamatsu and Osram supply chains. |
| Blockchain Verification Partnership | Distributed ledger integration with molecular fingerprinting creates tamper-evident authentication for high-value biologics shipments. |
| Sub-Saharan Africa Distribution Buildout | Low-cost field screening devices address unmet demand at Nigerian and Kenyan port-of-entry checkpoints with weak regulatory infrastructure. |
Methodological Framework
A spread of perspectives from pharmaceutical quality control directors, customs agency procurement officers, biomedical device regulatory consultants, and spectroscopy instrumentation engineers converged on the working assumptions governing market sizing and growth trajectory. Primary field engagement combined structured interviews with secondary validation against FDA DSCSA implementation timelines, EMA centralized procedure documentation requirements, CDSCO export certification databases, and Indian PLI scheme disbursement records. Bottom-up unit economics for handheld versus desktop device categories triangulated against top-down pharmaceutical industry capital expenditure patterns across the analysis window.
Segmentation dimensions modeled include product type hierarchy, spectroscopic versus chromatographic technology families, end-user purchasing authority structures, and application workflow integration complexity. CAGRs were derived from regression analysis of historical procurement volumes against regulatory enforcement phase-in schedules, with cross-reference to pharmaceutical manufacturing capacity expansion in India and Brazil. Forecast inputs incorporated machine learning adoption curves for edge computing inference, optical component supplier capacity constraints, and hospital pharmacy centralization trends in US and German health systems.
Forecasts assume regulatory continuity in FDA DSCSA, EU Falsified Medicines Directive, and CDSCO track-and-trace regimes; material policy shifts would require re-modeling of wholesale distributor and manufacturer procurement timelines. Specific risks include EU MDR reclassification extending device approval timelines, REACH chemical registration burden escalation for detection reagents, and reference standard API supply disruption from originator manufacturer access restrictions. Recalibration cycles align with material shifts in serialization enforcement deadlines, PLI scheme revisions, and spectroscopic edge computing capability releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Procalcitonin Antibody Market