
 Global Anti-Suicide Drugs Market | 2026-2036
Global Anti-Suicide Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Suicide Drugs Market Foresight
Psychiatric clinics are redrawing procurement priorities around rapid-acting antidepressant protocols, while mental health hospitals is redrawing their reliance on traditional oral antidepressants. Pfizer Inc. leverages its established neuroscience infrastructure to sustain formulary access across outpatient facilities. Eli Lilly and Company anchors its position through R&D intensity in novel mechanisms for treatment-resistant depression. H. Lundbeck A/S specializes in CNS therapeutics, competing on geographic dominance across European psychiatric networks.
Anti-suicide drugs comprise pharmacological agents engineered to modulate neurotransmitter systems—primarily serotonin, dopamine, and glutamate pathways—to reduce acute suicidal ideation and stabilize mood dysregulation. These compounds undergo formulation as oral tablets, intranasal sprays, and parenteral solutions, with bioavailability parameters and receptor-binding profiles determining clinical deployment speed. Selective Serotonin Reuptake Inhibitors occupy the largest installed base due to decades of safety data and generic availability, though Atypical Antipsychotics are capturing faster growth in acute crisis settings where rapid behavioral stabilization is paramount. Mood Stabilizers command concentrated margin pools within bipolar disorder protocols, while Tricyclic Antidepressants face structural decline amid toxicity concerns and newer therapeutic alternatives.
The FDA's Breakthrough Therapy designation pathway accelerates market access for novel anti-suicidal agents, while the EMA's centralized authorization process shapes commercialization timelines across European psychiatric markets. REACH compliance governs active pharmaceutical ingredient sourcing and environmental discharge standards for manufacturing facilities. Stakeholders must monitor evolving pharmacovigilance requirements and reimbursement negotiations tied to outcome-based contracts as regulatory frameworks tighten around mental health pharmaceutical interventions.
Market Dynamics
The FDA's Breakthrough Therapy pathway for rapid-acting antidepressants is compressing clinical trial timelines and forcing established psychiatric protocols to accommodate intranasal and parenteral administration formats within emergency department workflows.
Growth Catalysts
- Esketamine nasal spray protocols:Emergency psychiatric services in the United States are integrating dissociative anesthetic protocols for acute suicidal ideation, creating new reimbursement categories for crisis intervention.
- Federal parity mandates:The Mental Health Parity and Addiction Equity Act compels commercial insurers to cover specialty psychiatric pharmaceuticals at equivalent rates to medical-surgical benefits.
- Integrated care networks:Accountable care organizations are embedding psychiatric pharmacists into primary care workflows, expanding prescriptive authority for mood stabilizers and atypical antipsychotics.
Market Restraints
- Ketamine supply concentration:Active pharmaceutical ingredient production for esketamine concentrates among three contract manufacturers, exposing formularies to single-source disruption risk.
- Specialty pharmacy distribution requirements:Risk Evaluation and Mitigation Strategy mandates for rapid-acting agents restrict dispensing to certified REMS providers, limiting rural access.
- Tricyclic antidepressant substitution:Generic amitriptyline and nortriptyline retain formulary presence in resource-constrained settings despite inferior safety profiles.
Strategic Opportunities
- Brazilian psychiatric network expansion:ANVISA's accelerated review pathway for CNS therapeutics enables first-mover positioning in Latin America's largest behavioral health market.
- Telepsychiatry-enabled prescribing:Remote psychiatric consultation platforms are creating direct-to-patient channels for maintenance antidepressant therapy outside traditional hospital formularies.
- Digital therapeutic adjacency:FDA-cleared prescription digital therapeutics for major depressive disorder are creating combination therapy protocols that pair pharmacologic and algorithmic interventions.
Industry Challenges
- Psychiatric pharmacogenomics integration:CYP2D6 and CYP2C19 metabolic profiling requires specialized laboratory partnerships that most community mental health centers lack.
- REMS compliance infrastructure:Certified healthcare settings must maintain dedicated adverse event reporting systems and prescriber training modules that strain administrative bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Suicide Drugs Market |
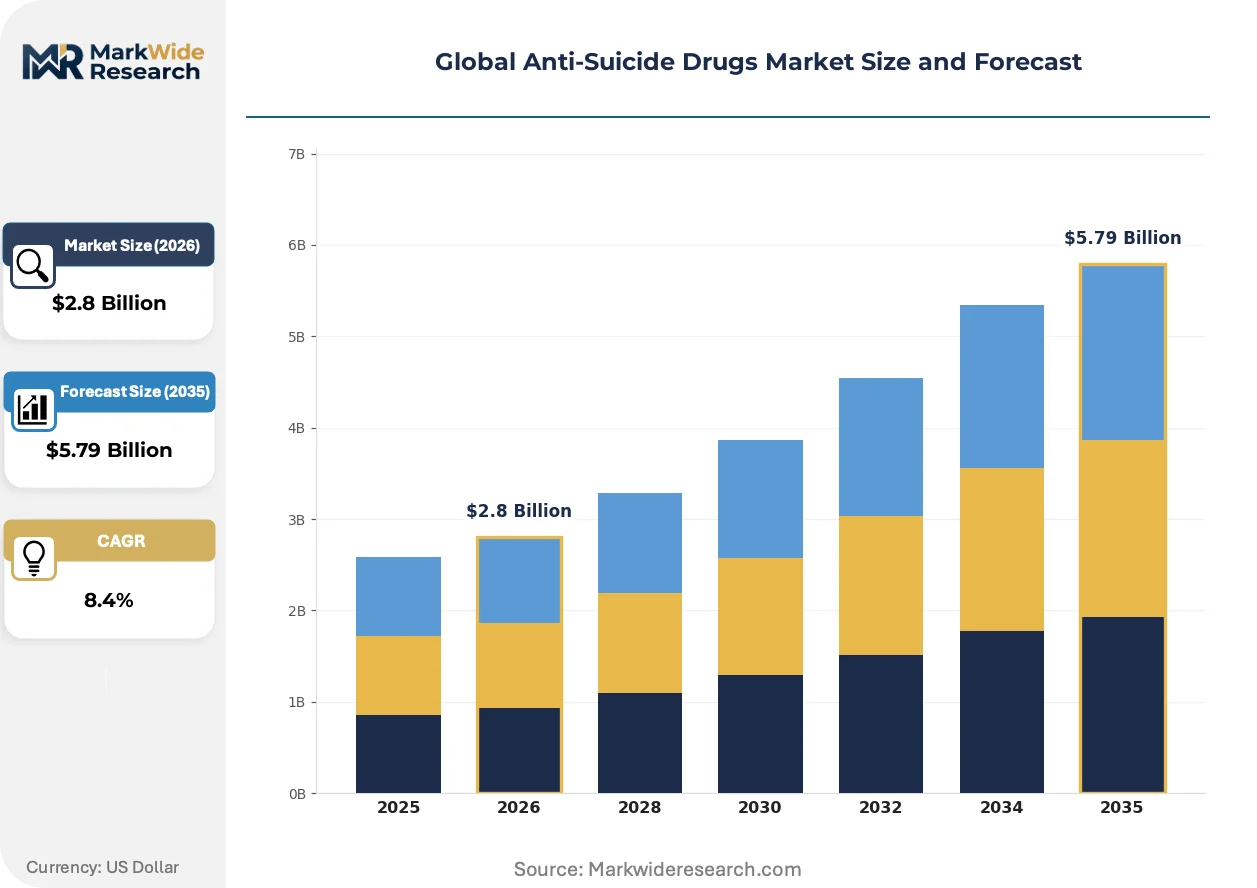
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Selective Serotonin Reuptake Inhibitors, Tricyclic Antidepressants, Monoamine Oxidase Inhibitors, Atypical Antipsychotics, Mood Stabilizers Therapy Area: Major Depressive Disorder, Bipolar Disorder, Post-Traumatic Stress Disorder, Borderline Personality Disorder, Schizoaffective Disorder End User: Psychiatric Clinics, Rehabilitation Centers, Mental Health Hospitals, Outpatient Facilities, Private Practices Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Healthcare Providers, Specialty Pharmacies |
| Companies Covered | Pfizer Inc., AstraZeneca plc, Eli Lilly and Company, Johnson & Johnson, GlaxoSmithKline plc, Merck & Co., Inc., H. Lundbeck A/S, Allergan plc, NeuroRx Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Suicide Drugs Market Shifts & Advancements
Neuropharmacology is pivoting toward glutamatergic modulation mechanisms that bypass the delayed onset limitations of monoaminergic antidepressants, with formulation innovation concentrating on bioavailability optimization and route-of-administration diversification.
Ketamine-derived rapid-acting antidepressants are supplanting extended-release oral formulations in emergency psychiatric settings. Hospital-based crisis intervention teams are adopting intranasal delivery protocols for patients presenting with acute suicidal ideation. The structural consequence is a compression of the traditional 4-6 week therapeutic onset window to hours, enabling same-day discharge protocols that reshape inpatient psychiatric capacity planning.
EMA's centralized authorization process for orphan psychiatric indications is harmonizing market access requirements across German, French, and Italian psychiatric networks. The industrial consequence is reduced regulatory fragmentation for novel CNS therapeutics seeking European commercialization. Treatment-resistant depression indications are attracting conditional marketing authorizations that mandate post-authorization outcome studies.
Specialty pharmacy carve-outs are displacing traditional wholesale distribution for high-touch psychiatric medications. Payers are mandating limited distribution networks that integrate adherence monitoring and adverse event surveillance. This channel consolidation is most visible in United States commercial insurance markets where pharmacy benefit managers are creating exclusive formulary tiers for REMS-restricted agents.
Global Anti-Suicide Drugs Market Segmentation
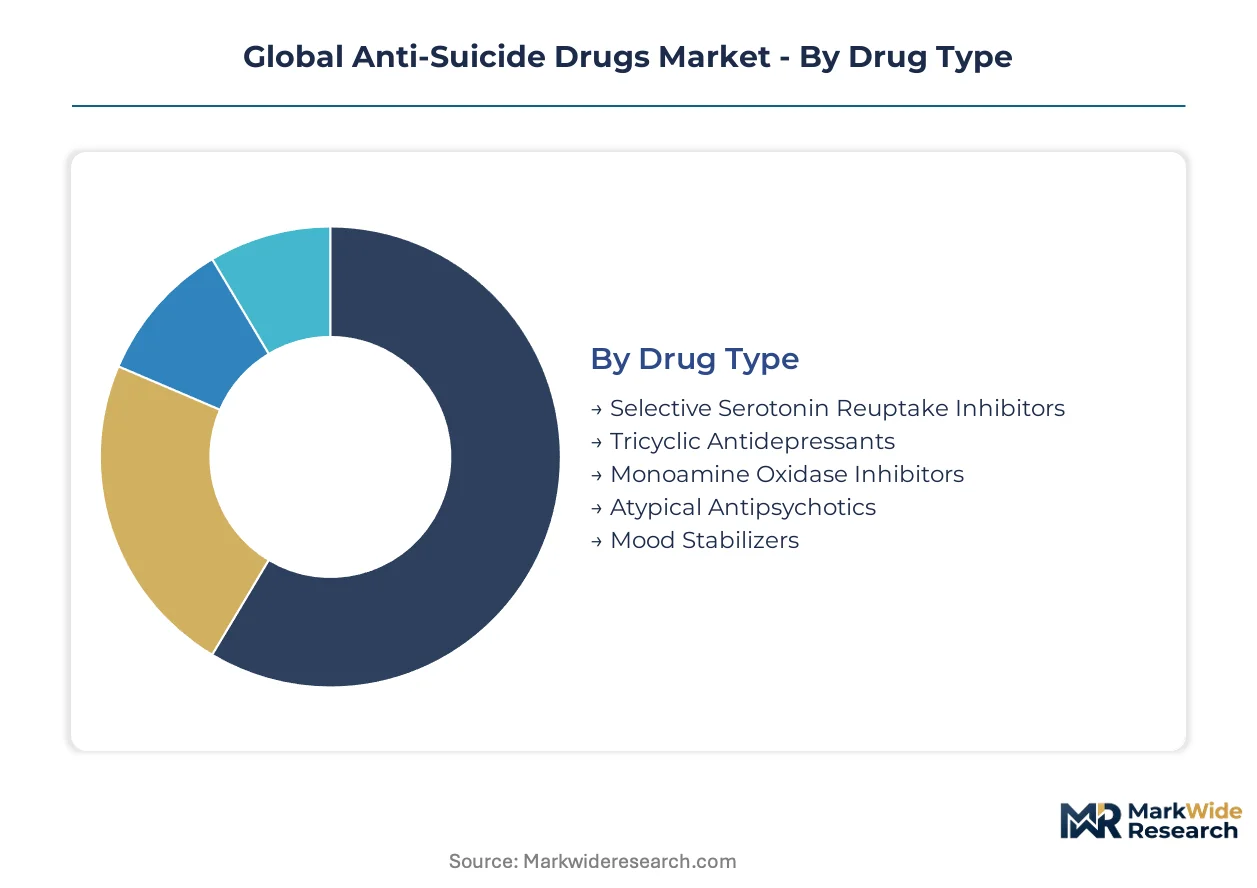
Segmentation in anti-suicide pharmacology reveals distinct margin architectures across mechanism classes, therapeutic indications, and care delivery settings. Each dimension carries unique regulatory, reimbursement, and clinical workflow implications that reshape competitive positioning.
Drug Type:
Margin concentration follows speed-to-efficacy profiles and REMS complexity, with rapid-acting agents commanding premium reimbursement despite restricted distribution.
- Selective Serotonin Reuptake Inhibitors:First-line oral formulations with extensive generic penetration and decades of FDA safety data. Demand concentrates in outpatient facilities across the United States where federal parity mandates guarantee reimbursement, though prescriptive volume faces erosion from newer mechanisms.
- Atypical Antipsheticals:Intramuscular and oral formulations engineered for acute behavioral stabilization in emergency psychiatric settings. Mental health hospitals in Germany and France are expanding formulary access for crisis intervention protocols where rapid sedation prevents inpatient admission.
- Tricyclic Antidepressants:Legacy oral compounds with established cardiovascular toxicity profiles limiting use to treatment-resistant cases.
- Monoamine Oxidase Inhibitors:Restricted to specialist psychiatric settings due to dietary interaction requirements and hypertensive crisis risk.
- Mood Stabilizers:Lithium and anticonvulsant derivatives anchoring bipolar disorder maintenance protocols with narrow therapeutic windows requiring serum monitoring.
The dominant share belongs to Selective Serotonin Reuptake Inhibitors, while Atypical Antipsychotics is closing the gap fastest.
Therapy Area:
Revenue pools align with diagnostic prevalence and chronicity, with treatment-resistant subpopulations driving specialty pharmaceutical uptake.
- Major Depressive Disorder:The largest addressable population with established SSRI protocols now disrupted by ketamine-derived rapid-acting alternatives. Psychiatric clinics in Japan and Australia are piloting intranasal esketamine for patients failing two or more oral antidepressant trials.
- Bipolar Disorder:Chronic cycling condition requiring lifelong mood stabilization with lithium retaining gold-standard status despite toxicity monitoring burdens. Rehabilitation centers in the United Kingdom are integrating pharmacogenomic testing to optimize valproate and lamotrigine selection.
- Post-Traumatic Stress Disorder:Emerging indication for psychedelic-assisted therapies with MDMA-assisted psychotherapy advancing through FDA Phase III trials.
- Borderline Personality Disorder:Off-label antipsychotic and mood stabilizer use dominating as no FDA-approved pharmacologic indication exists.
- Schizoaffective Disorder:Complex diagnostic category requiring combined antipsychotic and mood stabilizer protocols with poor treatment adherence.
Major Depressive Disorder captures the deepest revenue pool, though Bipolar Disorder delivers superior per-patient lifetime value through chronic maintenance requirements.
End User:
Procurement authority and reimbursement rates vary sharply across institutional settings, with hospital-based formularies controlling access to high-cost rapid-acting agents.
- Mental Health Hospitals:Inpatient facilities with 24-hour nursing capacity to administer REMS-restricted intravenous and intranasal formulations. Crisis intervention teams in California and Texas are redesigning capacity planning around same-day discharge protocols enabled by rapid-acting antidepressants.
- Psychiatric Clinics:Outpatient settings with prescriptive authority for maintenance oral therapies and monitoring infrastructure for long-acting injectables. Accountable care organizations in Massachusetts are embedding psychiatric pharmacists to expand prescriptive authority.
- Rehabilitation Centers:Substance use disorder facilities with growing dual-diagnosis populations requiring integrated mood stabilization.
- Outpatient Facilities:Community mental health centers serving Medicaid populations with formulary constraints favoring generic oral agents.
- Private Practices:Solo and group psychiatric practices with direct patient relationships but limited infrastructure for REMS compliance.
Mental Health Hospitals dominate high-value acute intervention, while Psychiatric Clinics are expanding fastest through integrated care network contracts.
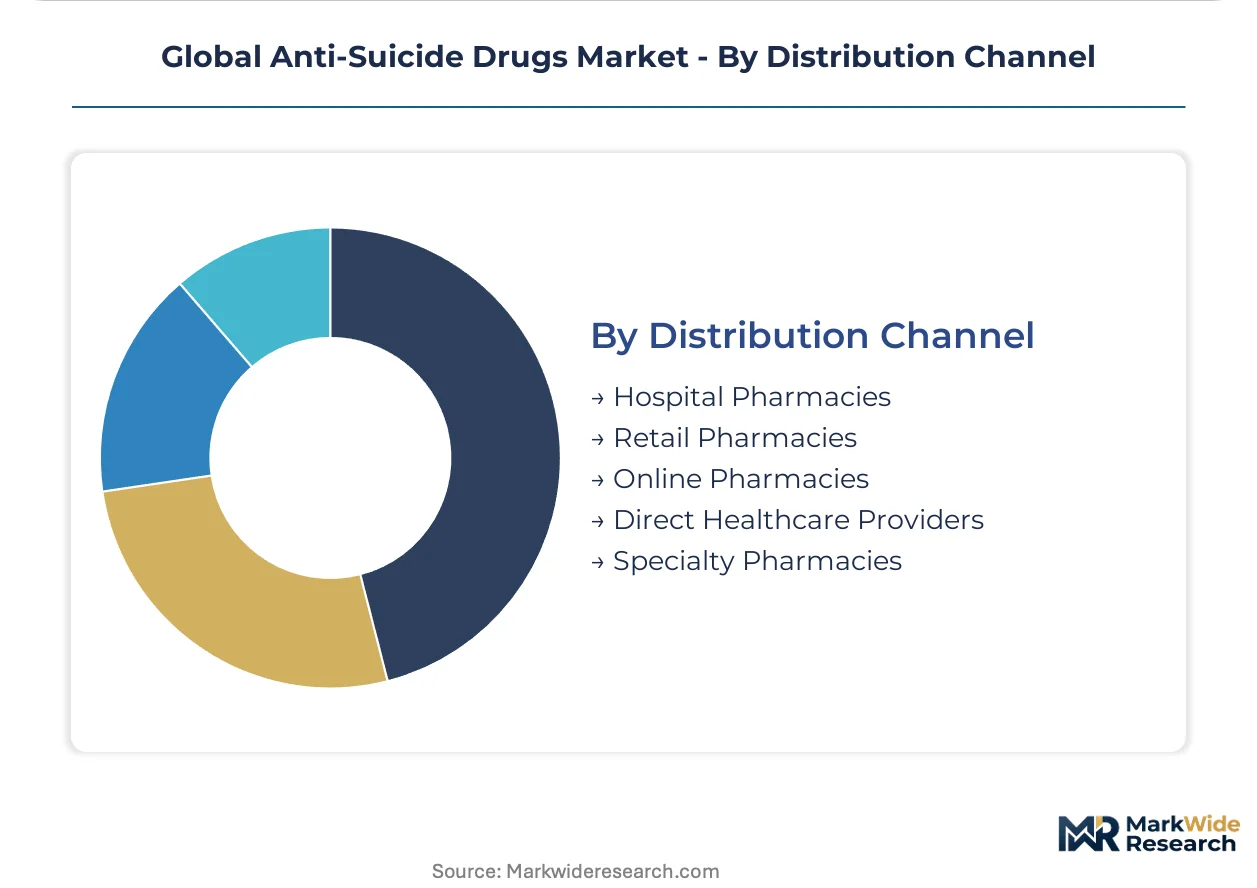
Distribution Channel:
Channel economics reflect handling complexity, with limited distribution networks capturing specialty pharmaceutical margin through adherence monitoring integration.
- Specialty Pharmacies:REMS-certified dispensing with mandatory adverse event reporting and prescriber training verification. CVS Specialty and Accredo dominate United States commercial insurance carve-outs for esketamine and similar restricted agents.
- Hospital Pharmacies:Captive inpatient dispensing with 340B pricing advantages for eligible mental health hospitals serving underserved populations.
- Retail Pharmacies:Mass-market oral generic dispensing with thin margins and high volume throughput.
- Online Pharmacies:Telepsychiatry-enabled direct-to-patient delivery expanding fastest in states with relaxed prescribing regulations.
- Direct Healthcare Providers:In-office dispensing permitted in select jurisdictions for long-acting injectables.
Specialty Pharmacies command the steepest expansion trajectory, while Hospital Pharmacies retain the largest institutional volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production for esketamine concentrates among three contract manufacturers, exposing formularies to single-source disruption risk. The United States, Germany, and Japan anchor commercial deployment through distinct regulatory pathways for rapid-acting antidepressants. Brazil and Australia represent emerging expansion vectors with accelerated review mechanisms for CNS therapeutics.
United States
Emergency psychiatric services integrate dissociative anesthetic protocols for acute suicidal ideation, creating new reimbursement categories for crisis intervention. The FDA's Breakthrough Therapy designation pathway accelerates market access for novel anti-suicidal agents. California and Texas mental health hospitals redesign capacity planning around same-day discharge protocols enabled by rapid-acting antidepressants.
Germany
Mental health hospitals expand formulary access for crisis intervention protocols where rapid sedation prevents inpatient admission. The EMA's centralized authorization process shapes commercialization timelines across European psychiatric markets. Bavaria's psychiatric networks concentrate prescriptive authority for intramuscular atypical antipsychotic formulations in emergency settings.
Japan
Psychiatric clinics pilot intranasal esketamine for patients failing two or more oral antidepressant trials. The PMDA reviews novel CNS therapeutics through harmonized standards aligned with ICH guidelines. Tokyo's integrated care networks embed psychiatric pharmacists into primary care workflows to expand prescriptive authority for mood stabilizers.
Brazil
ANVISA's accelerated review pathway for CNS therapeutics enables first-mover positioning in Latin America's largest behavioral health market. Federal parity mandates compel commercial insurers to cover specialty psychiatric pharmaceuticals at equivalent rates to medical-surgical benefits. São Paulo's psychiatric networks concentrate procurement authority for maintenance oral therapies and long-acting injectables.
Australia
Telepsychiatry-enabled prescribing creates direct-to-patient channels for maintenance antidepressant therapy outside traditional hospital formularies. The TGA evaluates prescription digital therapeutics for major depressive disorder through combination therapy protocols. Victoria's accountable care organizations embed psychiatric pharmacists to expand prescriptive authority across outpatient facilities.
Global Anti-Suicide Drugs Market Competitive Landscape
Concentration sits with established neuroscience infrastructure holders and CNS therapeutic specialists competing across distinct geographic networks. Three strategic archetypes define competitive positioning: diversified pharmaceutical conglomerates with established psychiatric formularies, specialized CNS therapeutics companies with regional dominance, and emerging biotech developers pursuing rapid-acting mechanisms. M&A activity targets REMS-certified distribution capabilities, while portfolio diversification concentrates on glutamatergic modulation platforms.
Within the diversified pharmaceutical tier, Pfizer Inc. and Johnson & Johnson occupy positions anchored by established neuroscience infrastructure across outpatient facilities. Eli Lilly and Company exemplifies R&D-intensive positioning in novel mechanisms for treatment-resistant depression. H. Lundbeck A/S represents the specialized CNS archetype, competing through geographic dominance across European psychiatric networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca plc |
| Eli Lilly and Company |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| H. Lundbeck A/S |
| Allergan plc |
| NeuroRx Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day inventory buffers for esketamine active pharmaceutical ingredients concentrate pricing power among three contract manufacturers, compressing margins for downstream formularies while elevating REMS-certified specialty pharmacies to gatekeeper status. This lead-time architecture forces mental health hospitals into long-term offtake agreements that lock in administered pricing for rapid-acting antidepressant protocols.
Pricing Analysis
The FDA's Risk Evaluation and Mitigation Strategy dictates the pricing tier structure across the anti-suicide drugs landscape, separating REMS-restricted intranasal and intravenous formulations from unrestricted oral generics. Three-tier pricing stratifies across premium rapid-acting agents, standard oral antidepressants, and economy generic SSRIs, with price differentiation anchored in certification complexity and administration setting. Cost compression in the oral generic tier intensifies as Indian and Chinese API manufacturers expand capacity, while community mental health centers exhibit highest price sensitivity due to Medicaid formulary constraints.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for ketamine-derived APIs sourced from Indian and Chinese contract manufacturers, exposing formularies to inventory disruption. The supply chain draws from concentrated API production in India, China, and the United States, with single-source vulnerability for esketamine isomer separation technology. Distribution runs through REMS-certified specialty pharmacy networks that integrate adherence monitoring, displacing traditional wholesale channels for high-touch psychiatric medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of REMS-certified manufacturing infrastructure and psychiatric pharmacist training pipelines constrains market entry, privileging incumbents with established regulatory relationships and crisis intervention formulary access.
For Market Incumbents: Compound formulary lock-in through exclusive long-term offtake agreements with mental health hospital networks facing capacity redesign pressures. Defend against ketamine supply concentration risk by securing dual-source API contracts with Indian and Chinese manufacturers, while expanding backward integration into isomer separation capabilities to capture margin pools currently retained by contract manufacturers. For New Entrants and Emerging Players: Lead with telepsychiatry-enabled prescribing platforms that bypass traditional REMS infrastructure requirements, targeting private psychiatric practices in states with relaxed remote prescribing regulations. Brazil's ANVISA accelerated review pathway offers the most penetrable geographic entry point, with combination therapy protocols pairing pharmacologic and digital therapeutic interventions providing differentiated go-to-market positioning against established oral antidepressant portfolios. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because REMS compliance infrastructure and psychiatric pharmacist networks compound competitive advantage over multi-year horizons. Acquisition targets should display REMS certification capabilities and established relationships with accountable care organizations embedding psychiatric pharmacists. The signal to watch is FDA Breakthrough Therapy designation velocity for novel glutamatergic mechanisms, indicating inflection points in prescriptive protocol disruption.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Expansion | Unlocks dispensing access for esketamine protocols in emergency psychiatric settings across United States commercial networks. |
| API Manufacturing Scale-Up | Reduces single-source dependency for ketamine isomer production concentrated among Indian and Chinese contract manufacturers. |
| Digital Therapeutic Partnership | Creates combination therapy protocols pairing pharmacologic intervention with FDA-cleared algorithmic depression management tools. |
| Telepsychiatry Platform Integration | Enables direct-to-patient channels bypassing traditional hospital formulary gatekeepers in states with relaxed prescribing regulations. |
| Pharmacogenomic Testing Adjacency | Addresses CYP2D6 metabolic profiling gaps that strain community mental health center laboratory partnerships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, capturing perspectives from drug development executives at established neuroscience portfolios, regulatory affairs leads navigating FDA Breakthrough Therapy pathways, formulary directors at integrated care networks, hospital procurement managers in mental health facilities, and payer access specialists at commercial insurance carriers. Secondary validation drew from FDA filings, EMA centralized authorization records, ClinicalTrials.gov depression indication databases, and formulary restriction databases. Bottom-up patient population modeling triangulated against top-down pharmaceutical revenue estimates to anchor volume and value projections.
Across the analysis window, the forecasting framework segmented by drug mechanism class, therapeutic indication severity, administration route complexity, and regional regulatory cluster to capture reimbursement variation. CAGRs derived from growth rate convergence modeling across patient prevalence trends, prescriptive protocol adoption curves, and pricing trajectory assumptions for generic versus specialty pharmaceutical tiers. Forecast inputs incorporated REMS expansion velocity, federal parity mandate enforcement intensity, and crisis intervention same-day discharge protocol penetration.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough designation momentum, stable ketamine API trade flows, or intact commercial insurance parity enforcement would require recalibration. Forecasts reflect documented assumptions regarding prescriptive authority expansion and specialty pharmacy channel consolidation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Controlled Release Drug Delivery Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Germany Opioids Market