
 Latin America Generic Injectables Market | 2026-2036
Latin America Generic Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Generic Injectables Market Intelligence
Aftermarket technical support and cold-chain logistics revenue is tilting from originators toward generic injectable manufacturers across Latin America. Fresenius Kabi leverages its regional manufacturing footprint to sustain contract fill-finish operations for multiple buyers. Laboratorio Elea anchors Argentine oncology injectable supply through backward integration into active pharmaceutical ingredient sourcing. Teva Pharmaceutical Industries Ltd. competes on penicillin and cephalosporin vial volumes in Mexican institutional tenders.
Generic injectables are sterile liquid or lyophilized drug products administered parenterally, requiring aseptic manufacturing under ISO 5 cleanroom conditions with endotoxin limits typically below 0.5 EU per kilogram. Their primary purpose is to deliver critical therapies—antibiotics, cytotoxics, biologics—when oral bioavailability is inadequate or patient consciousness is compromised. Pre-filled syringes command premium positioning due to dosing accuracy and reduced medication errors in hospital settings, while multi-dose vials retain cost advantages in high-volume antibiotic administration. Intravenous delivery dominates therapy area value pools, particularly in oncology where infusion protocols require precise rate-controlled administration.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce GMP inspections and bioequivalence standards that determine market access timelines for imported and locally manufactured injectables. These regulators are harmonizing pharmacovigilance reporting requirements, which elevates compliance costs for smaller manufacturers while creating barriers to informal product entry. Stakeholders must monitor evolving serialization mandates and temperature excursion protocols as regional integration deepens.
Market Dynamics
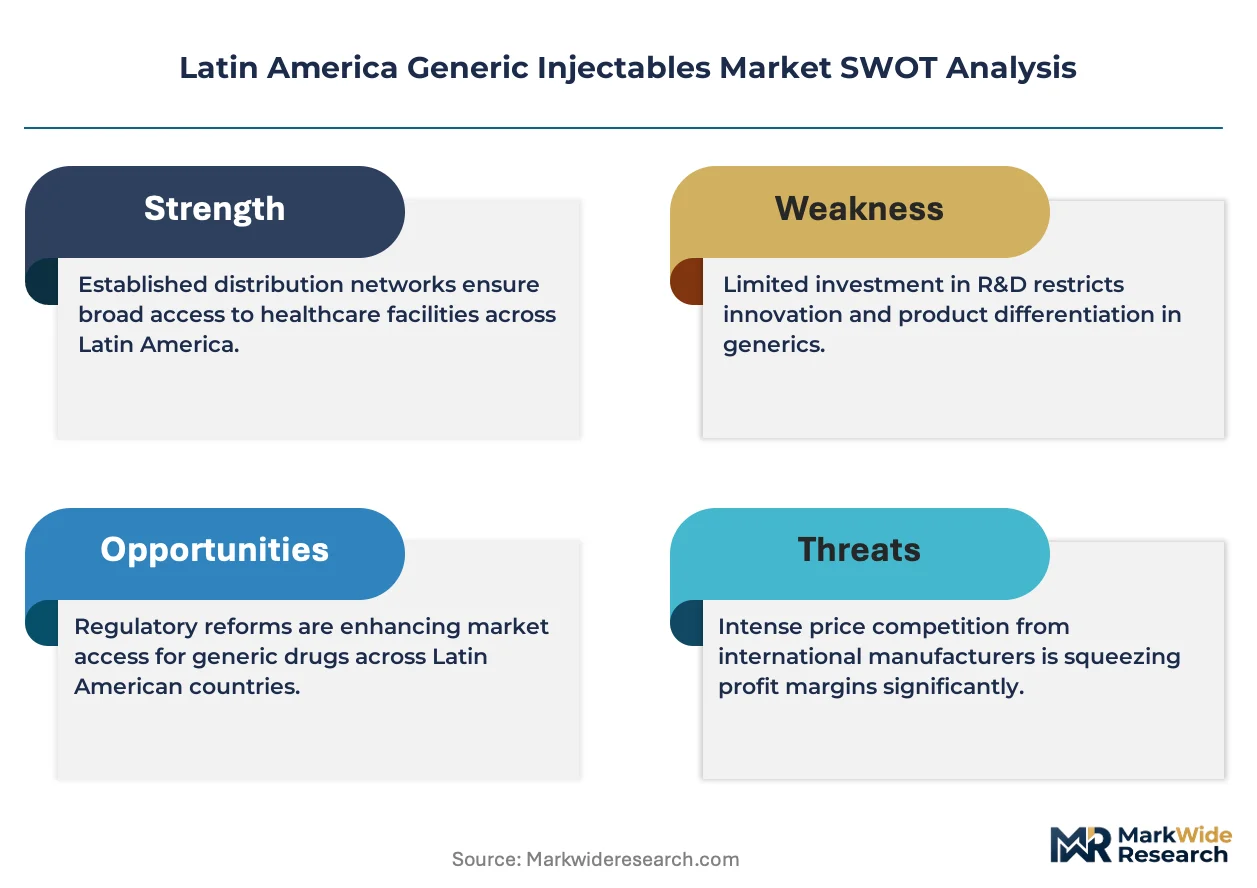
Brazil's PLI-style pharmaceutical incentives and ANVISA's compressed bioequivalence timelines are redrawing competitive entry barriers, pulling manufacturing investment toward São Paulo and compressing hospital procurement cycles for oncology and antibiotic injectables.
Growth Catalysts
- ANVISA's streamlined bioequivalence pathway:Brazil's updated guidelines for complex generics reduce approval timelines for imported sterile injectables, accelerating market entry for manufacturers with existing FDA or EMA dossiers.
- Hospital network consolidation:Brazilian public hospital procurement centralization under SUS is aggregating demand for high-volume antibiotic vials, creating scale incentives for local fill-finish investments.
- Lyophilization technology adoption:Mexican and Argentine manufacturers are deploying advanced lyophilization to extend shelf stability of temperature-sensitive oncology injectables, reducing cold-chain dependency.
Market Restraints
- API import concentration:Latin American generic injectable manufacturers remain dependent on Chinese and Indian active pharmaceutical ingredient suppliers, exposing margins to freight cost volatility and customs delays.
- COFEPRIS inspection backlog:Mexico's national pharmaceutical regulator maintains extended GMP inspection queues for foreign manufacturing sites, stretching approval timelines for new market entrants.
- Biologic substitution limits:Biosimilar injectables face restricted interchangeability protocols in Argentine hospital formularies, capping volume expansion despite price advantages over originator molecules.
Strategic Opportunities
- Colombian institutional expansion:INVIMA's harmonization with ICH Q7 standards is opening procurement access for regional manufacturers to supply Colombia's EPS hospital networks.
- Pre-filled syringe penetration:Mexican social security institutions are transitioning from multi-dose vials to single-use pre-filled formats for insulin and anticoagulant administration, creating premium positioning openings.
- Serialization mandate compliance:Brazil's ANVISA track-and-trace requirements for sterile injectables are forcing technology upgrades that favor manufacturers with integrated packaging-automation capabilities.
Industry Challenges
- Aseptic operator certification scarcity:ISO 5 cleanroom-qualified technicians are concentrated in São Paulo and Mexico City, constraining manufacturing scale-up in secondary Brazilian states and Argentine provinces.
- Endotoxin testing capacity bottlenecks:Regional contract laboratories face LAL reagent supply constraints, delaying batch release for lyophilized oncology products.
- Legacy ERP integration friction:Hospital procurement systems in Argentina's public sector require manual bridging with manufacturer serialization databases, complicating order fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Generic Injectables Market |
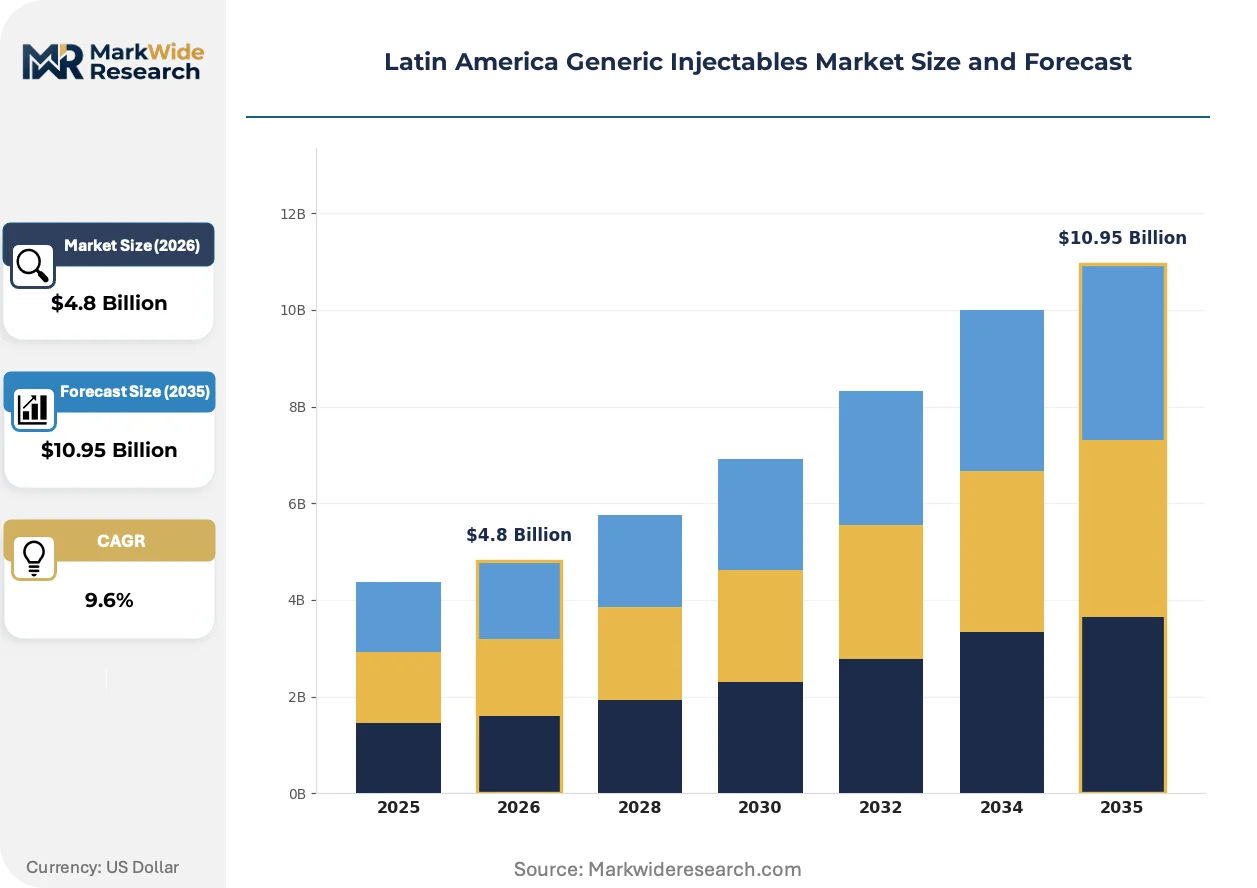
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose Vials, Multi Dose Vials, Pre-filled Syringes, Injectable Solutions End User: Hospitals, Clinics, Long-term Care Facilities, Home Healthcare Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Intradermal Therapy Area: Oncology, Cardiovascular, Endocrinology, Antibiotics |
| Companies Covered | Fresenius Kabi, Laboratorio Elea, Viatris Inc., Teva Pharmaceutical Industries Ltd., Sandoz, Hikma Pharmaceuticals PLC, Pfizer Inc., Aurobindo Pharma Limited, Eurofarma, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Generic Injectables Market Strategic Shifts & Innovations
Manufacturing automation and regulatory harmonization are compressing production economics while reshaping how sterile injectables reach institutional buyers across Latin American hospital networks.
Isolator-based aseptic processing is migrating from legacy open cleanroom configurations to closed restricted access barrier systems in Brazilian and Mexican manufacturing facilities. Hospital procurement officers in São Paulo and Mexico City are prioritizing suppliers with isolator-certified lines for high-risk cytotoxic preparations. This technology transition is compressing contamination risk profiles while elevating capital barriers for new market entrants.
ANVISA's adoption of ICH Q12 lifecycle management guidelines is enabling post-approval manufacturing changes without full resubmission for Brazilian-registered injectables. This regulatory convergence reduces compliance burden for manufacturers maintaining dual FDA-ANVISA dossiers. Oncology and biologic injectable portfolios see the greatest benefit, with firms accelerating process optimization cycles.
Consignment inventory arrangements are displacing traditional purchase-order models in Mexican IMSS and ISSSTE hospital networks. Generic injectable manufacturers now maintain buffer stock at regional distribution centers, transferring ownership only upon patient administration. This demand pattern shift concentrates working capital requirements on suppliers while compressing stockout risk for public oncology wards.
Latin America Generic Injectables Market Segmentation
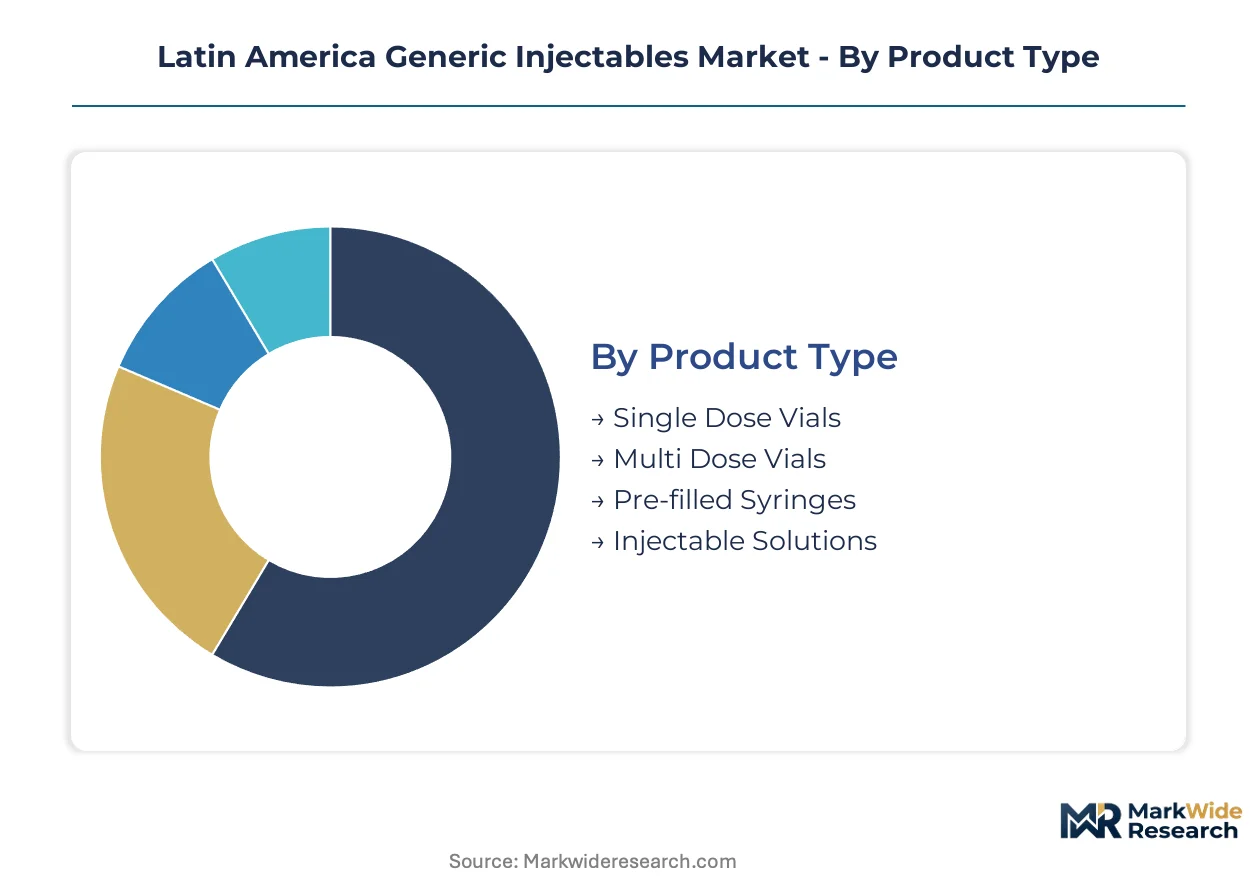
Segmentation in Latin American generic injectables reveals how packaging format, care setting, and therapy urgency drive divergent manufacturing economics and procurement cycles. Each dimension exposes distinct margin pressures and regulatory compliance burdens that reshape competitive positioning across Brazilian, Mexican, and Argentine markets.
Product Type:
Cycle times vary dramatically across packaging formats, with pre-filled syringes turning inventory fastest due to institutional safety mandates while multi-dose vials sit longest in antibiotic stockpiles.
- Single Dose Vials:Sterile glass or polymer containers sealed with elastomeric stoppers, designed for one-time withdrawal to eliminate cross-contamination risk. Brazilian SUS hospital networks concentrate procurement for oncology cytotoxics where dosing precision and waste reduction override unit cost considerations.
- Multi Dose Vials:Larger-volume containers incorporating antimicrobial preservatives enabling multiple withdrawals over 28-day stability windows. Argentine public hospitals aggregate demand for high-volume penicillin and cephalosporin administration, though preservative compatibility constraints limit application in renal-compromised patient populations.
- Pre-filled Syringes:Ready-to-administer units with integrated needles or Luer locks, reducing medication errors and preparation time in emergency settings.
- Injectable Solutions:Sterile liquid formulations in ampoules or bags for immediate infusion, dominating antibiotic and fluid replacement therapy across Mexican IMSS facilities.
Multi-dose vials anchor the volume base while pre-filled syringes gain share at the steepest rate.
End User:
Cost tiers stratify sharply across care settings, with acute hospital procurement commanding premium pricing for aseptic assurance while home healthcare operates on compressed margins.
- Hospitals:Tertiary and secondary acute care institutions with centralized pharmacy compounding and infection control protocols. Brazilian public hospital networks and Mexican social security institutions drive concentrated demand for oncology and antibiotic injectables, with ANVISA and COFEPRIS GMP inspections determining supplier eligibility.
- Clinics:Ambulatory surgical and specialty infusion centers with limited on-site sterilization capacity. Mexican metropolitan clinic chains are expanding chemotherapy administration capabilities, creating pull-through demand for portable cytotoxic preparation systems.
- Long-term Care Facilities:Extended-stay institutions managing chronic parenteral nutrition and antibiotic therapy.
- Home Healthcare:Patient-directed administration with family caregiver training requirements.
Hospitals capture the dominant value pool while home healthcare climbs the fastest as infusion therapy migrates beyond institutional walls.
Delivery Mode:
Application urgency divides routes by therapeutic intensity, with intravenous dominating life-sustaining therapies and subcutaneous expanding in chronic self-administration.
- Subcutaneous:Depot formulations and biologic injections delivered into adipose tissue with slower absorption kinetics. Mexican diabetes management programs are transitioning insulin delivery from vial-and-syringe to pen systems, though generic injectable manufacturers face device patent barriers.
- Intravenous:Direct vascular administration enabling immediate bioavailability and precise titration. Brazilian oncology wards and Argentine hematology centers concentrate demand for rate-controlled infusion of cytotoxics and supportive care molecules.
- Intramuscular:Deep tissue deposition for sustained-release antibiotics and vaccine adjuvants.
- Intradermal:Superficial dermal layer targeting for diagnostic testing and certain immunizations.
Intravenous delivery holds the volume anchor while subcutaneous administration expands most quickly through biologic and anticoagulant adoption.
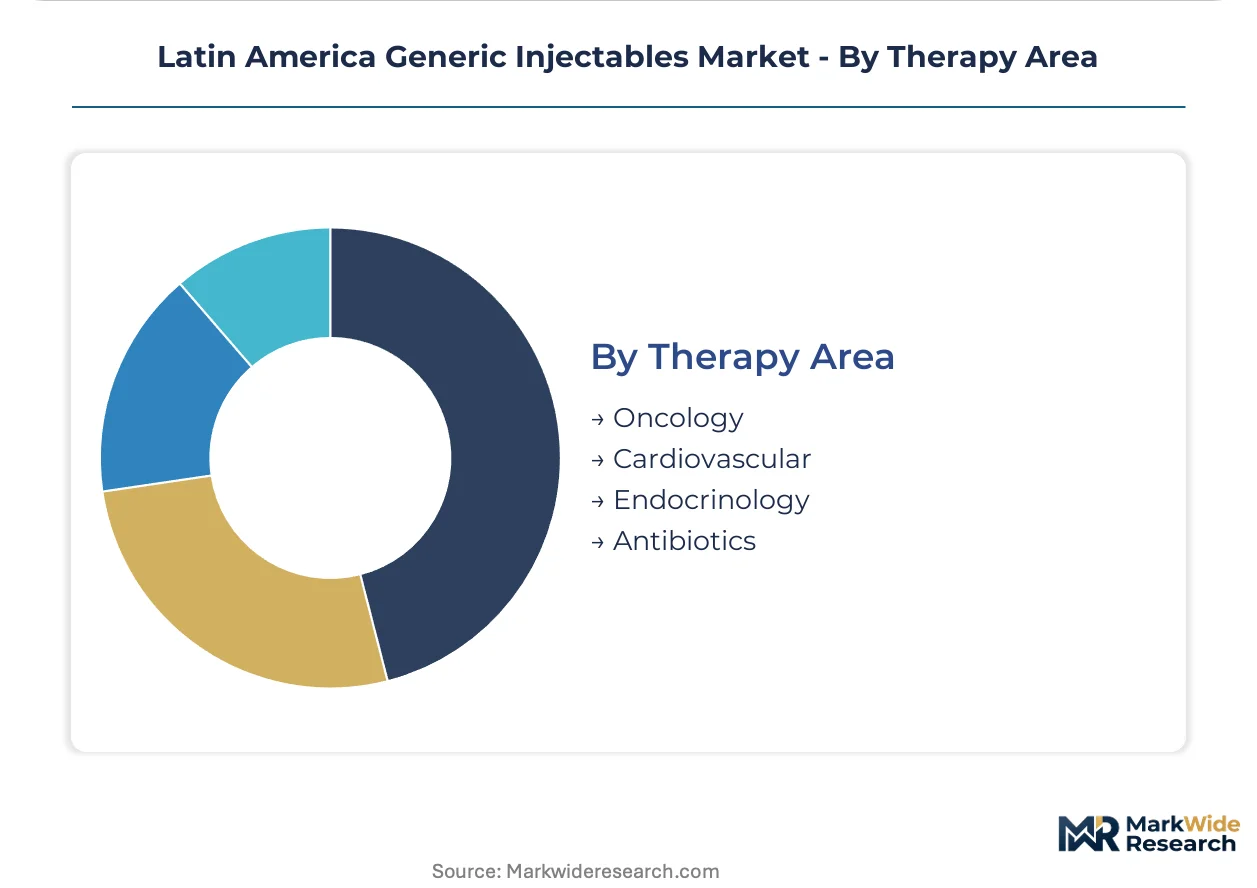
Therapy Area:
Supply concentration clusters around oncology and antibiotics, where manufacturing complexity and procurement scale create divergent margin structures.
- Oncology:Cytotoxic and supportive care injectables requiring isolator-based aseptic processing and dedicated containment facilities. Brazilian hospital networks and Argentine cancer institutes concentrate demand, with lyophilization technology investments reducing cold-chain dependency for temperature-sensitive molecules.
- Cardiovascular:Anticoagulants, antiarrhythmics, and emergency intervention agents for acute coronary and stroke protocols.
- Endocrinology:Insulin analogs and hormone replacement therapies, with Mexican social security institutions driving pre-filled format transition.
- Antibiotics:Broad-spectrum parenteral agents for sepsis and nosocomial infection management. Brazilian SUS centralized procurement aggregates massive volume for generic cephalosporin and carbapenem vials, though API import concentration from Asian suppliers exposes margin volatility.
Antibiotics anchor the volume base while oncology gains share at the steepest rate through hospital network consolidation and biosimilar pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates hospital procurement under centralized SUS networks while Mexico fragments demand across social security institutions; Argentina and Colombia split between public oncology wards and private clinic chains, creating divergent compliance burdens and pricing tiers across the region.
Brazil
São Paulo's hospital networks drive concentrated demand for oncology and antibiotic injectables through SUS procurement aggregation. ANVISA's streamlined bioequivalence pathways for complex generics compress approval timelines for manufacturers with existing FDA dossiers. The São Paulo-Guarulhos industrial corridor anchors regional fill-finish investments from multinational and domestic manufacturers seeking proximity to institutional buyers.
Mexico
IMSS and ISSSTE social security institutions generate institutional volume for pre-filled syringe formats in diabetes and anticoagulant therapy. COFEPRIS maintains extended GMP inspection queues for foreign manufacturing sites, stretching market entry timelines for new entrants. Mexico City metropolitan hospitals and Nuevo León industrial clusters concentrate both demand and aseptic manufacturing capacity.
Argentina
Public cancer institutes and hematology centers concentrate demand for lyophilized oncology injectables requiring cold-chain stability. Laboratorio Elea's backward integration into API sourcing anchors domestic supply security for cytotoxic therapies. Buenos Aires province hosts the dominant share of aseptic manufacturing infrastructure, with secondary capacity emerging in Córdoba.
Colombia
EPS hospital networks are expanding procurement access for regional manufacturers as INVIMA harmonizes with ICH Q7 standards. The regulator's GMP alignment creates entry pathways for Brazilian and Mexican suppliers previously excluded by divergent compliance requirements. Bogotá's tertiary hospital clusters concentrate demand for high-value sterile injectables.
Chile
Private clinic chains and public hospital networks split demand for emergency antibiotic and cardiovascular injectables. The national pharmaceutical regulator enforces serialization and temperature excursion protocols that elevate compliance costs for smaller regional suppliers. Santiago's metropolitan health system anchors procurement volume with secondary demand concentration in Valparaíso.
Latin America Generic Injectables Market Key Industry Players
Capability concentration sits with specialized aseptic manufacturers; scale advantage sits with diversified pharmaceutical conglomerates. The market structures around three tiers: multinational injectable specialists with regional manufacturing footprints, domestic champions with backward API integration, and contract fill-finish operators serving institutional tenders. Strategic moves center on isolator technology licensing for cytotoxic capacity and consignment inventory arrangements with public hospital networks.
Among multinational injectable specialists, Fresenius Kabi and Teva Pharmaceutical Industries Ltd. occupy positions defined by regional manufacturing scale and institutional tender participation. Laboratorio Elea anchors the domestic champion tier through captive API supply and oncology portfolio concentration. These three exemplify divergent strategic postures: technology-led capacity expansion, volume-driven antibiotic positioning, and vertical integration into upstream pharmaceutical ingredients.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Laboratorio Elea |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sandoz |
| Hikma Pharmaceuticals PLC |
| Pfizer Inc. |
| Aurobindo Pharma Limited |
| Eurofarma |
| Others |
Cost & Logistics Intelligence
São Paulo's industrial corridor concentrates aseptic fill-finish capacity for Brazilian hospital networks, granting manufacturers with local isolator-certified lines leverage in SUS oncology tender negotiations while compressing margins for API-dependent importers facing freight volatility.
Pricing Analysis
Long-term offtake contracts with Brazilian SUS and Mexican IMSS anchor volume commitments for antibiotic vials and oncology injectables, though spot procurement for temperature-sensitive biologics commands premiums during cold-chain disruptions. Price differentiation hinges on ANVISA GMP certification tier and isolator technology deployment, with isolator-certified manufacturers capturing premium positioning over open-cleanroom competitors. Pricing pressure stems from Chinese API cost volatility feeding into cephalosporin and carbapenem production. Public hospital procurement officers exhibit highest price sensitivity, while private oncology clinics prioritize supply assurance over unit cost.
Supply Chain Analysis
Export-control regimes on advanced lyophilization equipment from European and US suppliers constrain Argentine and Colombian manufacturers seeking to reduce cold-chain dependency for temperature-sensitive cytotoxics. Active pharmaceutical ingredient supply draws from India and China, with endotoxin-free grades and sterile crystalline forms feeding Brazilian and Mexican fill-finish operations. Single-source vulnerability concentrates in LAL reagent supply for batch release testing, with regional contract laboratories facing extended lead times. Distribution runs through consignment inventory arrangements at regional distribution centers serving IMSS and ISSSTE networks, transferring ownership upon patient administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American generic injectables sit in early-cycle expansion as ANVISA's ICH Q12 adoption accelerates post-approval manufacturing optimization for oncology and biologic portfolios, compressing compliance burdens for dual-dossier holders.
For Market Incumbents: Pre-empt API supply disruption by securing captive sourcing agreements for high-potency oncology actives or qualifying secondary Indian suppliers for cephalosporin intermediates. Invest in isolator technology licensing for cytotoxic capacity expansion in São Paulo to defend SUS tender positioning against Mexican competitors with COFEPRIS backlog advantages. For New Entrants and Emerging Players: Pursue Colombian EPS network access as INVIMA's ICH Q7 harmonization opens procurement pathways previously blocked by divergent standards. Target lyophilized oncology injectables for Argentine public cancer institutes where Laboratorio Elea's domestic API integration leaves gaps in supportive care molecules. Lead with consignment inventory capabilities to differentiate from legacy purchase-order suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital network procurement centralization under SUS and IMSS favors scaled manufacturers with integrated serialization and cold-chain infrastructure. Acquisition candidates include mid-cap Brazilian fill-finish operators with ANVISA-approved isolator lines and underutilized lyophilization capacity. The signal to watch is COFEPRIS inspection queue clearance rates for foreign sites, which would unlock Mexican market entry for regional challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Licensing | ANVISA-certified isolator lines unlock SUS cytotoxic procurement eligibility for high-value oncology tenders. |
| Backward API Integration | Captive sourcing of high-potency actives insulates margins from Indian and Chinese supplier volatility. |
| Consignment Inventory Arrangements | Buffer stock at IMSS regional centers transfers ownership upon administration, compressing stockout risk. |
| ICH Q12 Lifecycle Adoption | Post-approval manufacturing changes without full resubmission accelerate process optimization cycles for biologics. |
| Serialization Infrastructure Upgrade | Integrated packaging-automation capabilities satisfy Brazil's ANVISA track-and-trace mandates for sterile injectables. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across Brazilian SUS procurement officers, Mexican IMSS formulary directors, Argentine hospital pharmacy managers, ANVISA regulatory affairs leads, and Colombian EPS network administrators. Secondary validation drew from ANVISA bioequivalence filings, COFEPRIS GMP inspection records, INVIMA harmonization guidelines, hospital procurement databases, and customs trade data for API imports. Bottom-up volume estimates by packaging format and therapy area triangulated against top-down market sizing from institutional tender aggregation.
Calibration against historical SUS procurement cycles and IMSS consignment inventory transitions anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, delivery mode, therapy area, and regional regulatory cluster. CAGRs derived from weighted average of institutional volume growth rates and pricing trajectory assumptions, with specific inputs from lyophilization technology adoption curves and isolator certification penetration by manufacturing facility.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or Argentine import tariff regimes would shift the trajectory for API-dependent manufacturers. Forecasts reflect documented assumptions regarding ANVISA inspection throughput and COFEPRIS queue clearance efficiency. Material shifts in ICH guideline adoption timelines or serialization mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Depression Drugs Market