
 Dental Medication Market | 2026-2036
Dental Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Medication Market Insights
Dental product distribution is fragmenting as e-procurement platforms and direct-to-practice channels erode traditional distributor control. Henry Schein sustains its position through extensive warehouse networks and same-day delivery commitments to metropolitan practices. Dentsply Sirona leverages its integrated equipment-pharmaceutical portfolio to capture bundled purchasing decisions. Septodont specializes in endodontic medicaments and local anesthetics, anchoring its reputation in specialty procedures.
Dental medications comprise pharmacologically active agents formulated for intraoral administration, including amide-based local anesthetics with epinephrine concentrations of 1:100,000 to 1:200,000 for vasoconstriction control and sustained effect duration. These compounds serve to manage perioperative pain, prevent surgical site infection, and support hard-tissue remineralization in clinical dental practice. Analgesics and antibiotics occupy the largest share of product type value, while preventive care applications demonstrate the strongest expansion trajectory as risk-based caries management protocols gain protocol adoption. Injectable delivery modes command premium positioning in oral surgery settings, whereas rinse formulations compete on volume and reimbursement accessibility.
The FDA oversees local anesthetic safety labeling and adverse event reporting, while the EPA regulates mercury-containing amalgam waste disposal that indirectly shapes antibiotic preference in restorative follow-up care. The EMA's MDR framework in Europe imposes clinical evidence requirements on antimicrobial dental formulations, elevating documentation costs for market entrants. Stakeholders must monitor evolving reimbursement thresholds for preventive pharmacological interventions as payors recalibrate risk-sharing models.
Market Dynamics
Statutory health insurance reimbursement expansion in Germany is compressing preventive fluoride protocol timelines and forcing manufacturers to recalibrate volume forecasting models around public payor cycles rather than private practice purchasing patterns.
Growth Catalysts
- MDR Clinical Evidence Requirements:The EMA's tightened documentation standards for antimicrobial dental formulations are elevating barriers for low-cost entrants and consolidating premium positioning among incumbents with established dossiers.
- Amide-Based Local Anesthetic Innovation:Reformulation efforts targeting epinephrine concentration optimization are extending vasoconstriction control windows in oral surgery settings.
- Metropolitan Same-Day Delivery Infrastructure:Dense warehouse networks in United States dental clusters are compressing formulary replenishment cycles and reducing safety stock requirements.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for lidocaine and articaine base materials clusters in Indian and Chinese chemical manufacturing zones, exposing formulators to export licensing volatility.
- Mercury Amalgam Waste Compliance:EPA disposal regulations for mercury-containing restorative materials are elevating downstream antibiotic preference costs in follow-up care protocols.
- Bioresorbable Barrier Limitations:Collagen membrane degradation rate inconsistency in guided tissue regeneration is constraining predictable outcomes in periodontal medicament adjunct therapy.
Strategic Opportunities
- Risk-Based Caries Management Protocols:Preventive pharmacological intervention reimbursement thresholds are broadening patient access in German statutory health insurance frameworks.
- E-Procurement Platform Penetration:Direct-to-practice digital channels are eroding traditional distributor margins and enabling manufacturer price transparency in United States metropolitan markets.
- Silver Diamine Fluoride Convergence:Arresting agent integration with remineralization chemistry is opening pediatric and geriatric application white spaces where conventional drilling tolerance is limited.
Industry Challenges
- Perioperative Anesthesia Training Gaps:Vasoconstrictor dosing precision in medically compromised patients requires specialized continuing education that general practice residencies inadequately cover.
- Biocompatibility Certification Timelines:ISO 10993 cytotoxicity and sensitization testing for novel rinse formulations extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Medication Market |
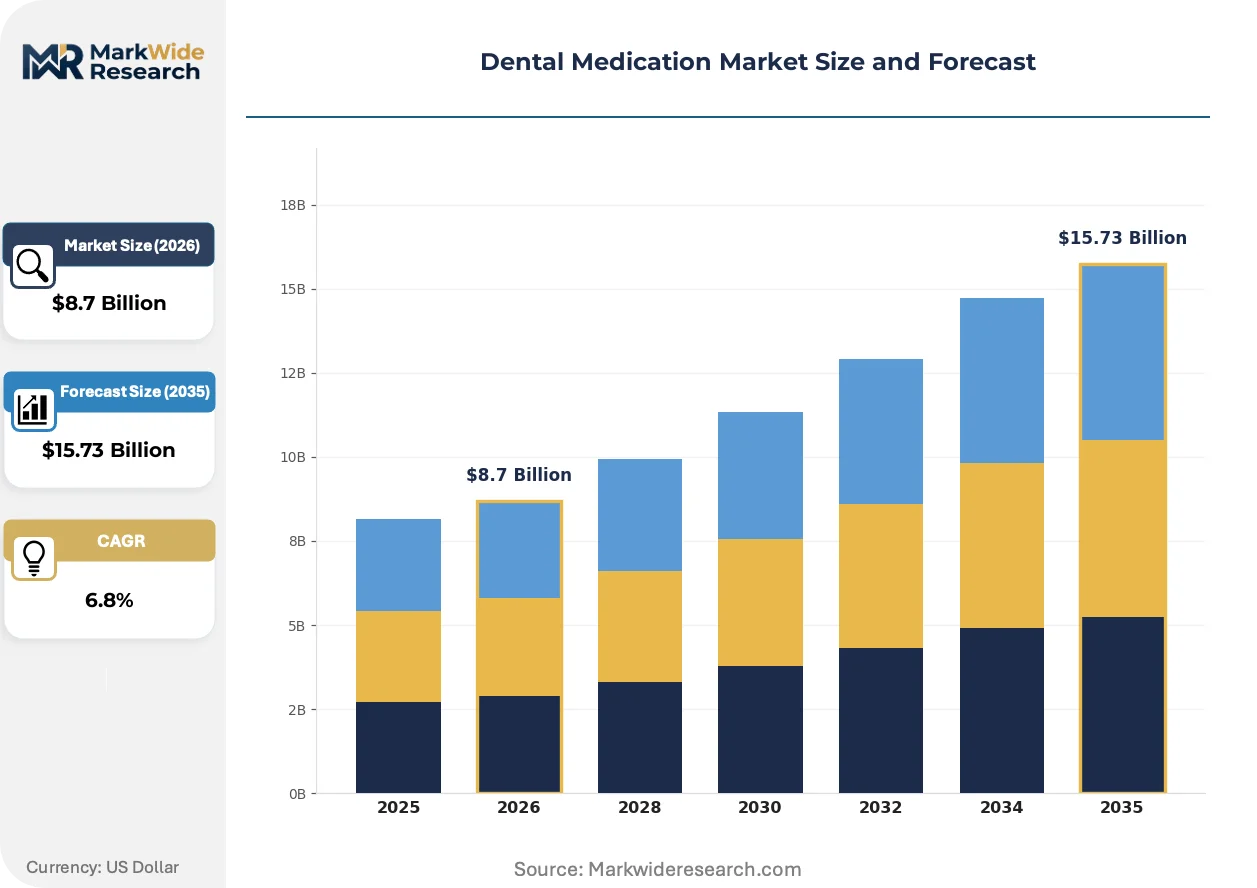
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antibiotics, Antiseptics, Fluoride Application: Oral Surgery, Periodontal Treatment, Preventive Care, Pain Management Delivery Mode: Topical, Injectable, Oral Tablets, Rinse End User: Dentists, Hospitals, Clinics, Consumers |
| Companies Covered | Dentsply Sirona, Henry Schein, 3M Company, Septodont, Ivoclar Vivadent, Institut Straumann, Envista, Patterson Companies, Hikma Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Medication Market Trends and Innovations
Digital procurement infrastructure and regenerative biomaterial science are compressing traditional supply hierarchies while expanding therapeutic boundaries beyond conventional restorative paradigms.
Injectable local anesthetic delivery is migrating from conventional cartridge systems toward computer-controlled flow rate devices. Oral surgery suites in academic medical centers are adopting these platforms to reduce needle deflection and improve aspiration reliability. The technology is migrating from premium positioning toward mid-market penetration as hardware costs decline and training protocols standardize.
REACH substance restriction candidate listing for certain quaternary ammonium compounds is pressuring antimicrobial rinse reformulation across European manufacturing. German and French formulators are accelerating phenolic alternative screening to preempt authorization sunset clauses. The regulatory friction is concentrating R&D expenditure among multinationals with dedicated toxicology dossier teams.
Group purchasing organization consolidation is compressing vendor negotiation cycles and unbundling equipment-pharmaceutical bundles that historically locked practices into single-source relationships. Metropolitan United States dental service organizations are leveraging aggregated volume to extract direct manufacturer pricing. The behavioral shift is most visible in Texas and California markets where DSO penetration exceeds 35% of chair capacity.
Dental Medication Market Segmentation
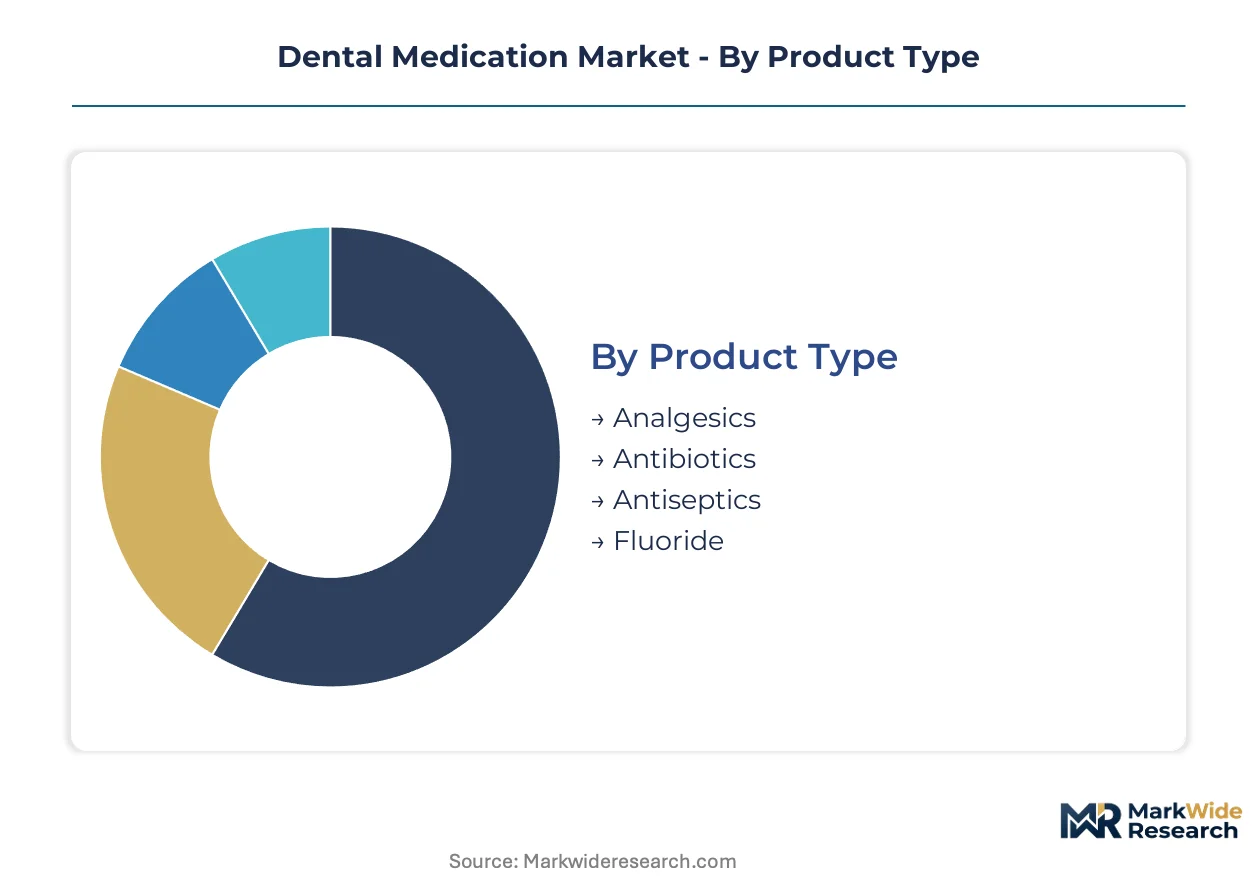
Dental medication procurement cycles vary dramatically across product categories, with acute-care formulations turning over weekly while preventive agents stretch across quarterly reimbursement windows. Understanding these velocity differentials helps manufacturers align inventory models with actual consumption patterns rather than aggregated demand assumptions.
Product Type:
Analgesics and antibiotics turn over fastest due to acute procedural consumption, while fluoride protocols cycle slowly through preventive reimbursement schedules.
- Analgesics:NSAID and acetaminophen combinations dominate perioperative protocols in United States oral surgery suites. Demand clusters around metropolitan dental service organizations where same-day extraction volumes drive bulk purchasing.
- Antibiotics:Amoxicillin-clavulanate and clindamycin formulations serve surgical site infection prophylaxis and post-operative coverage. German statutory health insurance reimbursement for prophylactic protocols is broadening access beyond symptomatic prescribing.
- Antiseptics:Chlorhexidine gluconate rinses and povidone-iodine preparations target biofilm suppression in periodontal maintenance.
- Fluoride:Varnish and gel formulations for remineralization therapy operate on extended procurement cycles tied to pediatric recall intervals.
Analgesics anchor the volume base while fluoride gains share at the steepest rate.
Application:
Cost tiers separate emergency interventions from elective preventive protocols, with surgical applications commanding premium positioning and routine care competing on reimbursement accessibility.
- Oral Surgery:Perioperative anesthesia and hemostatic agents require sterile injectable formats with documented aspiration protocols. Academic medical centers in California and Texas are standardizing computer-controlled delivery platforms to reduce needle deflection incidents.
- Periodontal Treatment:Locally applied antimicrobial gels and sustained-release chips target subgingival biofilm management. Collagen membrane adjuncts face bioresorbability consistency constraints that elevate follow-up antibiotic dependency.
- Preventive Care:Risk-based caries management protocols in German statutory insurance frameworks are compressing fluoride varnish application timelines.
- Pain Management:Topical anesthetic formulations and systemic NSAID protocols bridge acute post-operative windows.
Oral surgery commands the premium tier while preventive care expands most quickly under reimbursement pressure.
Delivery Mode:
Volume concentration favors rinse formulations in high-frequency hygiene applications, whereas injectable formats capture value concentration in surgical settings despite lower unit throughput.
- Injectable:Amide-based local anesthetics with epinephrine concentrations of 1:100,000 to 1:200,000 provide vasoconstriction control for sustained effect duration. FDA safety labeling tightening is driving reformulation investments among United States manufacturers.
- Rinse:Chlorhexidine and essential oil formulations compete on reimbursement tier accessibility in periodontal maintenance protocols. REACH substance restrictions in Europe are pressuring quaternary ammonium compound alternatives.
- Topical:Benzocaine and lidocaine gels serve superficial mucosal anesthesia for minor procedures.
- Oral Tablets:Systemic antibiotics and analgesics follow standard pharmaceutical distribution through pharmacy channels rather than dental-specific procurement.
Rinse formulations anchor the volume base while injectable platforms climb the fastest on technology substitution.
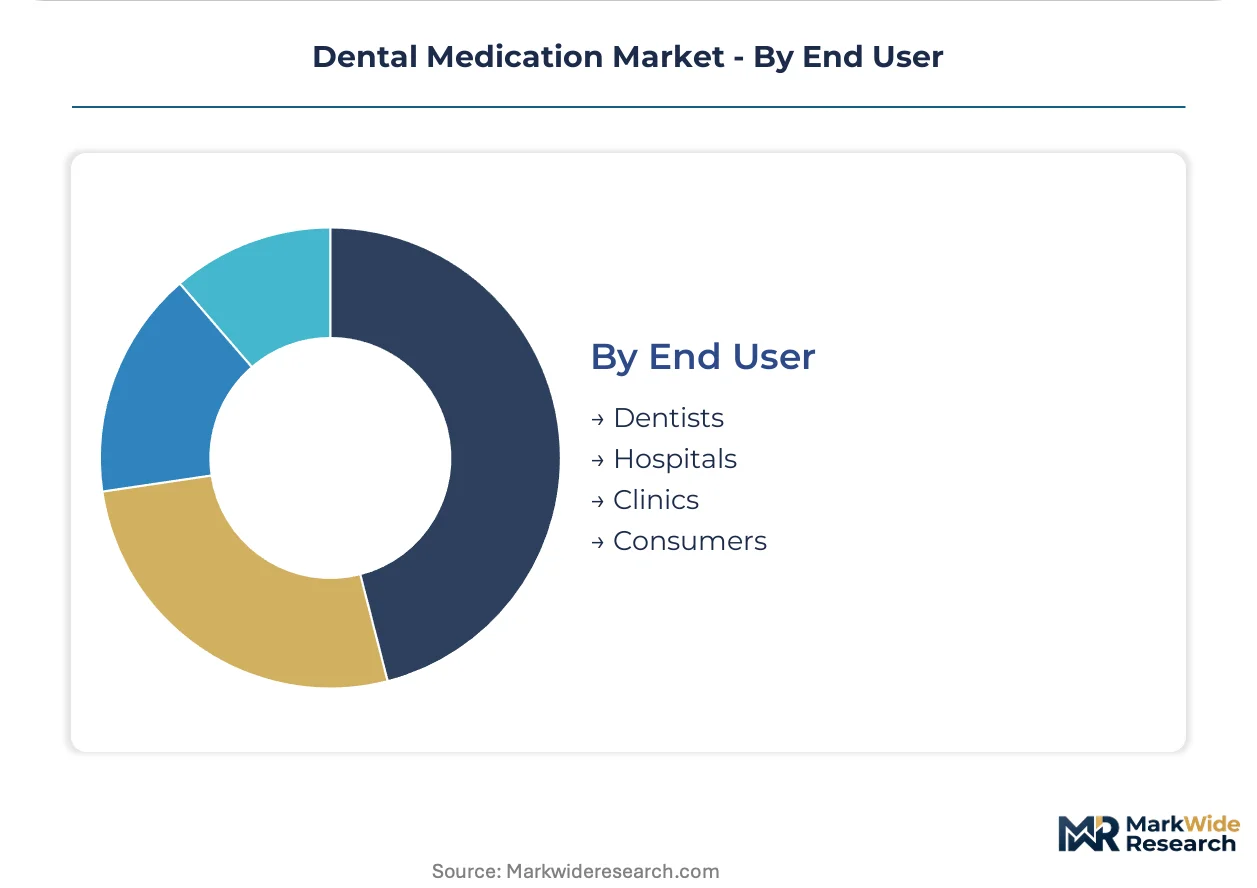
End User:
Customer type determines procurement channel structure, with institutional buyers leveraging aggregated volume and individual practitioners remaining fragmented across distributor relationships.
- Dentists:Independent and group practice procurement patterns diverge sharply as dental service organizations extract direct manufacturer pricing. Metropolitan United States clusters show DSO penetration exceeding 35% of chair capacity.
- Hospitals:Academic medical center oral surgery suites standardize on computer-controlled anesthetic delivery and advanced hemostatic protocols.
- Clinics:Federally qualified health centers and community clinics operate on formulary constraints tied to 340B drug pricing programs.
- Consumers:Over-the-counter fluoride rinses and desensitizing toothpastes compete through retail pharmacy and e-commerce channels.
Dentists anchor the volume base while hospital procurement shows the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA safety labeling revisions for local anesthetics are reshaping manufacturer priorities across the United States, while EMA clinical evidence requirements under MDR are elevating documentation burdens for antimicrobial formulations in Europe. Demand clusters in Germany, where statutory health insurance reimbursement expansion is compressing preventive fluoride protocol timelines and forcing volume forecasting recalibration around public payor cycles.
United States
Metropolitan dental service organizations in Texas and California are leveraging aggregated volume to extract direct manufacturer pricing, with DSO penetration exceeding 35 percent of chair capacity in these states. FDA tightening of epinephrine concentration labeling is driving reformulation investments among domestic manufacturers. Academic medical centers in California are standardizing computer-controlled anesthetic delivery platforms to reduce needle deflection incidents.
Germany
Statutory health insurance reimbursement broadening for preventive fluoride protocols is accelerating patient access and compressing application intervals across Bavaria and North Rhine-Westphalia. EMA MDR framework imposes clinical evidence requirements on antimicrobial dental formulations, elevating documentation costs for market entrants. Manufacturing clusters in Baden-Württemberg are accelerating phenolic alternative screening to preempt REACH authorization sunset clauses for quaternary ammonium compounds.
China
Active pharmaceutical ingredient sourcing for lidocaine and articaine base materials concentrates in eastern chemical manufacturing zones, exposing formulators to export licensing volatility. NMPA oversight of local anesthetic safety profiles is tightening documentation standards for imported formulations. Industrial corridors in Jiangsu and Zhejiang provinces are expanding sterile injectable capacity to serve domestic oral surgery demand.
Japan
PMDA review timelines for novel rinse formulations are extending development cycles as biocompatibility certification requirements intensify. METI support for regenerative biomaterial research is channeling R&D expenditure toward periodontal medicament adjunct therapies. Manufacturing concentration in the Kansai region around Osaka is supplying computer-controlled delivery devices to academic medical centers.
India
API manufacturing for amide-based local anesthetic base materials clusters in Gujarat and Maharashtra, with CDSCO oversight of export quality standards shaping international supply reliability. Domestic dental clinic expansion in Delhi-NCR and Bangalore is driving formulary adoption of perioperative therapies. BIS certification requirements for sterile injectable formats are elevating compliance costs for regional formulators.
Dental Medication Market Competitive Landscape
Integrated equipment-pharmaceutical bundlers and specialized endodontic suppliers split the market between bundled purchasing decisions and procedure-specific formulary anchoring. Three strategic archetypes dominate: diversified healthcare conglomerates with dental divisions, pure-play dental pharmaceutical specialists, and distribution intermediaries with same-day delivery infrastructure. Competitive moves concentrate on direct-to-practice digital channel penetration and warehouse network densification in metropolitan clusters.
Within the integrated equipment-pharmaceutical tier, Dentsply Sirona and Henry Schein exemplify divergent approaches to market presence, with the former leveraging bundled portfolio breadth and the latter anchoring position through distribution infrastructure scale. Septodont occupies the specialist archetype as a France-based entity focused on endodontic medicaments and local anesthetics. These three entities collectively represent the structural tension between bundled convenience and specialized depth that characterizes procurement decision-making across United States and European dental practices.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Henry Schein |
| 3M Company |
| Septodont |
| Ivoclar Vivadent |
| Institut Straumann |
| Envista |
| Patterson Companies |
| Hikma Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
API export licensing volatility from Indian and Chinese chemical manufacturing zones determines both the premium spread for domestically formulated amide-based local anesthetics and the geographic shape of multi-source procurement strategies among United States formulators. Henry Schein's same-day delivery commitments and Dentsply Sirona's bundled equipment-pharmaceutical portfolios anchor divergent pricing architectures that compress or extend tier spreads based on warehouse proximity and volume aggregation.
Pricing Analysis
The customization-premium spread separates computer-controlled anesthetic delivery platforms from conventional cartridge systems. Pricing stratifies across premium, standard, and economy tiers based on epinephrine concentration precision and FDA safety labeling compliance grade. Cost compression in the standard tier is intensifying because group purchasing organization consolidation extracts direct manufacturer pricing from DSO-aggregated volume. Federally qualified health centers operating under 340B constraints exhibit the highest price sensitivity, while academic medical centers standardizing on aspiration-protocol devices show the least.
Supply Chain Analysis
Contract manufacturing for lidocaine and articaine base materials concentrates in Gujarat and Maharashtra chemical corridors, with secondary capacity in Jiangsu and Zhejiang provinces. Active pharmaceutical ingredient sourcing draws from Indian export zones and Chinese sterile injectable facilities, with formulation finishing tethered to Baden-Württemberg manufacturing clusters for European market access. Single-source vulnerability in epinephrine API supply elevates exposure to export licensing disruptions. Distribution runs through Henry Schein's metropolitan warehouse networks and direct-to-practice e-procurement channels that erode traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental medication demand is recovering from pandemic-deferred elective procedure backlogs, with oral surgery volumes in Texas and California metropolitan clusters driving cyclical replenishment of perioperative anesthesia and antibiotic inventories.
For Market Incumbents: Pre-empt silver diamine fluoride convergence by accelerating pediatric and geriatric formulation dossiers before REACH authorization sunsets force quaternary ammonium compound reformulation. Deepen backward integration into amide-based API sourcing to reduce exposure to Indian and Chinese export licensing volatility. Anchor channel control through same-day delivery infrastructure densification in DSO-penetrated metropolitan markets. For New Entrants and Emerging Players: Mid-market dental service organizations in Texas and California represent the most penetrable entry point, where aggregated volume exceeds 35 percent of chair capacity and bundled equipment-pharmaceutical relationships show fatigue. Risk-based caries management protocol reimbursement expansion in German statutory health insurance frameworks offers a secondary white space. Pursue direct-to-practice e-procurement platform partnerships to bypass incumbent distributor lock-in. For Investors and Strategic Acquirers: EMA MDR clinical evidence requirements reshape the acquisition landscape by elevating documentation costs that favor incumbents with established antimicrobial dossiers. Five-to-ten year viability favors specialized endodontic medicament suppliers with toxicology teams already deployed against REACH substance restrictions. Monitor FDA epinephrine concentration labeling revisions as the signal for reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Computer-Controlled Delivery Platform Launch | Reduces needle deflection incidents in California academic medical center oral surgery suites. |
| Phenolic Alternative Screening Acceleration | Preempts REACH authorization sunset clauses for German and French antimicrobial rinse formulators. |
| Direct-to-Practice E-Procurement Partnership | Extracts price transparency from DSO-aggregated volume in Texas and California metropolitan clusters. |
| Silver Diamine Fluoride Formulation Dossier | Opens pediatric and geriatric application white spaces where drilling tolerance is limited. |
| Metropolitan Warehouse Network Densification | Compresses formulary replenishment cycles for same-day delivery commitments to United States practices. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oral surgeons, periodontal specialists, dental service organization procurement directors, and pharmaceutical regulatory affairs leads. Secondary validation drew from FDA adverse event reporting databases, EMA MDR submission records, German statutory health insurance reimbursement schedules, and United States group purchasing organization contract disclosures. Bottom-up consumption modeling triangulated against top-down manufacturer revenue aggregation.
Calibration anchored volume and value outputs to historical procurement cycle analysis across acute-care and preventive formulation categories. Segmentation dimensions modeled include product type, application, delivery mode, and end-user procurement channel structure. CAGRs were derived from procedure volume elasticity to reimbursement expansion and technology substitution rates for computer-controlled anesthetic platforms.
Macroeconomic conditions sit as an overlay; deviation in statutory health insurance reimbursement timelines or API export licensing volatility would shift the trajectory. Quarterly review of FDA safety labeling revisions, REACH substance restriction candidate listings, and DSO penetration rates in metropolitan United States markets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Benzodiazepine Drugs Market